
Market Overview:
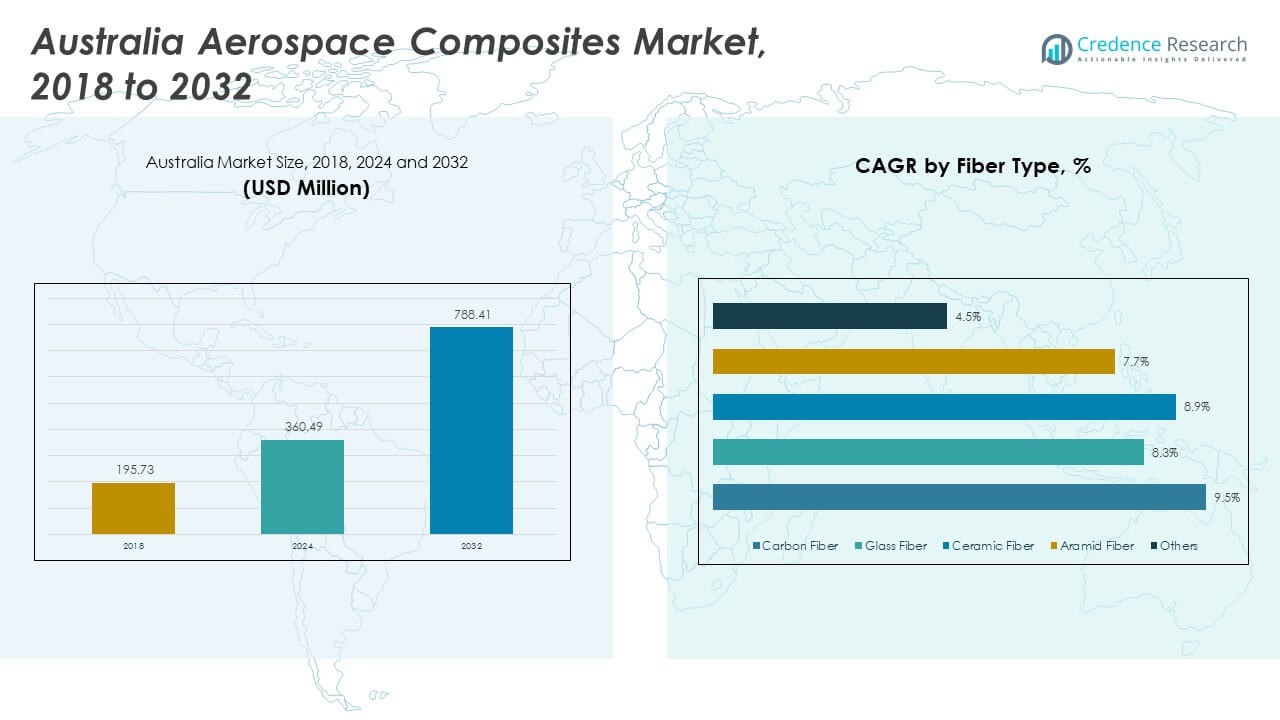
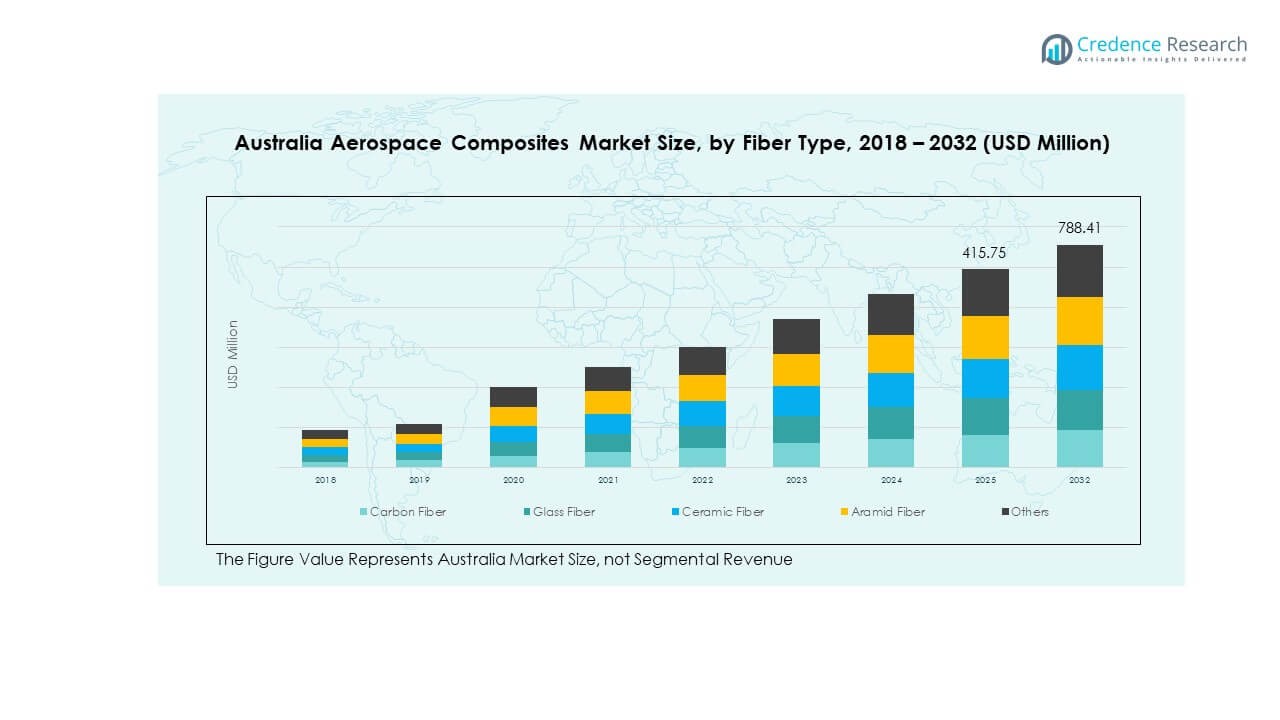
The Australia Aerospace Composites Market size was valued at USD 195.73 million in 2018 to USD 360.49 million in 2024 and is anticipated to reach USD 788.41 million by 2032, at a CAGR of 9.57% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Australia Aerospace Composites Market Size 2024 | USD 360.49 Million |
| Australia Aerospace Composites Market, CAGR | 9.57% |
| Australia Aerospace Composites Market Size 2032 | USD 788.41 Million |
Growing investments in advanced composite technologies are driving the Australia Aerospace Composites Market. The demand for lightweight, fuel-efficient aircraft is pushing manufacturers to adopt carbon fiber and high-strength resin systems. Increased defense modernization, strong domestic production capacity, and research-led innovation contribute to market expansion. Composite structures improve durability, reduce maintenance costs, and enhance aircraft performance. Government-backed programs and private sector investments accelerate technology adoption.
Victoria leads the Australia Aerospace Composites Market due to its strong aerospace manufacturing base and well-developed infrastructure. Queensland is rapidly emerging as a key hub, supported by strategic defense investments and growing MRO capabilities. New South Wales is strengthening its position through R&D initiatives and increased private sector involvement. Regional collaborations with global OEMs are enhancing technology transfer and boosting production. These state-level developments are shaping a competitive ecosystem that supports innovation, efficiency, and export potential.
Market Insights
- The Australia Aerospace Composites Market was valued at USD 195.73 million in 2018, reached USD 360.49 million in 2024, and is projected to reach USD 788.41 million by 2032, growing at a CAGR of 9.57%.
- Victoria leads with 38% of the market share, supported by advanced infrastructure and strong defense programs. Queensland follows with 33% share, benefiting from growing MRO capabilities, while New South Wales holds 29%, driven by R&D and private investments.
- Queensland represents the fastest-growing region with a 33% share, supported by strategic defense contracts, expanding aerospace clusters, and export-oriented manufacturing capacity.
- Carbon fiber dominates the segment distribution, holding roughly 40% of the total fiber share, reflecting its strong use in structural components for weight reduction.
- Glass fiber ranks second with nearly 25% of the share, used mainly in secondary structures and cost-efficient applications in commercial aerospace programs.
Market Drivers
Rising Demand for Lightweight and High-Performance Materials in Aircraft Manufacturing
The Australia Aerospace Composites Market benefits from increasing use of advanced lightweight materials in aircraft production. Composite materials lower the overall aircraft weight and improve fuel efficiency. Growing carbon emission regulations encourage manufacturers to adopt sustainable solutions. Rising demand for longer aircraft range and higher payload capacity further drives the need for composites. The defense sector is also increasing its investments in lightweight materials for better agility and durability. Composite parts help improve structural integrity and reduce maintenance costs. High stiffness-to-weight ratios make these materials suitable for critical components. It is strengthening its role as a core enabler of aerospace innovation.
Expanding Domestic Aerospace Production Capabilities Across Key States
Local aerospace manufacturers are expanding composite production facilities to meet rising demand. Strategic investments by government and private players boost R&D capabilities. Victoria, Queensland, and New South Wales are emerging as strong manufacturing hubs. Partnerships with global aerospace OEMs increase technology transfer and adoption of advanced materials. This expansion supports local job creation and strengthens the supply chain network. Strong defense procurement programs further accelerate domestic production. Rising collaboration with research institutions enhances technical capabilities. It is shaping a resilient and competitive national aerospace ecosystem.
Increased Defense Spending and Upgradation of Military Fleets
Strong defense budgets fuel composite demand across military aircraft, helicopters, and UAV platforms. Advanced composites improve stealth features, reduce weight, and increase operational performance. Fleet modernization programs encourage the use of lighter and stronger components. Australian defense contracts increasingly require high-performance composite structures. The push for enhanced mobility and endurance in defense aircraft drives this demand. Composites also lower maintenance costs and enhance durability in extreme conditions. Local suppliers benefit from growing government support. It is reinforcing the country’s defense modernization goals.
- For instance, in August 2025, the U.S. Defense Security Cooperation Agency approved a USD 404 million Baseline 2 upgrade for Australia’s MC-55A Peregrine fleet. L3Harris Technologies was named the principal contractor under this ISR/EW program supporting the Royal Australian Air Force. The deal strengthens bilateral defense cooperation and enhances airborne intelligence capabilities.
Growing R&D Investments and Technological Innovation in Composite Processing
Rising investments in R&D programs drive technological progress in composite manufacturing. Advanced processing technologies, such as automated fiber placement and out-of-autoclave methods, enable cost-effective production. These innovations reduce manufacturing cycle times and improve product quality. Industry-academic collaborations strengthen technical knowledge and workforce development. Government initiatives support innovation in sustainable aerospace materials. Improved heat resistance and impact strength make composites ideal for critical aircraft systems. Advanced automation also improves production accuracy and scalability. It is supporting continuous modernization of the aerospace materials sector.
- For instance, UNSW’s Automated Composites Laboratory hosts Australia’s most advanced Automated Fibre Placement (AFP) robotic system-featuring a 6-axis platform, high-temperature thermoplastic layup capability, and the ability to produce aerospace components up to 4 meters. The lab, working with industry partners under the ARC Training Centre for Automated Manufacture, has positioned UNSW as a core R&D hub for next-gen aerospace material automation.
Market Trends
Integration of Advanced Manufacturing Technologies to Enhance Efficiency and Precision
The Australia Aerospace Composites Market is witnessing rising adoption of advanced manufacturing methods. Automation in composite production reduces labor dependency and increases consistency. Digital twins and AI-driven systems improve quality control and operational efficiency. Lightweight structures with high mechanical performance are becoming standard. OEMs use additive manufacturing to produce complex shapes with less waste. This shift enables faster development cycles and reduced production costs. Real-time monitoring also ensures greater precision in assembly lines. It is driving transformation across the aerospace materials value chain.
Emergence of Sustainable Composite Materials for Green Aviation Goals
Sustainability trends are influencing composite production strategies in the aerospace sector. Manufacturers are adopting bio-based and recyclable composites to meet environmental standards. Lower lifecycle emissions and improved end-of-life recyclability strengthen their adoption. Sustainable manufacturing methods align with net-zero emission targets. OEMs are introducing greener aircraft models with reduced environmental impact. Material suppliers are focusing on lower resin toxicity and energy-efficient processing. This trend also attracts investors interested in climate-focused innovation. It is supporting a more sustainable aerospace manufacturing ecosystem.
- For instance, in September 2024, Change Climate Pty Ltd, in partnership with the University of Southern Queensland, the Australian National University, and the University of South Australia, developed the BYOXY Bio-Epoxy Resin-the world’s first epoxy resin made entirely from 100% renewable resources. Supported by the iLAuNCH Trailblazer program, the resin is UV-resistant and recyclable, specifically formulated for aerospace and space composite applications.
Increased Use of Multifunctional Composites for Performance Optimization
The industry is shifting toward multifunctional composite materials with integrated capabilities. These composites combine structural strength with advanced properties such as thermal resistance or lightning protection. Their multifunctionality reduces component count and simplifies aircraft design. OEMs benefit from lower weight and reduced maintenance costs. Integration of sensors into composites also enhances predictive maintenance. Multifunctional designs support faster assembly and better operational efficiency. They also improve aircraft safety and durability during harsh operations. It is enabling new performance standards in next-generation aircraft.
Strategic Collaborations and Supply Chain Strengthening Among Key Players
Rising collaborations between global aerospace OEMs and Australian suppliers enhance technology transfer. Strong alliances support local production capacity and capability development. Joint ventures enable faster adoption of advanced composite solutions. Supply chain diversification strategies mitigate risks and increase resilience. Investments in logistics infrastructure support timely deliveries and quality assurance. Partnerships with research bodies strengthen knowledge sharing and innovation. International cooperation enhances export competitiveness. It is strengthening the country’s position in the global aerospace ecosystem.
- For instance, in May 2025, Lockheed Martinpartnered with the Royal Australian Air Force (RAAF) to link F-35 flight simulators across the Williamtown and Tindal bases under a Distributed Mission Training (DMT) This marked Australia’s first international F-35 simulator connection, improving pilot readiness, networked training, and system resilience within Lockheed Martin’s global aerospace ecosystem.
Market Challenges Analysis
High Production Costs and Complex Manufacturing Processes Limiting Scalability
The Australia Aerospace Composites Market faces challenges from high production costs and complex processing steps. Composite manufacturing requires specialized equipment, cleanrooms, and skilled labor. These factors increase capital expenditure and limit small-scale entry. Autoclave processes demand high precision and long cycle times. Achieving uniform quality across large structures remains difficult. Limited standardization raises production variability and cost uncertainty. This complexity impacts pricing strategies for OEMs and suppliers. It is restraining rapid scaling of composite adoption in aerospace applications.
Supply Chain Disruptions and Limited Raw Material Availability
Volatility in global supply chains creates procurement challenges for composite manufacturers. Dependence on imported raw materials increases lead times and costs. Geopolitical factors and shipping delays disrupt consistent availability of carbon fibers and resins. Lack of domestic large-scale suppliers limits flexibility in responding to demand spikes. These constraints affect production timelines and project deliveries. Inventory management becomes more difficult during market fluctuations. Rising transportation costs further pressure profit margins. It is adding operational risks to the composite manufacturing value chain.
Market Opportunities
Expansion of Domestic Composite Manufacturing Capacity Through Strategic Investments
The Australia Aerospace Composites Market holds strong potential through strategic capacity expansion. Local players are increasing their production footprint to meet aerospace and defense demand. Government-backed programs support infrastructure and advanced technology integration. Collaborations with international firms help scale capabilities faster. Investments in automated production lines improve quality and throughput. Localizing key stages of the supply chain also reduces dependency on imports. Regional economic zones are fostering industrial growth. It is creating a favorable environment for aerospace material innovation.
Growth in Exports and Integration with Global Aerospace Supply Chains
Expanding global collaborations provide opportunities for Australian suppliers to access new markets. Partnerships with international OEMs increase export potential of advanced composite components. Certification and quality standard alignment enable entry into established aerospace programs. Strengthened logistics and port infrastructure support competitive delivery timelines. Rising demand for lightweight materials globally expands trade prospects. Integration with global supply chains also improves technology access. It is reinforcing Australia’s position in the international aerospace ecosystem.
Market Segmentation Analysis
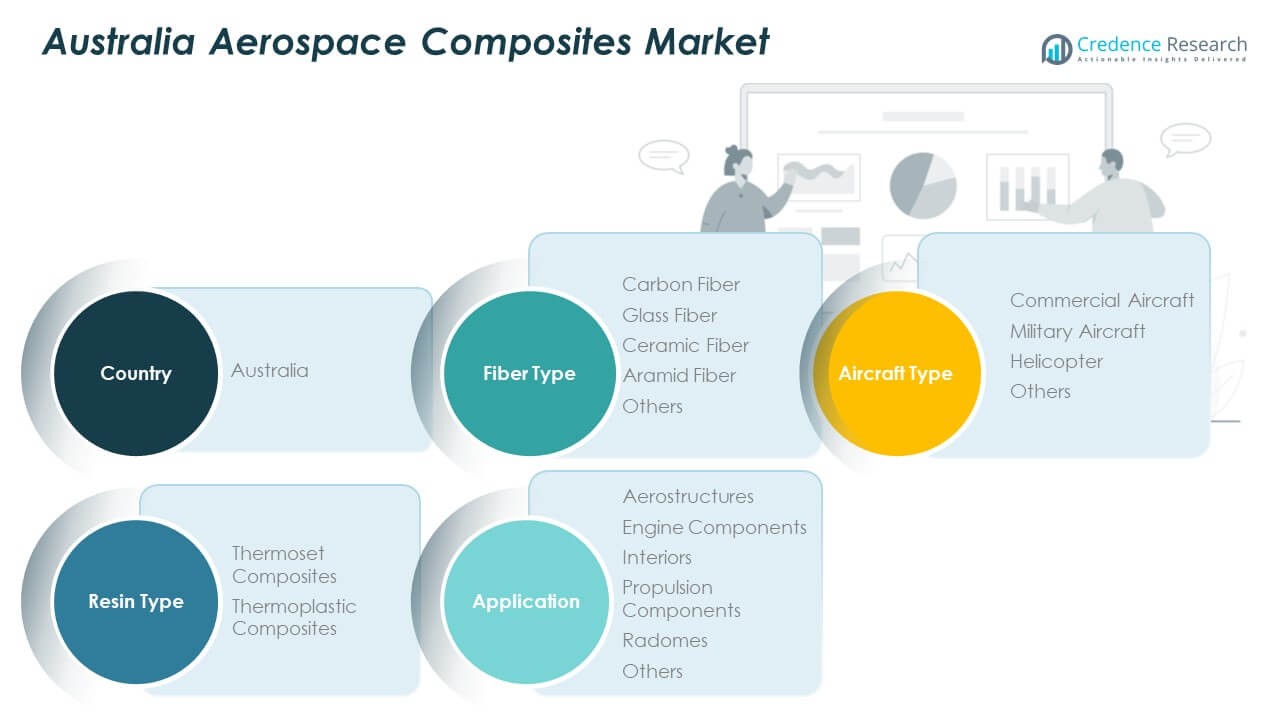
The Australia Aerospace Composites Market is segmented by fiber type, aircraft type, resin type, and application.
By fiber type, carbon fiber dominates due to its high strength-to-weight ratio and durability. Glass fiber is used in secondary structures, while ceramic and aramid fibers support high-performance applications.
- For instance, Toray Carbon Fibers Europe expanded production capacity at its Abidos facility in France from 5,000 to 6,000 metric tons of medium and high modulus carbon fiber tows to meet growing aerospace demand. The expansion aims to strengthen the company’s supply capabilities for advanced aerospace applications.
By aircraft type, commercial aircraft hold a major share, with military aircraft and helicopters contributing to specialized demand.
By resin type, thermoset composites lead for their superior performance in structural components, while thermoplastic composites gain traction for repairability and recyclability.
By application, aerostructures form the largest segment, followed by engine components, interiors, propulsion components, and radomes. It is diversifying applications across both civil and defense aerospace programs.
- For instance, Spirit AeroSystems manufactures composite fuselage sections and nacelles for Airbus A350, Boeing 787, and Sikorsky CH-53K aircraft using resin transfer infusion and automated fiber placement, optimizing weight efficiency in major aerostructures.
Segmentation
By Fiber Type
- Carbon Fiber
- Glass Fiber
- Ceramic Fiber
- Aramid Fiber
- Others
By Aircraft Type
- Commercial Aircraft
- Military Aircraft
- Helicopter
- Others
By Resin Type
- Thermoset Composites
- Thermoplastic Composites
By Application
- Aerostructures
- Engine Components
- Interiors
- Propulsion Components
- Radomes
- Others
Regional Analysis
Victoria leads the Australia Aerospace Composites Market with a 38% share, supported by advanced manufacturing infrastructure and defense-focused programs. The state hosts key aerospace suppliers, research institutions, and government-backed innovation hubs. Strong partnerships with global OEMs enhance local composite production capabilities. Major aircraft assembly and component manufacturing facilities drive industrial growth. Skilled workforce availability strengthens its competitive position. The region also benefits from targeted investment in R&D and digital production technologies. It is driving large-scale composite adoption in both civil and defense segments.
Queensland holds a 33% market share, driven by its growing aerospace manufacturing ecosystem and strategic defense contracts. The state focuses on integrating composite technologies into maintenance, repair, and overhaul operations. Government incentives encourage private investments in advanced production facilities. Aerospace clusters in Brisbane and surrounding areas support high-volume component production. Rising exports to Asia-Pacific markets enhance the region’s economic contribution. Its growing presence in UAV and rotary-wing programs accelerates demand. It is becoming a key production and innovation hub for next-generation aerospace materials.
New South Wales accounts for 29% of the market, supported by strong R&D activity and university-industry collaborations. The region invests in composite testing, design, and prototyping capabilities. Local aerospace companies are expanding production capacity to support both domestic and export programs. Strategic proximity to major transport hubs supports supply chain efficiency. High investment in digital engineering strengthens material performance research. Its focus on sustainability and smart manufacturing enhances industry competitiveness. It is building a strong foundation for future composite technology leadership.
Key Player Analysis
- Gurit Holding AG
- Hexcel Corporation
- Solvay SA
- Owens Corning
- Huntsman Corporation
- Aerovac LLC
- SGL Carbon SE
- Advanced Composites Group
- Rock West Composites
- Cytec Solvay Group
- Quickstep Holdings Ltd (Australia)
- Boeing Australia
- Airbus Australia Pacific
- Lockheed Martin Australia
- Northrop Grumman Australia
- GE Aviation
Competitive Analysis
The Australia Aerospace Composites Market is defined by strong collaboration between local manufacturers and global OEMs. Key players include Quickstep Holdings, Boeing Australia, Airbus Australia Pacific, Lockheed Martin Australia, Northrop Grumman, and GE Aviation. These companies invest heavily in R&D and advanced composite processing technologies. Strategic partnerships with research institutes support innovation and workforce training. The competitive landscape is shaped by vertical integration and localization of supply chains. Focus on carbon fiber innovation and lightweight structural solutions drives product differentiation. Increasing investment in automation and digital manufacturing boosts cost efficiency. It is positioning Australia as a competitive player in the global aerospace composites value chain.
Recent Developments
- In June 2025, Owens Corning established a partnership with Switzerland-based Composite Recycling to develop industrial-scale recycling technologies for glass fiber reinforcement products. The initiative centers on integrating reclaimed glass fibers into Owens Corning’s production streams, thereby supporting circular economy efforts within aerospace and related industries.
- In May 2025, Hexcel Corporation entered a major partnership with U.S.-based aerospace startup JetZero to develop and qualify next-generation carbon fiber composites for JetZero’s blended wing body (BWB) aircraft platform under the FAA’s Fueling Aviation’s Sustainable Transition (FAST) program.
- In March 2025, Gurit Holding AG reaffirmed its commitment to the defense composites sector by re-signing a long-term supply contract with USMI for the delivery of advanced composite materials used in government and marine applications. The renewed agreement strengthens Gurit’s global position in high-performance composite manufacturing and supports innovations in structural materials applicable to aerospace and defense environments.
- In March 2025, Huntsman Corporation announced a strategic collaboration with Advanced Material Development Ltd. (AMD) to co-develop carbon nanotube-integrated resin systems for aerospace and defense composites. The partnership leverages Huntsman’s resin expertise and AMD’s nanotechnology research capabilities to create electrically enhanced materials offering improved strength and conductivity.
Report Coverage
The research report offers an in-depth analysis based on Fiber Type, Aircraft Type, Resin Type and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Australia Aerospace Composites Market will expand through stronger domestic manufacturing capacity and strategic investments.
- Advancements in lightweight material technologies will support the next generation of aircraft designs.
- Increased defense modernization programs will drive steady composite demand across military platforms.
- Automation and digitalization in production will enhance cost efficiency and precision.
- Growing collaborations with global OEMs will integrate local suppliers into international supply chains.
- Sustainability goals will accelerate the adoption of recyclable and eco-friendly composite materials.
- Multifunctional composites will gain traction due to their superior performance characteristics.
- Expansion of aerospace clusters in Victoria, Queensland, and New South Wales will strengthen the supply base.
- R&D investments will boost innovation in resin systems, fiber technologies, and manufacturing methods.
- Export growth and international certifications will position Australia as a competitive global composite supplier.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Australia Aerospace Composites Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Australia Aerospace Composites Market projected to grow between 2024 and 2032?
Which Australia Aerospace Composites Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Australia Aerospace Composites Market?
Who are the leading companies in the Australia Aerospace Composites Market?
Which region commanded the largest share of the Australia Aerospace Composites Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 360.49 million → 2032: USD 788.41 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Aerospace Composites Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Aerospace Composites Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Aerospace Composites Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Aerospace Composites Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Aerospace Composites Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Aerospace Composites Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Aerospace Composites Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Aerospace Composites Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 360.49 million → 2032: USD 788.41 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Aerospace Composites Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Aerospace Composites Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Australia Aerospace Composites Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Australia Aerospace Composites Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

