
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Aircraft Cockpit Display System Market Size 2024 | USD 3190.8 million |
| Aircraft Cockpit Display System Market, CAGR | 4.49% |
| Aircraft Cockpit Display System Market Size 2032 | USD 4534.16 million |
Market Overview:
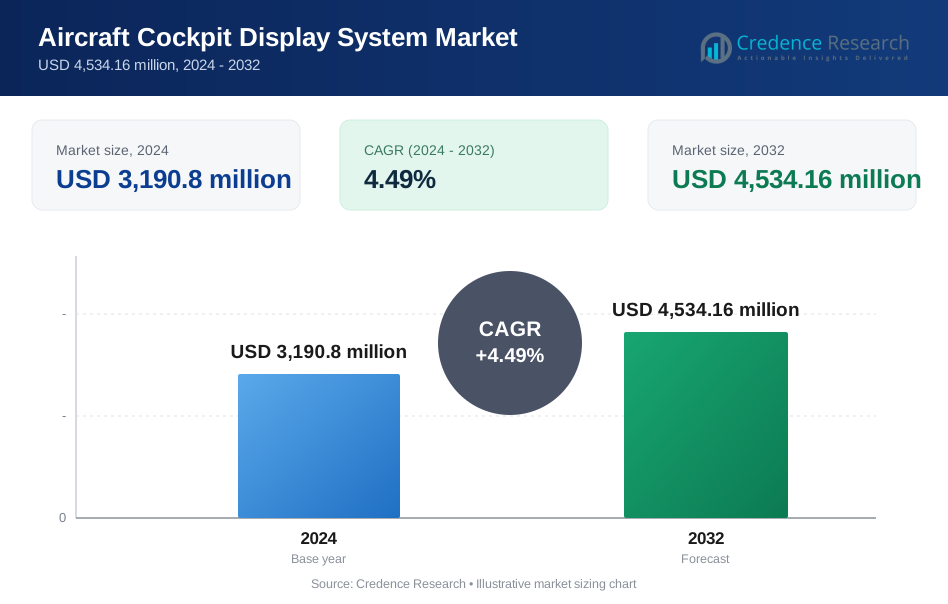
The Aircraft Cockpit Display System Market is projected to grow from USD 3190.8 million in 2024 to an estimated USD 4534.16 million by 2032, with a compound annual growth rate (CAGR) of 4.49% from 2024 to 2032.
Key drivers of the aircraft cockpit display system market include the increasing demand for advanced cockpit technologies that enhance pilot situational awareness, safety, and operational efficiency. These systems are vital for improving flight navigation, weather monitoring, and communication. As the aviation industry continues to focus on safety, modernizing cockpit technology with high-resolution displays, touchscreens, and integrated systems is becoming a priority for both commercial and military aircraft manufacturers. The growing adoption of digital cockpits and glass cockpit systems is another major contributor to the market growth, providing pilots with intuitive, user-friendly interfaces that consolidate critical information. Furthermore, the increasing number of air traffic and the rise in passenger travel are pushing airlines to upgrade their fleets with the latest cockpit display systems. Technological advancements such as augmented reality and synthetic vision systems are also expected to drive market demand, as they provide enhanced flight safety by offering clear, comprehensive views of the surroundings, even in poor visibility conditions. Additionally, the ongoing development of automation technologies and unmanned aerial vehicles (UAVs) further supports the growth of the cockpit display system market, as these systems are integral to unmanned flight operations.
Regionally, North America is leading the market due to the presence of major aircraft manufacturers and technological advancements in aviation systems. Europe follows closely, with strong demand for cockpit display systems driven by commercial aviation operators and defense contracts. The Asia Pacific region is expected to experience significant growth, with expanding air travel and increasing investments in military and commercial aviation. As regional governments invest in upgrading aircraft fleets, demand for modern cockpit display systems will continue to rise globally.
Market insights:
- The Aircraft Cockpit Display System Market is projected to grow from USD 3190.8 million in 2024 to USD 4534.16 million by 2032, with a CAGR of 4.49% from 2024 to 2032.
- Increasing demand for advanced cockpit technologies to improve safety, situational awareness, and operational efficiency is driving market growth.
- The adoption of digital cockpits and glass cockpit systems is accelerating due to their ability to consolidate critical flight information on intuitive displays.
- Technological advancements such as augmented reality and synthetic vision systems are enhancing pilot performance and contributing to market expansion.
- High investments in modernization and upgrades by airlines to improve fleet safety and efficiency are a significant factor driving market growth.
- North America leads the market with significant contributions from major aircraft manufacturers, followed by Europe, with strong demand in both commercial and defense aviation.
- The Asia Pacific region is expected to witness significant growth, driven by increasing air travel and investments in military and commercial aviation technologies.
Market Drivers:
Technological Advancements in Cockpit Display Systems:
The growing demand for advanced cockpit display systems is largely driven by technological innovations that enhance flight safety, pilot situational awareness, and operational efficiency. In recent years, there has been a significant shift from traditional cockpit systems to digital cockpits, also known as glass cockpits, which integrate various functionalities into high-resolution displays. These systems provide pilots with real-time data, improved navigation, and better weather monitoring. Notable advancements include the integration of augmented reality (AR) and synthetic vision systems (SVS), which provide clear views of the aircraft’s surroundings, even in poor visibility conditions. The European Union Aviation Safety Agency (EASA) has been emphasizing the development and adoption of digital cockpit technologies as part of its safety improvement programs.
Increasing Demand for Safety and Efficiency:
Safety remains the highest priority in the aviation industry, pushing the demand for sophisticated cockpit display systems. These systems enable pilots to make more informed decisions by providing critical information in a user-friendly format. The Federal Aviation Administration (FAA) has highlighted that improving cockpit design and functionality can substantially reduce human error, which is a leading cause of aviation accidents. The FAA has also been working on policies that require new safety measures, such as real-time monitoring of flight parameters, which directly contributes to the adoption of advanced cockpit display systems. Operational efficiency is a major driver. Cockpit display systems are essential for optimizing fuel usage, reducing operational costs, and improving flight planning.
Government Regulations and Policies:
Government regulations and policies are instrumental in driving the growth of cockpit display systems. Authorities such as the FAA and EASA impose strict regulations on cockpit technology and safety standards. For instance, the FAA’s NextGen program, which focuses on modernizing U.S. air traffic control infrastructure, includes initiatives for the integration of advanced cockpit systems that enhance flight operations and safety. As part of this program, the FAA is working with key stakeholders in the aviation industry to implement satellite-based navigation and communication systems, which are closely linked to cockpit display advancements. The ICAO’s Global Aviation Safety Plan also encourages the adoption of modern cockpit systems as part of international safety protocols.
Growth in Global Air Traffic:
The increasing volume of air traffic worldwide is another key driver of the market for cockpit display systems. According to the World Bank, global air traffic is expected to double by 2035. This surge in air traffic is prompting the need for more advanced cockpit display systems to handle the growing complexity of flight operations. The International Air Transport Association (IATA) also supports this outlook, predicting a steady increase in passenger and cargo flights over the next decade. In response, governments are investing heavily in upgrading aircraft fleets and modernizing cockpit systems to accommodate higher traffic volumes and improve flight safety. For instance, in Asia-Pacific, countries like China and India are rapidly expanding their aviation sectors.
Market Trends:
Integration of Artificial Intelligence and Machine Learning:
One of the emerging trends in the aircraft cockpit display system market is the increasing integration of artificial intelligence (AI) and machine learning (ML) technologies. These innovations help improve decision-making processes, predict maintenance needs, and enhance the overall flight experience by providing real-time data analysis. AI and ML can process large volumes of data from cockpit sensors, weather information, and air traffic, enabling pilots to make better-informed decisions. The U.S. Federal Aviation Administration (FAA) has supported this trend through initiatives like the “UAS Integration Pilot Program,” which includes AI applications for both manned and unmanned aerial vehicles. The FAA allocated over $2.5 million in 2020 for AI-driven programs aimed at improving aviation safety through automated flight control systems.
Growing Demand for Retrofit and Modernization:
As airlines and military operators strive to maintain competitive advantages, there is a growing trend toward the retrofit and modernization of older aircraft with advanced cockpit display systems. Governments are supporting this trend through funding programs that encourage fleet upgrades. The U.S. Department of Defense, for instance, has committed approximately $10 billion to modernize its military aircraft over the next decade, including cockpit modernization projects. The U.S. Department of Defense allocated $1.4 billion in 2021 to modernize avionics in legacy military aircraft, emphasizing the integration of cutting-edge cockpit display systems and automation technologies.
Advancements in Augmented Reality and Synthetic Vision Systems:
Another trend in the market is the growing implementation of augmented reality (AR) and synthetic vision systems (SVS) in cockpit displays. These systems offer pilots a comprehensive, real-time view of the aircraft’s surroundings, which is especially valuable in low-visibility conditions. The U.S. National Aeronautics and Space Administration (NASA) has been at the forefront of research in this area. NASA’s $3.5 million investment in AR and SVS technologies has demonstrated that these systems improve situational awareness and can significantly reduce the chances of accidents. For instance, NASA’s Ames Research Center is collaborating with various aviation organizations to test and refine these technologies. Their studies have shown that AR and SVS can improve flight safety by offering pilots better navigation data and visualizations of complex environments, leading to more informed decision-making in adverse weather conditions.
Rising Adoption in Emerging Markets:
The demand for advanced cockpit display systems is also increasing in emerging markets, particularly in Asia-Pacific and Latin America, where air traffic is growing rapidly. Governments in these regions are investing in the development of aviation infrastructure, including the modernization of fleets and the integration of new cockpit technologies. According to the International Civil Aviation Organization (ICAO), Asia-Pacific countries are expected to see a 5.3% annual growth in air traffic over the next decade, driving the need for more advanced cockpit display systems. For instance, China’s Civil Aviation Administration has allocated funds toward improving aviation safety, with a significant portion directed at upgrading cockpit systems to align with international standards.
Market Challenge Analysis:
High Implementation Costs:
One of the significant challenges facing the Aircraft Cockpit Display System market is the high cost of implementing advanced cockpit technologies. The integration of cutting-edge systems such as augmented reality, synthetic vision, and digital cockpits requires substantial investment in both hardware and software. This high initial cost can be a barrier for smaller airlines or military operators with limited budgets. Additionally, the maintenance, training, and software updates required for these sophisticated systems further increase the financial burden. The U.S. Department of Defense's modernization of military aircraft cockpits has seen significant expenditures, with budgets for avionics updates over the next decade. This substantial financial commitment reflects the ongoing challenge of adopting such high-tech solutions, especially when fleets need to be updated across multiple aircraft types and service branches.
Regulatory and Certification Hurdles:
Another challenge facing the market is the complex regulatory and certification processes that new cockpit display systems must undergo. In aviation, safety is paramount, and any new technology must meet stringent standards set by regulatory authorities like the Federal Aviation Administration (FAA) and the European Union Aviation Safety Agency (EASA). These agencies require extensive testing, data validation, and rigorous certification processes before new cockpit systems can be implemented in commercial and military aircraft. In 2021, the FAA’s certification of new avionics systems for aircraft took an average of 18 months. This extended approval period delays the deployment of innovative technologies, creating a bottleneck in the market. The regulatory hurdles associated with new technology integration can slow down the pace of adoption, especially for airlines or defense contractors looking to modernize their fleets quickly.
Market Opportunities:
The Aircraft Cockpit Display System market presents significant opportunities driven by the growing demand for advanced safety, operational efficiency, and improved user experience. As air travel continues to increase globally, the need for more sophisticated cockpit technologies becomes ever more critical. Airlines and defense sectors are increasingly focused on modernizing fleets to enhance flight safety, reduce pilot workload, and improve decision-making through integrated display systems. Moreover, advancements in digital cockpit systems, augmented reality (AR), and synthetic vision systems offer significant potential to revolutionize the cockpit experience. This trend is particularly promising in emerging markets like Asia-Pacific, where rapid air traffic growth is driving demand for updated aviation technologies.
Furthermore, as governments and private sector players continue to invest in modernizing aviation infrastructure, significant opportunities arise for manufacturers of cockpit display systems. The U.S. Department of Defense, for example, has committed billions to aircraft modernization projects, including avionics and cockpit upgrades. Similarly, the International Civil Aviation Organization (ICAO) is pushing for the adoption of more advanced cockpit technologies in commercial aircraft, particularly in regions with high air traffic growth. These investments create opportunities for technology providers to partner with aviation operators and defense agencies, offering tailored cockpit solutions that meet evolving safety, regulatory, and operational standards. The continued evolution of smart cockpit technologies, with features like real-time data analytics and automated systems, further enhances market prospects for innovation and growth.
Market Segmentation Analysis:
By Display Size
The Aircraft Cockpit Display System market is segmented based on display size, with categories including less than 5 inches, 5 to 10 inches, and greater than 10 inches. Smaller display sizes, under 5 inches, are primarily used in military aircraft and smaller aircraft models due to their compact nature, providing essential data without taking up too much cockpit space. Displays in the 5 to 10-inch range are commonly found in commercial aircraft, where they strike a balance between functionality and space efficiency. The larger displays, greater than 10 inches, are typically used in advanced, modern cockpits, offering detailed, high-resolution imagery and multiple layers of flight information. These larger displays are particularly favored in commercial aviation for their ability to present complex data in an easily readable format, enhancing pilot situational awareness.
By Application
The market is also segmented based on application, primarily military and commercial aviation. Military applications often demand specialized cockpit displays for fighter jets, helicopters, and unmanned aerial vehicles (UAVs), where rugged, real-time data processing and high durability are critical. Military cockpit display systems focus on tactical data, mission support, and enhanced flight safety. In contrast, commercial aviation demands cockpit systems that provide high levels of efficiency, safety, and integration with navigation, weather, and aircraft systems. Commercial cockpit display systems focus on user-friendliness, scalability, and integration with other avionics systems to improve passenger safety and operational efficiency.
Segmentation:
Based on Type
- Primary Flight Display (PFD)
- Multifunction Display (MFD)
- Engine Indicating and Crew Alerting System (EICAS)
Based on Display Size
- Less Than 5 Inches
- 5 to 10 Inches
- Greater Than 10 Inches
Based on Application
- Military
- Commercial
Based on Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a dominant share of the Aircraft Cockpit Display System market, accounting for approximately 35% of the total market. The region’s leadership can be attributed to its established aviation infrastructure, significant defense contracts, and the presence of major aircraft manufacturers like Boeing and Lockheed Martin. The U.S. Federal Aviation Administration (FAA) has been instrumental in setting stringent safety standards and regulations, pushing for the adoption of advanced cockpit technologies. The U.S. Department of Defense continues to invest heavily in modernizing military aircraft, including cockpit display systems. For instance, the U.S. government allocated $1.4 billion in 2021 for the modernization of avionics and cockpit systems in legacy military aircraft. These investments contribute to the continued growth of the region's market share.
Europe
Europe holds a significant portion of the market, with a share of around 28%. The European aviation industry, including both commercial and defense sectors, continues to embrace advanced cockpit technologies, particularly with organizations like the European Union Aviation Safety Agency (EASA) leading regulatory efforts to modernize cockpit displays for enhanced safety. Countries such as the United Kingdom, France, Germany, and Russia have high demands for cockpit display systems, driven by the need for modernized fleets and improved operational efficiencies. The European defense sector also supports market growth through ongoing modernization programs. For instance, the European Space Agency (ESA) has been investing in new satellite technologies, which are integrated with cockpit systems to improve navigation and communication. The emphasis on reducing environmental impact through more efficient aviation also contributes to the market’s growth, as advanced cockpit systems play a role in optimizing fuel usage and reducing emissions.
Asia-Pacific
The Asia-Pacific region is experiencing the fastest growth in the Aircraft Cockpit Display System market, with an expected market share of 25%. The rapid expansion of the aviation industry, particularly in China, India, and Japan, is a primary driver. China’s Civil Aviation Administration (CAAC) reports an annual increase in domestic air travel, necessitating significant upgrades to the aviation fleet and cockpit systems. The Indian aviation sector is also growing, with the Directorate General of Civil Aviation (DGCA) pushing for modernization across both commercial and military aircraft. Additionally, Asia-Pacific’s defense sector is investing heavily in next-generation avionics systems, which boosts demand for cockpit display technologies. For instance, Japan's Ministry of Defense has announced plans to modernize its fleet of fighter jets, including cockpit upgrades.
Key Player Analysis:
- Garmin Ltd.
- Dynon Avionics
- RTX Corporation
- Dassault Systemes SE
- Elbit Systems Ltd
- TransDigm Group Incorporated
- Northrop Grumman Corporation
- L3Harris Technologies, Inc.
- Honeywell Aerospace Inc.
- Alpine Electronics, Inc.
Competitive Analysis:
The Aircraft Cockpit Display System market is highly competitive, with key players such as BAE Systems, Elbit Systems, and Airbus leading the way in technological advancements and product offerings. These companies continually innovate to meet the growing demand for more efficient, user-friendly, and safer cockpit solutions across both commercial and military aviation sectors. BAE Systems, for example, focuses on retrofitting avionics systems to enhance operational performance in military aircraft, while Elbit Systems is making strides with enhanced flight vision systems (EFVS) for commercial aircraft like the Boeing B737NG. Airbus, on the other hand, is focusing on upgrading cockpit displays for major airlines to improve pilot interface and overall flight safety. Competition within the market is intensified by the rapid technological advancements in avionics and the continuous demand for next-generation digital cockpits, augmented reality systems, and integrated flight displays, driving innovation and pushing companies to maintain a competitive edge.
Recent Developments:
- In November 2022, BAE Systems plc secured avionics support contracts for the Eurofighter Typhoon, amounting to a total of USD 90.2 million for Typhoon Avionics Support.
- In July 2022, Elbit Systems' Universal Avionics subsidiary was awarded a USD 33 million contract by AerSale to provide enhanced flight vision systems (EFVS) for the Boeing B737NG, with delivery scheduled through 2023.
- In March 2024, Bell introduced a new-generation retrofit flight display system designed specifically for Bell 412 helicopters. This advanced system enhances cockpit capabilities with upgraded navigation aids and real-time data visualization, aiming to modernize older aircraft models. The retrofit improves operational efficiency and pilot situational awareness, reflecting Bell's commitment to innovation in aviation technology. This upgrade is expected to optimize mission performance and safety while meeting modern avionics and digital cockpit standards, addressing the evolving needs of global helicopter operators.
- In March 2024, Astronautics' Badger Pro+ integrated flight display system received FAA approval for Bell's Basix-Pro glass cockpit retrofit in 412EP helicopters with PT6T-3D engines. This upgrade replaces analog instrumentation with a full-glass cockpit, featuring four high-resolution smart displays that provide primary flight, navigation, and engine data. Bell Aeronautical Accessories offers the retrofit kit, which is installed at their global completion centers of excellence.
- In April 2023, Airbus upgraded the cockpit displays of over 100 A320-family jets operated by American Airlines. This upgrade aimed to enhance operational efficiency and pilot interface, improving the overall performance of the airline’s fleet of A320s.
Market Concentration & Characteristics:
The Aircraft Cockpit Display System market exhibits moderate concentration, with a few dominant players such as BAE Systems, Elbit Systems, Honeywell, and Rockwell Collins holding substantial market share. These companies are highly focused on innovation, leveraging advancements in avionics, digital displays, and augmented reality to maintain their competitive edge. The market is characterized by high barriers to entry due to the complex technological requirements, strict regulatory standards, and substantial investment needed for research and development. Additionally, the demand for customized solutions tailored to specific military and commercial applications contributes to the market's fragmented nature, with different players specializing in particular niches. The evolving nature of aviation technology and the increasing focus on safety, efficiency, and user experience drive continuous development within this market. Collaboration between industry leaders, government agencies, and research institutions also plays a key role in advancing the capabilities of cockpit display systems.
Report Coverage:
The research report offers an in-depth analysis based on By type, By Display Size, By Application, By Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for advanced cockpit display systems will continue to rise as airlines and defense contractors modernize fleets to improve safety and operational efficiency.
- Ongoing advancements in augmented reality (AR) and synthetic vision systems will redefine the cockpit experience, offering pilots enhanced situational awareness.
- The integration of AI and machine learning technologies into cockpit systems will streamline decision-making processes and predict maintenance needs more effectively.
- Regulatory bodies like the FAA and EASA will continue to enforce stricter safety standards, driving the adoption of modern cockpit technologies in both commercial and military aviation.
- The increasing focus on fuel efficiency and sustainability will prompt greater adoption of digital cockpit solutions, helping operators optimize flight routes and reduce environmental impact.
- Military aircraft modernization programs, particularly in North America and Europe, will fuel demand for high-performance cockpit displays and avionics systems.
- Emerging markets in Asia-Pacific and Latin America will experience significant growth as air travel increases, leading to higher demand for advanced cockpit technologies.
- Manufacturers will continue to invest heavily in research and development to meet the evolving needs of the aviation industry and stay ahead of competitors.
- Collaborative partnerships between aviation companies, government agencies, and research institutions will drive innovations in cockpit display technologies.
- The trend towards digital cockpits will accelerate, with more aircraft adopting glass cockpit systems to replace traditional analog instruments for improved functionality.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Aircraft Cockpit Display System Market?
What factors are driving the Aircraft Cockpit Display System Market?
What are the key segments within the Aircraft Cockpit Display System Market?
What are some challenges faced by the Aircraft Cockpit Display System Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Aircraft Cockpit Display System Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Aircraft Cockpit Display System Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,190.8 million → 2032: USD 4,534.16 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Aircraft Cockpit Display System Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Aircraft Cockpit Display System Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Aircraft Cockpit Display System Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Aircraft Cockpit Display System Market Drivers
- 3.3 Aircraft Cockpit Display System Market Restraints & Challenges
- 3.4 Aircraft Cockpit Display System Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Aircraft Cockpit Display System Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Aircraft Cockpit Display System Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Aircraft Cockpit Display System category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Aircraft Cockpit Display System Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Aircraft Cockpit Display System Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Aircraft Cockpit Display System market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Aircraft Cockpit Display System Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Aircraft Cockpit Display System Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Aircraft Cockpit Display System Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Aircraft Cockpit Display System (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Aircraft Cockpit Display System Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Aircraft Cockpit Display System Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Aircraft Cockpit Display System Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Aircraft Cockpit Display System Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Aircraft Cockpit Display System Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Aircraft Cockpit Display System Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Aircraft Cockpit Display System Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Aircraft Cockpit Display System Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Aircraft Cockpit Display System Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
