
Market Overview
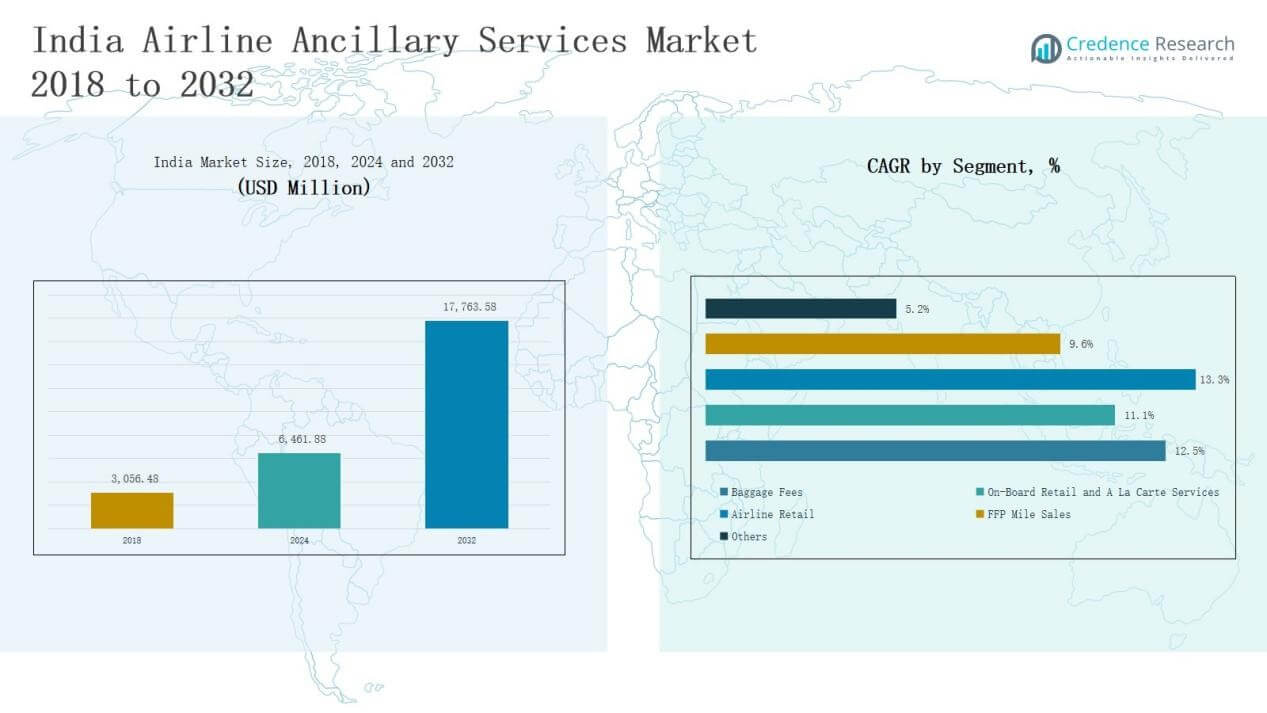
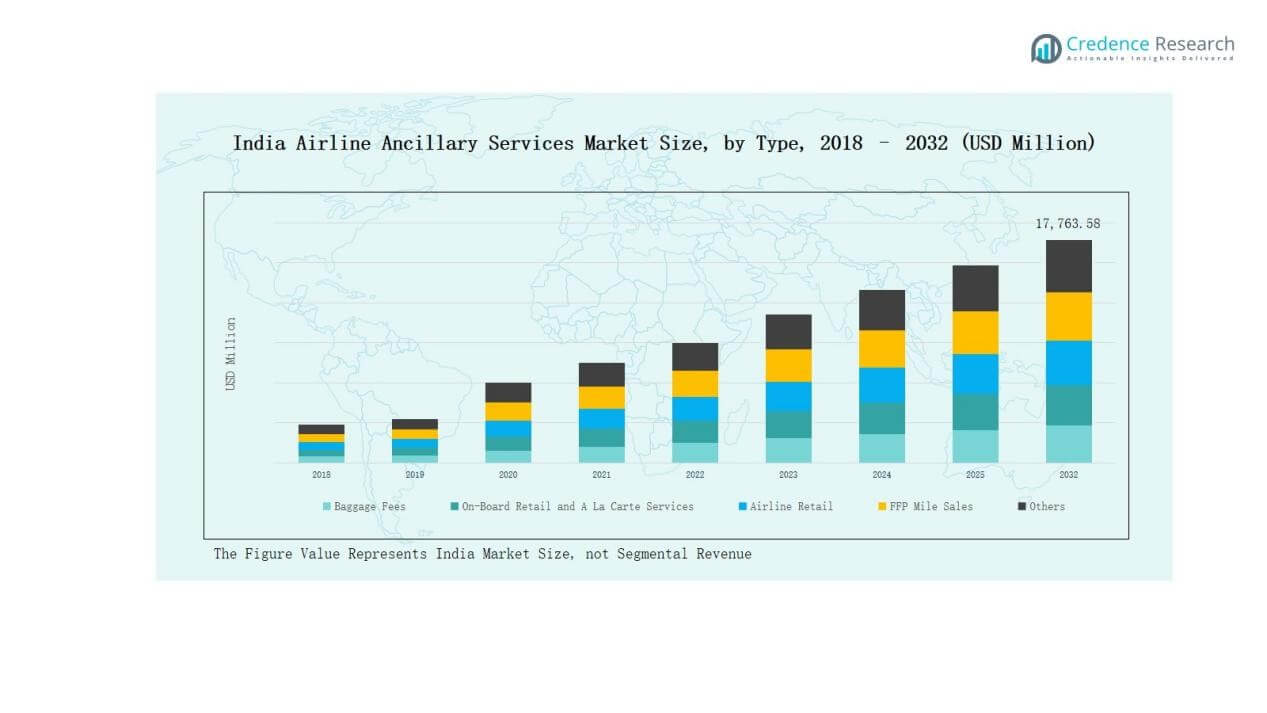
India Airline Ancillary Services Market size was valued at USD 3,056.48 million in 2018, reached USD 6,461.88 million in 2024, and is anticipated to reach USD 17,763.58 million by 2032, at a CAGR of 12.56% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| India Airline Ancillary Services Market Size 2024 | USD 6,461.88 Million |
| India Airline Ancillary Services Market, CAGR | 12.56% |
| India Airline Ancillary Services Market Size 2032 | USD 17,763.58 Million |
The India Airline Ancillary Services Market is shaped by leading players such as IndiGo, SpiceJet, Air India, Vistara, Akasa Air, Cleartrip, and Bird Group. IndiGo leads the market with a strong focus on baggage fees, dynamic pricing, and wide domestic coverage, while SpiceJet and Akasa Air emphasize bundled ancillary offerings to attract price-sensitive travelers. Air India and Vistara leverage loyalty programs, premium services, and international connectivity to strengthen revenues. Cleartrip and Bird Group expand ancillary ecosystems through digital travel solutions. Regionally, South India commanded the largest share at 31% in 2024, supported by strong passenger traffic from Bengaluru, Hyderabad, and Chennai, along with international routes connecting Southeast Asia and the Middle East.
 Market Insights
- The India Airline Ancillary Services Market grew from USD 3,056.48 million in 2018 to USD 6,461.88 million in 2024 and is projected to reach USD 17,763.58 million by 2032, expanding at 12.56% CAGR.
- South India led with 31% share in 2024, supported by strong traffic from Bengaluru, Hyderabad, and Chennai, while North, West, and East India accounted for 29%, 24%, and 16% respectively.
- By type, baggage fees dominated with 34% share in 2024, followed by on-board retail and à la carte services at 26%, airline retail at 18%, FFP mile sales at 15%, and others at 7%.
- By carrier type, low-cost carriers commanded 58% share in 2024, driven by baggage and seat selection revenues, while full-service carriers held 42% with strength in loyalty programs and premium services.
- Key players include IndiGo, SpiceJet, Air India, Vistara, Akasa Air, Cleartrip, and Bird Group, with IndiGo leading through dynamic pricing and wide domestic coverage.
Market Segment Insights
By Type
Baggage fees dominated the India Airline Ancillary Services Market with 34% share in 2024, driven by rising passenger volumes, strict baggage policies, and dynamic pricing by airlines. On-board retail and à la carte services followed with 26% share, supported by demand for food, beverages, seat upgrades, and convenience add-ons. Airline retail contributed 18%, boosted by duty-free sales and brand partnerships. FFP mile sales accounted for 15%, led by full-service carriers, while the “Others” segment held 7%, covering insurance and mobility services.
For instance, Air India expanded its premium meals and seat-selection services in 2024 as part of its broader transformation plan to enhance in-flight experience and boost non-ticket income
By Carrier Type
Low-cost carriers led the market with 58% share in 2024, capitalizing on baggage fees, meal sales, and seat selection to offset lower base fares. Their dynamic pricing strategies and wide domestic networks fuel strong revenue growth. Full-service carriers accounted for 42% share, supported by structured loyalty programs, premium retail sales, and business traveler demand. Expanding international connectivity and global alliances continue to strengthen their ancillary revenue streams, balancing premium services with loyalty-driven customer retention.
For instance, American Airlines expanded its ancillary revenue through premium services such as upgraded seating and loyalty program monetization, contributing millions in incremental revenue annually.
Key Growth Drivers
Rising Passenger Traffic and Air Travel Demand
The rapid increase in domestic and international passenger traffic is a primary growth driver in the India Airline Ancillary Services Market. Expanding middle-class income, affordable airfare options, and regional airport development have boosted air travel adoption. With more passengers opting for low-cost carriers, ancillary revenue from baggage fees, meals, and seat selection grows steadily. This rising travel demand creates opportunities for airlines to expand service portfolios, maximize revenues, and enhance customer experiences, especially in cost-sensitive and price-competitive markets.
For instance, SpiceJet expanded its paid in-flight meal and preferred seating options, successfully increasing its non-ticket revenue.
Adoption of Low-Cost Carrier Business Models
The dominance of low-cost carriers significantly contributes to ancillary revenue growth in India. These carriers rely heavily on non-ticket income streams, emphasizing baggage fees, priority services, and on-board retail. Their competitive base fares attract mass travelers, while ancillary services boost profitability. As low-cost carriers expand networks to tier-II and tier-III cities, they introduce new opportunities to monetize additional services. This model strengthens the share of ancillary revenues, positioning them as a vital component of overall airline financial strategies.
For instance, SpiceJet has expanded its ancillary portfolio by offering priority check-in, “SpiceMax” seating, and charter services to enhance non-fare income.
Digitalization and Personalized Service Offerings
Digital platforms and data-driven strategies are transforming ancillary revenue generation in India. Airlines are integrating pre-booking options for meals, seat selection, and baggage to improve convenience and revenue predictability. Personalized offers through mobile apps and loyalty programs enhance customer engagement. The rise of cashless payments and in-flight connectivity further supports the adoption of digital ancillary services. This shift not only streamlines operations but also ensures that passengers perceive added value, strengthening ancillary income streams for both low-cost and full-service carriers.
 Key Trends & Opportunities
Expansion of Loyalty Programs and Partnerships
Frequent flyer programs (FFPs) are evolving into broader lifestyle ecosystems through partnerships with banks, retailers, and digital platforms. Airlines in India increasingly monetize mile sales to credit card companies and third-party partners, boosting ancillary revenues. Loyalty integration provides passengers with value-driven benefits such as upgrades and exclusive privileges. The trend presents a strong opportunity for airlines to strengthen brand loyalty, improve customer retention, and diversify ancillary income, particularly as full-service carriers expand their global alliance networks.
For instance, Air India, after joining the Star Alliance network, enhanced its Flying Returns program by partnering with SBI Card to allow members to earn and redeem miles through co-branded credit cards.
Growth of Ancillary Revenue from Regional Connectivity
India’s regional connectivity scheme (UDAN) and growing focus on underserved routes open opportunities for ancillary revenue growth. With rising traffic on short-haul domestic routes, low-cost carriers can expand offerings such as baggage bundles, priority boarding, and insurance add-ons. Ancillary services also provide airlines with higher margins on budget-friendly routes, ensuring financial sustainability. As smaller cities witness increasing air travel adoption, airlines can leverage localized demand, strengthen market penetration, and diversify ancillary income streams beyond major metropolitan hubs.
For instance, IndiGo introduced its “6E QuickBoard” paid priority boarding service across metro and tier-2 routes, providing passengers faster access while boosting non-ticket revenues.
Key Challenges
Regulatory Constraints on Pricing Flexibility
Government regulations around pricing transparency and passenger rights present challenges for ancillary revenue growth. Restrictions on charging excessive baggage or cancellation fees limit airlines’ ability to maximize non-ticket income. Regulatory interventions to protect consumer interests can disrupt airline pricing models, especially for low-cost carriers dependent on ancillary revenue streams. Airlines must balance compliance with profitability, making it difficult to implement aggressive ancillary pricing strategies. This regulatory oversight continues to shape the competitive landscape of India’s aviation sector.
High Competition Among Domestic Carriers
The competitive landscape of India’s aviation market intensifies pricing pressures and limits revenue flexibility. With multiple low-cost carriers competing for the same passenger base, ancillary service differentiation becomes critical. Price-sensitive consumers often compare costs across airlines before booking, making it difficult for carriers to sustain higher ancillary fees. This competitive environment forces airlines to invest heavily in service innovation while maintaining affordable pricing. Sustaining profitability amid growing competition poses a consistent challenge to market players.
Passenger Sensitivity Toward Additional Charges
Indian travelers remain highly price-conscious, creating resistance toward paying for extra services. While baggage fees and priority add-ons are common, passenger pushback against rising charges can restrict revenue growth. Negative perceptions around hidden costs may also impact airline brand loyalty. To counter this, airlines must focus on transparent pricing and demonstrate clear value for ancillary services. Balancing affordability with profitability remains a critical challenge, as customer satisfaction plays a vital role in sustaining market presence.
Regional Analysis
North India
North India held 29% share in 2024, driven by strong air traffic in Delhi, Chandigarh, and Lucknow. The region benefits from international connectivity through Indira Gandhi International Airport, which serves as a major hub. Low-cost carriers dominate here by leveraging baggage fees and retail add-ons. Full-service carriers strengthen revenue through loyalty programs targeting corporate and premium travelers. Rising disposable incomes and growing tourism to hill states contribute to service demand. The India Airline Ancillary Services Market in this region continues to expand with increased passenger preference for both domestic and international flights.
South India
South India accounted for the largest share with 31% in 2024, supported by leading airports in Bengaluru, Hyderabad, and Chennai. The region’s strength comes from high outbound passenger traffic and expanding IT and business hubs. Low-cost carriers maximize revenue through à la carte services, while full-service airlines benefit from international routes to Southeast Asia and the Middle East. Strong baggage revenue streams and retail sales enhance growth. It remains the most dynamic regional market with a strong mix of business and leisure travelers.
West India
West India represented 24% share in 2024, anchored by major airports in Mumbai, Pune, and Ahmedabad. Mumbai serves as both a financial hub and a key international gateway, fueling demand for premium services and frequent flyer programs. Low-cost carriers drive growth in tier-II cities through baggage and seat selection revenues. Retail partnerships at airports enhance airline revenues in this region. It benefits from a mix of corporate and leisure travel, ensuring a balanced contribution to overall ancillary income.
East India
East India contributed 16% share in 2024, led by traffic from Kolkata, Bhubaneswar, and Guwahati. The region experiences steady growth through expanding connectivity under government-supported regional schemes. Low-cost carriers capitalize on baggage fees and on-board retail services for profitability. Rising tourism to northeastern states supports passenger demand for bundled travel services. Full-service carriers are gradually expanding their presence to capture premium travelers. It remains the smallest regional market but demonstrates strong growth potential with increasing passenger traffic.
 Market Segmentations:
By Type
- Baggage Fees
- On-Board Retail and A La Carte Services
- Airline Retail
- FFP (Frequent Flyer Program) Mile Sales
- Others
By Carrier Type
- Full-Service Carriers
- Low-Cost Carriers
By Region
- North India
- South India
- West India
- East India
Competitive Landscape
The India Airline Ancillary Services Market is highly competitive, shaped by a mix of low-cost and full-service carriers alongside digital travel platforms. IndiGo leads with a strong focus on baggage fees and dynamic pricing strategies, contributing significantly to its profitability. SpiceJet and Akasa Air strengthen competition through bundled ancillary offerings targeting cost-sensitive travelers. Air India and Vistara leverage premium services, loyalty programs, and international networks to capture high-value customers. Online platforms such as Cleartrip and Bird Group expand the ecosystem by offering integrated travel services and cross-selling opportunities. Airlines adopt diversified strategies, including digitalization, partnerships, and retail collaborations, to maximize non-ticket revenue. Competition intensifies as carriers expand routes and passenger bases, while price-sensitive consumers push for transparency and value-driven services. The landscape continues to evolve, with innovation in personalized services and loyalty integration expected to further shape competitive positioning in this fast-growing ancillary services market.
Key Players
- IndiGo (InterGlobe Aviation Ltd.)
- SpiceJet Ltd.
- Air India (Tata Group)
- Vistara
- Akasa Air
- Cleartrip
- Bird Group
Recent Developments
- On September 5, 2024, Air India became the first Indian airline to implement the New Distribution Capability (NDC) standard. This integration allows travel agents to access real-time, personalized offers, including tailored flight packages and ancillary products, enhancing the booking experience
- In October 2024, Air India announced a strategic partnership with Verteil Technologies to make its NDC content accessible through Verteil's distribution platform, Verteil Direct Connect.
- In October 2024, SpiceJet introduced 32 new flights, including 30 domestic routes and two daily non-stop services between Delhi and Phuket, improving connectivity.
- In November 2024, IndiGo launched IndiGoStretch, a premium service offering business-class seats, healthy meals by Oberoi, priority check-in, and up to 30 kg baggage allowance.
Report Coverage
The research report offers an in-depth analysis based on Type, Carrier Type and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Airlines will expand ancillary revenue streams through bundled baggage and seat selection services.
- Digital platforms will strengthen pre-booking and in-flight purchases for food, retail, and upgrades.
- Loyalty programs will evolve with broader partnerships across banking, retail, and hospitality sectors.
- Low-cost carriers will continue to lead ancillary revenue generation through flexible add-on models.
- Full-service carriers will enhance premium service offerings to attract business and frequent travelers.
- Airport retail and duty-free collaborations will boost non-ticket revenues for both carriers and partners.
- Regional connectivity growth will create opportunities for ancillary service adoption in tier-II and tier-III cities.
- Personalized offers based on passenger data will improve ancillary sales and customer satisfaction.
- Travel insurance and third-party service tie-ups will diversify revenue beyond traditional categories.
- Technology adoption, including mobile apps and digital payments, will drive seamless ancillary experiences.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Passenger Traffic and Air Travel Demand
The rapid increase in domestic and international passenger volumes, driven by expanding middle-class income, affordable airfares, and regional airport development, is fueling demand for ancillary services such as baggage fees, meals, and seat selection, thereby boosting market growth.
Adoption of Low-Cost Carrier Business Models
The dominance of low-cost carriers in India, which rely heavily on ancillary revenue streams like baggage fees, priority services, and on-board retail, is significantly increasing the share of non-ticket income and driving overall market expansion.
Digitalization and Personalized Service Offerings
The integration of digital platforms, mobile apps, and data-driven personalization enables airlines to offer pre-booked meals, seat selection, and tailored ancillary services, enhancing customer convenience and increasing ancillary revenue streams.
Expansion of Loyalty Programs and Partnerships
Airlines are evolving frequent flyer programs into broader lifestyle ecosystems through partnerships with banks, retailers, and digital platforms, monetizing mile sales and strengthening customer retention, which diversifies and grows ancillary income.
Growth of Ancillary Revenue from Regional Connectivity
Government initiatives like the UDAN scheme and increased connectivity to tier-II and tier-III cities are opening new opportunities for airlines to offer bundled ancillary services, such as baggage bundles and priority boarding, especially on short-haul and underserved routes.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for India Airline Ancillary Services Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the India Airline Ancillary Services Market projected to grow between 2025 and 2032?
Which India Airline Ancillary Services Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the India Airline Ancillary Services Market?
Who are the leading companies in the India Airline Ancillary Services Market?
Which region commanded the largest share of the India Airline Ancillary Services Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Baggage Fees
- 1.2.2 On-Board Retail and A La Carte Services
- 1.2.3 Airline Retail
- 1.2.4 FFP (Frequent Flyer Program) Mile Sales
- 1.2.5 Others
- 1.3 By Carrier Type
- 1.3.1 Full-Service Carriers
- 1.3.2 Low-Cost Carriers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6,461.88 million → 2032: USD 17,763.58 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 India Airline Ancillary Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 India Airline Ancillary Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 India Airline Ancillary Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 India Airline Ancillary Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 India Airline Ancillary Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 India Airline Ancillary Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 India Airline Ancillary Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 India Airline Ancillary Services Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6,461.88 million → 2032: USD 17,763.58 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 India Airline Ancillary Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Baggage Fees
- 12.3.6.2 On-Board Retail and A La Carte Services
- 12.3.6.3 Airline Retail
- 12.3.6.4 FFP (Frequent Flyer Program) Mile Sales
- 12.3.6.5 Others
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Carrier Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Full-Service Carriers
- 12.4.6.2 Low-Cost Carriers
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 India Airline Ancillary Services Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 India Airline Ancillary Services Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2024-2032
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 India Airline Ancillary Services Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 IndiGo (InterGlobe Aviation Ltd.)
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 SpiceJet Ltd.
- 17.4 Air India (Tata Group)
- 17.5 Vistara
- 17.6 Akasa Air
- 17.7 Cleartrip
- 17.8 Bird Group
- 17.9 Go First
- 17.10 MakeMyTrip
- 17.11 AirAsia India
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

