
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Alcohol E-Commerce Market Size 2024 | USD 64,545 Million |
| Alcohol E-Commerce Market, CAGR | 16.8% |
| Alcohol E-Commerce Market Size 2032 | USD 223,565.78 Million |
Market Overview:
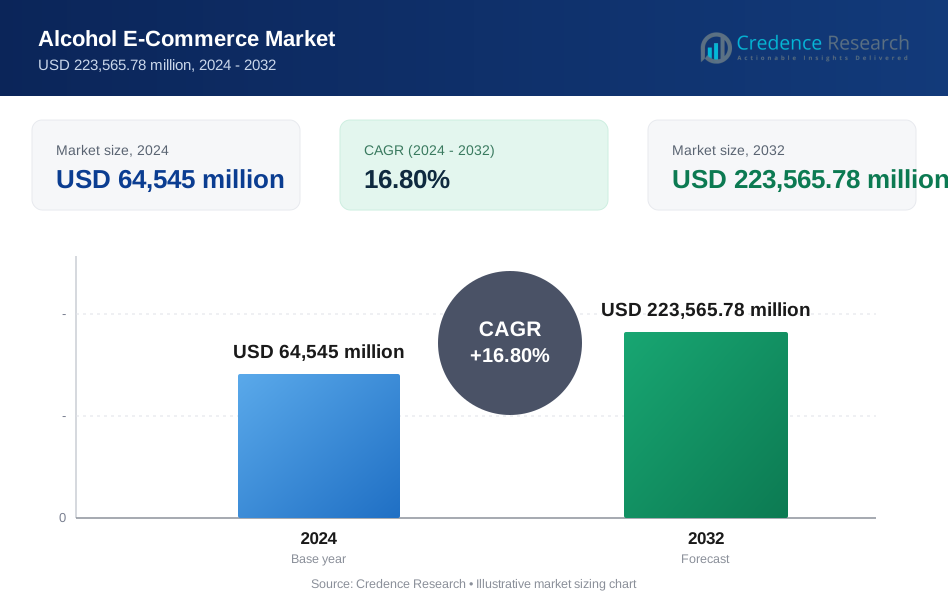
The Alcohol E-Commerce Market is projected to grow from USD 64,545 million in 2024 to USD 223,565.78 million by 2032, expanding at a robust CAGR of 16.8% during the forecast period.
The Alcohol E-Commerce Market is witnessing significant growth driven by increasing internet penetration, changing consumer preferences, and the convenience of online shopping. Rapid urbanization and rising disposable incomes have fueled demand for premium and craft alcoholic beverages, encouraging consumers to explore digital platforms for diverse product options. The adoption of direct-to-consumer (DTC) strategies by alcohol brands, along with the expansion of same-day delivery and subscription services, has further boosted online alcohol sales. Regulatory relaxations in various regions have also enabled smoother operations for alcohol e-commerce platforms. Additionally, the integration of advanced technologies such as AI-powered recommendations and mobile applications enhances customer experience and engagement. Social media marketing and influencer collaborations are shaping consumer choices, making digital channels increasingly influential. The COVID-19 pandemic accelerated this shift by highlighting the benefits of contactless delivery and digital convenience. These factors collectively indicate a sustained upward trend in the alcohol e-commerce landscape, presenting new opportunities for retailers and manufacturers alike.
The alcohol e-commerce market exhibits significant regional variation, with North America holding the largest share of 38% in 2024, driven by robust digital infrastructure and favorable regulations. Europe, accounting for 28%, is supported by strong consumer demand for premium beverages and established online retail ecosystems. Asia-Pacific, with a 22% share, is expanding rapidly due to urbanization and increasing disposable income, particularly in China and India. The Rest of the World, holding 12%, includes emerging markets in Latin America, the Middle East, and Africa, where internet access and regulatory changes are opening new opportunities. Key players like Drizly, BevMo, Flaviar, Bright Cellars, and Delivery.com have established a strong presence across these regions, catering to diverse consumer preferences and leveraging local logistics networks to capture market share. Their strategic expansion is pivotal in tapping into regional growth potential.
Market Insights:
- The alcohol e-commerce market is projected to grow from USD 64,545 million in 2024 to USD 223,565.78 million by 2032, expanding at a CAGR of 16.8%.
- Increasing internet penetration, smartphone adoption, and the convenience of online shopping are major drivers of the market’s growth.
- Consumer preferences are shifting toward premium, craft, and niche alcoholic beverages, boosting demand for diverse product offerings online.
- Direct-to-consumer strategies and the rise of subscription-based models are enhancing the customer experience and driving sales.
- Regulatory relaxations in various regions, along with the implementation of age verification technologies, are creating a more favorable environment for alcohol e-commerce.
- The COVID-19 pandemic accelerated the adoption of e-commerce, emphasizing the benefits of contactless delivery and digital platforms.
- North America holds the largest market share (38%), followed by Europe at 28%, Asia-Pacific at 22%, and the Rest of the World at 12% in 2024.
Market Drivers:
Growing Internet Penetration and Smartphone Usage:
The rapid expansion of internet connectivity and the increasing adoption of smartphones have significantly contributed to the growth of the alcohol e-commerce market. Consumers across urban and semi-urban areas now have access to digital platforms, enabling them to explore and purchase a variety of alcoholic beverages from the comfort of their homes. For instance, Uber expanded its alcohol delivery services by acquiring Drizly in 2021, enabling millions of app users to order a wide selection of alcoholic beverages for home delivery through their smartphones. This digital shift has transformed traditional buying behaviors and facilitated seamless transactions, making e-commerce platforms a preferred choice for alcohol purchases.
Shifting Consumer Preferences and Lifestyle Changes:
Modern consumers, particularly younger demographics, are increasingly inclined toward convenience, premium experiences, and personalized services. The demand for craft spirits, organic wines, and niche alcoholic beverages has surged, aligning well with the offerings available online. For instance, Vivino, a leading wine app, leverages its database of over 12 million wines and more than 46 million users to provide personalized wine recommendations based on individual taste profiles, with over 85% of users finding its rating system accurately reflects their preferences. E-commerce platforms cater to these evolving tastes by providing access to diverse product ranges, curated collections, and user reviews, which empower consumers to make informed decisions and enjoy customized shopping experiences.
Expansion of Direct-to-Consumer Strategies:
Alcohol brands are increasingly leveraging direct-to-consumer (DTC) strategies to strengthen their online presence and build deeper customer relationships. By bypassing traditional retail intermediaries, brands can offer exclusive products, better pricing, and enhanced customer service. This approach allows companies to collect valuable consumer data, personalize marketing campaigns, and improve customer retention. As a result, DTC models have become a vital driver of growth in the alcohol e-commerce ecosystem.
Regulatory Adaptation and Market Liberalization:
Recent regulatory changes in various regions have created a more favorable environment for alcohol e-commerce. Governments and regulatory bodies have recognized the potential of online platforms in ensuring responsible sales and tax compliance. Revisions in licensing frameworks and the introduction of age verification technologies have helped address safety and legal concerns, encouraging more businesses to enter the market. These progressive developments are fostering innovation, competition, and long-term sustainability in the alcohol e-commerce sector.
Market Trends:
Rise of Omnichannel Retailing:
A key trend shaping the alcohol e-commerce market is the growing adoption of omnichannel retail strategies. Traditional liquor retailers and large beverage companies are increasingly integrating online and offline touchpoints to enhance customer engagement and improve service delivery. For instance, Majestic Wine in the UK connects its website, mobile app, and physical stores, allowing customers to shop and receive personalized recommendations based on data collected from all touchpoints, which has driven increased loyalty and sales. This hybrid approach allows consumers to browse products online and choose between home delivery or in-store pickup, offering greater flexibility and convenience. Retailers are also using data from both channels to personalize marketing and refine inventory strategies.
Growth of Subscription-Based Models:
Subscription services are gaining traction in the alcohol e-commerce market as consumers seek curated, convenient, and consistent delivery of their preferred beverages. These models often include monthly boxes of wines, craft beers, or spirits tailored to individual taste profiles. For instance, Barsys and ReserveBar launched the Barsys Subscription Box in 2024, offering AI-personalized cocktail kits delivered to consumers’ doors, allowing users to select spirits and mixers based on their unique taste profiles. The personalized experience not only enhances customer loyalty but also offers brands valuable insights into consumer preferences. Subscription models also help brands forecast demand more accurately and manage logistics more efficiently.
Expansion of Premium and Niche Product Segments:
There is a notable increase in consumer interest in premium, craft, and niche alcoholic products through online channels. Consumers are drawn to limited-edition releases, artisanal brands, and organic or sustainably sourced options that are more readily available through digital platforms. E-commerce sites are capitalizing on this trend by offering exclusive collections, detailed product information, and storytelling that highlights brand authenticity, helping consumers make more informed and emotionally connected purchase decisions.
Integration of Advanced Technologies:
Technological advancements such as AI-powered product recommendations, AR-based label scanning, and voice-activated shopping are enhancing the digital alcohol purchasing experience. These innovations are enabling platforms to provide personalized experiences, improve customer satisfaction, and streamline operations. The use of big data analytics and predictive algorithms is also helping companies better understand buying patterns and optimize marketing strategies, ultimately driving efficiency and sales in the alcohol e-commerce market.
Market Challenges Analysis:
Complex Regulatory Landscape:
The alcohol e-commerce market is heavily influenced by a fragmented and stringent regulatory environment, which poses a significant challenge to industry growth and scalability. Alcohol is subject to diverse laws across jurisdictions, encompassing licensing, taxation, age verification, and marketing limitations. These laws vary not only between countries but also within states and provinces, making cross-border operations complex and costly. Many regions still prohibit or restrict the online sale and home delivery of alcohol, while others require businesses to obtain multiple licenses to legally operate. For instance, a California Department of Alcoholic Beverage Control investigation found that on-demand delivery apps such as DoorDash and Postmates failed to verify the age of recipients in up to 80% of test deliveries, highlighting both the regulatory risks and the operational challenges companies face in maintaining compliance with age verification requirements. Navigating this intricate legal landscape demands substantial resources for compliance management and legal consultation. Failure to comply with regulations can lead to penalties, revoked licenses, or reputational damage, deterring new entrants and limiting expansion opportunities. Additionally, evolving policies around digital alcohol sales mean companies must stay continually updated, adapting their operational and legal frameworks accordingly. This regulatory uncertainty creates a barrier to innovation and adds friction to consumer accessibility.
Logistical and Operational Barriers:
Operational challenges significantly impact the alcohol e-commerce market’s efficiency and customer experience. Unlike standard retail items, alcoholic beverages require specialized logistics due to their weight, fragility, and regulatory constraints related to transport and storage. Shipping costs are often higher, especially when dealing with glass packaging or products requiring temperature control. Ensuring that deliveries meet legal age verification standards adds another layer of complexity. In many regions, alcohol must be handed directly to an adult with valid ID, complicating the last-mile delivery process and reducing the feasibility of using traditional courier services. Delays, damaged goods, or failed delivery attempts can affect customer satisfaction and retention. Additionally, reverse logistics-handling returns, exchanges, or refunds-is more difficult due to the perishability and regulation of alcohol products. Smaller players often struggle to invest in the infrastructure required for efficient logistics, giving larger companies with established supply chains a competitive edge. These logistical challenges demand innovative solutions and continued investment to support sustainable growth.
Market Opportunities:
The alcohol e-commerce market presents substantial opportunities driven by shifting consumer behavior, digital transformation, and expanding global accessibility. As consumers increasingly seek convenience and personalized experiences, e-commerce platforms are well-positioned to meet these evolving expectations through curated product selections, tailored recommendations, and on-demand delivery options. The growth of digital payment systems and mobile commerce further facilitates seamless purchasing, encouraging higher consumer engagement and repeat transactions. Additionally, the rising popularity of social commerce and influencer marketing offers alcohol brands new avenues to connect with younger, tech-savvy audiences. Brands that invest in data analytics and customer relationship management can leverage insights to refine targeting strategies, improve customer retention, and offer customized promotions, ultimately enhancing brand loyalty and revenue generation.
Expanding into emerging markets also represents a significant opportunity for alcohol e-commerce players. As internet penetration and smartphone usage continue to rise in developing regions, consumers are becoming more receptive to online shopping for alcoholic beverages. These markets often feature a growing middle class with increasing disposable income and a willingness to explore new product categories. Furthermore, as regulatory frameworks in many of these regions begin to evolve in favor of controlled online alcohol sales, early movers can establish a strong foothold and capture market share. There is also potential for growth in underrepresented product categories such as non-alcoholic alternatives and sustainable or organic alcoholic beverages, which are gaining traction among health-conscious consumers. By adopting innovative delivery models, forging partnerships with local logistics providers, and leveraging localized marketing strategies, alcohol e-commerce businesses can tap into these expanding market segments and drive long-term, sustainable growth.
Market Segmentation Analysis:
By Alcohol Type
The alcohol e-commerce market is segmented into beer & cider, spirits, and wine. Beer & cider dominate in volume due to widespread popularity and affordability. Spirits account for significant value driven by premiumization trends, while wine continues to grow steadily, especially among health-conscious and socially engaged consumers seeking variety and exclusivity online.
By Value
The market categorizes products into economy, mid-range, and luxury segments. Economy options attract price-sensitive buyers, particularly in developing regions. Mid-range products represent the largest segment, balancing affordability and quality. Meanwhile, the luxury segment is expanding rapidly, driven by consumer demand for craft beverages, exclusivity, and unique tasting experiences in the digital retail space.
By Revenue Model
Alcohol e-commerce operates primarily through one-time purchases and subscription-based models. One-time purchases dominate overall revenue, offering flexibility and accessibility. However, subscription-based models are gaining momentum, especially for wine and craft spirits, as they provide curated selections, enhanced customer loyalty, and consistent revenue streams for e-commerce platforms and alcohol brands.
Segments:
Based on Alcohol Type
- Beer & Cider
- Spirits
- Wine
Based on Value
- Economy
- Luxury
- Mid-Range
Based on Revenue Model
- One-Time Purchase
- Subscription-Based
Based on Distribution Channel
- Direct to Consumer
- Licensed Specialty Retailer
- Online Alcohol Marketplace
Based on the Geography:
- North America
- S.
- Canada
- Mexico
- Europe
- Germany
- France
- K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a significant position in the alcohol e-commerce market, accounting for the largest share of 38% in 2024. The region's mature digital infrastructure, coupled with a high adoption rate of online shopping, has fostered rapid growth in this segment. The U.S. market, in particular, benefits from evolving state-level regulations that increasingly permit online alcohol sales and home delivery. Consumers are drawn to the convenience of digital platforms, personalized offerings, and a wide selection of craft beverages. Additionally, the rising demand for premium spirits and wines, along with robust direct-to-consumer models, has reinforced North America’s dominance in the global market.
Europe
Europe represented 28% of the global alcohol e-commerce market share in 2024, driven by strong consumer demand for premium and organic alcoholic beverages. Countries like the United Kingdom, Germany, and France have well-established online retail ecosystems and favorable regulatory frameworks supporting alcohol sales via e-commerce channels. European consumers increasingly prefer curated experiences, subscription boxes, and access to international and craft brands. Moreover, the region's strong wine culture and evolving drinking habits, particularly among younger demographics, continue to support market expansion through digital platforms.
Asia-Pacific
Asia-Pacific accounted for 22% of the alcohol e-commerce market share in 2024, fueled by rapid urbanization, increasing disposable income, and rising smartphone penetration. China and India are key growth engines in this region, with expanding middle-class populations embracing online shopping and premium lifestyle choices. Government initiatives supporting digital commerce, along with growing investments in logistics infrastructure, have made it easier for e-commerce platforms to cater to alcohol consumers. Additionally, the region is witnessing growing interest in international spirits and wines, making it an attractive area for global alcohol brands to explore e-commerce opportunities.
Rest of the World
The Rest of the World, including Latin America, the Middle East, and Africa, held 12% of the alcohol e-commerce market share in 2024. While these regions are still emerging in terms of digital alcohol retail, increasing internet access and gradual regulatory changes are opening new avenues. Markets such as Brazil and South Africa are showing promising growth, supported by youthful populations and rising awareness of online purchasing platforms. Continued investment in local logistics and legal reforms could unlock significant potential in these underserved areas over the coming years.
Key Player Analysis:
- Flaviar, Inc.
- BevMo!
- eVino, d.o.o.
- Drizly, LLC by Uber Technologies, Inc.
- Cellarstash
- Drink Supermarket
- com, LLC
- Harris Teeter
- Bright Cellers
- Bid for Wine
- Avalara, Inc.
Competitive Analysis:
The alcohol e-commerce market is highly competitive, with several prominent players driving growth and innovation. Leading companies like Drizly, BevMo!, Flaviar, and Bright Cellars have established strong market presence by offering a wide range of products, including premium, craft, and niche alcoholic beverages, along with convenient delivery services. Drizly, backed by Uber Technologies, has revolutionized the market with its same-day delivery service, while Flaviar excels in curated subscription offerings, appealing to enthusiasts of rare and exclusive spirits. BevMo! continues to leverage its strong offline retail presence, expanding into the online sphere to cater to both budget-conscious and premium consumers. Bright Cellars uses data-driven recommendations to personalize wine subscriptions, fostering customer loyalty. Other notable players like Delivery.com and eVino focus on specific niches, offering diverse alcohol selections with a focus on user convenience. As competition intensifies, companies must innovate their product offerings, improve customer service, and optimize delivery operations to stay ahead in this fast-growing market.
Recent Developments:
- In September 2024, Flaviar, Inc. announced the acquisition of Speakeasy Co., a leading US beverage alcohol (BevAlc) e-commerce enablement provider, in a cash and stock deal.
- On February 1, 2023, BevMo! became available on Drizly’s platform as part of a significant e-commerce expansion following a partnership between Drizly and Gopuff.
- In April 2024, Bright Cellars was acquired by Full Glass Wine Co., a move that expands Full Glass Wine’s direct-to-consumer (DTC) wine portfolio and strengthens its position in the DTC wine market.
- In April 2025, Avalara announced it had been verified as a Trusted Seller on TrustRadius, highlighting its commitment to transparency, unbiased customer reviews, and providing current product information.
Market Concentration & Characteristics:
The alcohol e-commerce market exhibits moderate to high concentration, with several key players dominating the landscape. Leading companies, such as Drizly, BevMo!, Flaviar, and Bright Cellars, capture significant market share through robust online platforms and strong brand presence. These companies leverage advanced technologies, personalized services, and diverse product offerings to attract a wide customer base. Despite the dominance of major players, the market also offers opportunities for smaller, niche companies to thrive, particularly those focusing on craft or premium alcoholic beverages. These niche players often differentiate themselves through curated experiences, subscription models, and personalized recommendations, catering to evolving consumer preferences for unique and exclusive products. While large companies benefit from economies of scale and established logistics networks, smaller players can remain competitive by focusing on specific segments or regional markets. The dynamic nature of the market encourages continuous innovation, driving growth and competition.
Report Coverage:
The research report offers an in-depth analysis based on Alcohol Type, Value, Revenue Model, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The alcohol e-commerce market is expected to continue expanding, driven by increasing consumer demand for convenience and variety.
- The growing trend of premiumization will lead to higher sales of craft and luxury alcoholic beverages through online platforms.
- Direct-to-consumer (DTC) models will become more prevalent, allowing brands to build stronger customer relationships and offer exclusive products.
- The rise of subscription services will further cater to consumers seeking curated selections and personalized experiences.
- Regulatory frameworks will continue to evolve, creating more favorable conditions for alcohol e-commerce in emerging markets.
- The increasing adoption of AI and data analytics will enhance product recommendations, improving customer satisfaction and engagement.
- Mobile platforms will play a critical role in the market’s growth, offering seamless shopping experiences and payment options.
- Social media marketing and influencer collaborations will significantly shape consumer purchasing decisions in the alcohol e-commerce space.
- Emerging markets in Asia-Pacific and Latin America will provide new opportunities, fueled by urbanization and rising disposable incomes.
- Logistics infrastructure improvements will reduce delivery times and costs, boosting the efficiency of alcohol e-commerce operations.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Alcohol E-Commerce Market?
What factors are driving the growth of the Alcohol E-Commerce Market?
What are the key segments within the Alcohol E-Commerce Market?
What are some challenges faced by the Alcohol E-Commerce Market?
Who are the major players in the Alcohol E-Commerce Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Alcohol E-Commerce Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Alcohol E-Commerce Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 64,545 million → 2032: USD 223,565.78 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Alcohol E-Commerce Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Alcohol E-Commerce Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Alcohol E-Commerce Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Alcohol E-Commerce Market Drivers
- 3.3 Alcohol E-Commerce Market Restraints & Challenges
- 3.4 Alcohol E-Commerce Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Alcohol E-Commerce Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Alcohol E-Commerce Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Alcohol E-Commerce category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Alcohol E-Commerce Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Alcohol E-Commerce Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Alcohol E-Commerce. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Alcohol E-Commerce Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Alcohol E-Commerce Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Alcohol E-Commerce Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Alcohol E-Commerce (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Alcohol E-Commerce
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Alcohol E-Commerce Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Alcohol E-Commerce Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Alcohol E-Commerce Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Alcohol E-Commerce Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Alcohol E-Commerce Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Alcohol E-Commerce Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Alcohol E-Commerce Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Alcohol E-Commerce Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
