
Market Overview
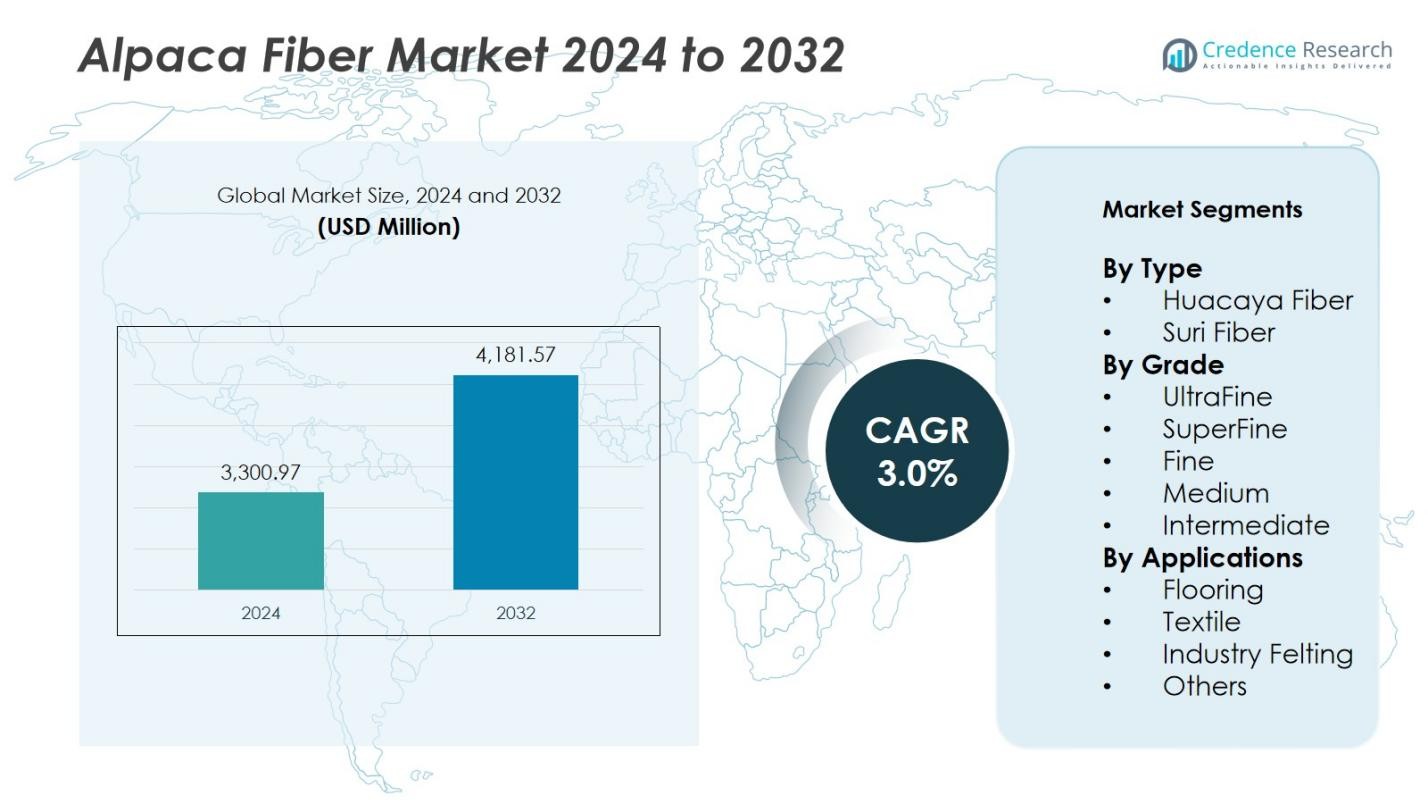
The Global Alpaca Fiber Market size was valued at USD 3,300.97 million in 2024 and is anticipated to reach USD 4,181.57 million by 2032, expanding at a CAGR of 3.0% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Alpaca Fiber Market Size 2024 | USD 3,300.97 Million |
| Alpaca Fiber Market, CAGR | 3.0% |
| Alpaca Fiber Market Size 2032 | USD 4,181.57 Million |
The Global Alpaca Fiber Market is characterized by moderate competition and growing international participation. Leading companies include Malabrigo Yarn, The Natural Fiber, Plymouth Yarn, Zeilinger Wool, New Era Fiber, Cascade Yarns, The Alpaca Yarn, AndeanSun Yarns, AHA Bolivia, and Coopecan. These firms focus on sourcing premium Huacaya and Suri fibers, maintaining quality through sustainable farming and traceable supply chains. Product innovation, such as blended alpaca yarns and eco-certified fabrics, strengthens their global positioning. Strategic partnerships with local cooperatives in Peru and Bolivia enhance raw material access and brand authenticity. Europe emerged as the leading region with a 28% share in 2024, driven by a strong preference for luxury, eco-friendly textiles and an established fashion industry. Continuous technological advancement and sustainability-led production practices are expected to support competitive differentiation and long-term growth across the Alpaca Fiber Market.
Market Insights
- The Global Alpaca Fiber Market was valued at USD 3,300.97 million in 2024 and is projected to reach USD 4,181.57 million by 2032, expanding at a CAGR of 3.0%.
- Growing demand for sustainable and biodegradable fibers drives market expansion, supported by rising adoption in luxury apparel, knitwear, and home textiles.
- Market trends highlight technological improvements in fiber processing, promoting better softness, durability, and eco-friendly dyeing methods.
- The competitive landscape features key players such as Malabrigo Yarn, The Natural Fiber, Plymouth Yarn, Zeilinger Wool, and Cascade Yarns, focusing on premium-grade and ethically sourced alpaca fiber.
- Europe held a 28% regional share in 2024, leading global consumption, while the Huacaya fiber segment dominated with 72% share, supported by increasing demand for high-quality textile and furnishing applications.
Market Segmentation Analysis:
By Type
Huacaya fiber dominates the Global Alpaca Fiber Market with a share of 72% in 2024, owing to its soft, crimpy texture and superior insulation properties, making it ideal for knitwear and high-end textiles. The fiber’s natural elasticity and volume enable easy spinning and dye absorption, which supports demand in luxury apparel and home furnishings. Suri fiber, with a 28% share, grows steadily due to its silky luster and strength, finding niche use in premium fashion and decorative products across the U.S., Peru, and European markets.
For instance, Peruvian company Inca Alpacas produces Huacaya fiber extensively for luxury knitwear and blankets, valuing its warmth and elasticity for easy spinning and dyeing.
By Grade
The SuperFine grade holds the largest share of 38% in 2024, driven by rising demand for lightweight, soft, and warm apparel such as sweaters, scarves, and shawls. Its fine diameter ensures exceptional comfort and breathability, making it popular among premium textile manufacturers. The UltraFine segment, accounting for 26%, is growing in high-end fashion applications due to its rarity and luxurious feel. Medium and Intermediate grades together contribute 36%, catering to upholstery and industrial textile applications where durability is prioritized.
For instance, Superfine fabrics produced by Austrian manufacturer Superfine are renowned for their fineness, softness, and comfort. Leading brands of premium clothing rely on Superfine® fabrics for their next-to-skin garments, emphasizing their homogeneous, smooth surface preferred in high-end knitwear.
By Application
The Textile segment leads the Alpaca Fiber Market, capturing 64% of total revenue in 2024, supported by growing use in luxury clothing, knitwear, and home furnishing products. Rising consumer preference for sustainable and hypoallergenic fabrics strengthens demand across fashion and interior sectors. The flooring segment, holding nearly 18%, benefits from increased use in rugs and carpets due to alpaca’s resilience and thermal insulation. Industrial felting and other applications collectively account for the remaining 18%, utilized in acoustic insulation and technical nonwoven products.
Key Growth Drivers
Rising Demand for Sustainable and Natural Fibers
The Global Alpaca Fiber Market grows due to the increasing consumer shift toward sustainable and eco-friendly materials. Alpaca fiber’s biodegradable nature, low environmental footprint, and absence of lanolin make it a preferred alternative to synthetic fibers. Fashion brands are integrating alpaca into luxury apparel lines, driven by ethical sourcing trends and sustainable fashion initiatives. Growing awareness about environmental protection further boosts its adoption in textiles, home furnishings, and high-end garments across Europe, North America, and Asia-Pacific.
For instance, Kelly & Windsor launched the Alpaca Royale quilt collection in 2024, featuring 100% pure alpaca fiber processed with environmentally friendly methods, further demonstrating the fiber's growing position in luxury eco-conscious products.
Expanding Luxury Apparel and Home Textile Segment
The expansion of luxury clothing and home décor markets strongly drives alpaca fiber consumption. Its softness, warmth, and hypoallergenic qualities enhance its appeal among high-income consumers. Premium brands increasingly use alpaca yarns for sweaters, scarves, coats, and blankets, supporting steady revenue growth. Rising disposable incomes, evolving fashion trends, and growing demand for handmade, artisanal products fuel segment expansion. The premium positioning of alpaca fiber products ensures consistent growth across developed and emerging economies.
For instance, PAKA, a well-known luxury brand, launched the Ultralight COOLPLUS line in May 2025, which combines thermoregulating alpaca fiber with organic cotton and advanced cooling yarns to create breathable, stylish sweaters suited for warm weather.
Government Support and Local Production Incentives
Government initiatives supporting rural economies and livestock management promote alpaca farming, particularly in Peru, Bolivia, and Chile. Programs focusing on quality improvement, genetic enhancement, and export promotion enhance fiber yield and quality. Financial incentives and technical support to small producers strengthen market supply and international competitiveness. The establishment of cooperatives and partnerships between local breeders and textile brands accelerates industry standardization. These initiatives collectively boost the availability of fine-quality alpaca fiber for global markets.
Key Trends & Opportunities
Technological Advancements in Fiber Processing
Innovations in spinning, dyeing, and blending technologies improve alpaca fiber quality and versatility. Automated processing systems help reduce fiber waste and enhance uniformity, supporting broader industrial use. Manufacturers increasingly blend alpaca with wool, silk, or synthetic fibers to enhance texture, elasticity, and performance. Such advancements expand applications across fashion, home textiles, and industrial felting. Continuous R&D investments in fiber treatment and color retention create new growth opportunities in premium textile manufacturing.
For instance, Tintalana, an Italian textile firm, upgraded its dyeing department with Cubotex RVS machines, achieving higher process efficiency and superior color quality while reducing energy consumption.
Rising Adoption in High-End Sustainable Fashion
The growing emphasis on ethical sourcing and transparency drives luxury fashion brands to adopt alpaca fiber. Designers are showcasing alpaca-based collections in major fashion events, highlighting its eco-friendly and luxurious appeal. The fiber’s durability and thermal comfort suit both winter and trans-seasonal clothing. Collaborations between global designers and South American cooperatives strengthen sustainable supply chains. Increasing consumer awareness about cruelty-free fibers further accelerates market opportunities in high-value fashion markets.
For instance, Samantha Holmes, a luxury brand, showcases alpaca knitwear and scarves designed for sustainability and durability, resonating with eco-conscious consumers.
Key Challenges
High Production and Processing Costs
Alpaca fiber production remains labor-intensive and costlier than other natural fibers. Limited automation in shearing, sorting, and grading increases overall production costs. Transporting raw fiber from remote regions to processing centers adds logistical expenses. These high operational costs restrict its adoption in mass-market textile applications. Manufacturers face challenges in maintaining affordability without compromising quality, making cost optimization critical for expanding market accessibility and competitiveness.
Limited Supply Chain Integration and Standardization
The alpaca fiber supply chain is fragmented, with inconsistent quality grading and lack of global certification standards. Variations in fiber quality across regions affect uniformity and pricing transparency. Small-scale producers often lack access to modern equipment and export networks, reducing efficiency and market reach. Absence of standardized quality benchmarks complicates international trade, limiting large-scale industrial adoption. Strengthening cooperative structures and establishing certification systems are essential to enhance global competitiveness.
Regional Analysis
North America
North America holds a market share of 26% in the Global Alpaca Fiber Market, driven by growing consumer preference for sustainable luxury textiles. The U.S. leads regional demand, supported by strong retail presence of eco-conscious brands and expanding artisan yarn markets. Increased import volumes from Peru and Bolivia strengthen supply chains for local manufacturers. Rising popularity of handmade knitwear and premium outdoor apparel further boosts consumption. Canada also shows growing adoption due to favorable climatic conditions for alpaca fiber use in winter garments and interior textiles.
Europe
Europe accounts for 28% of the market, led by countries such as the U.K., Germany, Italy, and France. The region’s well-established fashion industry and emphasis on eco-friendly materials drive continuous demand for alpaca fiber. European consumers value its natural softness and hypoallergenic properties, which suit luxury clothing and home décor. Several high-end fashion brands integrate alpaca textiles into their sustainable product lines. Government-backed green initiatives and rising import partnerships with South American suppliers further contribute to regional market expansion.
Asia-Pacific
Asia-Pacific captures a 22% share, emerging as one of the fastest-growing regions in the alpaca fiber market. China, Japan, and Australia lead demand, driven by rising disposable incomes and growing appreciation for premium fabrics. Expanding fashion and home furnishing sectors in these markets create lucrative opportunities for imports and local production. Increasing consumer interest in sustainable materials fuels collaborations between South American suppliers and Asian textile firms. Investments in blending technologies and fiber finishing also enhance the competitiveness of alpaca fiber in the region.
Latin America
Latin America dominates the global landscape with a 20% share, primarily driven by Peru, Bolivia, and Chile. Peru remains the world’s leading producer and exporter, supported by favorable climatic conditions for alpaca breeding and government-backed agricultural programs. The region benefits from abundant raw material availability and a well-developed network of cooperatives. Local value addition through yarn spinning and textile exports continues to strengthen regional economies. Growing global recognition of Peruvian alpaca fiber as a luxury textile material supports both export growth and domestic consumption.
Middle East & Africa
The Middle East & Africa region holds a 4% share, characterized by niche adoption in premium textile and fashion markets. Demand is gradually increasing in the UAE and South Africa due to expanding luxury retail sectors. Importers focus on alpaca’s natural insulation and moisture-wicking properties, catering to high-end consumers seeking sustainable fashion. Limited local production and high import costs currently restrict large-scale adoption. However, rising awareness of eco-conscious fabrics and potential partnerships with Latin American exporters are expected to create future growth avenues.
Market Segmentations:
By Type
- Huacaya Fiber
- Suri Fiber
By Grade
- UltraFine
- SuperFine
- Fine
- Medium
- Intermediate
By Applications
- Flooring
- Textile
- Industry Felting
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Global Alpaca Fiber Market features prominent players such as Malabrigo Yarn, The Natural Fiber, Plymouth Yarn, Zeilinger Wool, New Era Fiber, Cascade Yarns, The Alpaca Yarn, AndeanSun Yarns, AHA Bolivia, and Coopecan. The market is moderately fragmented, with competition centered around product quality, fiber grade, and sustainability standards. Companies focus on sourcing premium Huacaya and Suri fibers directly from Latin American farms to maintain consistent quality. Leading manufacturers emphasize eco-friendly processing and organic certifications to attract environmentally conscious consumers. Strategic collaborations with local cooperatives and expansion of online retail channels enhance brand visibility in international markets. Product innovation, including blended yarns and dyed alpaca fabrics, continues to shape competition. Many players are also investing in traceability and ethical sourcing programs to strengthen brand credibility and appeal to global fashion brands seeking sustainable luxury materials.
Key Player Analysis
- Malabrigo Yarn
- The Natural Fiber
- Plymouth Yarn
- Zeilinger Wool
- New Era Fiber
- Cascade Yarns
- The Alpaca Yarn
- AndeanSun Yarns
- AHA Bolivia
- Coopecan
Recent Developments
- In Nov 2024, the company PAKA expanded its Traceable Alpaca program to its full product line, enabling consumers to scan a QR code and trace the exact coordinates of the alpaca herds used in each garment.
- In Sep 2025, SOL ALPACA announced its expansion into strategic airports across Europe and Asia from Q1 2026, focusing on high-traffic locations and partnering with duty-free operators to enhance its international presence.
- In August 2024, MGI Tech, along with the National Agrarian University La Molina (UNALM) and Inca Tops S.A., announced a genomics partnership that will sequence 1,500 alpacas to improve fiber fineness and strengthen Peru's textile industry.
Report Coverage
The research report offers an in-depth analysis based on Type, Grade, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Alpaca Fiber Market is expected to grow steadily due to rising demand for sustainable textiles.
- Luxury fashion brands will continue integrating alpaca fiber into eco-friendly collections.
- Advancements in fiber processing technology will improve softness, color retention, and durability.
- Increasing consumer awareness about biodegradable and hypoallergenic fabrics will boost adoption.
- Online and specialty retail channels will expand global access to alpaca-based products.
- Latin America will remain the primary production hub, supported by government programs.
- Europe and North America will drive demand through sustainable apparel and home décor markets.
- Collaboration between cooperatives and global textile firms will enhance supply chain efficiency.
- Blending alpaca with other fibers will expand its use in industrial and functional textiles.
- Growing interest in cruelty-free and ethically sourced materials will sustain long-term market growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Alpaca Fiber Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Alpaca Fiber Market projected to grow between 2025 and 2032?
Which Alpaca Fiber Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Alpaca Fiber Market?
Who are the leading companies in the Alpaca Fiber Market?
Which region commanded the largest share of the Alpaca Fiber Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,300.97 million → 2032: USD 4,181.57 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Alpaca Fiber Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Alpaca Fiber Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Alpaca Fiber Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Alpaca Fiber Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Alpaca Fiber Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Alpaca Fiber Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Alpaca Fiber Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Alpaca Fiber Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,300.97 million → 2032: USD 4,181.57 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Alpaca Fiber Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Alpaca Fiber Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Alpaca Fiber Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Alpaca Fiber Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

