
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Aluminum Cable Market Size 2024 | USD 22805 Million |
| Aluminum Cable Market, CAGR | 5% |
| Aluminum Cable Market Size 2032 | USD 33693.37 Million |
Market Overview:
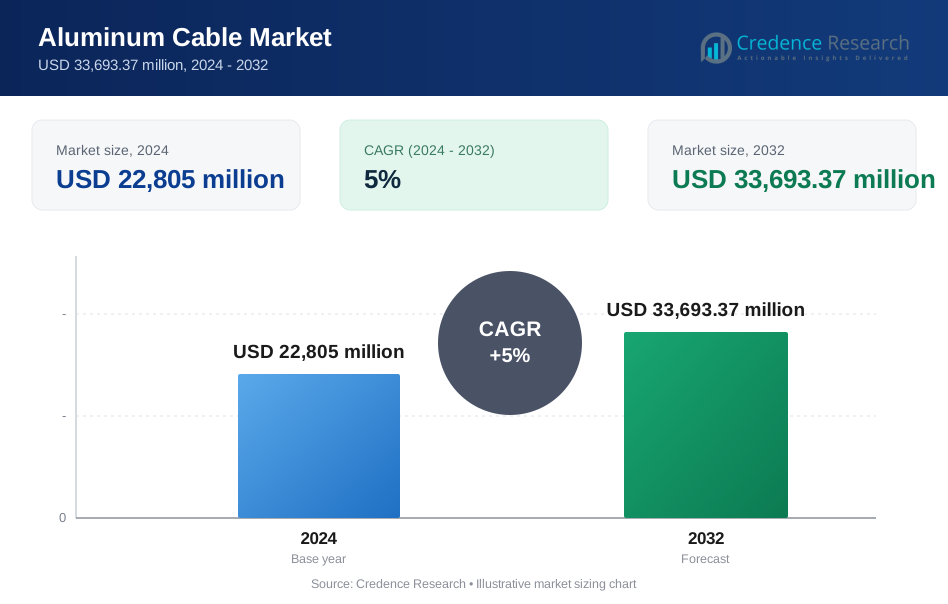
The Aluminum Cable Market is projected to grow from USD 22805 million in 2024 to an estimated USD 33693.37 million by 2032, with a compound annual growth rate (CAGR) of 5% from 2024 to 2032.
Several key factors are driving the growth of the aluminum cable market. First, the increasing need for efficient power distribution networks, particularly in developing economies, has led to a rise in infrastructure projects requiring aluminum cables. Additionally, the automotive industry's shift towards electric vehicles (EVs) and the demand for lighter materials to improve vehicle efficiency are fueling the market. Aluminum's properties, such as resistance to corrosion and thermal performance, make it ideal for power cables, especially in high-voltage applications. Furthermore, the push for renewable energy sources, like solar and wind power, is creating additional demand for aluminum cables used in energy transmission systems, offering sustainable growth opportunities for the market.
Regional analysis shows that Asia-Pacific dominates the aluminum cable market, accounting for the largest share due to rapid industrialization and urbanization in countries like China, India, and Japan. China is the leading consumer, owing to its extensive infrastructure projects and energy needs. North America is also witnessing significant growth, particularly in the renewable energy and automotive sectors, with the U.S. being a key market. Europe, driven by advancements in electric vehicle production and stringent energy-efficiency regulations, is expected to see steady growth as well. Meanwhile, the Middle East and Africa region offers promising potential, supported by expanding energy projects and increasing government investment in infrastructure.
Market Drivers:
Rising Demand for Energy Infrastructure:
One of the primary drivers of the aluminum cable market is the growing need for reliable energy infrastructure across the globe. As developing economies expand, the demand for electricity and efficient power transmission is rising significantly. Aluminum cables, known for their high conductivity and lightweight properties, are widely used in overhead power lines and underground systems. Governments and utility companies are investing heavily in modernizing aging infrastructure and expanding electricity grids to meet the needs of growing populations. This trend is particularly strong in regions such as Asia-Pacific, where industrialization and urbanization are driving the construction of new power plants, substations, and transmission lines. As a result, the need for durable, cost-effective materials like aluminum cables has surged.
Growth in Electric Vehicle (EV) Adoption:
The automotive sector, particularly the electric vehicle (EV) industry, is another key contributor to the growth of the aluminum cable market. As governments and consumers shift towards cleaner, more sustainable transportation options, the demand for EVs has increased significantly. Aluminum cables are crucial in the manufacturing of electric vehicles because they offer a lightweight solution that improves energy efficiency and vehicle range. Automakers are increasingly turning to aluminum to reduce the weight of the wiring and cabling systems in electric cars, leading to lower overall energy consumption. For instance, the International Energy Agency (IEA) highlights that nearly one in five cars sold in 2023 was electric, reflecting a significant shift towards EVs. Additionally, with the expansion of EV charging infrastructure, particularly in developed regions such as North America and Europe, aluminum cables are becoming more prevalent in high-voltage charging stations, further boosting market demand.
Renewable Energy Expansion:
The global push towards renewable energy sources is another major factor propelling the aluminum cable market. Solar, wind, and hydropower projects require efficient transmission networks to carry energy from remote generation sites to urban centers. Aluminum cables are particularly suitable for these applications due to their strength, corrosion resistance, and ability to conduct electricity efficiently over long distances. Many countries are increasing their investments in renewable energy infrastructure to reduce dependence on fossil fuels and meet carbon reduction targets. For instance, the International Renewable Energy Agency (IRENA) reports that global renewable power capacity is expected to grow to 7,300 GW by 2028, with solar and wind accounting for 95% of this expansion. This shift is creating significant opportunities for the aluminum cable market, as large-scale renewable energy projects require extensive wiring and transmission systems that rely heavily on aluminum. As the renewable energy sector grows, so will the demand for aluminum cables.
Cost-Effectiveness and Material Advantages:
Aluminum cables offer a more affordable alternative to copper cables, which has made them increasingly popular in various industries. Aluminum is less expensive and more abundant than copper, providing a cost-effective solution for both manufacturers and end-users. Its lightweight nature also makes aluminum cables easier to install, reducing labor and transportation costs. Furthermore, aluminum has excellent resistance to corrosion, making it a suitable material for outdoor and underground applications where durability is essential. These advantages have made aluminum cables a preferred choice in industries such as construction, energy, and telecommunications. As companies continue to seek cost-effective materials without compromising performance, the aluminum cable market is expected to maintain its growth trajectory.
Market Trends:
Increasing Use of Aluminum in High-Voltage Applications:
The automotive industry, particularly with the rise of electric vehicles (EVs), is increasingly demanding lightweight materials, which has accelerated the use of aluminum cables. Automakers are under pressure to improve fuel efficiency and extend the driving range of EVs. Aluminum cables, being lighter than traditional copper alternatives, offer a solution that reduces the overall weight of vehicles, contributing to better energy efficiency. This trend is especially strong in the EV market, where every kilogram saved can have a significant impact on vehicle performance. For instance, according to the International Energy Agency, electric car sales doubled to 6.6 million units in 2021, with the global electric car fleet totaling approximately 16.5 million vehicles by the end of that year. As electric vehicle production scales up globally, the use of aluminum cables in automotive applications is expected to rise, reinforcing this market trend.
Rising Demand for Lightweight Materials in the Automotive Sector:
The automotive industry, particularly with the rise of electric vehicles (EVs), is increasingly demanding lightweight materials, which has accelerated the use of aluminum cables. Automakers are under pressure to improve fuel efficiency and extend the driving range of EVs. Aluminum cables, being lighter than traditional copper alternatives, offer a solution that reduces the overall weight of vehicles, contributing to better energy efficiency. This trend is especially strong in the EV market, where every kilogram saved can have a significant impact on vehicle performance. As electric vehicle production scales up globally, the use of aluminum cables in automotive applications is expected to rise, reinforcing this market trend.
Expansion of Renewable Energy Projects:
Another key trend shaping the aluminum cable market is the expansion of renewable energy projects. With governments and private companies investing heavily in solar, wind, and hydropower, the demand for efficient and durable cable solutions is growing. Aluminum cables are increasingly being used in renewable energy installations due to their ability to withstand harsh environmental conditions, such as exposure to moisture and extreme temperatures. For example, GBP Co., Ltd., a leading Japanese technology provider, launched new aluminum cables specifically designed for photovoltaic (PV) systems, offering easier installation and significant labor cost savings compared to copper conductors. As the global transition to clean energy accelerates, aluminum cables will play a critical role in supporting these developments.
Technological Advancements in Aluminum Cable Manufacturing:
Technological advancements in aluminum cable manufacturing are also driving market trends. Manufacturers are continuously improving the performance characteristics of aluminum cables by developing advanced aluminum alloys and insulation technologies that enhance durability, flexibility, and conductivity. These innovations are expanding the range of applications where aluminum cables can be used, including in industries that require highly specialized wiring, such as aerospace, telecommunications, and industrial automation. The ongoing development of high-performance aluminum cables is not only making them more competitive with copper but is also opening up new opportunities for aluminum cable applications, fostering further market growth.
Market Restraints and Challenges:
Lower Conductivity Compared to Copper:
One of the key restraints in the aluminum cable market is the lower electrical conductivity of aluminum compared to copper. Although advancements in aluminum alloy technology have improved its performance, aluminum still has about 60% of the conductivity of copper. This means that, for the same amount of electrical current, aluminum cables need to have a larger cross-sectional area, which can increase the material's bulk in certain applications. In some cases, industries that require compact cabling systems may still prefer copper, limiting aluminum’s adoption in these areas despite its cost and weight advantages.
Susceptibility to Creep and Corrosion:
Aluminum cables are more susceptible to "creep" or deformation under sustained load compared to copper, which can lead to loosening of connections over time, especially in high-temperature environments. This property can cause long-term maintenance challenges, particularly in applications requiring high mechanical stability. According to research conducted by Empa, the Swiss Federal Laboratories for Materials Science and Technology, aluminum alloy cables tend to "creep" at low temperatures, with wires growing longer over time and causing sag in power lines. Additionally, although aluminum has good corrosion resistance in certain environments, it is prone to oxidation when exposed to moisture, especially in marine or industrial settings with high humidity. This can lead to deterioration of cable performance, posing a challenge for long-term reliability.
Market Competition from Copper:
The aluminum cable market also faces competition from copper, which remains the standard material in many industries, particularly in regions with established copper infrastructure. Copper cables are more compact and offer higher conductivity, making them preferred in industries where space constraints and performance are crucial. The entrenched position of copper in markets like telecommunications and high-performance electronics presents a challenge for aluminum cables to penetrate these areas, despite aluminum’s lower cost and weight advantages. Convincing industries to switch from copper to aluminum remains an ongoing challenge for manufacturers.
Market Segmentation Analysis:
By grade, the market is categorized into electrical, alloy, and mechanical. Electrical-grade aluminum cables dominate due to their extensive use in power transmission and distribution systems. Alloy-grade aluminum is gaining traction in industries requiring enhanced strength and flexibility, such as aerospace and automotive, while mechanical-grade cables find applications in industrial machinery and equipment.
By product, aluminum cables are segmented into enameled, paper insulated, fiberglass insulated, Mika insulated, cotton insulated, and Nomex insulated cables. Enameled and fiberglass insulated cables are widely used due to their durability and high-temperature resistance, particularly in industrial and electrical applications. Mika and Nomex insulated cables are preferred in high-voltage and fire-resistant applications due to their superior insulation properties. Paper and cotton-insulated cables are less common but are used in specific low-voltage or retrofitting projects.
By application, the market serves various sectors including automobile, circuit breakers, home electrical appliances, switches and meters, transformers, motors, rotating machines, and shipping. The automobile sector is experiencing significant growth due to the increasing production of electric vehicles, where lightweight aluminum cables are preferred. Transformers and motors account for substantial demand due to the need for efficient power transmission systems, while home electrical appliances and circuit breakers also represent significant market segments for aluminum cables, particularly in residential and commercial sectors. Shipping applications utilize aluminum cables for their corrosion resistance in marine environments.
Segmentation:
By Grade
- Electrical
- Alloy
- Mechanical
By Product
- Enameled
- Paper insulated
- Fiberglass insulated
- Mika insulated
- Cotton insulated
- Nomex insulated
By Application
- Automobile
- Circuit breakers
- Home electrical appliances
- Switches and meters
- Transformers
- Motors
- Rotating machines
- Shipping
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Latin America
- Brazil
- Argentina
- Chile
- Middle East & Africa
- South Africa
- UAE
- Saudi Arabia
- Nigeria
Regional Analysis:
Asia-Pacific
Asia-Pacific holds the largest market share in the aluminum cable market, accounting for approximately 40% of the global revenue. This dominance is driven by rapid industrialization, urbanization, and infrastructure development in countries like China, India, and Japan. China, in particular, is the largest consumer of aluminum cables due to its massive investments in power transmission and distribution, renewable energy projects, and transportation infrastructure. Additionally, the region's growing automotive sector, especially the electric vehicle market, is contributing to the increased demand for lightweight materials like aluminum cables. India is also witnessing significant growth, supported by government initiatives focused on expanding the power grid and boosting renewable energy capacities.
North America
North America accounts for around 25% of the market share, with the United States being the leading contributor. The region’s growth is driven by the rising adoption of renewable energy sources such as wind and solar power, both of which require efficient transmission networks. Additionally, the electric vehicle (EV) industry is rapidly expanding in North America, further fueling the demand for aluminum cables due to their lightweight and cost-effective nature. The modernization of aging power infrastructure in the U.S. and Canada, coupled with the increasing need for energy-efficient solutions, is also contributing to the market's expansion in this region.
Europe
Europe holds approximately 20% of the global market share, driven by stringent energy efficiency regulations and the region’s focus on sustainability. Countries like Germany, the U.K., and France are at the forefront of the shift towards renewable energy, with significant investments in wind and solar power. This transition has boosted the demand for aluminum cables in power generation and transmission projects. Moreover, Europe’s growing electric vehicle market, along with the need for lightweight and efficient materials, is further driving the market. The automotive and industrial sectors in the region are increasingly adopting aluminum cables to meet environmental regulations and reduce carbon emissions.
Latin America
Latin America represents around 8% of the aluminum cable market, with Brazil and Mexico leading the region. The region’s growing infrastructure projects, particularly in power generation and distribution, are contributing to the demand for aluminum cables. The expanding manufacturing sector in Mexico, along with renewable energy projects in Brazil, is driving growth in this region. Additionally, the shift towards urbanization and modernization of electricity grids is fueling market expansion.
Middle East & Africa
The Middle East & Africa region holds about 7% of the market share, with significant growth potential due to the region’s increasing investments in infrastructure and energy projects. Saudi Arabia, the UAE, and South Africa are key markets in the region, focusing on expanding their power grids and renewable energy capacities. The aluminum cable market is expected to grow as these countries invest heavily in infrastructure development, particularly in the energy and transportation sectors, to meet the needs of their growing populations.
Key Player Analysis:
- Cerrowire LLC
- Ducab
- Henan Chalco Aluminium
- Kaiser Aluminum
- Nexans
- Norsk Hydro ASA
- Prysmian S.p.A.
- Southern Cable Group Berhad
- Southwire Company, LLC
- Sumitomo Electric Industries, Ltd.
Competitive Analysis:
The aluminum cable market is highly competitive, with numerous global and regional players vying for market share. Key players include companies such as Nexans S.A., Prysmian Group, General Cable Corporation, Southwire Company, and LS Cable & System. These companies focus on expanding their product portfolios, enhancing production capabilities, and adopting advanced technologies to maintain their competitive edge. They are also investing in research and development to improve the performance and durability of aluminum cables, especially for high-voltage and specialized applications. Additionally, mergers, acquisitions, and strategic partnerships are common strategies to expand market presence and cater to growing demand, particularly in emerging markets. The competition is also driven by the need to meet sustainability goals, with companies emphasizing the development of energy-efficient products and solutions tailored to the needs of the renewable energy and electric vehicle sectors. Regional players in Asia-Pacific and Europe are emerging as strong competitors due to local infrastructure projects.
Recent Developments:
- In March 2024, Norsk Hydro ASA partnered with NKT A/S to develop a low-carbon aluminum power cable value chain, integrating Hydro's low-carbon aluminum production with NKT's cable manufacturing expertise to reduce the carbon footprint of energy infrastructure.
- In May 2024, Southwire expanded its Cofer Technology Center in Carrollton, Georgia, to enhance its research and development capabilities, focusing on innovative aluminum wire products and electrical components for industries such as utilities, construction, and infrastructure.
- In April 2024, Ducab launched its new Eco-Aluminum Rods, designed with reduced carbon emissions, marking a significant move towards sustainability in the aluminum industry.
- In January 2024, Alcoa entered into a strategic partnership with Nexans to supply low-carbon aluminum produced using the ELYSIS technology, which eliminates direct carbon dioxide emissions during smelting. Nexans aims to use this aluminum to offer more sustainable wire solutions and support the transition to greener, carbon-neutral infrastructure.
Market Concentration & Characteristics:
The aluminum cable market is moderately fragmented, with several key global players holding significant market shares alongside numerous regional manufacturers. Companies such as Nexans, Prysmian Group, Southwire, and General Cable dominate the industry, with their broad product portfolios and advanced manufacturing capabilities. Despite this, regional players, particularly in Asia-Pacific and Europe, are gaining market presence due to local demand and infrastructure projects. Market characteristics include high demand from industries such as energy, construction, and automotive, driven by trends like electrification, renewable energy expansion, and infrastructure modernization. The market is also marked by increased emphasis on sustainability, with manufacturers focusing on producing low-carbon, energy-efficient aluminum cables. Technological advancements in alloy development and insulation techniques are further shaping the competitive landscape, allowing manufacturers to meet industry-specific needs while enhancing product performance and durability.
Report Coverage:
The research report offers an in-depth analysis based on By Grade, By Product and By Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing demand for lightweight materials in the automotive industry, particularly in electric vehicles, will drive market growth.
- Expanding renewable energy projects, such as solar and wind farms, will boost the need for aluminum cables in power transmission systems.
- Technological advancements in aluminum alloy production will improve conductivity and durability, increasing its use in high-voltage applications.
- Rising infrastructure development in emerging economies will create new opportunities for aluminum cable manufacturers.
- Growing investments in smart grids and energy-efficient infrastructure will support long-term demand for aluminum cables.
- Environmental regulations will drive the adoption of low-carbon and sustainable aluminum cables, aligning with global sustainability goals.
- Increased focus on modernizing aging power grids, especially in North America and Europe, will fuel demand for aluminum cables in energy distribution.
- Continued research and development in insulation technologies will broaden the scope of aluminum cable applications across industries.
- Competitive pricing and availability of aluminum compared to copper will encourage its adoption across sectors like construction and telecommunications.
- Strategic partnerships and mergers among key players will enhance market consolidation and innovation in aluminum cable solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Energy Infrastructure
Rapid industrialization and urbanization, especially in developing economies, are driving large-scale investments in power transmission and distribution networks, increasing the demand for aluminum cables due to their cost-effectiveness and suitability for overhead and underground systems.
Growth in Electric Vehicle Production
The shift towards electric vehicles in the automotive sector is boosting demand for lightweight aluminum cables, which help improve vehicle efficiency and range, making them increasingly preferred over heavier copper alternatives in EV wiring and charging infrastructure.
Renewable Energy Projects
The global transition to renewable energy sources such as solar and wind is creating significant demand for aluminum cables, which are essential for efficient, long-distance energy transmission from generation sites to consumption centers due to their corrosion resistance and favorable conductivity-to-weight ratio.
Cost and Material Advantages over Copper
Aluminum cables offer a more affordable and lighter alternative to copper, reducing installation and transportation costs while maintaining adequate performance, which is particularly attractive for large-scale infrastructure and utility projects.
Technological Advancements in Aluminum Cable Manufacturing
Ongoing innovations in aluminum alloy development and insulation technologies are enhancing the durability, flexibility, and conductivity of aluminum cables, expanding their use in high-voltage, automotive, and specialized industrial applications.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size for the aluminum cable market by 2032?
What factors are driving the growth of the aluminum cable market?
Which region dominates the aluminum cable market?
What are the main challenges in the aluminum cable market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Grade
- 1.2.1 Electrical
- 1.2.2 Alloy
- 1.2.3 Mechanical
- 1.3 By Product
- 1.3.1 Enameled
- 1.3.2 Paper insulated
- 1.3.3 Fiberglass insulated
- 1.3.4 Mika insulated
- 1.3.5 Cotton insulated
- 1.3.6 Nomex insulated
- 1.4 By Application
- 1.4.1 Automobile
- 1.4.2 Circuit breakers
- 1.4.3 Home electrical appliances
- 1.4.4 Switches and meters
- 1.4.5 Transformers
- 1.4.6 Motors
- 1.4.7 Rotating machines
- 1.4.8 Shipping
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 22,805 million → 2032: USD 33,693.37 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Aluminum Cable Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Aluminum Cable Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Aluminum Cable Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Aluminum Cable Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Aluminum Cable Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Aluminum Cable Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Aluminum Cable Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Aluminum Cable Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 22,805 million → 2032: USD 33,693.37 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Aluminum Cable Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Grade - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Electrical
- 12.3.7.2 Alloy
- 12.3.7.3 Mechanical
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Enameled
- 12.4.7.2 Paper insulated
- 12.4.7.3 Fiberglass insulated
- 12.4.7.4 Mika insulated
- 12.4.7.5 Cotton insulated
- 12.4.7.6 Nomex insulated
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Automobile
- 12.5.7.2 Circuit breakers
- 12.5.7.3 Home electrical appliances
- 12.5.7.4 Switches and meters
- 12.5.7.5 Transformers
- 12.5.7.6 Motors
- 12.5.7.7 Rotating machines
- 12.5.7.8 Shipping
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Aluminum Cable End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Aluminum Cable Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Aluminum Cable Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Aluminum Cable Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Nexans
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Prysmian S.p.A.
- 18.4 Southwire Company, LLC
- 18.5 Cerrowire LLC
- 18.6 Ducab
- 18.7 Henan Chalco Aluminium
- 18.8 Kaiser Aluminum
- 18.9 Norsk Hydro ASA
- 18.10 Sumitomo Electric Industries, Ltd.
- 18.11 Southern Cable Group Berhad
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

