
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Amino Acids Market Size 2024 | USD 31,419.79 million |
| Amino Acids Market, CAGR | 7.30% |
| Amino Acids Market Size 2032 | USD 57,457.84 million |
Market Overview
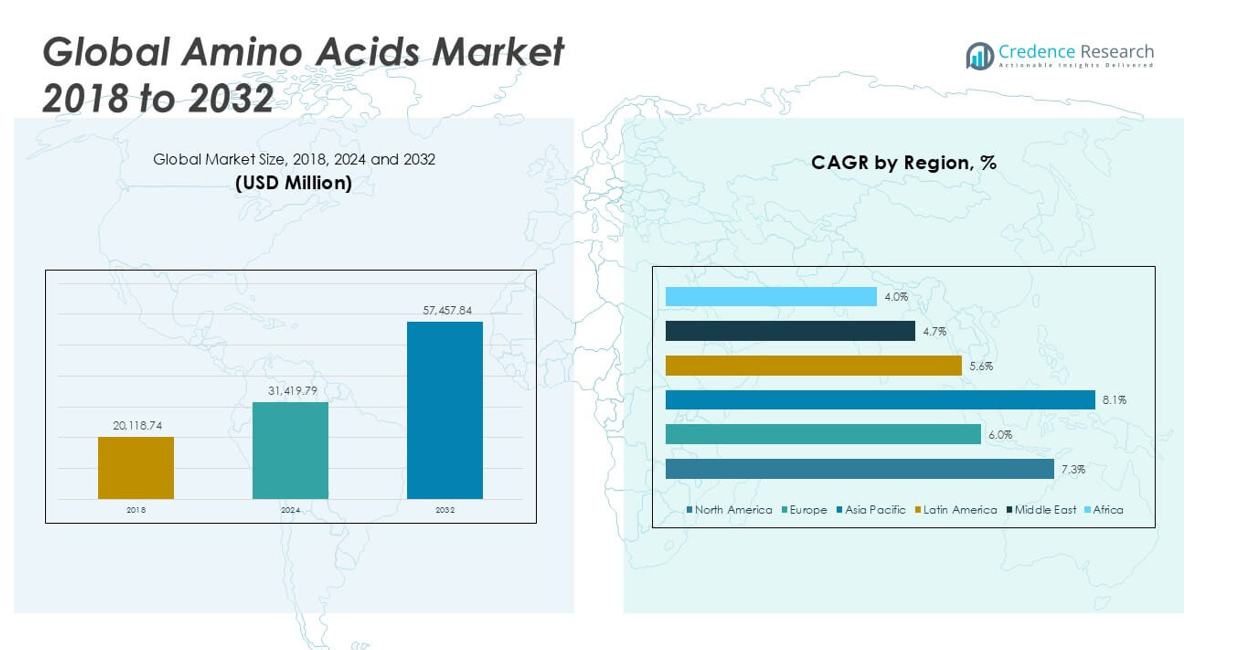
The Amino Acids Market size was valued at USD 20,118.74 million in 2018, reached USD 31,419.79 million in 2024, and is anticipated to reach USD 57,457.84 million by 2032, at a CAGR of 7.30% during the forecast period.
The Amino Acids Market is experiencing robust growth driven by rising demand from the food and beverage, pharmaceutical, and animal feed sectors. Increased awareness of health and wellness has fueled the adoption of amino acid–enriched dietary supplements, while the expansion of the processed food industry boosts market prospects. Growing use of amino acids in clinical nutrition, sports nutrition, and functional foods further accelerates demand. In animal nutrition, the shift toward protein-rich feed additives to enhance livestock health and productivity supports steady market expansion. Technological advancements in fermentation and extraction processes have improved production efficiency and product quality, enabling manufacturers to meet diverse industry requirements. However, fluctuating raw material costs and stringent regulatory standards remain key challenges. Market trends include the rising popularity of plant-based and fermentation-derived amino acids, expansion into emerging markets, and increased investment in R&D for customized and specialty amino acid formulations to address evolving consumer and industry needs.
The geographical analysis of the Amino Acids Market reveals dynamic growth across North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa, with Asia Pacific leading in production and consumption due to rapid industrialization and a growing population. North America and Europe demonstrate strong demand driven by advancements in food technology, pharmaceuticals, and dietary supplements, while Latin America, the Middle East, and Africa show steady progress supported by rising health awareness and expanding agricultural sectors. Major players shaping the competitive landscape include Ajinomoto Co., Inc., Evonik Industries AG, and ADM, each recognized for their extensive product portfolios, global reach, and continuous innovation. Companies like Adisseo and CJ CheilJedang Corp. also hold significant positions in the industry, focusing on research and development to deliver high-quality amino acid products that cater to diverse end-user needs across regions.
Market Insights
- The Amino Acids Market was valued at USD 20,118.74 million in 2018, reached USD 31,419.79 million in 2024, and is projected to achieve USD 57,457.84 million by 2032, with a CAGR of 7.3% during the forecast period.
- Rising demand from the food and beverage, pharmaceutical, and animal feed industries continues to drive market growth globally.
- Health-conscious consumers are increasingly adopting amino acid–fortified products for nutritional, therapeutic, and functional benefits.
- Key trends include the growing popularity of plant-based and fermentation-derived amino acids and the shift toward personalized nutrition and specialty formulations.
- Leading companies such as Ajinomoto Co., Inc., Evonik Industries AG, ADM, Adisseo, and CJ CheilJedang Corp. compete by expanding product portfolios and investing in R&D for innovative applications.
- Market restraints include raw material price volatility, supply chain disruptions, and stringent regulatory requirements that challenge manufacturers’ margins and operational flexibility.
- Asia Pacific dominates the market in terms of production and consumption, while North America and Europe maintain strong demand, and Latin America, the Middle East, and Africa display steady but emerging growth potential.
Market Drivers
Rising Demand from Food and Beverage Industry Boosts Market Expansion
Rising health consciousness and a focus on protein-rich diets continue to shape the food and beverage sector, driving significant demand for the Amino Acids Market. The incorporation of amino acids into functional foods, beverages, and nutritional supplements addresses evolving consumer preferences for wellness and preventive healthcare. Increasing consumption of ready-to-eat and convenience foods, especially in urban areas, contributes to wider adoption of amino acid ingredients. The market benefits from innovations in plant-based products and clean-label formulations that use amino acids for flavor enhancement, preservation, and nutritional fortification. Companies in the sector are responding to shifting dietary trends by developing novel food and beverage offerings enriched with essential amino acids. It strengthens the market’s position as a key supplier to global food manufacturers.
- For instance, Ajinomoto Co., Inc. has leveraged its advanced bioscience technology to supply over 20 types of amino acids to more than 130 countries, and has achieved an annual amino acid production capacity of over 1 million metric tons to support large-scale food manufacturing.
Expanding Pharmaceutical and Clinical Nutrition Applications Accelerate Market Growth
Pharmaceutical companies are actively seeking amino acids for the development of medicines, medical nutrition, and parenteral formulations. The Amino Acids Market benefits from strong research into therapeutic applications, including metabolic disorder treatment, chronic disease management, and immune support. Growth in the geriatric population and increased incidence of lifestyle-related illnesses have led to higher demand for clinical nutrition products, where amino acids play a central role. Amino acids serve as building blocks for protein synthesis, making them essential in critical care, recovery, and pediatric nutrition. The market receives support from government health programs that prioritize advanced medical nutrition and supplementation.
- For instance, Evonik Industries AG developed its pharmaceutical-grade amino acids through proprietary fermentation processes, supplying more than 30 different amino acids and derivatives for parenteral nutrition and active pharmaceutical ingredients, while maintaining GMP-compliant production at facilities capable of delivering over 100,000 metric tons annually.
Surge in Animal Feed Sector Enhances Market Opportunities
The animal feed sector represents a vital segment for the Amino Acids Market, driven by rising meat and dairy consumption and the push for higher livestock productivity. Formulating animal feed with essential amino acids ensures improved animal growth rates, better health outcomes, and enhanced feed conversion efficiency. Regulatory guidelines encourage the use of amino acids to minimize antibiotic reliance and promote sustainable livestock practices. Market participants focus on innovative feed solutions that cater to the needs of poultry, swine, aquaculture, and ruminant industries. It addresses evolving concerns about food safety and environmental sustainability in the agriculture sector.
Technological Advancements and R&D Investments Drive Product Innovation
Continuous improvements in fermentation and extraction technologies enable efficient and cost-effective production of amino acids, positively impacting the Amino Acids Market. Investments in research and development have led to specialized and customized amino acid formulations tailored for diverse end-use industries. Companies deploy advanced bioprocessing techniques to improve yield, purity, and scalability of amino acid products. The trend toward bio-based and fermentation-derived amino acids aligns with environmental and sustainability goals. Collaborations between industry leaders and research institutions foster innovation and support the introduction of next-generation amino acid solutions. It helps the market address stringent quality and regulatory standards while expanding into new application areas.
Market Trends
Growth of Plant-Based and Fermentation-Derived Amino Acids Alters Industry Dynamics
The shift toward plant-based diets and sustainable ingredients is shaping major trends within the Amino Acids Market. Consumers are demanding cleaner labels and more natural sources, leading to higher adoption of plant-based and fermentation-derived amino acids. Companies are innovating to replace synthetic variants with environmentally friendly options. This transformation supports the market’s commitment to sustainability and resonates with a broad spectrum of health-conscious customers. Product launches featuring non-animal-derived amino acids have gained strong traction across food, beverage, and supplement industries. It propels the industry toward more responsible sourcing and production practices.
- For instance, CJ CheilJedang Corp. achieved a milestone by developing L-methionine entirely from fermentation, and operates facilities capable of producing more than 120,000 metric tons annually, helping to significantly reduce the industry’s dependence on petrochemical sources.
Personalized Nutrition and Specialty Formulations Drive Product Diversification
Personalized nutrition is gaining significant momentum, prompting companies to develop amino acid blends tailored to individual dietary needs and health profiles. The Amino Acids Market is witnessing increased demand for specialty formulations that support specific goals such as sports recovery, metabolic health, and cognitive function. Consumer interest in functional foods and beverages containing targeted amino acid combinations is increasing. Nutraceutical brands are collaborating with research institutions to advance precision nutrition, launching products designed for life stage–specific or condition-specific requirements. It expands the market’s reach by offering differentiated value to consumers seeking unique health benefits.
- For instance, DSM has introduced customized amino acid blends for sports nutrition that are clinically tested to support muscle recovery, with its innovation pipeline including over 150 clinical trials on amino acid applications for human health in the past five years.
Integration of Amino Acids into Advanced Pharmaceutical and Medical Applications
The integration of amino acids into innovative pharmaceutical and medical applications is reshaping the growth trajectory of the Amino Acids Market. Amino acids are now essential components in formulations for parenteral nutrition, wound healing, and immune health support. Pharmaceutical companies are investing in research to identify new therapeutic uses for amino acids in treating metabolic disorders and chronic conditions. Hospital and clinical settings increasingly rely on amino acid–enriched solutions for patient care, particularly for aging and immunocompromised populations. It expands opportunities for market participants to address emerging healthcare demands.
Expansion into Emerging Economies and Growth in Animal Nutrition Applications
Rising disposable incomes, urbanization, and evolving dietary patterns in emerging economies are fueling growth prospects for the Amino Acids Market. Animal nutrition remains a major area of application, where amino acids are incorporated into feed to optimize livestock health and production efficiency. Regulatory trends favoring antibiotic alternatives support wider adoption of amino acids in animal feed. Regional expansion and strategic investments help global and local manufacturers establish a stronger presence in Asia Pacific, Latin America, and Africa. It drives new product introductions and supports market penetration in high-potential regions.
Market Challenges Analysis
Volatility in Raw Material Prices and Supply Chain Disruptions Impact Market Stability
Fluctuations in the cost of raw materials such as corn, soy, and other feedstocks pose significant challenges to the Amino Acids Market. Supply chain disruptions, often triggered by global trade uncertainties or extreme weather events, have led to unpredictable input costs and delivery delays. Manufacturers must manage these instabilities while maintaining competitive pricing and consistent product quality. Price volatility can reduce margins and force companies to adjust procurement strategies frequently. The market relies on a steady supply of agricultural commodities, making it sensitive to geopolitical and environmental risks. It complicates long-term planning for industry players seeking sustainable growth.
Stringent Regulatory Frameworks and Quality Standards Hinder Market Expansion
The complex regulatory landscape governing the production, labeling, and marketing of amino acids presents a major challenge for the Amino Acids Market. Companies must comply with diverse international standards that cover food safety, pharmaceutical purity, and environmental impact. Navigating these requirements often leads to increased operational costs and delays in product approvals. Meeting rigorous quality standards demands significant investment in research, testing, and documentation. It places pressure on both established firms and new entrants, particularly in markets with strict enforcement and evolving regulations. These hurdles can slow innovation and limit the speed at which new products reach consumers.
Market Opportunities
Rising Adoption in Functional Foods and Personalized Nutrition Unlocks New Growth Channels
Expanding consumer focus on health and wellness presents significant opportunities for the Amino Acids Market. Functional foods and beverages fortified with amino acids are gaining traction among health-conscious individuals seeking targeted benefits such as improved energy, muscle recovery, and cognitive function. Personalized nutrition trends enable companies to offer amino acid blends tailored for specific dietary needs and life stages. Innovative delivery formats like gummies, ready-to-drink shakes, and bars help attract new consumer segments. The market can capitalize on partnerships with nutraceutical brands and healthcare professionals to expand product portfolios and strengthen brand credibility. It benefits from rising demand in preventive healthcare and lifestyle management.
Emerging Markets and Sustainable Production Methods Drive Long-Term Expansion
Economic growth and shifting dietary patterns in emerging markets present promising avenues for the Amino Acids Market. Rising disposable incomes and urbanization in Asia Pacific, Latin America, and Africa support higher consumption of amino acid–enriched foods, supplements, and animal feeds. Sustainable production methods, including fermentation-based and plant-derived amino acids, align with global trends toward environmentally friendly products. Companies can leverage investments in green technology to address regulatory expectations and attract eco-conscious consumers. Strategic expansion into these high-potential regions and the adoption of circular economy practices help position the market for sustained growth. It allows for broader market penetration and differentiation in competitive landscapes.
Market Segmentation Analysis:
By Type:
Lysine maintains a dominant position due to its critical role in animal nutrition and food fortification. Methionine and glutamic acid are also prominent, driven by their extensive use in livestock feed and food flavor enhancement, respectively. Thymine, alanine, leucine, arginine, and glycine contribute to specialized applications, including pharmaceuticals, sports nutrition, and clinical supplements. The “others” category encompasses less common amino acids with emerging potential in niche sectors.
- For instance, Adisseo’s production of methionine has exceeded 500,000 metric tons per year across its global manufacturing sites, solidifying its leadership in the animal nutrition segment with technology that enables continuous, high-volume production to meet global demand.
By Form:
The market is segmented into solid and liquid variants. Solid amino acids, available in powder, granule, and crystalline forms, hold a larger share due to ease of handling, transportation, and storage. It supports bulk distribution for food processing, animal feed, and pharmaceutical manufacturing. Liquid amino acids provide advantages in terms of rapid absorption and precise dosing, making them suitable for dietary supplements, clinical nutrition, and specialized industrial uses. Companies in this segment are introducing new formulations to address evolving customer preferences and regulatory requirements.
- For instance, AMINO GmbH specializes in high-purity solid and liquid amino acids, offering more than 500 customized amino acid solutions for clinical, pharmaceutical, and biotechnological applications, with production facilities certified for pharmaceutical-grade quality management systems.
By Source:
Plant-based amino acids continue to gain traction, driven by the growing popularity of vegan, vegetarian, and clean-label products. The Amino Acids Market benefits from sustainable sourcing and advances in extraction techniques from soy, wheat, and other crops. Animal-based sources remain relevant for certain medical and specialty applications, where specific amino acid profiles are necessary. Chemical synthesis plays a role in producing pure and specialty amino acids for industrial and research purposes. Fermentation-based production stands out for its scalability, cost efficiency, and environmental benefits, with manufacturers using microbial fermentation to meet rising global demand.
Segments:
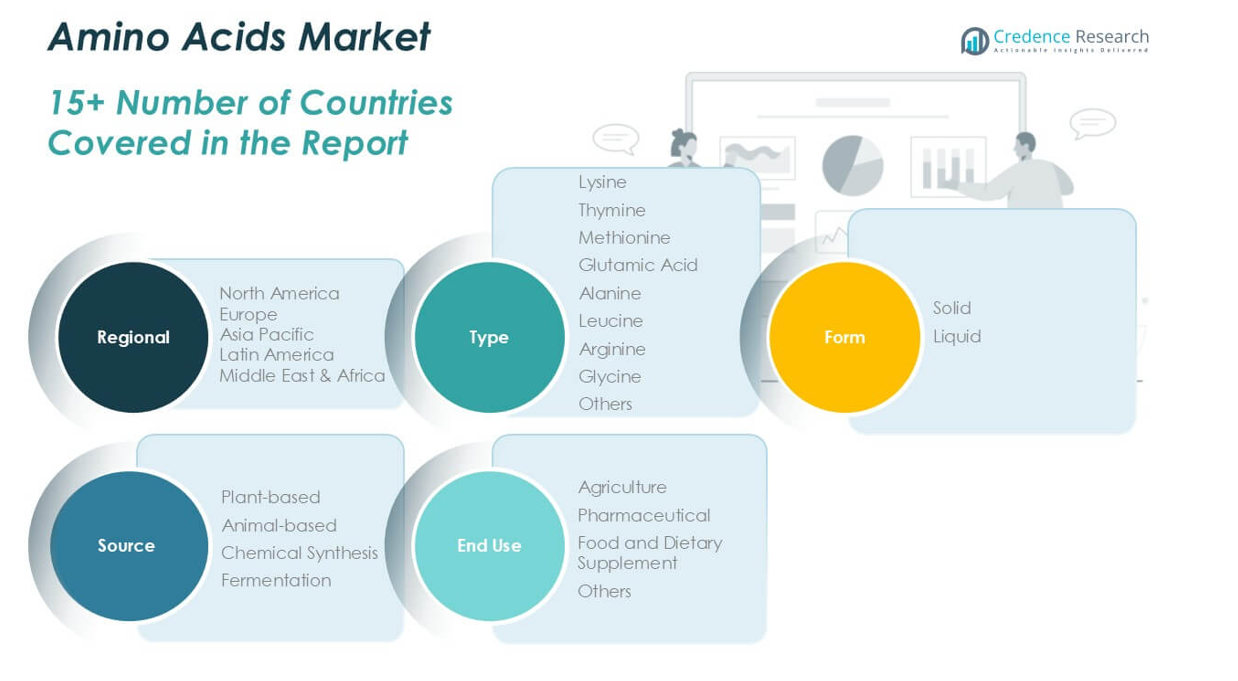
Based on Type:
- Lysine
- Thymine
- Methionine
- Glutamic Acid
- Alanine
- Leucine
- Arginine
- Glycine
- Others
Based on Form:
- Solid
- Liquid
Based on Source:
- Plant-based
- Animal-based
- Chemical Synthesis
- Fermentation
Based on End Use:
- Agriculture
- Pharmaceutical
- Food and Dietary Supplement
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Amino Acids Market
North America Amino Acids Market grew from USD 6,347.62 million in 2018 to USD 9,770.70 million in 2024 and is projected to reach USD 17,936.77 million by 2032, reflecting a compound annual growth rate (CAGR) of 7.3%. North America is holding a 31% market share. The United States, Canada, and Mexico drive this region’s growth with robust demand from food and beverage, pharmaceutical, and animal feed sectors. The adoption of amino acid–enriched products, advanced manufacturing, and strong health awareness underpin regional expansion. Strategic investments in clinical nutrition and dietary supplements further bolster the market’s position.
Europe Amino Acids Market
Europe Amino Acids Market grew from USD 3,603.33 million in 2018 to USD 5,306.04 million in 2024 and is projected to reach USD 8,783.91 million by 2032, at a CAGR of 6.0%. Europe accounts for a 15% market share. Germany, France, the United Kingdom, and Italy are primary contributors, with a focus on high-quality food processing and advanced pharmaceuticals. Regulatory emphasis on food safety and sustainable agriculture shapes the market. It benefits from rising demand for plant-based products and strong R&D investment in specialty amino acids.
Asia Pacific Amino Acids Market
Asia Pacific Amino Acids Market grew from USD 8,454.15 million in 2018 to USD 13,709.95 million in 2024 and is expected to reach USD 26,659.73 million by 2032, demonstrating a CAGR of 8.1%. Asia Pacific captures a dominant 46% market share. China, Japan, India, and South Korea lead regional production and consumption. The market thrives on rapid industrialization, growing populations, and rising disposable incomes. It stands out for large-scale adoption in animal feed and functional foods, supported by robust supply chains and technological advances.
Latin America Amino Acids Market
Latin America Amino Acids Market grew from USD 917.13 million in 2018 to USD 1,413.85 million in 2024 and is estimated to reach USD 2,277.56 million by 2032, with a CAGR of 5.6%. Latin America holds a 4% market share. Brazil, Argentina, and Mexico are key markets, driven by growing meat and dairy sectors and an expanding food industry. The region experiences increasing uptake of amino acid–fortified animal feed and nutraceuticals. It focuses on meeting both domestic demand and export opportunities.
Middle East Amino Acids Market
Middle East Amino Acids Market grew from USD 509.14 million in 2018 to USD 719.53 million in 2024 and is projected to reach USD 1,085.98 million by 2032, at a CAGR of 4.7%. The Middle East has a 2% market share. The United Arab Emirates, Saudi Arabia, and Turkey are principal contributors, emphasizing food security and nutritional self-sufficiency. The market’s expansion is supported by demand for amino acid–based animal feeds and dietary supplements. It faces supply chain constraints but shows steady growth in clinical and food segments.
Africa Amino Acids Market
Africa Amino Acids Market grew from USD 287.36 million in 2018 to USD 499.72 million in 2024 and is set to reach USD 713.88 million by 2032, at a CAGR of 4.0%. Africa accounts for a 1% market share. South Africa, Nigeria, and Egypt play significant roles in driving demand for amino acids in agriculture and food processing. The market sees gradual adoption in animal nutrition and pharmaceuticals. It presents opportunities for growth through strategic investments and localized production to address emerging health and dietary needs.
Key Player Analysis
- Adisseo
- ADM
- Ajinomoto Co., Inc.
- AMINO GmbH
- Bill Barr & Company
- BI Nutraceuticals
- Blue Star Corp.
- CJ CheilJedang Corp.
- DAESANG
- DSM
- Donboo Amino Acid Co., Ltd.
- Evonik Industries AG
Competitive Analysis
The Amino Acids Market features a highly competitive landscape shaped by major players such as Ajinomoto Co., Inc., Evonik Industries AG, ADM, Adisseo, CJ CheilJedang Corp., DSM, and AMINO GmbH. These companies leverage extensive global networks, advanced manufacturing capabilities, and diverse product portfolios to maintain strong market positions. Companies invest heavily in research and development to create specialty amino acids, enhance purity levels, and improve production efficiency. Strategic moves such as capacity expansions, joint ventures, and acquisitions help strengthen their global presence and respond to evolving customer demands. Competitors prioritize sustainability through the adoption of bio-based and fermentation-derived production methods, appealing to environmentally conscious buyers. Emphasis on quality assurance, supply chain optimization, and regulatory compliance allows firms to differentiate themselves in mature and emerging markets alike. Continuous innovation and customer-centric solutions remain central to maintaining a competitive edge in this evolving market landscape.
Recent Developments
- In January 2025, Cizzle Brands launched Spoken Nutrition, a premium NSF Certified for Sport nutraceutical brand targeting athletes. Backed by experts and MLB team orders, the product line included Sleep Builder, Greens, Aminos + ATP, Creatine, Fish Oil + D, MAG 3, Pro Resolving Mediators, Vitamin D3 + K1/K2, Daily Packs, Grass Fed Whey, and Beef Protein.
- In September 2024, Agape ATP Corporation launched its enhanced wellness supplement, ATP2, featuring 76 essential minerals, 20 amino acids, and advanced enzymes. The product aims to address aging, metabolism, and chronic disease, promoting energy, vitality, and overall health.
- In September 2024, Arla Foods Ingredients launched the "Go High in Protein" campaign to inspire dairy manufacturers. The campaign highlighted the Nutrilac® ProteinBoost range, showcasing new high-protein dairy recipes like spoonable and drinking yogurts.
- In Dec 2023, Fenglihui Anjiachun, a novel biostimulant containing sugar alcohol and amino acids from the renowned US brand Brandt, has been introduced to the Chinese market and is now available through distribution by Beijing Xinhefeng Agricultural Materials.
- In July 2023, according toresearch & development by University of California, A novel synergistic approach combines synthetic photochemistry and biocatalysis to generate non-canonical amino acids.
Market Concentration & Characteristics
The Amino Acids Market demonstrates a moderate to high level of concentration, with a few large multinational firms controlling significant shares of global production and distribution. It is characterized by extensive vertical integration, where major players manage operations from raw material sourcing to end-product delivery, ensuring quality control and supply reliability. The market emphasizes innovation in product development, with a strong focus on specialty amino acids, tailored formulations, and sustainable production processes. Rapid advancements in biotechnology and fermentation techniques are shaping industry standards and enabling scalability. The sector is highly regulated, with strict quality and safety standards influencing market entry and expansion. Companies differentiate themselves by offering a wide portfolio of amino acids, responding to specific needs across food, pharmaceutical, and animal feed applications. It maintains a competitive environment driven by ongoing research, strategic partnerships, and responsiveness to evolving consumer preferences and regulatory trends.
Report Coverage
The research report offers an in-depth analysis based on Type, Form, Source, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Market expansion will continue through rising demand in personalized nutrition and tailored amino acid blends.
- Investment in biotechnological innovations will enhance yield, purity, and cost-efficiency.
- Fermentation-based and plant-derived amino acids will gain greater traction with sustainability-focused consumers.
- Manufacturers will increase collaboration with research institutions to develop specialty amino acid formulations.
- Technological integration will support real-time data monitoring and optimize production processes.
- Adoption in clinical nutrition and therapeutic applications will strengthen due to healthcare sector growth.
- Animal feed segment will grow through emphasis on antibiotic alternatives and livestock performance.
- Companies will expand geographic presence in emerging economies to tap untapped demand.
- Regulatory compliance will push firms toward transparent sourcing and higher production standards.
- Digital marketing and e-commerce strategies will help firms engage directly with end consumers.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Functional Foods and Dietary Supplements
The growing consumer focus on health and wellness is driving demand for amino acid–fortified foods, beverages, and supplements, as these products offer targeted benefits such as muscle recovery, energy, and cognitive support.
Growth in Pharmaceutical and Clinical Nutrition Applications
Amino acids are increasingly used in pharmaceutical formulations, clinical nutrition, and parenteral solutions, supported by rising incidences of chronic diseases, aging populations, and the need for advanced medical nutrition.
Rising Demand for Animal Feed Additives
The animal feed sector is a major consumer of amino acids, as livestock producers seek to enhance feed efficiency, animal health, and productivity while reducing reliance on antibiotics and meeting regulatory requirements.
Technological Advancements in Production
Innovations in fermentation and extraction technologies have improved the efficiency, scalability, and sustainability of amino acid production, enabling manufacturers to meet diverse industry needs and respond to environmental concerns.
Shift Toward Plant-Based and Sustainable Ingredients
Consumer preference for plant-based diets and clean-label products is boosting demand for plant-derived and fermentation-based amino acids, encouraging companies to develop environmentally friendly and sustainable solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Amino Acids Market?
What factors are driving the growth of the Amino Acids Market?
What are some challenges faced by the Amino Acids Market?
Who are the major players in the Amino Acids Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Solid
- 1.2.2 Liquid
- 1.3 By Type
- 1.3.1 Lysine
- 1.3.2 Methionine
- 1.3.3 Glutamic Acid
- 1.3.4 Alanine
- 1.3.5 Leucine
- 1.3.6 Arginine
- 1.3.7 Glycine
- 1.3.8 Thymine
- 1.3.9 Others
- 1.4 By Source
- 1.4.1 Plant-based
- 1.4.2 Animal-based
- 1.4.3 Chemical Synthesis
- 1.4.4 Fermentation
- 1.5 By End Use
- 1.5.1 Food and Dietary Supplement
- 1.5.2 Pharmaceutical
- 1.5.3 Agriculture
- 1.5.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 31,419.79 million → 2032: USD 57,457.84 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Amino Acids Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Amino Acids Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Amino Acids Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Amino Acids Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Amino Acids Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Amino Acids Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Amino Acids Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Amino Acids Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 31,419.79 million → 2032: USD 57,457.84 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Amino Acids Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Solid
- 12.3.7.2 Liquid
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Lysine
- 12.4.7.2 Methionine
- 12.4.7.3 Glutamic Acid
- 12.4.7.4 Alanine
- 12.4.7.5 Leucine
- 12.4.7.6 Arginine
- 12.4.7.7 Glycine
- 12.4.7.8 Thymine
- 12.4.7.9 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Source - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Plant-based
- 12.5.7.2 Animal-based
- 12.5.7.3 Chemical Synthesis
- 12.5.7.4 Fermentation
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End Use - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Food and Dietary Supplement
- 12.6.7.2 Pharmaceutical
- 12.6.7.3 Agriculture
- 12.6.7.4 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Amino Acids End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Amino Acids Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Amino Acids Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Amino Acids Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Ajinomoto Co., Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Evonik Industries AG
- 18.4 ADM
- 18.5 Adisseo
- 18.6 CJ CheilJedang Corp.
- 18.7 DSM
- 18.8 AMINO GmbH
- 18.9 DAESANG
- 18.10 Blue Star Corp.
- 18.11 Donboo Amino Acid Co., Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

