
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
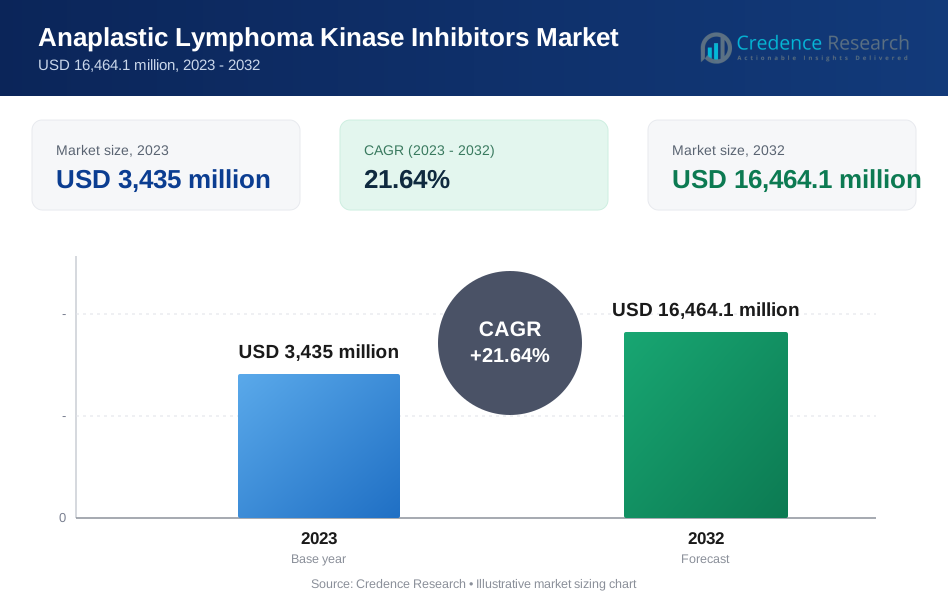
| Anaplastic Lymphoma Kinase (ALK) Inhibitors Market Size 2023 | USD 3,435 Million |
| Anaplastic Lymphoma Kinase (ALK) Inhibitors Market , CAGR | 21.64% |
| Anaplastic Lymphoma Kinase (ALK) Inhibitors Market Size 2032 | USD 16,464.1 Million |
Market Overview
The Anaplastic Lymphoma Kinase (ALK) Inhibitors Market is projected to grow from USD 3,435 million in 2023 to an estimated USD 16,464.1 million by 2032, with a compound annual growth rate (CAGR) of 21.64% from 2024 to 2032. This significant expansion is driven by the rising incidence of ALK-positive cancers, particularly non-small cell lung cancer (NSCLC), which necessitates targeted therapeutic options.
Key market drivers include the growing emphasis on targeted therapies, driven by increasing cancer prevalence and breakthroughs in oncology research. Strong interest from pharmaceutical companies in developing innovative and effective ALK inhibitors fuels robust R&D investments and clinical trials. Additionally, favorable regulatory approvals and increasing availability of drugs across global markets propel the uptake of these therapies. Trends point towards combining ALK inhibitors with immunotherapies to achieve synergistic effects, improving patient outcomes.
Regionally, North America leads the market due to robust healthcare infrastructure, high adoption of innovative therapeutics, and significant investment in cancer research. Europe follows, driven by similar factors, while Asia-Pacific exhibits the fastest growth owing to rising healthcare access, increased cancer prevalence, and regulatory support. Key players dominating the global ALK inhibitors market include Pfizer Inc., Novartis AG, F. Hoffmann-La Roche Ltd., Takeda Pharmaceutical Company Limited, and AstraZeneca PLC, among others, consistently advancing the therapeutic landscape through novel product launches and strategic collaborations.
Market Drivers
Increasing Prevalence of ALK-Positive Cancers
The rising incidence of ALK-positive cancers, particularly non-small cell lung cancer (NSCLC), is a significant driver for the ALK inhibitors market. For instance, ALK rearrangements are identified in a notable percentage of NSCLC patients, which translates to a considerable number of individuals requiring specialized treatment globally. As cancer remains a leading cause of mortality, healthcare systems have prioritized research and development in targeted therapies to alleviate the disease burden. This urgency is reflected in the ongoing clinical trials and innovations aimed at improving diagnostic methods for identifying ALK gene alterations, thereby enhancing the market for ALK-targeted drugs. The unmet clinical needs of patients with advanced-stage or refractory cancers have heightened the demand for innovative ALK inhibitors that offer improved survival outcomes and quality of life. This increasing prevalence not only drives therapeutic advancements but also encourages diagnostic innovations to better identify ALK gene alterations, boosting the market for ALK-targeted drugs.
Advancements in Precision Medicine and Oncology Research
The rise of precision medicine has revolutionized the cancer treatment landscape, propelling significant growth in the ALK inhibitors market. For instance, precision medicine tailors treatments to individual patient profiles based on genetic and lifestyle factors, which has been increasingly adopted due to its potential for delivering effective therapies with fewer side effects. This shift is exemplified by the focus on developing new ALK inhibitors that target specific genetic mutations associated with tumor growth, illustrating a significant commitment from pharmaceutical companies to innovate within this space. ALK inhibitors represent a quintessential example of precision oncology, targeting specific genetic mutations that drive tumor growth. Pharmaceutical companies have increasingly focused on research and development of ALK inhibitors, leading to the introduction of new molecules with enhanced efficacy, fewer adverse effects, and broader therapeutic indications. Furthermore, ongoing clinical trials and the potential for combination therapies are expected to further expand treatment options for patients with ALK-positive malignancies.
Favorable Regulatory Environment and Expedited Drug Approvals
Supportive regulatory policies and expedited drug approval pathways have also played a critical role in driving the ALK inhibitors market. For instance, regulatory agencies have implemented pathways such as breakthrough designations and accelerated approvals to ensure timely access to innovative ALK inhibitors for patients facing urgent medical needs. This favorable environment has provided a strong impetus for biopharmaceutical companies to focus their efforts on developing novel ALK inhibitors, expediting their clinical and commercial availability. The combination of supportive regulations and collaboration between regulators and industry stakeholders creates a dynamic market environment conducive to innovation and growth. Regulatory agencies such as the U.S. Food and Drug Administration (FDA), the European Medicines Agency (EMA), and their counterparts across the globe have recognized the need for faster approvals of drugs that address urgent, unmet medical needs in cancer treatment. This supportive framework encourages biopharmaceutical companies to prioritize the development of novel therapies, contributing to a dynamic market environment that fosters innovation and growth within the ALK inhibitors sector.
Growing Interest in Combination Therapies
The adoption of combination therapies has emerged as a pivotal trend in the ALK inhibitors market, significantly influencing market growth. The limitations of monotherapies, including drug resistance and disease relapse, have led researchers and clinicians to explore synergistic treatment options that combine ALK inhibitors with other therapeutic agents, such as immune checkpoint inhibitors or chemotherapy. This approach aims to enhance the overall efficacy of treatment while potentially overcoming resistance mechanisms and prolonging progression-free survival. Leading pharmaceutical companies and research institutions are actively conducting studies to investigate the safety, efficacy, and optimal combination regimens for ALK-positive cancers. The positive clinical outcomes from such combinations offer new treatment paradigms and generate significant commercial interest, driving investment and partnerships in this rapidly evolving market segment. Combination therapies not only enhance the therapeutic value of ALK inhibitors but also broaden their utility in managing more complex or advanced cases of cancer.
Market Trends
Development of Next-Generation ALK Inhibitors
A prominent trend shaping the ALK inhibitors market is the development and adoption of next-generation ALK inhibitors. While first-generation ALK inhibitors have demonstrated efficacy in managing ALK-positive cancers, challenges such as acquired resistance and central nervous system (CNS) metastasis have prompted the need for more advanced therapeutic options. Next-generation ALK inhibitors, including drugs like alectinib, brigatinib, and lorlatinib, have been designed to overcome these limitations. For instance, clinical studies have shown that patients treated with alectinib as their first ALK TKI experienced a median real-world progression-free survival (rwPFS) of 29.3 months, significantly higher than the 10.4 months observed for those receiving crizotinib. This substantial difference highlights the enhanced efficacy of next-generation inhibitors in managing ALK-positive cancers, particularly in overcoming challenges associated with CNS metastasis and acquired resistance. Furthermore, real-world data indicates that alectinib not only improves progression-free survival but also correlates with better overall survival outcomes, reinforcing its role as a preferred first-line therapy in clinical practice. The shift towards these advanced therapies represents a significant change in treatment protocols, emphasizing their growing importance in the management of ALK-positive non-small cell lung cancer (NSCLC).
Expansion of Clinical Trials and Real-World Evidence Studies
The expansion of clinical trials and real-world evidence studies is another key trend in the ALK inhibitors market. Pharmaceutical companies and research institutions are actively conducting large-scale trials to evaluate the efficacy, safety, and optimal use of existing and emerging ALK inhibitors in diverse patient populations. These studies not only provide robust data to support regulatory approvals but also help identify optimal treatment regimens and strategies to address drug resistance.For instance, a comprehensive analysis of real-world outcomes for patients receiving ALK TKIs revealed that 1-year survival rates reached 73% among those treated with alectinib compared to lower rates for earlier-generation therapies. This data underscores the critical role of large-scale clinical trials and real-world evidence studies in validating the effectiveness and safety of emerging ALK inhibitors across diverse patient populations. Additionally, ongoing research efforts aim to refine treatment regimens based on findings from these studies, which have demonstrated that integrating real-world evidence with traditional clinical trial data can significantly enhance clinical decision-making and optimize patient outcomes. This trend reflects a broader commitment within the pharmaceutical industry to ensure that therapies are not only effective in controlled environments but also translate into meaningful benefits for patients in everyday clinical settings.
Market Restraints and Challenges
High Cost and Limited Accessibility of ALK Inhibitor Therapies
One significant market restraint is the high cost and limited accessibility of ALK inhibitor therapies. Advanced cancer treatments, including ALK inhibitors, often come with substantial costs due to the complexities involved in drug development, clinical trials, and regulatory approvals. For patients and healthcare systems, the financial burden of long-term therapy can be considerable, resulting in affordability and accessibility challenges. In many low- and middle-income regions, limited insurance coverage and inadequate reimbursement mechanisms exacerbate these issues, restricting patient access to life-saving therapies. While some initiatives aim to increase access through patient assistance programs or partnerships, affordability remains a barrier, particularly for newer, next-generation ALK inhibitors. The high cost can also strain healthcare budgets, making it difficult for broader segments of the population to benefit from these advancements.
Emergence of Drug Resistance and Complex Treatment Landscapes
The emergence of drug resistance is another major challenge in the ALK inhibitors market. While many patients initially respond well to ALK-targeted therapies, resistance often develops over time, leading to disease progression. This resistance can be driven by secondary mutations within the ALK gene or through alternative signaling pathways that bypass the inhibitory effects of ALK-targeted drugs. The evolving resistance mechanisms complicate the treatment landscape, requiring ongoing research and the development of new inhibitors or combination strategies to manage resistant cases effectively. Moreover, the complexity of tailoring treatment regimens to individual patients based on their unique genetic and disease profiles further adds to the clinical and operational challenges. Addressing drug resistance demands continuous innovation and collaboration across the healthcare ecosystem, which can be resource-intensive and complex.
Market Segmentation Analysis
By Type
The ALK inhibitors market is segmented into first-generation, second-generation, and third-generation inhibitors. First-generation ALK inhibitors include crizotinib, which was the first ALK-targeted therapy approved for ALK-positive non-small cell lung cancer (NSCLC). Despite demonstrating initial efficacy, these inhibitors are often limited by the development of drug resistance and poor central nervous system (CNS) penetration, which has led to the need for more advanced therapies. Second-generation ALK inhibitors, such as alectinib, ceritinib, and brigatinib, have been designed to address these limitations. They exhibit improved CNS penetration and are effective against many resistance mutations. Second-generation inhibitors have become increasingly used as first-line therapies due to their superior clinical outcomes compared to first-generation drugs. Third-generation ALK inhibitors, including lorlatinib, represent the latest advancements in the market. They are specifically developed to overcome resistance to both first- and second-generation inhibitors and have shown strong efficacy in patients with complex resistance profiles and brain metastases. The growing adoption of next-generation inhibitors highlights the market’s trend toward more effective and durable therapies.
By Application
The market can also be segmented by application into hospital pharmacies, retail pharmacies, and others. Hospital pharmacies dominate the segment due to the nature of cancer treatment protocols, which often require the administration and monitoring of ALK inhibitors within a clinical setting. Hospitals are critical for ensuring accurate diagnosis, precision prescribing, and proper management of any adverse reactions associated with ALK therapies. Retail pharmacies are an important distribution channel, especially for outpatient care and follow-up treatments. Patients often rely on retail pharmacies to obtain maintenance doses of ALK inhibitors following initial hospital-based treatment. This segment is gaining prominence as cancer treatment becomes more widely accessible and patient management moves toward outpatient care. Other segments include specialty clinics and online pharmacies that provide flexible options for accessing ALK inhibitors. Specialty clinics often offer a focused approach to cancer treatment, while online pharmacies provide convenience, particularly for long-term maintenance therapy patients.
Segments
Based on Type
- First Generation ALK Inhibitor
- Second Generation ALK Inhibitor
- Third Generation ALK Inhibitor
Based on Application
- Hospital Pharmacy
- Retail Pharmacy
- Others
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America (38%):
North America holds the largest share in the ALK inhibitors market, accounting for approximately 38% of the total market. This dominance is attributed to robust healthcare infrastructure, a high prevalence of ALK-positive cancers, and strong adoption of innovative oncology therapies. The United States leads the region due to significant investments in cancer research, widespread availability of advanced diagnostic technologies, and favorable regulatory support from agencies like the FDA, which expedites drug approvals and facilitates clinical trials. High awareness levels regarding targeted therapies among healthcare professionals and patients further drive market growth. Canada also contributes notably, benefiting from a well-established healthcare system and increasing access to new cancer treatments.
Europe (30%):
Europe represents the second-largest regional market, with a share of approximately 30%. The region’s growth is driven by rising cancer incidence, strong emphasis on precision medicine, and proactive regulatory policies that promote the adoption of innovative therapies. Key markets within Europe include Germany, the United Kingdom, France, and Italy. Government initiatives to improve cancer diagnosis and treatment, coupled with strong collaboration between academia and industry for R&D activities, bolster market development. Additionally, patient advocacy groups and healthcare organizations play a crucial role in raising awareness about genetic testing and targeted therapies, further fueling demand for ALK inhibitors.
Key players
- Betta Pharmaceuticals Co. Ltd.
- Bio-Techne Corp.
- Chia Tai Tianqing Pharmaceutical Group Co. Ltd.
- Hoffmann-La Roche Ltd.
- Helsinn Healthcare SA
- Merck KGaA
- Novartis AG
- Pfizer Inc.
- Takeda Pharmaceutical Co. Ltd.
- Turning Point Therapeutics Inc.
Competitive Analysis
The ALK inhibitors market is highly competitive, with several major pharmaceutical companies and emerging players contributing to its growth. Pfizer Inc. and Novartis AG are market leaders, leveraging extensive R&D capabilities and broad product portfolios to develop and commercialize advanced ALK-targeted therapies. F. Hoffmann-La Roche Ltd. and Takeda Pharmaceutical Co. Ltd. also play prominent roles, offering next-generation inhibitors that address resistance and improve CNS penetration. Companies such as Betta Pharmaceuticals and Turning Point Therapeutics focus on innovative drug development to capture niche market segments. The competitive landscape is further shaped by strategic partnerships, acquisitions, and a strong emphasis on clinical trials, ensuring continuous innovation. Growing interest in combination therapies and overcoming drug resistance fuels intense competition, while smaller and regional players aim to capture market share through cost-effective solutions and novel research approaches.
Recent Developments
- In September 2024, Betta Pharmaceuticals announced the initiation of a Phase III clinical trial for a novel ALK inhibitor aimed at treating advanced ALK-positive non-small cell lung cancer (NSCLC).
- In October 2024, Bio-Techne launched a new diagnostic tool designed to enhance the detection of ALK rearrangements in NSCLC, facilitating the identification of patients eligible for ALK inhibitor therapies.
- In August 2024, Chia Tai Tianqing received regulatory approval for its ALK inhibitor, which is expected to be available in the market by early 2025.
- In November 2024, Roche announced positive results from a Phase II study of its next-generation ALK inhibitor, showing improved efficacy in patients with CNS metastases.
- In July 2024, Helsinn announced a strategic partnership with a biotech firm to co-develop an ALK inhibitor aimed at enhancing patient outcomes in advanced lung cancer.
- In September 2024, Merck KGaA launched a new formulation of its existing ALK inhibitor that allows for improved patient adherence due to reduced dosing frequency.
- In October 2024, Novartis reported the successful completion of a Phase III trial for its ALK inhibitor, which is now under review for regulatory approval in multiple regions.
- In August 2024, Pfizer announced the acquisition of a promising ALK inhibitor candidate from a smaller biotech firm as part of its strategy to expand its oncology portfolio.
- In November 2024, Takeda launched a new combination therapy involving its ALK inhibitor and an immune checkpoint inhibitor, aiming to enhance treatment efficacy in advanced NSCLC.
- In September 2024, Turning Point Therapeutics received FDA approval for its next-generation ALK inhibitor, which targets specific mutations resistant to earlier therapies.
Market Concentration and Characteristics
The Anaplastic Lymphoma Kinase (ALK) Inhibitors Market exhibits a moderately high market concentration, with a mix of major multinational pharmaceutical companies and emerging biotechs shaping its competitive landscape. Key players such as Pfizer Inc., Novartis AG, and F. Hoffmann-La Roche Ltd. dominate the market through extensive R&D capabilities, broad product portfolios, and strong global distribution networks. The market is characterized by intense competition driven by ongoing innovation, the introduction of next-generation therapies, and strategic collaborations. Additionally, regulatory support for accelerated approvals and precision medicine advancements further underscore the market’s dynamic nature. Smaller players often focus on niche areas, providing innovative approaches to overcome drug resistance and target new mutations, thereby creating opportunities within this evolving sector.
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will witness continued growth in next-generation ALK inhibitors designed to overcome resistance and improve patient outcomes, driving sustained demand.
- Future treatment protocols will likely incorporate ALK inhibitors with immunotherapies or targeted agents, offering enhanced efficacy and minimizing resistance.
- Further integration of precision medicine approaches, such as genetic profiling and personalized treatment plans, will boost the adoption of ALK inhibitors.
- The growth of clinical trials and real-world evidence (RWE) studies will provide more comprehensive insights into treatment effectiveness, safety, and optimal usage.
- Increased availability and regulatory approvals in emerging markets, particularly in Asia-Pacific and Latin America, will expand patient access and drive growth.
- New therapeutic strategies targeting complex resistance mutations will emerge, addressing one of the market’s most critical challenges.
- Use of digital health technologies and telemedicine to monitor patient responses and tailor therapies will improve treatment outcomes and patient management.
- Companies will focus on partnerships and strategic collaborations to accelerate drug discovery, strengthen distribution, and enhance their competitive position.
- Continued regulatory backing for faster drug approvals and expanded indications will encourage innovation and speed the availability of novel ALK inhibitors.
- Increased efforts to make ALK inhibitors more affordable and accessible through price adjustments, insurance coverage, and patient support programs will broaden market reach.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the size and growth projection of the ALK inhibitors market?
What factors are driving the growth of the ALK inhibitors market?
Which regions lead the ALK inhibitors market?
What role do pharmaceutical companies play in this market?
Are there any trends in the treatment approaches using ALK inhibitors?
How does regulatory support influence the ALK inhibitors market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Anaplastic Lymphoma Kinase Inhibitors Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Anaplastic Lymphoma Kinase Inhibitors Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 3,435 million → 2032: USD 16,464.1 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Anaplastic Lymphoma Kinase Inhibitors Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Anaplastic Lymphoma Kinase Inhibitors Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Anaplastic Lymphoma Kinase Inhibitors Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Anaplastic Lymphoma Kinase Inhibitors Market Drivers
- 3.3 Anaplastic Lymphoma Kinase Inhibitors Market Restraints & Challenges
- 3.4 Anaplastic Lymphoma Kinase Inhibitors Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Anaplastic Lymphoma Kinase Inhibitors Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Anaplastic Lymphoma Kinase Inhibitors Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Anaplastic Lymphoma Kinase Inhibitors category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Anaplastic Lymphoma Kinase Inhibitors Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Anaplastic Lymphoma Kinase Inhibitors Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Anaplastic Lymphoma Kinase Inhibitors market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Anaplastic Lymphoma Kinase Inhibitors Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Anaplastic Lymphoma Kinase Inhibitors Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Anaplastic Lymphoma Kinase Inhibitors Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Anaplastic Lymphoma Kinase Inhibitors (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Anaplastic Lymphoma Kinase Inhibitors Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Anaplastic Lymphoma Kinase Inhibitors Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Anaplastic Lymphoma Kinase Inhibitors Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Anaplastic Lymphoma Kinase Inhibitors Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Anaplastic Lymphoma Kinase Inhibitors Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Anaplastic Lymphoma Kinase Inhibitors Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Anaplastic Lymphoma Kinase Inhibitors Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Anaplastic Lymphoma Kinase Inhibitors Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Anaplastic Lymphoma Kinase Inhibitors Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
