
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Anti-Caking Agents Market Size 2024 | USD 999.4 million |
| Anti-Caking Agents Market, CAGR | 4.30% |
| Anti-Caking Agents Market Size 2032 | USD 1,295.7 million |
Market Overview:
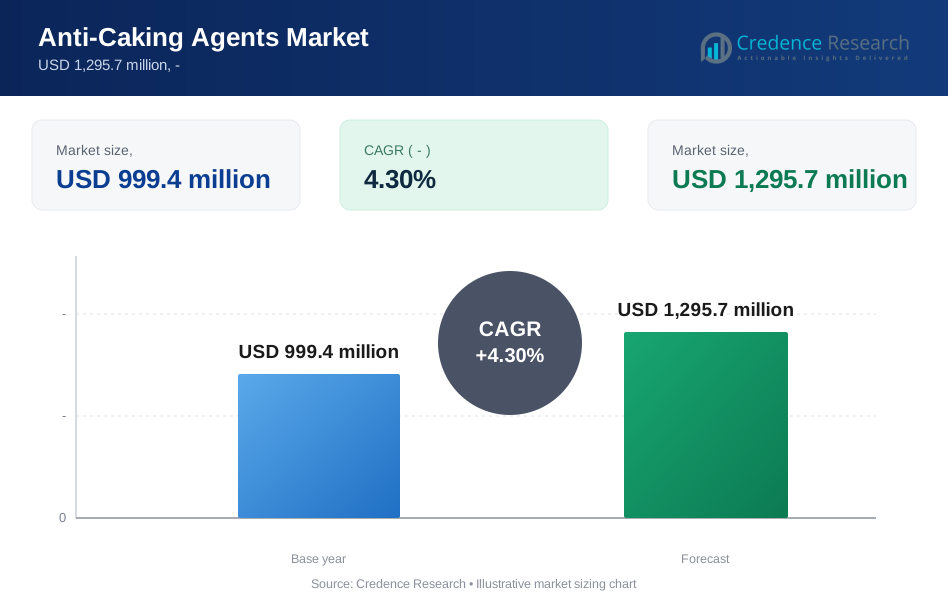
The Anti-Caking Agents Market is experiencing notable growth, fuelled by the increasing demand for enhanced product quality and efficiency in various industries such as food and pharmaceuticals. As of 2024, the global Anti-Caking Agents Market is valued at USD 999.4 million and is projected to grow at a compound annual growth rate (CAGR) of 4.30% over the forecast period, reaching approximately USD 1,295.7 million by 2032. This growth trajectory reflects the rising need for anti-caking agents to maintain the quality and consistency of powdered and granular products, ensuring they remain free-flowing and easy to handle.
Several factors are driving this market expansion. The growing demand for convenience foods and processed products, which often require anti-caking agents to prevent clumping and ensure smooth processing, is a significant driver. Additionally, advancements in anti-caking agent technology and the development of novel products are enhancing their effectiveness and applications across different sectors. The increasing emphasis on product quality and regulatory standards in industries such as food, pharmaceuticals, and agriculture is further propelling the demand for anti-caking agents.
Regionally, North America holds a substantial share of the Anti-Caking Agents Market, driven by a well-established food and beverage industry, stringent quality standards, and high consumer awareness. Europe follows closely, with robust growth fuelled by similar factors and a strong focus on innovation in food processing. The Asia-Pacific region is anticipated to witness significant growth during the forecast period due to rapid industrialization, increasing urbanization, and rising disposable incomes, leading to higher demand for processed foods and advanced anti-caking solutions. Emerging economies in this region, such as China and India, are expected to offer considerable growth opportunities due to their expanding food and beverage sectors and increasing adoption of anti-caking agents in various applications.
Market Drivers:
Increasing Demand for Processed Foods and Convenience Products:
The demand for processed foods and convenience products is a primary driver for the growth of the Anti-Caking Agents Market. As global lifestyles become increasingly fast-paced, there is a marked shift toward ready-to-eat and easy-to-prepare food items. Processed foods, such as powdered soups, sauces, and instant noodles, often require anti-caking agents to ensure that they remain free-flowing and do not form clumps during storage and handling. For Instance, Organization (FAO) and the World Health Organization (WHO) have highlighted the growing trend toward processed foods due to their convenience and longer shelf life. This increasing consumer preference necessitates the use of anti-caking agents to maintain product quality and functionality, driving market growth.
Advancements in Anti-Caking Agent Technology:
Technological advancements in anti-caking agents are significantly contributing to market growth. Recent innovations have led to the development of more effective and specialized anti-caking agents that cater to diverse applications across different industries. For example, the use of new formulations and delivery systems enhances the efficiency of anti-caking agents, making them more effective in preventing clumping and ensuring consistent product quality. ForInstance,according to the International Food Policy Research Institute (IFPRI), the continuous evolution of technology in food processing and the development of advanced anti-caking solutions are crucial in meeting the stringent quality and regulatory standards set by industry authorities. This technological progress supports the market by providing enhanced solutions that meet the needs of modern food production and processing.
Regulatory Standards and Quality Assurance:
Stringent regulatory standards and quality assurance requirements are driving the demand for anti-caking agents. Regulatory bodies, such as the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA), enforce strict guidelines to ensure the safety and quality of food products. These regulations often mandate the use of anti-caking agents to maintain product consistency and prevent clumping, which can affect both product quality and consumer safety. For Instance,The World Health Organization (WHO) also emphasizes the importance of adhering to these standards to ensure the safety of food products. Compliance with regulatory standards not only ensures consumer safety but also enhances the market demand for high-quality anti-caking agents that meet these rigorous requirements.
Rising Urbanization and Economic Growth in Emerging Economies:
Rapid urbanization and economic growth in emerging economies are fuelling the expansion of the Anti-Caking Agents Market. According to the World Bank, urbanization is increasing demand for processed and packaged foods in developing regions, where rising disposable incomes and changing consumer lifestyles are driving greater consumption of convenience products. Countries like China and India are experiencing significant economic growth and urban expansion, leading to higher demand for food products that require anti-caking agents to ensure quality and functionality.For instance,The International Monetary Fund (IMF) also reports that the growing middle class in these regions is contributing to increased consumption of processed foods, further driving the demand for anti-caking agents. The economic development and urbanization trends in these emerging markets present substantial growth opportunities for the anti-caking agents’ industry, as they align with the increasing need for advanced and effective solutions in food processing.
Market Trends:
Rise in Demand for Sustainable Solutions:
A key trend shaping the Anti-Caking Agents Market is the growing demand for sustainable and eco-friendly solutions. As environmental awareness increases among consumers and businesses, there is a significant shift towards using natural and biodegradable anti-caking agents. This trend is influenced by global sustainability initiatives and regulatory pressures to reduce the environmental impact of industrial processes. For instance, according to a report by the United Nations Environment Programme (UNEP), the push for sustainability is driving industries to adopt greener alternatives that align with environmental regulations and corporate social responsibility goals. Companies are responding by developing anti-caking agents derived from renewable resources or designed to minimize ecological footprints. The emphasis on sustainability is not only a response to consumer demand but also a strategic move to comply with evolving regulatory standards set by organizations like the European Food Safety Authority (EFSA) and the U.S. Environmental Protection Agency (EPA), which are increasingly prioritizing environmental considerations in product approvals and industry practices.
Technological Advancements and Innovations:
Technological advancements are rapidly transforming the Anti-Caking Agents Market, with a strong focus on improving the efficacy and functionality of these additives. Innovations such as nano-technology and microencapsulation are enhancing the performance of anti-caking agents by providing better control over their release and interaction with other ingredients. The World Bank's research highlights the role of technology in driving efficiency and effectiveness in various industrial applications. These advancements enable more precise formulation and longer-lasting effects, addressing the growing need for high-performance solutions in diverse applications, from food processing to pharmaceuticals. Additionally, research and development investments by major players and academic institutions are pushing the boundaries of anti-caking technology, leading to the introduction of novel products that cater to specific market needs. The integration of advanced technologies also aligns with the broader trend of digital transformation and automation in the manufacturing sector, further driving innovation and competitiveness in the anti-caking agents’ market.
Market Challenge Analysis:
Regulatory Compliance and Safety Standards:
One of the primary challenges facing the Anti-Caking Agents Market is navigating the complex regulatory landscape and ensuring compliance with stringent safety standards. Regulatory authorities such as the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) impose rigorous requirements on the use of food additives, including anti-caking agents. Companies must navigate these regulations, which can vary significantly across different regions, to ensure that their products meet safety and quality standards. This process often involves extensive testing and documentation, which can be costly and time-consuming for manufacturers. The need for continual compliance and adaptation to new regulations adds a layer of complexity to market operations and can pose a significant barrier to entry for smaller companies.
Raw Material Price Volatility:
Another challenge in the Anti-Caking Agents Market is the volatility in raw material prices. The cost of raw materials used in the production of anti-caking agents, such as minerals and organic compounds, can fluctuate due to various factors, including supply chain disruptions, geopolitical tensions, and environmental regulations. These price fluctuations can impact the overall cost of production and affect the profitability of anti-caking agents. For instance, increased costs of raw materials can lead to higher prices for end products, potentially reducing competitiveness in the market. Additionally, volatility in raw material prices can complicate financial planning and forecasting for manufacturers, making it difficult to maintain stable pricing and supply strategies. Addressing these challenges requires effective supply chain management and strategic sourcing practices to mitigate the impact of raw material price instability on market operations.
Market Segmentation Analysis:
By Type:
The Anti-Caking Agents Market is segmented based on the type of agents used to prevent clumping in powders and granular products. Key types include silica-based agents, calcium-based agents, and sodium-based agents. Silica-based anti-caking agents, such as silica gel and precipitated silica, are widely utilized due to their effectiveness and cost-efficiency in maintaining product flowability. Calcium-based agents, including calcium carbonate and calcium silicate, are also popular for their neutral properties and suitability for various applications. Sodium-based agents, such as sodium aluminosilicate, are employed in specific applications due to their unique functional properties. Each type serves different needs depending on the product and industry requirements, influencing their market share and application areas.
By Technology:
In terms of technology, the Anti-Caking Agents Market is categorized into conventional and advanced delivery systems. Conventional technologies involve traditional formulations and mixing processes that are well-established but may offer limited performance in specific applications. In contrast, advanced technologies include innovations such as nano-technology and microencapsulation. Nano-technology enhances the efficiency and effectiveness of anti-caking agents by allowing for precise control over particle size and distribution. Microencapsulation technology improves the stability and release control of anti-caking agents, providing better performance in challenging environments. The adoption of advanced technologies is growing as industries seek improved solutions for maintaining product quality and consistency.
By End-User:
The market is further segmented by end-user industries, which include food and beverages, pharmaceuticals, agriculture, and others. The food and beverage industry is the largest consumer of anti-caking agents, utilizing them in products such as powdered foods, seasonings, and baking ingredients to ensure free-flowing properties and product stability. In the pharmaceutical sector, anti-caking agents are used in the formulation of powders and granules to ensure uniformity and prevent clumping during processing. The agricultural sector employs anti-caking agents in fertilizers and pesticides to improve application efficiency and storage stability. Each end-user segment drives specific demand patterns based on the functional requirements and regulations applicable to their respective industries.
Segmentation:
Based on Type:
- Silica-Based Agents • Calcium-Based Agents • Sodium-Based Agents • Other Types
Based on Technology:
- Conventional Formulations • Nano-Technology • Microencapsulation • Advanced Delivery Systems
Based on End-User:
- Food and Beverages • Pharmaceuticals • Agriculture • Others
Based on Region:
- North America: United States, Canada, Mexico • Europe: Germany, France, United Kingdom, Italy, Spain • Asia-Pacific: China, India, Japan, South Korea, Australia • Latin America: Brazil, Argentina, Chile • Middle East & Africa: South Africa, Saudi Arabia, United Arab Emirates, Egypt
Regional Analysis:
North America:
North America holds a significant share in the Anti-Caking Agents Market, accounting for approximately 35% of the global market. This dominance is primarily driven by the robust food and beverage industry in the United States and Canada, where anti-caking agents are crucial for maintaining the quality and consistency of a wide range of products. The region's strong regulatory framework, enforced by authorities such as the U.S. Food and Drug Administration (FDA), ensures high standards for food additives, including anti-caking agents. This regulatory environment supports the market by promoting the use of effective and safe anti-caking solutions. The United States, as the largest market within North America, exhibits a high demand for various types of anti-caking agents, driven by the extensive use in processed foods, seasonings, and baking ingredients. Canada also contributes significantly to the market, with increasing adoption of anti-caking agents in both domestic food processing and import-export activities. Additionally, the presence of major industry players and ongoing investments in food technology advancements further bolster the market growth in this region.
Europe:
Europe represents a substantial portion of the Anti-Caking Agents Market, holding a market share of around 30%. The European market is characterized by a diverse and sophisticated food industry, with countries such as Germany, France, and the United Kingdom leading in the adoption of advanced anti-caking solutions. The region's emphasis on product quality and stringent food safety regulations, overseen by bodies like the European Food Safety Authority (EFSA), drives the demand for high-quality anti-caking agents. Germany and France are major contributors to the European market, driven by their extensive food processing sectors and focus on innovative food solutions. The United Kingdom's market is also significant, with a growing preference for clean-label products and natural anti-caking agents. Additionally, the presence of a well-established regulatory framework in Europe ensures that only approved and safe anti-caking agents are used, aligning with consumer demands and industry standards.
Asia-Pacific:
The Asia-Pacific region is experiencing rapid growth in the Anti-Caking Agents Market, with a market share of approximately 25%. This growth is fuelled by increasing urbanization, economic development, and rising disposable incomes in countries such as China, India, and Japan. The expanding food and beverage industry in these countries drives the demand for anti-caking agents, particularly in processed foods, snacks, and convenience products. China and India are major contributors to the market's growth in Asia-Pacific. China's booming food processing sector and growing middle class increase the demand for effective anti-caking solutions. In India, the rising consumption of packaged foods and advancements in food technology further boost market growth. Japan, with its focus on high-quality food products and technological innovation, also contributes significantly to the region's market. The region's dynamic growth is supported by increasing investments in food processing technologies and the development of advanced anti-caking solutions to meet the evolving needs of the market.
Key Player Analysis:
- Evonik Industries AG
- Brenntag AG
- PPG Industries
- Univar Inc.
- Asiros Nordic
- Agropur Ingredients
- Solvay
- Vitaquest International
- Omya International AG
- Huber Engineered Materials
- Sweetener Supply Corp.
- International Media and Cultures, Inc.
- JELU-WERK J. Ehrler GmbH & Co. KG
Competitive Analysis:
The Anti-Caking Agents Market is highly competitive, characterized by the presence of several key players that dominate the global landscape. Major companies such as BASF SE, Evonik Industries, and Solvay are leading the market with their extensive portfolios of anti-caking solutions and strong R&D capabilities. BASF SE, for instance, offers a range of silica-based anti-caking agents that cater to various applications, including food and pharmaceuticals. Evonik Industries is known for its innovative microencapsulation technologies, which enhance the performance and stability of anti-caking agents. Solvay provides a diverse selection of calcium-based agents, which are essential for maintaining the quality of processed foods and industrial products. Additionally, emerging players and regional companies are increasingly entering the market, leveraging advancements in technology to introduce novel anti-caking solutions. For example, companies in Asia-Pacific are expanding their presence with cost-effective and region-specific products tailored to local industry needs. The competitive landscape is further shaped by factors such as technological innovation, regulatory compliance, and strategic partnerships. Companies are focusing on developing advanced delivery systems and natural anti-caking agents to meet evolving consumer preferences and stringent regulatory requirements. Furthermore, collaborations and mergers are common strategies employed by market leaders to enhance their product offerings and expand their global footprint. Overall, the market’s competitive dynamics are driven by a blend of established industry players and innovative new entrants, all striving to capture a share of the growing demand for effective anti-caking solutions.
Recent Developments:
Asiros Nordic Launches Prebiotic Berry Ingredients in the United States (July 24, 2024): Asiros Nordic A/S launched prebiotic juice powders, bespoke extracts, and nourishing liquid shots. Their offerings are a testament to the company’s meticulous journey from cultivation to production, ensuring unparalleled quality, transparency, and traceable practices. Moreover, their revolutionary prebiotic juice powders distinguish themselves by omitting maltodextrin, a common anti-caking agent, further cementing Asiros Nordic’s dedication to natural wellness and clean nutrition.
Vitaquest International Acquires Ashland Powder Processing Facility (October 2, 2023): Vitaquest International, a distinguished player in the nutraceuticals and functional foods sector, has strategically expanded its capabilities by acquiring a powder processing facility in Paterson, New Jersey, from Pharmachem Laboratories, a division of Ashland Inc. This acquisition marks a landmark event, enhancing Vitaquest’s repertoire of services that now encompasses application-specific product development and pilot and commercial manufacturing solutions leveraging advanced fluid bed technology.
Omya Set to Unveil Nutraceutical Solutions at CPhI in Barcelona (September 6, 2023): Omya International AG introduces its innovative Omyanutra range, enhancing the formulation of stable and swiftly disintegrating oral tablets (ODTs) and powders. Leveraging high-purity, naturally sourced minerals refined with proprietary technology, Omya has engineered excipients boasting a unique porous and layered structure that augments tablet compatibility while notably expediting disintegration.
Strategy Analysis & Recommendation: The strategic analysis is essential for organizations seeking a solid foothold in the global marketplace. Companies are better positioned to make informed decisions that align with their long-term aspirations by thoroughly evaluating their current standing in the Food Anti-caking Agent Market. This critical assessment involves a thorough analysis of the organization’s resources, capabilities, and overall performance to identify its core strengths and areas for improvement.
Market Concentration & Characteristics:
The Anti-Caking Agents Market exhibits a moderate to high level of concentration, with a few key players commanding a significant share while numerous smaller and regional firms contribute to the overall market dynamics. Leading global companies such as BASF SE, Evonik Industries, and Solvay dominate the market due to their extensive product portfolios, advanced technological capabilities, and strong R&D investments. These industry giants benefit from economies of scale, allowing them to offer a wide range of anti-caking solutions and innovate continuously. Despite this concentration, the market also features a growing number of specialized and emerging players, particularly in regions like Asia-Pacific, which introduce region-specific products and technologies to cater to local demands. The market is characterized by a diverse range of anti-caking agents, including silica-based, calcium-based, and sodium-based types, each suited for different applications across food, pharmaceuticals, and agriculture. Technological advancements such as nano-technology and microencapsulation are prominent characteristics, driving innovation and enhancing the effectiveness of anti-caking agents. Additionally, the market is influenced by stringent regulatory standards enforced by authorities like the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA), which shape product development and market entry strategies. The interplay between established players' market power and the innovative efforts of emerging firms creates a dynamic competitive environment, fostering continuous improvements and adaptation to changing consumer preferences and regulatory requirements.
Report Coverage:
This comprehensive report on the Anti-Caking Agents Market provides an in-depth analysis of the market's current landscape, including detailed insights into market dynamics, segmentation, and regional performance. The coverage encompasses a thorough examination of market drivers, trends, and challenges, offering a clear understanding of the factors influencing market growth. It segments the market by type (silica-based, calcium-based, sodium-based, and other types), technology (conventional formulations, nano-technology, microencapsulation, and advanced delivery systems), and end-user industries (food and beverages, pharmaceuticals, agriculture, and others). The report also provides a regional breakdown, highlighting key market trends and opportunities in North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. By analyzing market share and competitive dynamics, including the roles of major players like BASF SE, Evonik Industries, and Solvay, the report offers valuable insights into market concentration and characteristics. Additionally, it assesses technological advancements, regulatory impacts, and the strategic movements of leading companies and emerging players. This comprehensive coverage is designed to assist stakeholders in understanding the market landscape, identifying growth opportunities, and making informed decisions based on current and projected market conditions.
Future Outlook:
- The Anti-Caking Agents Market is expected to grow steadily, driven by increasing demand in the food and beverage sector.
- Technological advancements, such as nano-technology and microencapsulation, will enhance the performance of anti-caking agents.
- The shift towards natural and organic anti-caking agents will gain momentum as consumers demand cleaner labels.
- Regulatory environments will continue to tighten, influencing the development and approval of new anti-caking solutions.
- Emerging economies in Asia-Pacific will contribute significantly to market growth due to rapid industrialization and urbanization.
- Innovation in anti-caking agent formulations will focus on improving efficacy and functionality across diverse applications.
- Strategic partnerships and acquisitions among key players will shape the competitive landscape and drive market expansion.
- The rise in disposable incomes and changing lifestyles in developing regions will increase the consumption of processed foods.
- Growing environmental concerns will push for sustainable and eco-friendly anti-caking solutions.
- The market will see increased competition from new entrants offering specialized and region-specific products
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What are anti-caking agents and why are they used?
What types of anti-caking agents are available in the market?
How do technological advancements impact anti-caking agents?
Which industries are the primary users of anti-caking agents?
How do regulatory standards affect the anti-caking agents’ market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Anti-Caking Agents Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Anti-Caking Agents Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 999.4 million → forecast year: USD 1,295.7 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Anti-Caking Agents Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Anti-Caking Agents Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Anti-Caking Agents Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Anti-Caking Agents Market Drivers
- 3.3 Anti-Caking Agents Market Restraints & Challenges
- 3.4 Anti-Caking Agents Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Anti-Caking Agents Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Anti-Caking Agents Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Anti-Caking Agents category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Anti-Caking Agents Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Anti-Caking Agents Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Anti-Caking Agents market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Anti-Caking Agents Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Anti-Caking Agents Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Anti-Caking Agents Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Anti-Caking Agents (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Anti-Caking Agents Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Anti-Caking Agents Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Anti-Caking Agents Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Anti-Caking Agents Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Anti-Caking Agents Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Anti-Caking Agents Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Anti-Caking Agents Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Anti-Caking Agents Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Anti-Caking Agents Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
