
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Anti-Static Additives Market Size 2024 | USD 632.08 million |
| Anti-Static Additives Market, CAGR | 7.45% |
| Anti-Static Additives Market Size 2032 | USD 1,169.59 million |
Market Overview:
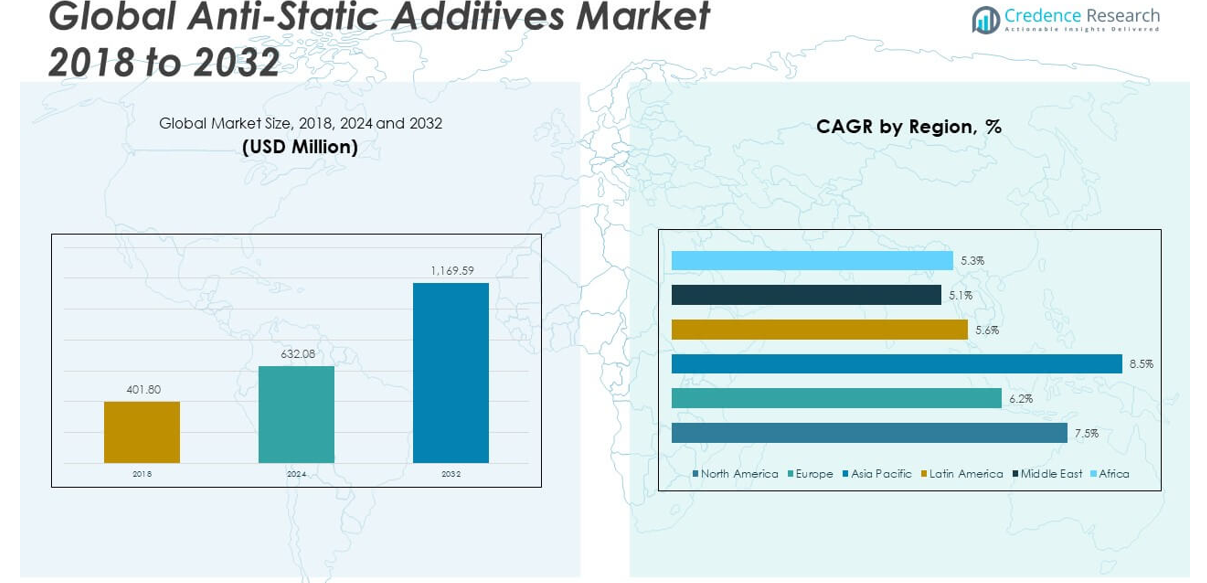
The Global Anti-Static Additives Market size was valued at USD 401.80 million in 2018 to USD 632.08 million in 2024 and is anticipated to reach USD 1,169.59 million by 2032, at a CAGR of 7.45% during the forecast period.
Several factors are propelling the expansion of the anti-static additives market. The escalating demand for consumer electronics, particularly in regions like North America and Asia-Pacific, necessitates the use of anti-static solutions to protect sensitive components from ESD. Additionally, the automotive industry's shift towards electric vehicles and the aerospace sector's emphasis on lightweight materials have increased the need for anti-static additives to maintain the integrity of electronic systems and components. Furthermore, stringent regulatory standards concerning electrostatic discharge in manufacturing processes are compelling industries to adopt anti-static additives to comply with safety norms and enhance product reliability..
The Asia-Pacific region holds the largest market share for anti-static additives. This dominance is driven by rapid industrialization, robust manufacturing capabilities, and a growing consumer electronics market in countries like China, India, and Japan. North America follows closely, with the United States leading in demand due to its advanced electronics, automotive, and aerospace industries. Europe also presents significant growth opportunities, particularly in countries such as Germany, France, and the United Kingdom, where the automotive and electronics sectors are expanding. Emerging markets in Latin America and the Middle East & Africa are witnessing increased adoption of anti-static additives, fueled by industrial growth and infrastructure development in countries like Brazil, Saudi Arabia, and South Africa.
Market Insights:
- The global anti-static additives market was valued at USD 401.80 million in 2018 and is projected to reach USD 1,169.59 million by 2032, growing at a CAGR of 7.45%.
- The increasing demand for consumer electronics, particularly in regions like North America and Asia-Pacific, is driving the growth of anti-static additives to protect sensitive components from electrostatic discharge (ESD).
- The automotive industry's shift towards electric vehicles (EVs) and the aerospace sector's emphasis on lightweight materials are further propelling the need for anti-static additives to maintain the integrity of electronic systems.
- Strict regulatory standards concerning electrostatic discharge are compelling industries to adopt anti-static additives, ensuring compliance and reducing product failures.
- The growth of e-commerce has led to increased demand for anti-static additives in packaging to prevent static buildup during the transportation of fragile electronic devices.
- The Asia-Pacific region holds the largest market share, driven by rapid industrialization, robust manufacturing capabilities, and a growing consumer electronics market in countries like China, India, and Japan.
- The high cost of advanced anti-static additives and limited compatibility with certain materials remain challenges, particularly for small to medium-sized manufacturers and industries with diverse material needs.
Market Drivers:
Increasing Demand from Electronics and Consumer Goods Industries
The global anti-static additives market is largely driven by the growing need for electrostatic discharge (ESD) protection in the electronics and consumer goods industries. The increasing production of electronic devices, such as smartphones, computers, and televisions, has amplified the need for anti-static solutions. These devices are highly sensitive to ESD, which can cause permanent damage to electronic components. Anti-static additives play a crucial role in ensuring that these products remain safe during manufacturing, transportation, and storage. The rising demand for consumer electronics, coupled with the need to mitigate risks associated with static charges, continues to fuel the growth of anti-static additives in the market.
- For example, DuPont’s Entira™ Antistat SD 100 and Entira™ Antistat 500 are specifically engineered for polyolefins and other polymers, ensuring permanent anti-static dissipationand maintaining clarity and non-yellowing properties over time.
Expansion in the Automotive and Aerospace Industries
The automotive and aerospace industries are another key factor propelling the growth of the anti-static additives market. The shift towards electric vehicles (EVs) has led to an increase in the use of electronic components, batteries, and lightweight materials that are susceptible to electrostatic charges. Anti-static additives are now being integrated into automotive parts to enhance the performance and safety of these components. Similarly, in the aerospace industry, stringent safety standards for electronic systems and the need for high-performance materials require the use of anti-static solutions. Anti-static additives are essential in preventing static buildup that could potentially lead to malfunctions or hazardous situations in these industries.
- For example, BASF’s Irgastat® P 18 anti-static additive is used in polypropylene (PP) and thermoplastic polyurethane (TPU) components, delivering surface resistivity values typically in the range of 10⁹–10¹² Ω/sq and static decay times around 1–3 seconds, as documented in BASF’s technical datasheets. These properties help meet ESD safety requirements in automotive and electronic applications.
Strict Regulatory Standards and Safety Compliance
Stringent regulatory requirements concerning electrostatic discharge protection are compelling industries to adopt anti-static additives. Governments and international regulatory bodies have set specific standards to safeguard sensitive electronic components and materials from ESD. Companies are under increasing pressure to meet these standards and avoid penalties related to non-compliance. The use of anti-static additives ensures that products conform to safety regulations, reducing the risk of product failures and recalls. This growing emphasis on compliance is pushing manufacturers across various sectors, such as electronics, packaging, and automotive, to incorporate anti-static additives into their production processes.
Growth of E-commerce and Packaging Applications
The expansion of e-commerce has significantly contributed to the demand for anti-static additives in packaging materials. Online retail has seen a surge in the volume of goods being transported, including electronic devices and fragile items. Packaging that incorporates anti-static additives protects these goods from potential damage caused by static buildup during shipping and handling. The growing emphasis on consumer protection and product quality assurance has further driven the need for static-free packaging solutions. Anti-static additives are increasingly being used in packaging materials, ensuring safe delivery and reducing the risk of damage during transit.
Market Trends:
Shift Towards Sustainable and Eco-Friendly Anti-Static Additives
A notable trend in the global anti-static additives market is the increasing demand for eco-friendly and sustainable additives. With growing awareness surrounding environmental concerns, industries are seeking additives that are both effective in preventing static build-up and less harmful to the environment. Manufacturers are developing additives that are biodegradable, non-toxic, and free from harmful solvents, aligning with global sustainability goals. This trend is particularly evident in industries such as packaging, where companies are focused on reducing their carbon footprint. The push for eco-friendly alternatives is expected to become more pronounced as governments introduce stricter environmental regulations, prompting further innovation in anti-static additives.
- For example, Palsgaard’s official product datasheets and technical bulletinsconfirm that Einar® 601, when used in LDPE and other polyolefins, achieves static decay times of less than 2 seconds.
Technological Advancements in Anti-Static Additive Formulations
Technological advancements in the formulation of anti-static additives have introduced new opportunities for growth in the market. Companies are increasingly investing in research and development to improve the performance of these additives in various applications. New formulations are providing more effective static control, longer-lasting protection, and better compatibility with a wider range of materials. These developments enable anti-static additives to be used in more demanding applications, such as high-temperature environments and complex electronic systems. As technology continues to advance, the formulation of anti-static additives is expected to become more sophisticated, driving greater efficiency and versatility in their use.
Rising Demand for Anti-Static Additives in the Automotive Sector
The automotive sector's adoption of anti-static additives is another significant trend in the market. With the increasing complexity of electronic systems in modern vehicles, the need for static control is more important than ever. Electric and hybrid vehicles, in particular, are incorporating more electronic components, including sensors, batteries, and control systems. Anti-static additives are being used in automotive parts to prevent ESD, ensuring the reliable operation of these sensitive components. This trend is expected to continue as automotive manufacturers increasingly prioritize the integration of electronic systems into their vehicles, further driving the demand for anti-static solutions.
Integration of Anti-Static Additives in New Industrial Applications
Anti-static additives are finding new applications in industries beyond electronics, packaging, and automotive. The growing use of anti-static solutions in textiles, construction materials, and medical devices is expanding the scope of the global anti-static additives market. In textiles, anti-static additives are being incorporated into fabrics used in clean rooms and medical environments to maintain sterile conditions. Similarly, the construction industry is using anti-static additives in materials like paints and coatings to reduce the risk of static discharge in sensitive areas such as data centers and laboratories. As industries become more aware of the benefits of static control in diverse environments, the demand for anti-static additives in these sectors is expected to rise.
- For example, the addition of 02–0.05 parts by weight of antistatic additive per part of fabricis standard in high-performance antistatic textiles, with ethoxylated alkylamines and quaternary ammonium compounds providing robust static control even at low humidity.
Market Challenges Analysis:
High Cost of Advanced Anti-Static Additives
One of the primary challenges faced by the global anti-static additives market is the high cost associated with advanced additives. Many of the more effective anti-static solutions, especially those that offer long-lasting and high-performance results, are often more expensive than traditional additives. This cost factor limits their adoption, particularly among small and medium-sized manufacturers that may have budget constraints. While these advanced additives provide superior protection, the increased cost can discourage industries from using them, especially in regions where cost optimization is a key consideration. Manufacturers must carefully weigh the benefits of higher-quality anti-static additives against their overall production costs, making price sensitivity a significant barrier in some sectors.
Limited Compatibility with Certain Materials
Another challenge facing the global anti-static additives market is the limited compatibility of certain additives with specific materials. Anti-static additives are often formulated for use with particular polymers or substrates, which means that their effectiveness can be reduced when applied to materials outside their intended range. This restricts the versatility of these additives in industries where a diverse set of materials is used. Incompatibility issues can result in reduced static protection or even product degradation over time, especially in high-performance applications such as electronics or automotive manufacturing. As industries continue to explore new materials and manufacturing processes, ensuring the compatibility of anti-static additives with a wider variety of substrates remains a challenge that must be addressed to expand their market potential.
Market Opportunities:
Expansion in Emerging Markets
The global anti-static additives market presents significant opportunities in emerging markets, where industrialization and infrastructure development are rapidly progressing. Regions such as Asia-Pacific, Latin America, and the Middle East are witnessing increased demand for anti-static solutions across various sectors, including electronics, packaging, and automotive. As these industries grow and adopt advanced manufacturing technologies, the need for reliable static control will rise. Companies operating in the market can capitalize on this trend by expanding their product offerings and improving accessibility to these regions, where economic development is driving higher production volumes and standards.
Technological Advancements and Customization
Technological advancements present another promising opportunity for the anti-static additives market. The increasing demand for highly specialized anti-static additives tailored to specific industrial applications opens the door for innovation. Manufacturers can focus on developing customized solutions that meet the unique needs of industries such as aerospace, healthcare, and textiles. These industries require high-performance, durable additives that can maintain static control in challenging environments. By investing in research and development, market players can position themselves as leaders in the supply of cutting-edge, application-specific anti-static additives, enhancing their competitive edge.
Market Segmentation Analysis:
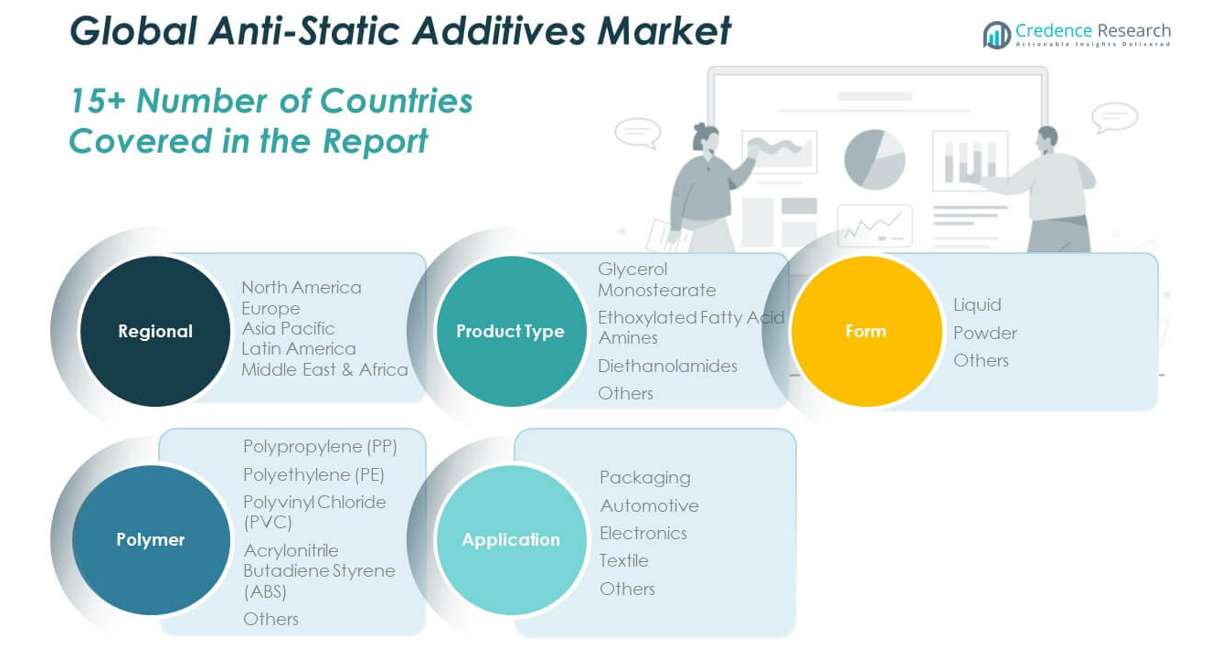
The global anti-static additives market is segmented into product type, form, polymer, and end-use categories.
By product type, glycerol monostearate, ethoxylated fatty acid amines, and diethanolamides are the primary additives, each serving different industrial needs based on their chemical properties. These additives are essential for controlling electrostatic charges in various applications.
By form, liquid additives dominate the market, offering easy integration into various manufacturing processes. Powdered additives also see significant use, especially in applications where more controlled release of anti-static properties is needed. The "others" category includes specialized forms used for unique applications.
- For powdered forms, Evonik Industriesmarkets TEGOMER® E 525, a powdered anti-static additive for engineering plastics, which is used at 5–2.0% loading for consistent ESD protection in injection-molded parts.
By polymer segment includes polypropylene (PP), polyethylene (PE), polyvinyl chloride (PVC), and acrylonitrile butadiene styrene (ABS). These polymers are common substrates in industries like automotive and electronics, where anti-static additives help maintain product integrity by preventing electrostatic discharge (ESD). Other polymers used in niche markets also contribute to segment growth.
- For ABS, Sabo S.p.A.offers SABOSTAT® 23150, an anti-static additive for ABS and PVC, which maintains ESD protection even after multiple processing cycles.
By end-use, packaging holds the largest share, driven by the need to protect sensitive electronic components during transport. The automotive sector also significantly contributes to the demand, particularly with the rise of electric vehicles. Electronics and textile industries increasingly adopt anti-static solutions to protect their products from damage. The “others” segment includes specialized industrial applications across various sectors.
Segmentation:
By Product Type:
- Glycerol Monostearate
- Ethoxylated Fatty Acid Amines
- Diethanolamides
- Others
By Form:
- Liquid
- Powder
- Others
By Polymer:
- Polypropylene (PP)
- Polyethylene (PE)
- Polyvinyl Chloride (PVC)
- Acrylonitrile Butadiene Styrene (ABS)
- Others
By End Use:
- Packaging
- Automotive
- Electronics
- Textile
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America Anti-Static Additives Market
The North America Anti-Static Additives Market size was valued at USD 160.10 million in 2018, projected to reach USD 248.98 million in 2024, and is anticipated to grow to USD 462.12 million by 2032, at a CAGR of 7.5% during the forecast period. North America holds a significant share of the global anti-static additives market, driven by the robust presence of the electronics, automotive, and aerospace industries. The demand for anti-static additives in this region is spurred by the increasing production of high-performance electronic devices and the adoption of electric vehicles. Moreover, stringent regulatory standards regarding electrostatic discharge (ESD) in manufacturing processes further boost market growth. The U.S. is the largest contributor to the region's market, accounting for a substantial portion of the market share. Canada and Mexico are also witnessing growing demand, driven by their expanding industrial sectors.
Europe Anti-Static Additives Market
The Europe Anti-Static Additives Market size was valued at USD 79.34 million in 2018, anticipated to reach USD 118.34 million in 2024, and is projected to reach USD 200.26 million by 2032, growing at a CAGR of 6.2% during the forecast period. Europe is one of the prominent markets for anti-static additives, with key industries such as automotive, electronics, and packaging driving demand. Countries like Germany, the UK, and France lead in industrial applications, with the growing automotive sector contributing significantly to market growth. The demand for eco-friendly and sustainable anti-static additives is also gaining traction, as European companies emphasize environmentally friendly solutions. Regulatory frameworks in the EU, which focus on product safety and electrostatic discharge control, are further supporting market growth in the region.
Asia Pacific Anti-Static Additives Market
The Asia Pacific Anti-Static Additives Market size was valued at USD 125.46 million in 2018, expected to reach USD 207.55 million in 2024, and projected to grow to USD 416.38 million by 2032, at a CAGR of 8.5% during the forecast period. Asia Pacific dominates the global market, accounting for a large share due to the rapid industrialization, growing electronics manufacturing, and increasing adoption of electric vehicles. China, Japan, and India are key contributors to the region’s market growth, driven by a surge in the production of electronic devices, automotive components, and packaging materials. The region's demand for anti-static additives is expected to increase as manufacturing sectors continue to expand, particularly in industries requiring high-performance static control.
Latin America Anti-Static Additives Market
The Latin America Anti-Static Additives Market size was valued at USD 17.01 million in 2018, expected to reach USD 26.39 million in 2024, and projected to grow to USD 42.56 million by 2032, at a CAGR of 5.6% during the forecast period. The market in Latin America is growing steadily, with Brazil and Mexico being key drivers of demand. The rise of consumer electronics and the expansion of the automotive sector in these countries are fueling the adoption of anti-static additives. While the market is still emerging compared to other regions, increasing industrialization and growing awareness about electrostatic protection are contributing to its growth. As more companies enter the manufacturing space, the demand for static control solutions is expected to rise.
Middle East Anti-Static Additives Market
The Middle East Anti-Static Additives Market size was valued at USD 10.99 million in 2018, projected to reach USD 15.76 million in 2024, and anticipated to grow to USD 24.48 million by 2032, at a CAGR of 5.1% during the forecast period. The market in the Middle East is driven by expanding industrial activities, particularly in the electronics and automotive sectors. Countries such as the UAE and Saudi Arabia are seeing an increase in the production of electronic devices and the introduction of electric vehicles, both of which require anti-static additives. The growing focus on infrastructure development and modern manufacturing processes in the region also supports the market’s growth, as static control becomes a priority in high-performance industries.
Africa Anti-Static Additives Market
The Africa Anti-Static Additives Market size was valued at USD 8.91 million in 2018, expected to reach USD 15.05 million in 2024, and is projected to grow to USD 23.77 million by 2032, at a CAGR of 5.3% during the forecast period. Africa's market for anti-static additives is growing at a moderate pace, with key growth drivers including industrial expansion in countries such as South Africa, Egypt, and Nigeria. The increasing manufacturing of consumer electronics and automotive products is contributing to the demand for anti-static additives. However, the market remains relatively small compared to other regions, with more focus on infrastructure development and emerging industrial sectors. As industries in the region adopt more advanced technologies, the need for static control solutions will continue to increase.
Key Player Analysis:
- Evonik Industries AG
- Clariant
- Croda International PLC
- Adeka Corporation
- 3M
- BASF SE
- Mitsubishi Chemical Group Corporation
- Nouryon
- LyondellBasell Industries Holdings BV
- Ampacet Corporation
- Arkema
- Kao Corporation
Competitive Analysis:
The global anti-static additives market is characterized by a competitive landscape with several key players focusing on innovation, product development, and expanding market reach. Leading companies in the market include BASF SE, Dow Chemical Company, Evonik Industries AG, and Clariant, among others. These players invest heavily in research and development to improve the performance and sustainability of anti-static additives, catering to industries such as electronics, automotive, and packaging. The competition is intensified by the increasing demand for eco-friendly and cost-effective solutions, pushing companies to develop more efficient, environmentally friendly additives. To maintain a competitive edge, firms are also leveraging strategic partnerships and acquisitions, targeting regional expansions and enhancing production capabilities. Smaller players are focusing on niche markets and offering tailored solutions, particularly in emerging markets. With innovation driving market growth, competition remains fierce as players strive to meet evolving industry needs.
Recent Developments:
- In May 2025, BASF announced its intention to acquire full ownership of Alsachimie, a joint venture with DOMO Chemicals, to strengthen its position in the polyamide 6.6 value chain-an important step for its performance polymer and additive business.
- In March 2025, Evonik Coating Additives launched its first mass-balanced products, TEGO® Wet 270 eCO and TEGO® Foamex 812 eCO. These additives deliver the same high-performance defoaming and wetting properties as their conventional counterparts but with a significantly reduced carbon footprint, thanks to the use of ISCC-certified, bio-attributed raw materials.
- In March 2023, Croda International Plcintroduced a new range of bio-based internal antistatic agents designed specifically for polyolefins, targeting improved processing efficiency and surface quality in packaging and automotive applications.
Market Concentration & Characteristics:
The global anti-static additives market exhibits moderate concentration, with a few dominant players holding significant market share. Key companies like BASF, Evonik Industries, and 3M lead the market by focusing on continuous product innovation and expanding their geographical presence. Smaller players often target niche applications or regions, offering specialized solutions to meet specific customer demands. The market is characterized by a high degree of competition, driven by the need for eco-friendly additives and high-performance solutions. The growing demand for anti-static additives across industries such as electronics, automotive, and packaging is encouraging new entrants and fostering strategic partnerships. Despite the dominance of large corporations, regional players are increasingly playing a vital role by catering to local needs and focusing on cost-effective solutions. This competitive landscape fuels both innovation and growth across the market.
Report Coverage:
The research report offers an in-depth analysis based on product type, form, polymer, and end-use. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The global anti-static additives market is expected to experience steady growth in the coming years, driven by increasing demand across multiple industries.
- Asia Pacific will continue to lead the market, with significant growth driven by the expanding electronics manufacturing sector.
- North America will see consistent growth, propelled by innovations in electronics and stricter regulatory standards for electrostatic discharge protection.
- Europe will focus on sustainable and eco-friendly additives, fostering steady market expansion as industries adopt more environmentally conscious solutions.
- Latin America and the Middle East are emerging markets with growing demand for anti-static solutions in sectors such as electronics and automotive.
- The African market will grow at a moderate pace, with increased industrialization and a rising focus on packaging and electronics industries.
- Technological advancements are expected to improve the performance and durability of anti-static additives in a variety of applications.
- The push for more sustainable, biodegradable additives will increase in response to rising environmental concerns.
- Strategic partnerships and acquisitions are likely to drive market consolidation, as companies expand their product offerings and geographical reach.
- Evolving regulatory standards related to electrostatic discharge will continue to drive the adoption of anti-static additives across various industries.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Escalating Demand for Consumer Electronics
The proliferation of smartphones, computers, and other electronic devices, especially in Asia-Pacific and North America, is driving the need for anti-static additives to protect sensitive components from electrostatic discharge (ESD) during manufacturing, transport, and storage.
Growth in Electric Vehicles and Lightweight Automotive Components
The automotive industry's shift toward electric vehicles and the use of lightweight materials has increased the integration of electronic systems, necessitating anti-static additives to ensure the reliability and safety of these components.
Stringent Regulatory Standards for ESD Protection
Tighter regulations and safety standards regarding electrostatic discharge in manufacturing processes are compelling industries to adopt anti-static additives to comply with safety norms and reduce product failures and recalls.
Expansion of E-commerce and Demand for Protective Packaging
The surge in e-commerce has led to increased shipping of fragile electronics, boosting the use of anti-static additives in packaging materials to prevent static buildup and ensure safe delivery.
Technological Advancements and Customization of Additives
Ongoing R&D is resulting in more effective, longer-lasting, and material-compatible anti-static additives, enabling their use in demanding applications and supporting market growth through innovation.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Anti-Static Additives Market?
What factors are driving the growth of the Global Anti-Static Additives Market?
What are some challenges faced by the Global Anti-Static Additives Market?
Who are the major players in the Global Anti-Static Additives Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Liquid
- 1.2.2 Powder
- 1.2.3 Others
- 1.3 By End Use
- 1.3.1 Packaging
- 1.3.2 Automotive
- 1.3.3 Electronics
- 1.3.4 Textile
- 1.3.5 Others
- 1.4 By Polymer
- 1.4.1 Polypropylene (PP)
- 1.4.2 Polyethylene (PE)
- 1.4.3 Polyvinyl Chloride (PVC)
- 1.4.4 Acrylonitrile Butadiene Styrene (ABS)
- 1.4.5 Others
- 1.5 By Product Type
- 1.5.1 Glycerol Monostearate
- 1.5.2 Ethoxylated Fatty Acid Amines
- 1.5.3 Diethanolamides
- 1.5.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 401.80 million → 2024: USD 632.08 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2024
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2024
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Anti-Static Additives Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Anti-Static Additives Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2024
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2024
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Anti-Static Additives Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2024
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Anti-Static Additives Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Anti-Static Additives Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Anti-Static Additives Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Anti-Static Additives Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Anti-Static Additives Market Outlook, 2018-2024
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 401.80 million → 2024: USD 632.08 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2024
- 11.2.1 Revenue Forecast to 2024
- 11.2.2 Volume Forecast to 2024
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Anti-Static Additives Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2018-2024
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2024
- 12.3.4 Volume Forecast, 2018-2024
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Liquid
- 12.3.7.2 Powder
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End Use - Market Size and Forecast, 2018-2024
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2024
- 12.4.4 Volume Forecast, 2018-2024
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Packaging
- 12.4.7.2 Automotive
- 12.4.7.3 Electronics
- 12.4.7.4 Textile
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Polymer - Market Size and Forecast, 2018-2024
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2024
- 12.5.4 Volume Forecast, 2018-2024
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Polypropylene (PP)
- 12.5.7.2 Polyethylene (PE)
- 12.5.7.3 Polyvinyl Chloride (PVC)
- 12.5.7.4 Acrylonitrile Butadiene Styrene (ABS)
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Product Type - Market Size and Forecast, 2018-2024
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2018-2024
- 12.6.4 Volume Forecast, 2018-2024
- 12.6.5 Base-Year Market Share, 2018
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Glycerol Monostearate
- 12.6.7.2 Ethoxylated Fatty Acid Amines
- 12.6.7.3 Diethanolamides
- 12.6.7.4 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Anti-Static Additives End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Anti-Static Additives Geographic Market Outlook, 2018-2024
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2024
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Anti-Static Additives Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2024
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Anti-Static Additives Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2024
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Evonik Industries AG
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Clariant
- 18.4 Croda International PLC
- 18.5 Adeka Corporation
- 18.6 3M
- 18.7 BASF SE
- 18.8 Mitsubishi Chemical Group Corporation
- 18.9 Nouryon
- 18.10 LyondellBasell Industries Holdings BV
- 18.11 Ampacet Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

