
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Asia Pacific Construction Aggregates Market Size 2024 | USD 95,654.89 million |
| Asia Pacific Construction Aggregates Market, CAGR | 6.34% |
| Asia Pacific Construction Aggregates Market Size 2032 | USD 1,56,471.95 million |
Market Overview
Asia Pacific Construction Aggregates Market size was valued at USD 95,654.89 million in 2024 and is anticipated to reach USD 1,56,471.95 million by 2032, at a CAGR of 6.34% during the forecast period (2024-2032).
The Asia Pacific construction aggregates market is driven by rapid urbanization, infrastructure development, and government investments in smart cities and transportation networks. Rising residential and commercial construction, particularly in emerging economies like India and China, fuels aggregate demand. The growing emphasis on sustainable and recycled aggregates due to environmental concerns and stringent regulations further shapes the market. Technological advancements, such as automated crushing and screening equipment, enhance efficiency and cost-effectiveness. Additionally, increasing foreign direct investments (FDIs) in construction and real estate sectors strengthen market expansion. The region’s booming e-commerce industry also contributes to demand for warehousing and logistics infrastructure. However, fluctuations in raw material prices and environmental restrictions on quarrying activities pose challenges. To mitigate supply chain risks, companies are adopting digital solutions for real-time monitoring and resource optimization. Overall, the Asia Pacific construction aggregates market is poised for steady growth, supported by infrastructure modernization and eco-friendly material innovations.
The Asia Pacific construction aggregates market is geographically diverse, with strong demand across both developed and emerging economies. China, India, Japan, South Korea, Australia, and Southeast Asian nations like Indonesia, Vietnam, and Thailand are key contributors to market growth. Rapid urbanization, large-scale infrastructure projects, and industrial expansion drive demand for aggregates in these regions. Governments are investing heavily in smart cities, transportation networks, and commercial real estate, further boosting the market. Additionally, sustainability concerns are promoting the adoption of recycled aggregates and eco-friendly construction materials. Key players in the Asia Pacific construction aggregates market include CRH plc, China National Building Material Co. Ltd, Colas Group, Siam Cement Group (SCG), CEMEX S.A.B. de C.V., Heidelberg Materials AG, EUROVIA Kamenolomy AS, Sika AG, Vulcan Materials Company, Martin Marietta Materials Inc., Fletcher Building, Buzzi S.p.A., Boral Limited, Tarmac, LSR Group, and Adbri Limited, all of whom are focusing on innovation and expansion strategies.
Market Insights
- The Asia Pacific construction aggregates market was valued at USD 95,654.89 million in 2024 and is expected to reach USD 156,471.95 million by 2032, growing at a CAGR of 6.34% during the forecast period.
- Rapid urbanization and infrastructure development, particularly in China and India, are key drivers boosting aggregate demand.
- The market is witnessing a shift toward sustainable and recycled aggregates due to environmental regulations and resource depletion concerns.
- Major players, including CRH plc, China National Building Material Co. Ltd, and Siam Cement Group (SCG), are expanding their product portfolios and adopting advanced processing technologies.
- Fluctuations in raw material prices, strict mining regulations, and logistical challenges act as market restraints, impacting supply chains and operational costs.
- China dominates the regional market, followed by India, Japan, and Southeast Asian countries, with strong demand from residential, commercial, and industrial sectors.
- Advancements in AI-driven quarrying, automated screening, and digital supply chain solutions are enhancing efficiency and cost-effectiveness.
Report Scope
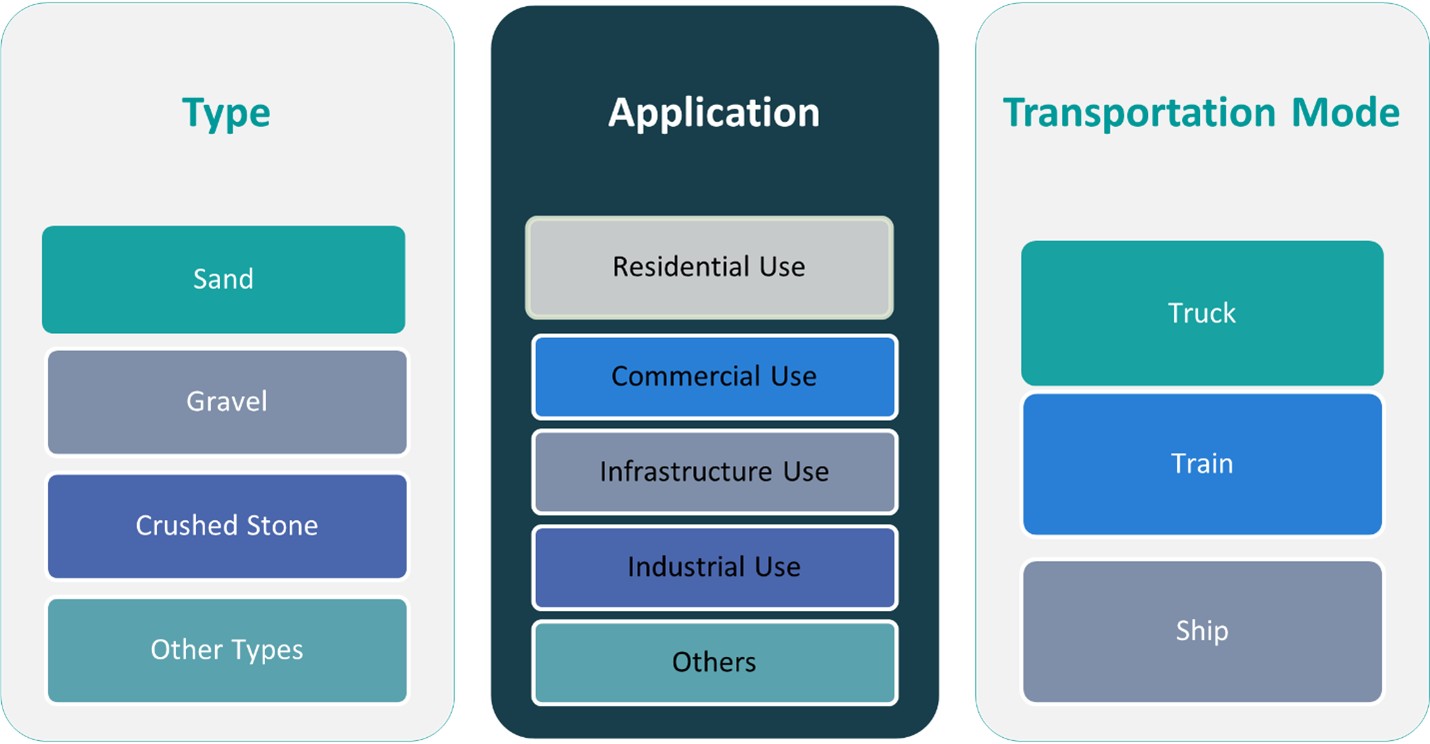
This report segments the Asia Pacific Construction Aggregates Market as follows:
Market Drivers
Rapid Urbanization and Infrastructure Development
The Asia Pacific construction aggregates market is primarily driven by rapid urbanization and large-scale infrastructure projects. Countries like China, India, and Indonesia are witnessing significant population growth in urban centers, leading to a surge in residential and commercial construction. For instance, the Indian government’s Smart Cities Mission has initiated projects in over 100 cities, focusing on urban renewal and retrofitting. Governments across the region are heavily investing in smart cities, transportation networks, and public infrastructure, which require substantial amounts of aggregates for roadways, bridges, railways, and airports. These developments directly boost the demand for construction aggregates, positioning the industry for long-term growth.
Government Investments and Policy Support
Strategic government initiatives play a crucial role in shaping the construction aggregates market. For instance, India’s National Infrastructure Pipeline (NIP) has allocated significant funding for urban infrastructure, including affordable housing and sustainable urban development. Large-scale public-private partnerships (PPPs) and foreign direct investments (FDIs) in real estate and infrastructure sectors are fostering industry expansion. Many governments in the region are focusing on affordable housing projects and sustainable urban development, further fueling aggregate consumption. Additionally, regulatory policies promoting sustainable mining practices and the use of recycled aggregates are driving innovation in the market.
Technological Advancements in Aggregate Processing
The adoption of advanced technologies in aggregate processing and production is another key driver of market growth. Automated crushing and screening equipment, along with digital monitoring solutions, are improving efficiency and reducing operational costs. The integration of AI and IoT in quarrying and mining operations helps optimize resource utilization and enhance environmental compliance. These advancements enable manufacturers to meet rising demand while adhering to stringent quality and sustainability standards, ensuring long-term market competitiveness.
Sustainability and the Shift Toward Recycled Aggregates
Environmental concerns and regulatory restrictions on quarrying activities are prompting a shift toward sustainable and recycled aggregates. Construction waste recycling is gaining traction, reducing reliance on natural aggregates and minimizing environmental impact. Many companies are investing in eco-friendly production techniques, such as carbon capture in cement manufacturing and the use of industrial by-products in aggregate production. The growing preference for green construction materials among developers and consumers is further accelerating the adoption of sustainable aggregates, ensuring the industry's alignment with global environmental goals.
Market Trends
Rising Demand for Sustainable and Recycled Aggregates
The Asia Pacific construction aggregates market is witnessing a strong shift toward sustainability, driven by increasing environmental regulations and growing awareness of eco-friendly construction materials. Governments and industry players are emphasizing the use of recycled aggregates sourced from construction and demolition waste to reduce dependence on natural resources. For instance, Japan has implemented policies to encourage the recycling of construction waste, significantly reducing reliance on natural aggregates. The adoption of circular economy practices in the construction sector is further encouraging the development of innovative recycling technologies. This trend not only minimizes environmental impact but also reduces material costs, making sustainable aggregates a preferred choice for infrastructure projects.
Technological Integration in Aggregate Processing
The integration of advanced technologies, such as artificial intelligence (AI), automation, and the Internet of Things (IoT), is transforming aggregate processing and supply chain management. Smart quarrying techniques, including automated crushing, screening, and real-time monitoring systems, are enhancing production efficiency while maintaining quality standards. Additionally, digital tracking solutions are improving logistics, reducing wastage, and optimizing resource utilization. As construction companies seek to enhance operational efficiency and reduce costs, the demand for tech-driven aggregate solutions continues to rise.
Expansion of Infrastructure and Mega Projects
Large-scale infrastructure projects, including highways, rail networks, airports, and smart city developments, are fueling the demand for construction aggregates across Asia Pacific. For instance, China's Belt and Road Initiative (BRI) has led to extensive infrastructure investments, including high-speed rail networks and urban transit systems. Countries like China, India, and Indonesia are leading the way with extensive government-backed infrastructure investments. The Belt and Road Initiative (BRI) and other regional development programs are further boosting aggregate consumption. This trend is expected to continue as urbanization accelerates and governments prioritize long-term infrastructure modernization.
Increasing Foreign Direct Investment in Construction
Foreign direct investment (FDI) in the Asia Pacific construction sector is playing a crucial role in market expansion. Global investors are actively participating in commercial real estate, industrial zones, and residential developments, leading to increased demand for aggregates. With rapid industrialization and the growth of e-commerce, the need for logistics hubs and warehouses is also rising, further driving aggregate consumption. As favorable investment policies and economic growth attract more foreign players, the construction aggregates market is expected to witness steady expansion in the coming years.
Market Challenges Analysis
Environmental Regulations and Resource Depletion
The Asia Pacific construction aggregates market faces significant challenges due to stringent environmental regulations and the depletion of natural resources. Governments are enforcing stricter policies on quarrying activities to curb deforestation, soil erosion, and air pollution caused by dust emissions. These regulations often lead to delays in obtaining mining permits and higher compliance costs for aggregate producers. Additionally, excessive extraction of natural aggregates is depleting reserves, making it difficult to meet the growing demand. As a result, companies must invest in sustainable alternatives, such as recycled aggregates, which require advanced processing technologies and higher initial capital investment.
Fluctuating Raw Material Prices and Supply Chain Disruptions
Volatility in raw material prices and supply chain disruptions pose major hurdles for the construction aggregates market. Factors such as fuel price fluctuations, labor shortages, and geopolitical uncertainties affect production costs and logistics. For instance, during the COVID-19 pandemic, supply chain vulnerabilities were exposed, leading to material shortages and project delays across countries like India and Indonesia. Additionally, transportation bottlenecks, especially in densely populated or remote areas, further escalate costs and impact timely project execution. To mitigate these risks, companies are increasingly adopting digital supply chain management solutions and diversifying sourcing strategies, but these adjustments require significant investment and operational restructuring.
Market Opportunities
The Asia Pacific construction aggregates market presents significant growth opportunities driven by rapid urbanization and large-scale infrastructure development. Governments across the region are investing heavily in transportation networks, smart cities, and residential housing projects, increasing the demand for high-quality aggregates. Emerging economies such as India, Indonesia, and Vietnam are witnessing a surge in construction activities, fueled by population growth and rising disposable incomes. Additionally, foreign direct investment (FDI) in the real estate and industrial sectors is creating new avenues for market expansion. The ongoing Belt and Road Initiative (BRI) and other cross-border infrastructure projects are further boosting aggregate consumption, offering long-term growth prospects for industry players.
Sustainability and innovation in aggregate production also present lucrative opportunities. The shift toward eco-friendly materials and recycled aggregates is gaining momentum due to stringent environmental regulations and the push for green construction practices. Companies that invest in advanced processing technologies, such as automated crushing and digital monitoring systems, can enhance operational efficiency and meet the rising demand for sustainable aggregates. Additionally, the development of lightweight and high-performance aggregates for specialized construction applications, such as high-rise buildings and earthquake-resistant structures, is opening new market segments. By embracing technological advancements and sustainable practices, businesses can position themselves as leaders in the evolving construction materials industry, ensuring long-term profitability and market relevance.
Market Segmentation Analysis:
By Type:
The Asia Pacific construction aggregates market is segmented by type into sand, gravel, crushed stone, and other materials. Sand is the most widely used aggregate, driven by its essential role in concrete production and masonry work. However, increasing environmental restrictions on river sand mining have led to the growing use of manufactured sand (M-sand) as a sustainable alternative. Gravel is another key segment, commonly used in road construction, railway ballast, and drainage systems due to its durability and strength. The demand for crushed stone is also rising, particularly in large-scale infrastructure projects, as it provides superior load-bearing capacity and structural stability. Other aggregates, such as slag and recycled concrete, are gaining traction as sustainable solutions to reduce reliance on natural resources. With advancements in aggregate processing and stricter environmental regulations, the market is shifting toward eco-friendly and high-performance alternatives, ensuring continued growth across all segments.
By Application:
Based on application, the Asia Pacific construction aggregates market is categorized into residential, commercial, infrastructure, and industrial use. The residential sector holds a significant share, fueled by increasing urbanization, government-led affordable housing programs, and rising disposable incomes. Commercial construction, including office spaces, shopping complexes, and hotels, is also a major contributor, driven by economic expansion and foreign direct investment. Infrastructure projects, such as highways, bridges, airports, and rail networks, represent a crucial market segment, with governments across the region prioritizing large-scale development initiatives. Additionally, the industrial sector, which includes manufacturing plants, logistics hubs, and energy projects, is witnessing steady demand for high-quality aggregates. With continued investment in real estate, transportation, and industrial expansion, the application-based demand for construction aggregates is expected to remain strong, providing substantial growth opportunities for market players.
Segments:
Based on Type:
- Sand
- Gravel
- Crushed Stone
- Other Types
Based on Application:
- Residential Use
- Commercial Use
- Infrastructure Use
- Industrial Use
Based on End- User:
- Truck
- Train
- Ship
Based on the Geography:
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
Regional Analysis
China
China leads the market, holding approximately 45% of the Asia Pacific construction aggregates market share. This dominance is driven by rapid urbanization and extensive infrastructure projects, including the Belt and Road Initiative, which have escalated the demand for construction materials. The country's commitment to urban development and industrial expansion continues to fuel the need for aggregates.
Japan and South Korea
Japan and South Korea also represent notable portions of the market. Japan accounts for 9% of the region's market share, while South Korea holds 4%. In Japan, the demand is primarily driven by maintenance projects, reconstruction efforts, and infrastructure upgrades, reflecting a mature construction industry. South Korea's market benefits from urban development initiatives and technological advancements in construction practices, contributing to its steady growth.
India
India holds a 5% share of the Asia Pacific construction aggregates market. The country's market is expanding due to rapid urbanization and government initiatives like the Smart Cities Mission, which promote investments in housing and urban infrastructure projects. The increasing population and urban migration further amplify the demand for construction aggregates in India.
Southeast Asian
The Southeast Asian region, including countries like Indonesia, Vietnam, Thailand, and the Philippines, collectively accounts for a significant portion of the market. Indonesia, for instance, holds a 7% share. The growing demand in these nations is attributed to rising disposable incomes, urban population growth, and government-led infrastructure initiatives. However, challenges such as regulatory complexities and logistical limitations can impact market expansion. Emphasis on sustainable practices and environmental regulations is also shaping the demand for recycled aggregates and eco-friendly construction materials in these countries.
Key Player Analysis
- CRH plc
- China National Building Material Co. Ltd
- Colas Group
- Siam Cement Group (SCG)
- CEMEX S.A.B. de C.V.
- Heidelberg Materials AG
- EUROVIA Kamenolomy AS
- Sika AG
- Vulcan Materials Company
- Martin Marietta Materials Inc.
- Fletcher Building
- Buzzi S.p.A.
- Boral Limited
- Tarmac
- LSR Group
- Adbri Limited
Competitive Analysis
The Asia Pacific construction aggregates market is highly competitive, with major players focusing on expansion, technological advancements, and sustainable solutions to strengthen their market positions. Leading companies such as CRH plc, China National Building Material Co. Ltd, Colas Group, Siam Cement Group (SCG), CEMEX S.A.B. de C.V., Heidelberg Materials AG, EUROVIA Kamenolomy AS, Sika AG, Vulcan Materials Company, Martin Marietta Materials Inc., Fletcher Building, Buzzi S.p.A., Boral Limited, Tarmac, LSR Group, and Adbri Limited are actively investing in modernizing production facilities and optimizing supply chains. Many of these companies are adopting eco-friendly practices, such as manufacturing recycled aggregates and implementing sustainable mining techniques, to comply with stringent environmental regulations. Additionally, firms are expanding their geographic presence through mergers, acquisitions, and joint ventures to capitalize on the region’s infrastructure boom. The increasing adoption of AI and automation in aggregate processing is also intensifying competition, as companies strive to enhance operational efficiency and reduce costs. Despite market fragmentation, key players with strong distribution networks and innovative product offerings continue to dominate, making technological adaptation and sustainability essential for maintaining a competitive edge in the evolving construction materials industry.
Recent Developments
- In September 2024, Holcim started the Holcim Sustainable Construction Academy. This is a free online training program that teaches about eco-friendly building methods. It helps people who work in construction learn new skills. The program offers both online classes and face-to-face training.
- In October 2024, CRH Ventures launched the Sustainable Building Materials accelerator to scale up creative climate and build technology firms that specialize in CO2-mineralized materials and sustainable binder solutions.
- In July 2024, Heidelberg Materials launched a recycling plant in Katowice, Poland, using a patented ReConcrete process to recycle demolition concrete and replace virgin material.
- In July 2024, Cemex USA formed a joint venture with Couch Aggregates and Premier Holdings for the production and distribution of aggregates in the Mid-South region. Cemex USA already had a strategic partnership with Couch Aggregates. The company stated that this vertical integration, combined with Premier Holdings' Gulf Coast marine terminals, would accelerate its regional growth.
- In April 2024, Rogers Group joined The Road Forward initiative to advance sustainable asphalt production and paving practices.
- In January 2024, Heidelberg Materials launched Evo Build, its new global brand for low-carbon and circular products. This initiative aims to provide sustainable solutions for the construction industry, focusing on reducing carbon emissions and promoting circular economy principles.
Market Concentration & Characteristics
The Asia Pacific construction aggregates market exhibits a moderate to high level of concentration, with a mix of global industry leaders and regional players competing for market share. Large multinational corporations such as CRH plc, China National Building Material Co. Ltd, and Siam Cement Group (SCG) dominate the market through extensive production capacities, advanced technologies, and strong distribution networks. Meanwhile, regional and local manufacturers cater to niche markets, benefiting from proximity to raw material sources and lower operational costs. The market is characterized by high demand variability, driven by infrastructure projects, urbanization, and economic growth in key countries like China, India, Japan, and Indonesia. Additionally, environmental concerns and stringent mining regulations are pushing companies to adopt sustainable production methods and invest in recycled aggregates. As technological advancements and government policies continue to shape the industry, market players must focus on innovation and efficiency to maintain competitiveness in this evolving landscape
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Transportation Mode and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Asia Pacific construction aggregates market will continue to grow steadily, driven by increasing urbanization and infrastructure development.
- Governments will invest heavily in smart cities, highways, rail networks, and commercial real estate projects, boosting aggregate demand.
- The adoption of sustainable and recycled aggregates will rise due to strict environmental regulations and resource conservation efforts.
- Technological advancements in AI, automation, and digital monitoring will improve efficiency and reduce operational costs in aggregate production.
- China will remain the dominant market, while India, Indonesia, and Vietnam will experience rapid growth due to industrialization and urban expansion.
- Major players will focus on mergers, acquisitions, and strategic partnerships to strengthen their market positions and expand geographically.
- Supply chain optimization and improved logistics management will play a crucial role in overcoming transportation challenges and cost fluctuations.
- The demand for high-performance aggregates in specialized construction applications like earthquake-resistant structures will increase.
- Government policies promoting green building materials will drive innovation and new product development in the market.
- Rising foreign direct investment in the construction sector will create new growth opportunities for aggregate manufacturers across the region.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rapid Urbanization and Infrastructure Development
Accelerated urban migration and government-backed infrastructure projects in countries like China, India, and Indonesia are significantly increasing the demand for construction aggregates for roads, bridges, railways, and urban housing.
Government Investments and Policy Support
Strategic initiatives such as India's National Infrastructure Pipeline and the Smart Cities Mission, along with public-private partnerships and FDI, are channeling substantial funding into construction, directly boosting aggregate consumption.
Technological Advancements in Aggregate Processing
The adoption of automated crushing, screening, and digital monitoring technologies is improving operational efficiency and reducing costs, enabling producers to meet rising demand while complying with quality and sustainability standards.
Shift Toward Sustainable and Recycled Aggregates
Stringent environmental regulations and resource depletion concerns are driving the adoption of recycled and eco-friendly aggregates, with companies investing in advanced recycling and green production techniques to align with sustainability goals.
Expansion of Mega Projects and Foreign Direct Investment
Large-scale infrastructure initiatives like China's Belt and Road Initiative and increasing FDI in real estate and logistics are fueling aggregate demand for commercial, industrial, and warehousing developments across the region.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Asia Pacific Construction Aggregates?
What factors are driving the growth of the Asia Pacific Construction Aggregates?
What are some challenges faced by the Asia Pacific Construction Aggregates?
Who are the major players in the Asia Pacific Construction Aggregates?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Sand
- 1.2.2 Gravel
- 1.2.3 Crushed Stone
- 1.2.4 Other Types
- 1.3 By Application
- 1.3.1 Residential Use
- 1.3.2 Commercial Use
- 1.3.3 Infrastructure Use
- 1.3.4 Industrial Use
- 1.4 By Transportation Mode
- 1.4.1 Truck
- 1.4.2 Train
- 1.4.3 Ship
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 95,654.89 million → 2032: USD 156,471.95 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Asia Pacific Construction Aggregates Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Asia Pacific Construction Aggregates Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Asia Pacific Construction Aggregates Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Asia Pacific Construction Aggregates Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Asia Pacific Construction Aggregates Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Asia Pacific Construction Aggregates Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Asia Pacific Construction Aggregates Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Asia Pacific Construction Aggregates Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 95,654.89 million → 2032: USD 156,471.95 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Asia Pacific Construction Aggregates Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Sand
- 12.3.7.2 Gravel
- 12.3.7.3 Crushed Stone
- 12.3.7.4 Other Types
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Residential Use
- 12.4.7.2 Commercial Use
- 12.4.7.3 Infrastructure Use
- 12.4.7.4 Industrial Use
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Transportation Mode - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Truck
- 12.5.7.2 Train
- 12.5.7.3 Ship
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Asia Pacific Construction Aggregates End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Asia Pacific Construction Aggregates Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Asia Pacific Construction Aggregates Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Asia Pacific Construction Aggregates Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 CRH plc
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 China National Building Material Co. Ltd
- 18.4 Siam Cement Group (SCG)
- 18.5 CEMEX S.A.B. de C.V.
- 18.6 Heidelberg Materials AG
- 18.7 Colas Group
- 18.8 Boral Limited
- 18.9 Fletcher Building
- 18.10 Adbri Limited
- 18.11 Tarmac
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

