
Market Overview
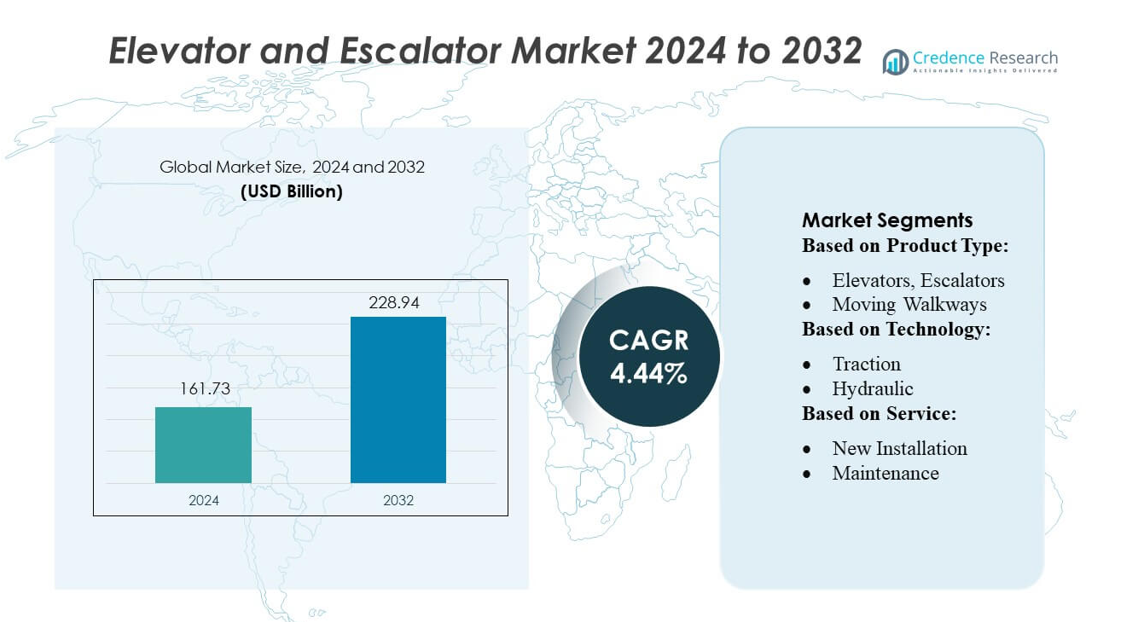
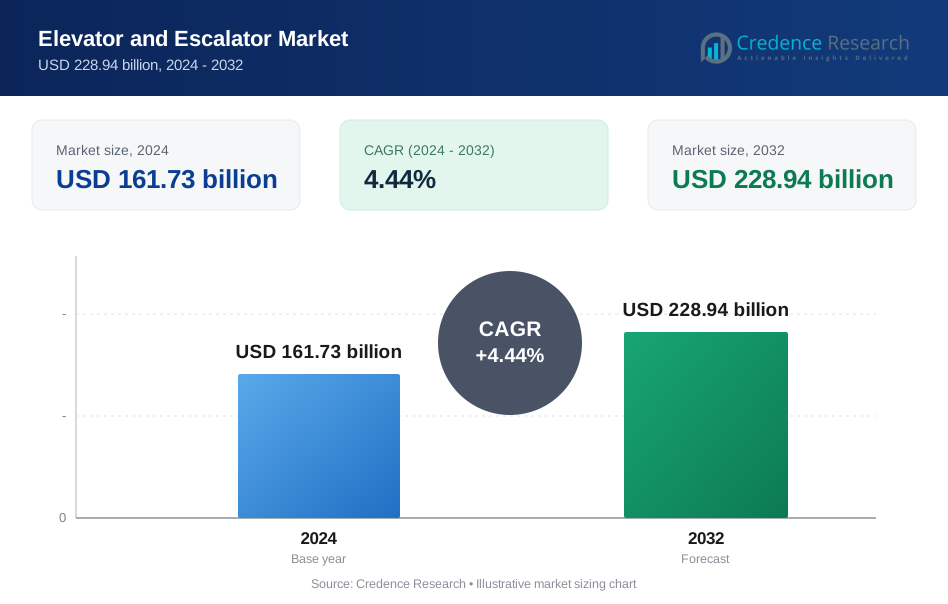
Elevator and Escalator Market size was valued USD 161.73 billion in 2024 and is anticipated to reach USD 228.94 billion by 2032, at a CAGR of 4.44% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Elevator and Escalator Market Size 2024 | USD 161.73 billion |
| Elevator and Escalator Market, CAGR | 4.44% |
| Elevator and Escalator Market Size 2032 | USD 228.94 billion |
The elevator and escalator market is dominated by established global players that include Otis, Kone, Schindler, Thyssenkrupp, Mitsubishi Electric, Hitachi, Fujitec, Hyundai Elevator, Toshiba Elevators and Building Systems, and SJEC, each leveraging strong portfolios in new installations, modernization, and digitally enabled maintenance services. These companies compete by advancing energy-efficient technologies, high-speed vertical mobility solutions, and IoT-driven predictive maintenance platforms. Asia-Pacific leads the global market with an estimated 55% share, driven by rapid urbanization, extensive high-rise residential development, and large-scale metro and airport projects across China, India, and Southeast Asia. Strong construction activity and continuous infrastructure expansion reinforce the region’s dominant position.
Market Insights
- The global elevator and escalator market reached USD 161.73 billion in 2024 and is projected to hit USD 228.94 billion by 2032 at a 4.44% CAGR, driven by rising urban density and continuous investment in vertical mobility solutions.
- Market growth is propelled by rapid infrastructure development, smart building adoption, and surging demand for energy-efficient, high-speed systems across commercial, residential, and transit segments.
- Key trends include the shift toward IoT-enabled predictive maintenance, touchless control technologies, and modernization services, with elevators holding the dominant product segment share due to high installation volumes.
- Competitive dynamics are shaped by global leaders like Otis, Kone, Schindler, Thyssenkrupp, and Mitsubishi Electric, who strengthen their positions through digital service platforms and advanced traction technologies.
- Asia-Pacific accounts for about 55% of the regional market, driven by China and India’s construction boom, while restraints include high installation costs, regulatory compliance requirements, and maintenance-intensive legacy systems.
Market Segmentation Analysis:
By Product Type:
Elevators dominate the market, accounting for over 60% of global revenue, driven by rapid urbanisation, high-rise residential development, and expanding commercial infrastructure. Their strong demand stems from improved safety standards, energy-efficient designs, and smart control systems that enhance passenger flow in dense urban environments. Escalators follow as the second-largest segment, supported by rising installations in transit hubs and shopping complexes. Moving walkways maintain a niche share, primarily in airports and large commercial spaces, where they support seamless passenger mobility.
- For instance, Azabudai Hills Mori JP Tower, Toshiba supplied 8 double-deck cabs, each rated for 34 passengers and a total load of 4,500 kg, moving at 360 m/min.
By Technology:
Traction technology leads the segment with more than 70% market share, supported by its superior energy efficiency, higher load capacity, and suitability for mid- to high-rise buildings. The adoption of regenerative drives and advanced motor systems further accelerates its demand in commercial and mixed-use towers. Machine-Room-Less (MRL) systems also grow steadily as space-saving solutions for modern buildings. Hydraulic elevators retain relevance in low-rise applications, while vacuum/pneumatic systems hold a small yet expanding share due to their eco-friendly installation and minimal maintenance needs.
- For instance, KONE’s UltraRope® carbon-fiber hoisting rope reduces the elevator moving mass. In a 500-meter travel, the rope itself weighs significantly less than a conventional steel rope, resulting in a total moving mass reduction of up to 60% (approximately 14,000 kg).
By Service:
Maintenance and repair services hold the dominant share at approximately 45–50%, driven by the expanding global installed base and mandatory safety compliance requirements. Continuous lifecycle support, predictive maintenance technologies, and remote monitoring capabilities reinforce this segment’s leadership. New installations contribute strongly as urban infrastructure, smart cities, and commercial developments grow. Modernisation services also gain traction as ageing elevator fleets in developed regions require upgrades for energy efficiency, safety enhancements, and digital control integration.
Key Growth Drivers
Rapid Urbanization and High-Rise Construction
Rapid urbanization and the expansion of high-rise residential and commercial buildings significantly drive demand for elevators and escalators. Governments worldwide continue to invest in smart cities, transit hubs, and mixed-use developments, pushing developers to adopt vertical mobility solutions to optimize space and improve accessibility. Emerging economies in Asia-Pacific contribute heavily, as urban population density rises and infrastructure projects accelerate. The need for efficient vertical transport systems within skyscrapers, metro stations, malls, and airports strengthens market growth across both new installations and modernization requirements.
- For instance, Schindler 5500 MRL elevator features a regenerative drive that achieves about 30% lower energy use compared to traditional systems. The drive uses a “Clean PowerFactor 1” design that can feed energy back into the building’s power grid.
Increasing Focus on Safety, Efficiency, and Automation
Rising safety standards and the demand for energy-efficient technologies fuel widespread adoption of advanced elevator and escalator systems. Manufacturers increasingly integrate regenerative drives, destination control systems, IoT-enabled predictive maintenance, and touchless interfaces to enhance performance and reduce operational costs. Automation-supported uptime improvements appeal strongly to building owners, especially in commercial complexes and public facilities. As end users prioritize reliability and optimized traffic flow, these innovations accelerate replacement cycles and boost modernization spending, creating steady growth across mature and developing markets.
- For instance, Fujitec’s PM gearless machine in its GLFV-D series uses a PWM converter that returns regenerated power during full-load downward travel - this reduces power consumption by about 35% compared to systems without the converter.
Expanding Infrastructure Investments Across Transport & Public Facilities
Global infrastructure expansion-particularly in metro rail networks, airports, and public transportation terminals-drives substantial demand for escalators, moving walkways, and heavy-duty elevators. Governments allocate large budgets to modernize transportation systems and improve commuter flow, requiring robust mobility solutions. New metro corridors in Asia, Europe, and the Middle East create sustained procurement cycles for high-capacity equipment. Increasing footfall in transit hubs amplifies the need for durable, low-maintenance systems, positioning escalators and moving walkways as essential assets in long-term infrastructure planning.
Key Trends & Opportunities
Adoption of IoT, Predictive Maintenance, and Smart Building Integration
The market is witnessing strong momentum in IoT-enabled monitoring systems that enhance equipment uptime and reduce service costs. Predictive maintenance uses real-time analytics to detect component wear and prevent failures, offering building owners operational savings and improved safety assurance. Integration with smart building platforms allows centralized control, energy optimization, and automated crowd management. This creates opportunities for manufacturers to offer subscription-based digital services, strengthening long-term customer relationships and differentiating portfolios in a highly competitive market.
- For instance, Hitachi’s Super HERIOS remote-intelligent observation system monitors elevator door operations at a precision of 0.1 mm, enabling detection of minute anomalies in real time.
Growing Demand for Sustainable and Energy-Efficient Solutions
Sustainability initiatives and regulatory pressure encourage adoption of green technologies such as regenerative braking, efficient traction systems, LED-based lighting, and standby modes. Building developers increasingly seek eco-friendly mobility solutions to meet green certification standards like LEED and BREEAM. Manufacturers responding with low-carbon materials and energy-saving designs gain competitive advantage. As urban centers commit to net-zero goals, demand for environmentally responsible elevators and escalators continues to rise, opening opportunities in both new installations and modernization projects.
- For instance, Otis’ Gen2® Comfort elevator supports a maximum load of 2,000 kg, travels up to 3.0 m/s, and can serve 50 stops, making it well-suited for mid-rise residential buildings.
Modernization Opportunities in Aging Infrastructure
A significant installed base of aging elevators and escalators-especially across North America, Europe, and parts of Asia-presents robust modernization opportunities. Building owners prioritize upgrades to improve energy efficiency, safety compliance, ride quality, and digital connectivity. Modernization often requires shorter installation times and lower operational disruptions, making it an attractive alternative to full equipment replacement. With safety codes tightening and asset reliability becoming mission-critical in dense buildings, modernization is emerging as one of the fastest-growing service segments globally.
Key Challenges
High Installation and Maintenance Costs
The elevator and escalator market faces cost-related challenges, as advanced technologies, premium materials, and specialized labor significantly increase capital expenditure. Building owners in developing markets often delay installations or choose lower-spec equipment due to budget constraints. Additionally, routine maintenance requires skilled technicians and expensive spare parts, increasing lifecycle costs. These financial pressures can slow adoption rates, particularly in low-income regions and smaller commercial buildings, limiting market penetration despite rising urban development.
Supply Chain Constraints and Skilled Labor Shortage
Global supply chain disruptions, fluctuating raw material prices, and component shortages affect production cycles and project timelines. Manufacturers often face delays in sourcing critical parts such as motors, controllers, and electronics, impacting delivery schedules. Additionally, the industry suffers from a persistent shortage of trained installation and maintenance professionals, especially as systems become more digital and complex. This skills gap increases service downtime, raises labor costs, and constrains the market’s ability to meet growing demand for high-performance solutions.
Regional Analysis
North America
North America holds around 20% of the global elevator and escalator market, driven by strong modernization activity across commercial buildings and public infrastructure. The United States leads demand as aging systems require upgrades to energy-efficient and connected technologies. Urban redevelopment projects, rising renovation cycles, and adoption of smart maintenance solutions support steady growth. Canada contributes through investments in residential high-rise construction and public transit expansion. The region focuses heavily on safety compliance, sustainable operations, and improved vertical mobility solutions, helping maintain a stable market position. Modernisation and repair services form a significant share of overall revenue.
Europe
Europe accounts for roughly 25% of the global market, supported by advanced regulatory standards, strong modernization needs, and consistent adoption of energy-efficient technologies. Countries such as Germany, France, Italy, and the United Kingdom drive demand through modernization of aging structures and expansion of commercial and public infrastructure. The region sees growing installation of smart elevators equipped with predictive maintenance and digital control systems. High urban density and stringent safety frameworks encourage replacement and retrofit projects. While new installations grow moderately, modernization generates the largest revenue share, maintaining Europe’s strong position in the global market.
Asia-Pacific
Asia-Pacific dominates the global elevator and escalator market with an estimated 50–60% share, driven by rapid urbanization, large-scale residential construction, and massive infrastructure investments. China remains the largest contributor, followed by India, Japan, and Southeast Asian countries. High-rise housing demand, metro rail expansion, and airport development significantly boost installation volumes. The region increasingly adopts smart, energy-efficient, and machine-room-less elevators. Growing middle-class populations and expanding commercial real estate further accelerate growth. Asia-Pacific remains the fastest-growing and most dynamic regional market, supported by continuous new-build activity and long-term modernization prospects.
Latin America
Latin America holds approximately 5–7% of the global elevator and escalator market, driven by urban growth and modernization of residential and commercial buildings. Brazil and Mexico dominate the regional demand through large population centers and infrastructure development plans. Economic recovery and investment in housing, retail, and public transportation systems are encouraging steady installation growth. The region sees rising interest in modernization services as older systems require upgrades for safety, efficiency, and reliability. Although growth is moderate compared to Asia-Pacific, Latin America shows stable long-term potential supported by urban expansion and improved building standards.
Middle East & Africa
The Middle East & Africa region captures roughly 6–8% of the global market, with demand centered in Gulf countries such as the UAE, Saudi Arabia, and Qatar. Large infrastructure projects, smart-city developments, and high-rise commercial buildings drive installations. Africa contributes through rising urban housing needs and expanding retail and hospitality sectors. Modern, energy-efficient systems and premium-grade solutions are in high demand in the Middle East, while Africa sees steady growth in basic installations. Although smaller in scale, the region is experiencing sustained investment that supports long-term market expansion.
Market Segmentations:
By Product Type:
- Elevators, Escalators
- Moving Walkways
By Technology:
- Traction
- Hydraulic
By Service:
- New Installation
- Maintenance
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the elevator and escalator market features major global players such as Toshiba Elevators and Building Systems Corporation, Hyundai Elevator Co., Ltd., Kone Corporation, SJEC Corporation, Schindler Group, Fujitec, Hitachi, Ltd., Otis Elevator Company, Mitsubishi Electric Corporation, and Thyssenkrupp AG. The elevator and escalator market remains highly dynamic, driven by continuous technological innovation, strong service capabilities, and expanding global footprints. Companies compete by enhancing product efficiency, safety, and reliability while integrating smart technologies such as IoT-enabled predictive maintenance, destination control systems, and energy-efficient traction solutions. Modernisation services form a major strategic focus as aging infrastructure across developed and emerging markets requires upgrades to meet current safety and sustainability standards. Manufacturers also strengthen competitiveness through long-term service contracts, partnerships with real estate developers, and investments in advanced manufacturing. The rise of high-density urban development and megaproject construction supports demand, pushing industry players to innovate in high-speed, machine-room-less, and eco-efficient vertical mobility systems. Overall, competition is shaped by product differentiation, digital capabilities, maintenance networks, and the ability to deliver reliable, lifecycle-focused solutions.
Key Player Analysis
- Toshiba Elevators and Building Systems Corporation
- Hyundai Elevator Co., Ltd.
- Kone Corporation
- SJEC Corporation
- Schindler Group
- Fujitec
- Hitachi, Ltd.
- Otis Elevator Company
- Mitsubishi Electric Corporation
- Thyssenkrupp AG
Recent Developments
- In August 2025, Rocket Lab boosts US investments to expand semiconductor manufacturing capacity and supply chain security for space-grade solar cells and electro-optical sensors, supported by Trump Administration award.
- In May 2025, Malaysian company SMD Semiconductor opened a new R&D Innovation Hub in Wales to collaborate with UK companies on designing next-generation semiconductor chips. The hub is co-located with the Compound Semiconductor Applications (CSA) Catapult near Newport.
- In April 2025, KONE was awarded a contract to supply 131 escalators and four autowalks for five stations on the Grand Paris Express Line 15 West. This project, which will begin operation in 2031, aims to improve commuter travel by creating a circular metro line around Paris, shortening travel times for residents in the Île-de-France region.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Technology, Service and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow steadily as urbanization accelerates and high-rise construction increases.
- Demand for smart, connected elevators using IoT and AI will rise across commercial and residential buildings.
- Modernisation of aging equipment will become a major revenue driver in both advanced and emerging markets.
- Energy-efficient and eco-friendly elevator technologies will gain strong adoption due to sustainability mandates.
- High-speed and machine-room-less elevators will see wider deployment in dense urban centers.
- Predictive maintenance solutions will replace traditional service models and improve operational efficiency.
- Infrastructure expansion in developing regions will create new installation opportunities.
- Digital twin and remote monitoring technologies will enhance safety, reliability, and lifecycle management.
- Public-sector investments in metro, airport, and institutional projects will support long-term demand.
- Competition will intensify as manufacturers focus on innovation, service offerings, and regional expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Elevator and Escalator Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Elevator and Escalator Market projected to grow between 2025 and 2032?
Which segment is expected to post the highest CAGR during the forecast period?
Which region is fueling the growth of the elevator and escalator industry?
Who are the major players in the global elevator and escalator market?
What are the major market drivers of the elevator and escalator industry?
What are the major market restraints of the elevator and escalator industry?
What are the elevator and escalator industry's primary market opportunities?
Who are the leading companies in the Elevator and Escalator Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Elevator and Escalator Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Elevator and Escalator Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 161.73 billion → 2032: USD 228.94 billion)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Elevator and Escalator Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Elevator and Escalator Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Elevator and Escalator Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Elevator and Escalator Market Drivers
- 3.3 Elevator and Escalator Market Restraints & Challenges
- 3.4 Elevator and Escalator Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Elevator and Escalator Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Elevator and Escalator Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Elevator and Escalator category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Elevator and Escalator Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Elevator and Escalator Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Elevator and Escalator. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Elevator and Escalator Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Elevator and Escalator Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Elevator and Escalator Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Elevator and Escalator (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Elevator and Escalator
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Elevator and Escalator Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Elevator and Escalator Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Elevator and Escalator Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Elevator and Escalator Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Elevator and Escalator Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Elevator and Escalator Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Elevator and Escalator Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Elevator and Escalator Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
