
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
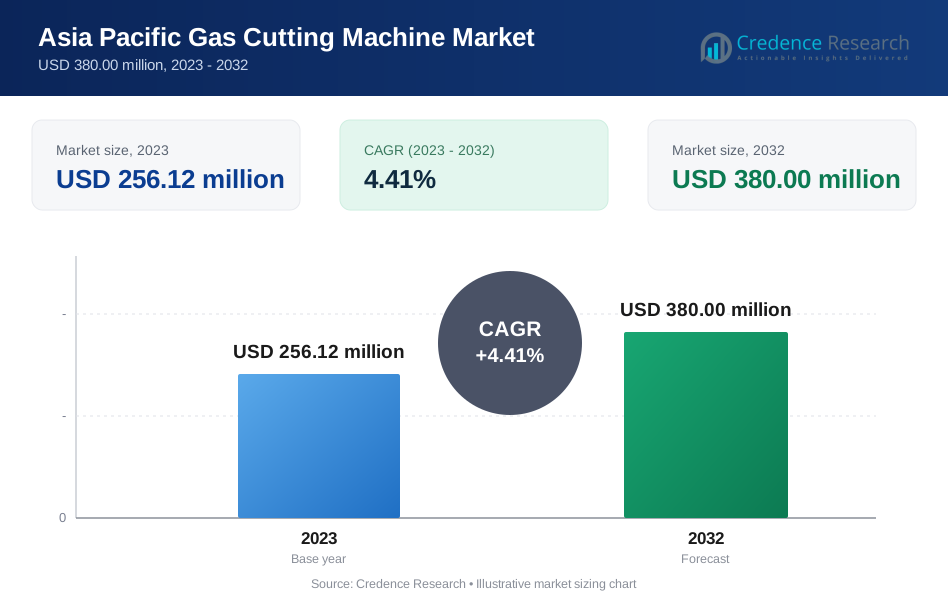
| Asia Pacific Gas Cutting Machine Market Size 2024 | USD 256.12 million |
| Asia Pacific Gas Cutting Machine Market, CAGR | 4.41% |
| Asia Pacific Gas Cutting Machine Market Size 2032 | USD 380.00 million |
Market Overview
The Asia Pacific Gas Cutting Machine Market is projected to grow from USD 256.12 million in 2023 to an estimated USD 380.00 million by 2032, with a compound annual growth rate (CAGR) of 4.41% from 2024 to 2032. This growth is driven by the increasing demand for efficient cutting tools in the manufacturing and construction sectors.
The market is influenced by several key drivers and trends. The rising need for precision and automation in cutting processes has led to the adoption of advanced gas cutting machines. Additionally, technological advancements and the integration of computer numerical control (CNC) systems are enhancing the accuracy and efficiency of these machines. The growing emphasis on safety and sustainability in industrial operations is further propelling the demand for gas cutting machines that offer safer and more environmentally friendly cutting solutions.
Geographically, China and India are the leading markets in the region, driven by their large manufacturing bases and continuous industrial growth. Japan and South Korea are also significant players, contributing to the market through their advanced technological capabilities. Key players in the Asia Pacific Gas Cutting Machine Market include Lincoln Electric Holdings, Inc., Hypertherm, Inc., and Koike Aronson, Inc. These companies are focusing on innovation and strategic partnerships to strengthen their market presence and cater to the evolving needs of customers in the region.
Market Drivers
Industrial Growth and Infrastructure Development
The Asia Pacific region is experiencing robust industrial growth and extensive infrastructure development, driving the demand for gas cutting machines. Rapid urbanization and industrialization, particularly in countries like China, India, and Southeast Asia, are leading to increased construction activities, which require efficient cutting tools. The need for gas cutting machines in various sectors, such as manufacturing, automotive, shipbuilding, and construction, is rising as these industries expand. Additionally, government initiatives aimed at boosting infrastructure and industrial capacity are further propelling market growth. The ability of gas cutting machines to provide precise and efficient cutting solutions makes them indispensable in large-scale construction projects and manufacturing processes.
Advancements in Technology and Automation
Technological advancements and the growing trend toward automation in the manufacturing sector are significant drivers of the gas cutting machine market in the Asia Pacific region. For example, ESAB displayed its three-torch Global Oxy-Fuel IR-VBA system mounted on the company's new SuprarexTM HDX heavy-duty big gantry cutting machine, suitable for extensive beveling on mild steel up to 75 mm thick. The integration of computer numerical control (CNC) systems into gas cutting machines has enhanced their precision, efficiency, and ease of operation. CNC technology allows for the automation of complex cutting tasks, reducing human error and increasing productivity. Furthermore, innovations such as plasma and laser-assisted gas cutting techniques are expanding the capabilities of traditional gas cutting machines, enabling them to cut a wider range of materials with greater accuracy. This technological evolution is not only meeting the demand for higher quality and efficiency but also addressing the need for customizable cutting solutions across various industries.
Rising Demand for Precision and Customization
The increasing emphasis on precision and customization in manufacturing processes is another key driver of the gas cutting machine market in the Asia Pacific region. Industries such as aerospace, automotive, and electronics require highly precise and complex cutting operations, which gas cutting machines are well-equipped to perform. The demand for tailored solutions that can cater to specific project requirements has led to the development of specialized gas cutting machines capable of handling intricate designs and materials. For instance, CNC profile gas cutting machines from manufacturers like Delta Engineering Works and Besttechno Dynamics enable precise cutting of metal sheets and profiles. Moreover, the growing trend of customized consumer goods, which requires precise cutting and shaping, is further boosting the demand for advanced gas cutting machines. The ability to deliver high-quality, precise cuts while maintaining efficiency is making gas cutting machines a preferred choice for manufacturers aiming to meet diverse customer needs.
Focus on Safety and Environmental Sustainability
The increasing focus on safety and environmental sustainability in industrial operations is significantly influencing the gas cutting machine market. Manufacturers are seeking cutting equipment that not only enhances operational safety but also minimizes environmental impact. For instance, Messer Cutting Systems offers the MetalMaster Xcel plasma cutting machine with advanced safety features such as a light curtain that automatically stops the machine if the light barrier is interrupted. Gas cutting machines that incorporate safety features, such as automated shut-off systems and protective enclosures, are gaining popularity. Additionally, the shift towards environmentally friendly cutting technologies, such as those that reduce emissions and energy consumption, is driving the adoption of advanced gas cutting machines. Governments and regulatory bodies in the Asia Pacific region are also implementing stricter safety and environmental regulations, prompting industries to adopt cutting machines that comply with these standards. This trend towards safer and more sustainable cutting solutions is expected to continue, further driving market growth.
Market Trends
Integration of Advanced Technologies
One of the prominent trends in the Asia Pacific Gas Cutting Machine Market is the increasing integration of advanced technologies, particularly automation and computer numerical control (CNC) systems. This trend is driven by the need for higher precision, efficiency, and versatility in cutting operations across various industries. For instance, Shibuya Corporation offers the EPOCS Hydrogen Gas Cutting System, which utilizes CNC technology to enable automated and precise control over the cutting process, allowing for intricate designs and patterns to be executed with minimal manual intervention. The adoption of CNC systems is particularly significant in industries such as automotive, aerospace, and heavy machinery, where precision and accuracy are critical. Additionally, advancements in plasma and laser-assisted gas cutting technologies are expanding the capabilities of traditional gas cutting machines, enabling them to cut a wider range of materials, including high-strength alloys and composites. Messer Cutting Systems, for example, showcases their robust Plasma Cutter unit, which offers powerful performance and flexibility in cutting, gouging, and marking various materials like steel, stainless steel, aluminum, and copper. This technological evolution is not only enhancing the performance of gas cutting machines but also reducing operational costs by minimizing waste and improving energy efficiency.
Shift Towards Environmentally Friendly Solutions
Another significant trend in the market is the growing emphasis on environmentally friendly and sustainable cutting solutions. As environmental regulations become more stringent across the Asia Pacific region, industries are increasingly adopting gas cutting machines that offer lower emissions and reduced environmental impact. Shibuya Corporation's EPOCS Hydrogen Gas Cutting System exemplifies this trend by utilizing hydrogen gas flames generated from the electrolysis of water, resulting in a low-cost and environmentally friendly cutting solution. The shift towards sustainability is being driven by both regulatory requirements and a broader industry commitment to sustainability. Manufacturers are developing gas cutting machines that utilize cleaner gases, such as hydrogen or natural gas, which produce fewer pollutants compared to traditional cutting gases like acetylene. Messer Cutting Systems introduces HyCut, a system specially developed for using hydrogen as a fuel gas, meeting modern demands for quality, productivity, and economy while significantly reducing emissions of CO2, nitrogen oxides, and dust. Additionally, innovations in gas mixing technologies are enabling more efficient use of cutting gases, further reducing environmental footprints. AAJJO, a B2B marketplace, connects businesses with manufacturers specializing in eco-friendly plasma cutting solutions that prioritize reduced emissions, energy conservation, and minimal material wastage. As industries continue to prioritize sustainable practices, the demand for environmentally friendly gas cutting machines is expected to grow, shaping the future landscape of the market.
Market Restraints and Challenges
High Initial Investment and Maintenance Costs
One of the primary restraints in the Asia Pacific Gas Cutting Machine Market is the high initial investment and ongoing maintenance costs associated with these machines. Gas cutting machines, especially those equipped with advanced features like CNC systems or laser-assisted technology, require substantial capital expenditure. This high cost can be a significant barrier for small and medium-sized enterprises (SMEs) that may lack the financial resources to invest in such equipment. Additionally, the maintenance and operation of these machines often require skilled technicians and regular upkeep, further adding to the overall cost. This financial burden can limit the adoption of advanced gas cutting machines, particularly in developing economies within the region, where cost sensitivity is higher. Consequently, this challenge affects market growth as potential customers may opt for cheaper, less advanced alternatives or second-hand equipment, which may not offer the same level of precision and efficiency.
Environmental and Safety Regulations
The stringent environmental and safety regulations prevalent in the Asia Pacific region pose another significant challenge to the gas cutting machine market. Governments and regulatory bodies are increasingly enforcing laws aimed at reducing industrial emissions and ensuring workplace safety. Gas cutting processes, particularly those involving acetylene and other traditional gases, can produce harmful emissions and pose safety risks, such as fire hazards and exposure to toxic fumes. Compliance with these regulations often requires companies to invest in additional safety equipment, training, and sometimes more expensive environmentally friendly gas alternatives. These requirements can increase operational costs and complicate the deployment of gas cutting machines, especially for businesses operating on tight budgets. Furthermore, non-compliance can result in fines, legal liabilities, and reputational damage, making it crucial for companies to adhere to these regulations. This regulatory landscape, while beneficial for environmental and safety standards, can act as a constraint on market expansion by limiting the use of traditional gas cutting methods and increasing operational complexities.
Market Segmentation Analysis
By Product Type
In-Place Gas Cutting Machines are designed for stationary operations, making them ideal for heavy industries such as shipbuilding and large-scale manufacturing. These machines offer high precision and can cut through thick materials, making them suitable for tasks requiring detailed and continuous cuts. On the other hand, Portable Gas Cutting Machines are valued for their mobility and ease of use, making them perfect for on-site operations in construction, maintenance, and repair. Their flexibility and convenience have led to widespread adoption in industries where mobility and versatility are essential.
By Application
Gas cutting machines are integral to several key industries, including automotive, aerospace and defense, industrial machinery, and other sectors such as construction, shipbuilding, and metalworking. In the automotive sector, these machines are crucial for the fabrication and assembly of components like body panels and chassis, where precision and speed are paramount. The aerospace and defense industries demand high precision and reliability, making CNC-assisted gas cutting a preferred choice for manufacturing complex components. In the industrial machinery and equipment segment, the need for robust and durable parts drives the use of gas cutting machines. Additionally, other industries rely on these machines for versatile and precise material cutting in various fabrication and assembly processes.
Segments
Based on Product Type
- In-Place Gas Cutting Machine
- Portable Gas Cutting Machine
Based on Application
- Automotive
- Aerospace and Defense
- Industrial Machinery and Equipment
- Others
Based on Type of Fuel Gas Used
- Acetylene
- Propane
- Propylene
- Natural Gas
- Others
Based on Type of Nozzle
- Acetylene Cutting Nozzle
- Liquefied Petroleum Gas (LPG) Cutting Nozzle
- Lateral Cutting Nozzle
Based on Region
- China
- India
- Japan
- South Korea
Regional Analysis
India (25%):
India holds around 25% of the market share, making it the second-largest market in the region. India's market is driven by its burgeoning construction and manufacturing sectors, particularly in automotive and industrial machinery. The government's push for infrastructure development and initiatives like "Make in India" are boosting demand for cutting machines. Additionally, the growth of small and medium-sized enterprises (SMEs) in India is contributing to the market, as these businesses seek cost-effective and efficient cutting solutions.
Japan (15%):
Japan accounts for approximately 15% of the market share, reflecting its advanced industrial base and focus on high-precision manufacturing. Japanese industries, particularly in automotive, aerospace, and electronics, demand cutting-edge technologies, including CNC and automated gas cutting machines. Japan's emphasis on quality and precision in manufacturing processes drives the adoption of sophisticated cutting equipment, positioning it as a key player in the region.
South Korea (10%):
South Korea holds about 10% of the market share, driven by its strong industrial and technological sectors. The country's focus on electronics, automotive, and shipbuilding industries generates substantial demand for gas cutting machines. South Korean manufacturers prioritize technological advancements and automation, contributing to the growth of the gas cutting machine market. Additionally, government support for industrial innovation and export-oriented manufacturing boosts the market.
Key players
- ESAB
- Haco Group
- Ador Welding Limited
- Colfax Corp.
- Esprit Automation Ltd.
- Hornet Cutting Systems
- KALTENBACH GmbH + Co. KG
- Koike Aronson Inc.
- Messer Cutting Systems Inc.
- SteelTailor
Competitive Analysis
The Asia Pacific Gas Cutting Machine Market is highly competitive, featuring prominent players such as ESAB, Colfax Corp., and Messer Cutting Systems Inc., which dominate with advanced technology and strong market presence. These companies focus on innovation, offering a range of cutting solutions including CNC systems and automated machines to cater to diverse industrial needs. Regional players like Ador Welding Limited and Koike Aronson Inc. provide competitive pricing and localized support, appealing to small and medium enterprises (SMEs). Companies like Haco Group and SteelTailor emphasize customizable solutions and aftermarket services, enhancing customer loyalty. The competition is characterized by continuous technological advancements, with a focus on automation, precision, and environmental sustainability, driving the market dynamics and fostering a landscape of rapid innovation and strategic partnerships.
Recent Developments
In January 2017, GCE Cutting & Welding Technologies introduced the Oxy-Fuel Machine Cutting Torch FIT+ two with Integrated Ignition. This innovative torch features a unique IHT height sensing system and integrated torch electronics, enabling easy connectivity to CNC systems. The FIT+ two enhances cutting precision and efficiency, meeting the growing demand for advanced cutting solutions in the market.
In June 2017, Voortman unveiled the HYPERTHERM XPR300, designed for cutting mild steel, stainless steel, and aluminum. This cutting-edge technology is available across Voortman's entire product range utilizing plasma cutting, including the V310, V304, V320, V330, V302, and V808. The HYPERTHERM XPR300 offers enhanced performance and precision, catering to diverse industrial needs.
In March 2023, ESAB launched its latest cutting solution, the Cutmaster 60i, which is a powerful and portable plasma cutter designed for heavy-duty industrial applications. This product features advanced technology for increased cutting speed and efficiency, making it suitable for a wide range of materials and thicknesses. The Cutmaster 60i is designed to meet the demands of modern industrial cutting requirements.
In July 2023, Messer Cutting Systems announced a significant software upgrade for its OmniWin 2023 software. The upgrade includes enhanced nesting algorithms, improved user interface, and advanced reporting features. This software upgrade aims to increase operational efficiency and precision in cutting processes, supporting industries in optimizing their production workflows.
In October 2023, Ador Welding Limited introduced the WeldPro 400, a state-of-the-art gas cutting machine designed for high-performance applications. The WeldPro 400 features advanced safety mechanisms, automated controls, and superior cutting capabilities. This new product aims to enhance productivity and safety in various industrial sectors, reinforcing Ador Welding Limited's position in the market.
Market Concentration and Characteristics
The Asia Pacific Gas Cutting Machine Market is moderately concentrated, characterized by the presence of several established players, such as ESAB, Messer Cutting Systems Inc., and Colfax Corp., alongside regional competitors like Ador Welding Limited and SteelTailor. This market features a blend of large multinational corporations and smaller local manufacturers, each contributing to a competitive landscape marked by innovation and technological advancements. Companies in this market focus on offering a diverse range of products, including both advanced CNC-integrated machines and cost-effective portable options, catering to various industry needs. The market is also influenced by factors such as rapid industrialization, a growing emphasis on automation, and increasing environmental and safety regulations, which drive the demand for advanced and sustainable cutting solutions.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, Type of fuel gas used, Type of Nozzle and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to witness significant technological advancements, particularly in automation and CNC integration, enhancing precision and efficiency in cutting operations.
- Continued industrialization in emerging economies like India and Southeast Asia will drive the demand for gas cutting machines, supporting infrastructure and manufacturing expansions.
- There will be a growing demand for environmentally friendly cutting solutions as industries strive to comply with stricter environmental regulations and reduce their carbon footprint.
- The market will see an expansion in application areas, including emerging industries such as renewable energy and electric vehicles, which require specialized cutting solutions.
- Manufacturers will increasingly focus on cost efficiency, offering versatile and durable gas cutting machines that cater to small and medium-sized enterprises (SMEs) seeking affordable solutions.
- The integration of smart technologies, such as IoT and AI, will enhance machine monitoring and maintenance, reducing downtime and improving operational efficiency.
- The competitive landscape will intensify with new entrants and innovations, pushing companies to continuously improve their product offerings and customer service.
- There will be a heightened demand for customizable and flexible cutting machines that can adapt to specific industry needs, including specialized materials and complex cutting tasks.
- The expansion of aftermarket services, including maintenance, training, and spare parts, will become a key differentiator for companies aiming to enhance customer loyalty and satisfaction.
- Regional market diversification will continue, with a focus on developing localized solutions to cater to the diverse industrial needs across different Asia Pacific countries, ensuring growth and market penetration.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Asia Pacific Gas Cutting Machine Market?
Which industries primarily use gas cutting machines?
What technological advancements are influencing the market?
How are environmental concerns impacting the market?
Who are the key players in the Asia Pacific Gas Cutting Machine Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Asia Pacific Gas Cutting Machine Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Asia Pacific Gas Cutting Machine Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 256.12 million → 2032: USD 380.00 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Asia Pacific Gas Cutting Machine Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Asia Pacific Gas Cutting Machine Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Asia Pacific Gas Cutting Machine Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Asia Pacific Gas Cutting Machine Market Drivers
- 3.3 Asia Pacific Gas Cutting Machine Market Restraints & Challenges
- 3.4 Asia Pacific Gas Cutting Machine Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Asia Pacific Gas Cutting Machine Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Asia Pacific Gas Cutting Machine Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Asia Pacific Gas Cutting Machine category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Asia Pacific Gas Cutting Machine Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Asia Pacific Gas Cutting Machine Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Asia Pacific Gas Cutting Machine market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Asia Pacific Gas Cutting Machine Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Asia Pacific Gas Cutting Machine Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Asia Pacific Gas Cutting Machine Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Asia Pacific Gas Cutting Machine (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Asia Pacific Gas Cutting Machine Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Asia Pacific Gas Cutting Machine Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Asia Pacific Gas Cutting Machine Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Asia Pacific Gas Cutting Machine Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Asia Pacific Gas Cutting Machine Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Asia Pacific Gas Cutting Machine Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Asia Pacific Gas Cutting Machine Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Asia Pacific Gas Cutting Machine Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Asia Pacific Gas Cutting Machine Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
