
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Asia Pacific Human Insulin Market Size 2023 | USD 6,171.90 Million |
| Asia Pacific Human Insulin Market, CAGR | 5.70% |
| Asia Pacific Human Insulin Market Size 2032 | USD 10,169.13 Million |
Market Overview
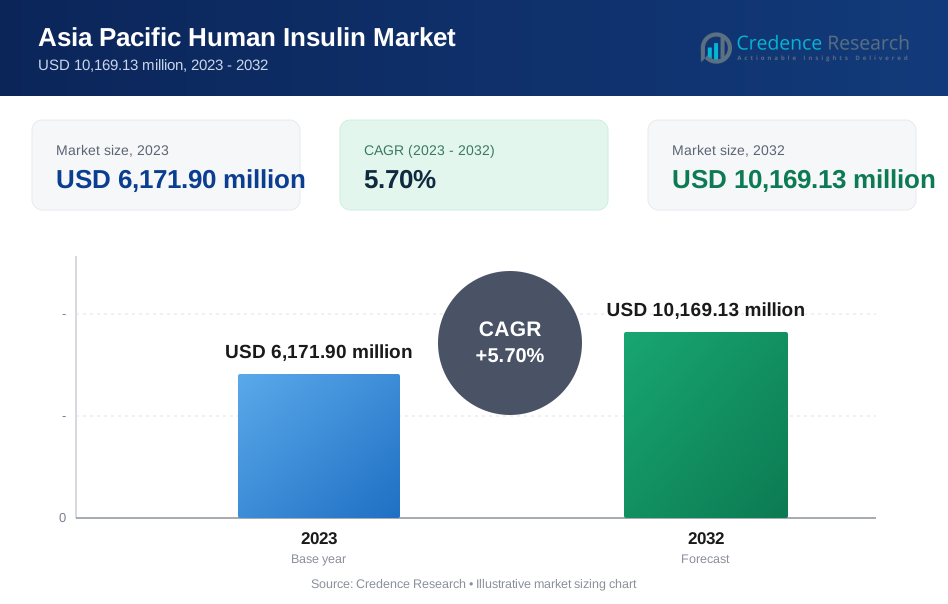
Asia Pacific Human Insulin market size was valued at USD 6,171.90 million in 2023 and is anticipated to reach USD 10,169.13 million by 2032, at a CAGR of 5.70% during the forecast period (2023-2032).
The Asia Pacific human insulin market is experiencing steady growth, driven by the rising prevalence of diabetes, particularly type 2 diabetes, across densely populated countries such as China and India. Increasing awareness of early diagnosis and insulin therapy, coupled with government initiatives aimed at improving diabetes management, continues to bolster market expansion. The growing elderly population and shifting lifestyles marked by poor dietary habits and reduced physical activity further contribute to the surge in insulin demand. Additionally, advancements in insulin delivery devices, such as insulin pens and pumps, are enhancing patient compliance and treatment outcomes. The expansion of healthcare infrastructure, especially in emerging economies, and the increasing affordability and availability of biosimilar insulin products are further shaping market trends. Strategic collaborations among pharmaceutical companies and the introduction of innovative, cost-effective therapies are also playing a key role in sustaining growth across the region.
The Asia Pacific human insulin market demonstrates significant geographical diversity, with major growth concentrated in countries such as China, India, Japan, and South Korea, while emerging economies like Indonesia, Vietnam, and the Philippines are witnessing increasing adoption due to improving healthcare infrastructure and rising diabetes awareness. Urbanization, changing lifestyles, and government initiatives across the region are fueling the demand for effective insulin therapies. Key players driving the market forward include global pharmaceutical giants such as Novo Nordisk A/S, Eli Lilly and Company, and Pfizer, alongside strong regional contributors like Biocon, Wockhardt, Tonghua Dongbao Pharmaceutical Co., and Lupin. These companies are focusing on expanding product portfolios, enhancing distribution networks, and launching affordable biosimilars to cater to a wide patient base. Strategic collaborations, R&D investments, and innovations in insulin delivery technologies continue to strengthen their market positions and support the evolving needs of diabetic populations across the Asia Pacific region.
Market Insights
- The Asia Pacific human insulin market was valued at USD 6,171.90 million in 2023 and is projected to reach USD 10,169.13 million by 2032, growing at a CAGR of 5.70%.
- The global human insulin market was valued at USD 21,000 million in 2023 and is projected to reach USD 31,208 million by 2032, growing at a CAGR of 4.50% from 2023 to 2032.
- Increasing diabetes prevalence across the region, particularly in countries like China and India, is driving significant demand for insulin products.
- The market is witnessing a shift toward biosimilars, providing more affordable insulin options and expanding patient access.
- Technological advancements in insulin delivery devices, such as insulin pens and pumps, are enhancing patient compliance and convenience.
- Strong competition exists among global giants like Novo Nordisk, Eli Lilly, and regional players like Biocon and Lupin.
- Market restraints include the high cost of insulin therapies and limited access in rural areas, hindering overall growth potential.
- Regional differences show robust growth in China, India, and Japan, while emerging markets in Southeast Asia continue to expand access to insulin.
Report Scope
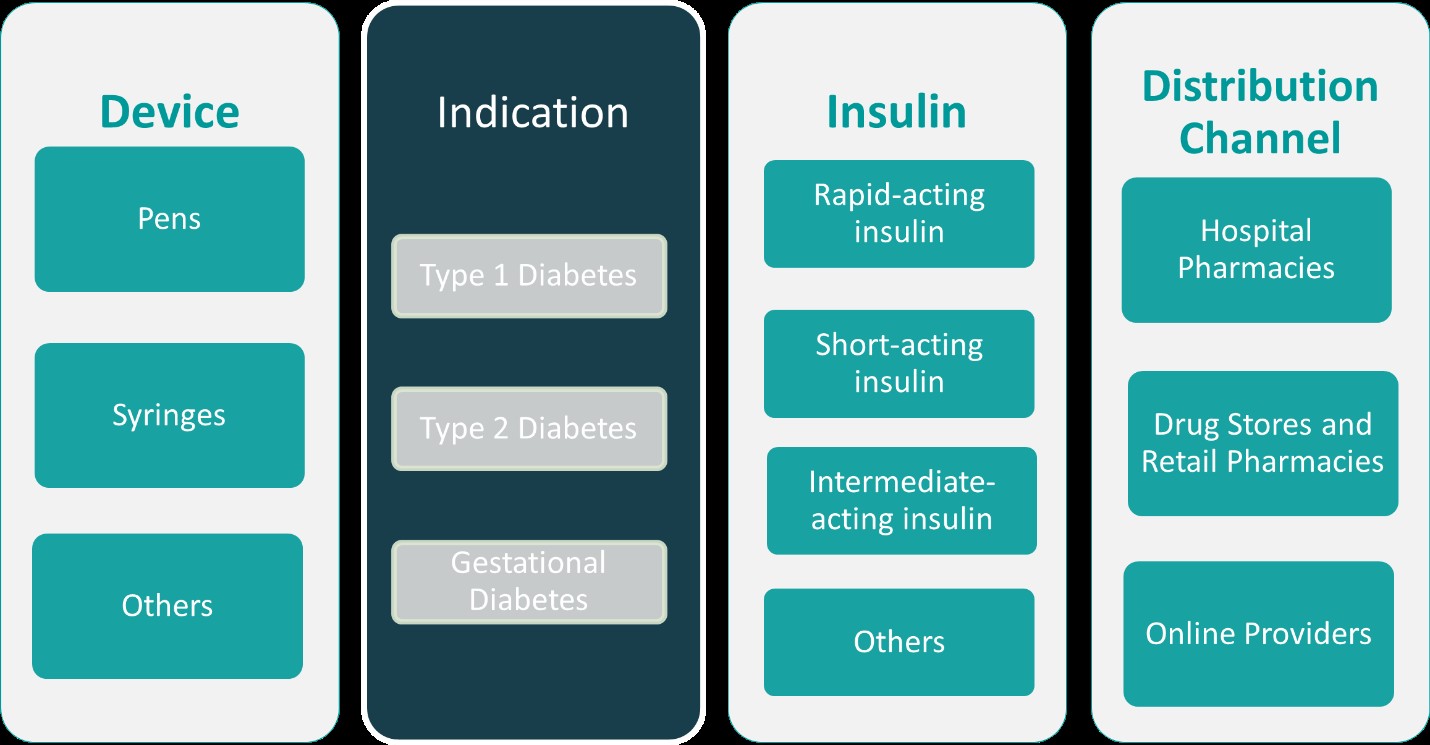
This report segments the Asia Pacific Human Insulin Market as follows:
Market Drivers
Rising Diabetes Prevalence and Aging Population
One of the primary drivers of the Asia Pacific human insulin market is the escalating prevalence of diabetes, particularly type 2 diabetes, across the region. For instance, the International Diabetes Federation estimates that Asia is home to over half of the global diabetic population. Countries like China, India, and Indonesia are witnessing a significant increase in diabetes incidence due to rapid urbanization, sedentary lifestyles, and unhealthy dietary patterns. This surge in diabetic patients has created a substantial and growing demand for effective glucose management therapies, including human insulin. Additionally, the region’s aging population contributes to the increasing diabetes burden, as age is a significant risk factor for the development of insulin resistance and type 2 diabetes.
Government Initiatives and Healthcare Policy Support
Governmental efforts and healthcare policy reforms are playing a pivotal role in shaping the human insulin market in Asia Pacific. For instance, several countries have introduced national diabetes programs focused on improving early diagnosis, patient education, and access to affordable treatment options. Subsidies for insulin and other diabetes medications, combined with public health awareness campaigns, have significantly improved insulin accessibility in rural and underdeveloped areas. Moreover, partnerships between public health agencies and private pharmaceutical firms are fostering innovation and increasing the availability of both branded and biosimilar human insulin products. These supportive policies are creating an enabling environment for market growth across urban and semi-urban areas.
Advancements in Insulin Delivery Technology
Technological innovation is another major catalyst propelling the Asia Pacific human insulin market forward. Traditional vial-and-syringe methods are gradually being replaced by more user-friendly delivery devices such as insulin pens and insulin pumps. These devices enhance treatment adherence by offering more convenient, precise, and painless delivery of insulin, especially beneficial for the elderly and pediatric populations. In addition, the integration of smart technologies—such as Bluetooth-enabled insulin pens and glucose monitoring systems—is improving patient compliance and enabling real-time data sharing with healthcare providers. These advancements not only increase patient satisfaction but also contribute to better clinical outcomes, thereby boosting the overall demand for human insulin therapies.
Rising Penetration of Biosimilars and Private Sector Engagement
The growing presence of biosimilar human insulin products in the Asia Pacific market is making insulin therapy more affordable and accessible. Several regional pharmaceutical companies are actively investing in the development and commercialization of biosimilars to cater to the rising demand and reduce dependency on imported brands. These efforts are supported by favorable regulatory frameworks that expedite biosimilar approvals while maintaining stringent quality standards. Furthermore, the private sector's increased involvement, through investments, strategic collaborations, and product launches, is expanding the competitive landscape and driving innovation. The resultant market dynamism is creating more choices for patients and healthcare providers, ultimately accelerating the adoption of human insulin across diverse socioeconomic segments.
Market Trends
Surge in Demand for Biosimilar Insulin Products
A notable trend in the Asia Pacific human insulin market is the growing adoption of biosimilar insulin products. With rising healthcare costs and increasing demand for cost-effective treatment options, biosimilars are gaining traction among both healthcare providers and patients. Several local and regional pharmaceutical companies have entered the market, offering competitively priced alternatives to branded insulin products. These biosimilars maintain comparable efficacy and safety profiles, making them attractive for national health systems seeking to expand access to insulin therapy. Regulatory frameworks in countries such as India, China, and South Korea are evolving to support the development and faster approval of biosimilars, further accelerating their integration into mainstream diabetes care.
Technological Advancements in Insulin Delivery Systems
The Asia Pacific market is witnessing significant technological progress in insulin delivery systems, transforming the patient experience and improving adherence to treatment. For instance, Medtronic has solidified its dominance in the Asia Pacific market by continuously innovating and enhancing its technology for insulin users. Traditional insulin administration methods are being replaced by more sophisticated solutions such as prefilled insulin pens, insulin pumps, and smart injection devices. These innovations offer greater accuracy, ease of use, and convenience, particularly for the elderly and children who require simpler dosing mechanisms. The integration of digital health technologies, including mobile apps and Bluetooth-enabled insulin pens, allows real-time monitoring and personalized dosing recommendations. This convergence of medical devices and digital platforms is fostering a more patient-centric approach, which is expected to gain momentum in the coming years.
Increased Focus on Preventive Healthcare and Early Diagnosis
Preventive healthcare and early diagnosis of diabetes are becoming central to national health strategies across Asia Pacific. For instance, the International Diabetes Federation (IDF) reports that there are roughly 537 million diabetes patients aged between 20 and 79 years, with projections indicating a significant increase by 2045. Governments and non-profit organizations are launching large-scale screening programs, awareness campaigns, and community outreach initiatives to promote early detection and better management of diabetes. As a result, more individuals are being diagnosed at earlier stages, leading to an uptick in the initiation of insulin therapy. This trend is also prompting pharmaceutical companies to expand their market reach into semi-urban and rural areas, where awareness and access have historically been limited. Early diagnosis combined with timely intervention is driving sustained demand for human insulin.
Expanding Role of Local Manufacturers and Strategic Collaborations
Local manufacturers are playing an increasingly influential role in shaping the Asia Pacific human insulin market. These companies are not only addressing affordability challenges but also contributing to regional self-sufficiency in insulin production. Strategic partnerships between local and global firms are becoming more common, aiming to co-develop innovative insulin formulations and improve distribution networks. Collaborative efforts between industry stakeholders, research institutions, and healthcare providers are also facilitating technology transfer and product localization. This regionalization of production and distribution is expected to enhance supply chain resilience and meet the growing demand more efficiently.
Market Challenges Analysis
High Cost of Insulin Therapy and Limited Access in Rural Areas
Despite growing demand and government efforts, the high cost of insulin therapy remains a significant barrier for many patients across the Asia Pacific region. For instance, research indicates that more than half of those who need insulin globally still cannot afford or access it due to high costs. Branded insulin products, especially analog variants, are often priced beyond the reach of low-income populations. Even though biosimilars offer a more affordable alternative, their market penetration is still limited in several countries due to regulatory hurdles and lack of awareness. In rural and remote areas, access to consistent insulin supply, refrigeration for storage, and trained healthcare professionals is often inadequate. These infrastructural and economic challenges hinder the timely initiation and continuation of insulin therapy, especially among underserved populations, ultimately affecting diabetes outcomes.
Regulatory Complexities and Supply Chain Disruptions
The Asia Pacific human insulin market also faces challenges stemming from complex and inconsistent regulatory environments across different countries. Varying standards for product approval, clinical trials, and biosimilar equivalency create difficulties for manufacturers looking to expand across borders. These inconsistencies not only delay market entry but also increase development and compliance costs. Moreover, disruptions in global and regional supply chains—exacerbated by geopolitical tensions, pandemics, and logistics inefficiencies—have highlighted the vulnerability of insulin distribution systems. Interruptions in raw material supply and manufacturing operations can result in insulin shortages, adversely impacting patient care. Addressing these regulatory and logistical hurdles is essential for ensuring a stable, equitable, and scalable insulin supply across the region.
Market Opportunities
The Asia Pacific human insulin market presents substantial opportunities driven by the rapid expansion of healthcare infrastructure and growing investments in chronic disease management. Emerging economies such as India, China, Vietnam, and the Philippines are witnessing increased healthcare spending, both from government and private sectors, enabling broader access to insulin therapies. Urbanization, coupled with a rise in lifestyle-related diseases, has led to a larger diabetic population that demands sustained and effective treatment solutions. As awareness around diabetes prevention and treatment grows, there is an increasing inclination toward early diagnosis and proactive disease management, fostering long-term demand for human insulin. Additionally, the continued rollout of universal healthcare schemes and subsidized drug programs across several countries is expanding patient reach and creating favorable conditions for insulin manufacturers.
Another key opportunity lies in the development and adoption of innovative delivery systems and digital health technologies tailored to the needs of local populations. Smart insulin pens, wearable devices, and mobile-based diabetes management platforms are opening new avenues for personalized, efficient treatment solutions that can significantly enhance patient adherence and clinical outcomes. Moreover, the production and commercialization of biosimilar insulin products by regional pharmaceutical companies offer a scalable solution to affordability concerns while reducing dependency on imports. This creates an attractive environment for foreign direct investments and strategic collaborations aimed at technology transfer and market expansion. As regulatory frameworks across the region continue to mature and align with international standards, they are expected to facilitate faster approval and market entry of next-generation insulin products, positioning Asia Pacific as a key growth engine in the global insulin market.
Market Segmentation Analysis:
By Device:
- Pens
- Syringes
- Others
By Indication:
- Type 1 Diabetes
- Type 2 Diabetes
- Gestational Diabetes
Segments:
Based on Device:
- Pens
- Syringes
- Others
Based on Indication:
- Type 1 Diabetes
- Type 2 Diabetes
- Gestational Diabetes
Based on Insulin:
- Rapid-acting insulin
- Short-acting insulin
- Intermediate-acting insulin
- Others
Based on Distribution Channel:
- Hospital Pharmacies
- Drug Stores and Retail Pharmacies
- Online Providers
Based on the Geography:
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
Regional Analysis
China
China, accounting for the largest share of the Asia Pacific human insulin market at approximately 30%, remains the dominant regional player due to its massive diabetic population and continued government investment in healthcare infrastructure. The country has seen increased awareness around diabetes management, supported by extensive public health campaigns and national screening programs. Local production of biosimilar insulin has also accelerated, reducing costs and increasing accessibility, especially in second- and third-tier cities. China's ongoing reforms in healthcare reimbursement and drug procurement are improving patient access to both traditional and analog insulin types. As urbanization and sedentary lifestyles continue to contribute to rising diabetes prevalence, China's demand for insulin is expected to maintain a strong upward trajectory.
India
India follows closely, capturing around 18% of the regional market. The country’s growing middle class, increasing diabetes prevalence, and improvements in diagnostic infrastructure are fueling market expansion. While human insulin dominates the public health sector due to affordability, insulin analogs are gradually gaining traction in private healthcare settings. The government's efforts to subsidize diabetes care through programs like Ayushman Bharat are broadening access to essential treatments. Furthermore, India's strong pharmaceutical manufacturing base enables domestic production of cost-effective biosimilar insulin, which is widely distributed both locally and to other developing markets. The combination of policy support, patient outreach, and private sector innovation positions India as a rapidly growing insulin market within the region.
Japan and South Korea
Japan and South Korea, together, contribute around 22% of the regional market share. Both countries have highly developed healthcare systems and high per capita healthcare expenditure, leading to widespread adoption of advanced insulin analogs and innovative delivery technologies like insulin pens and pumps. Japan’s aging population, coupled with a well-established reimbursement framework, has created a mature insulin market focused on therapeutic efficiency and convenience. Similarly, South Korea benefits from strong regulatory support, high awareness, and government programs that emphasize disease prevention and management, making it a key growth center for premium insulin products.
Rest of Asia Pacific
The Rest of Asia Pacific, including Australia, Thailand, Indonesia, Vietnam, Malaysia, the Philippines, and Taiwan, accounts for the remaining 30% of the market. While market maturity varies across these countries, common growth drivers include increasing diabetes incidence, improved healthcare access, and rising investments in public health initiatives. Australia, with its robust healthcare policies, is leaning toward high-end insulin therapies, whereas Southeast Asian nations are focusing on affordability and access. Multinational companies are expanding their footprint in these emerging markets through partnerships and biosimilar launches, supporting long-term growth potential across the broader Asia Pacific region.
Key Player Analysis
- Novo Nordisk A/S
- MannKind Corporation
- Pfizer
- Wockhardt
- Biocon
- Lupin
- Tonghua Dongbao Pharmaceutical Co.
- Eli Lilly and Company
Competitive Analysis
The Asia Pacific human insulin market is highly competitive, with key players vying for dominance in both developed and emerging economies. Leading global players such as Novo Nordisk A/S, Eli Lilly and Company, and Pfizer continue to hold substantial market share due to their strong brand recognition, extensive distribution networks, and wide product portfolios. These companies are focusing on expanding their insulin offerings with both traditional human insulin and innovative analogs to meet the growing demand for diabetes management solutions across the region. These companies continue to invest heavily in research and development to bring innovative insulin formulations and delivery systems to market, catering to the diverse needs of diabetic patients across the region. In addition to multinational companies, regional players are gaining traction by focusing on cost-effective solutions, such as biosimilar and generic insulin products. These players leverage local manufacturing capabilities and strong distribution channels to offer more affordable alternatives, making insulin therapies more accessible to a wider population. Strategic collaborations, partnerships, and acquisitions are common in the market, enabling both global and local firms to expand their reach and enhance their product offerings. Furthermore, advancements in insulin delivery technologies, such as prefilled insulin pens and smart insulin pumps, are playing a crucial role in differentiating products and driving patient adherence. The competitive landscape is also influenced by regulatory environments, pricing pressures, and shifting consumer preferences, as healthcare systems across the region prioritize cost-effective diabetes management solutions. This dynamic environment requires players to continuously innovate and adapt to meet the evolving demands of the Asia Pacific market.
Recent Developments
- In April 2025, Novo Nordisk announced the discontinuation of Human Mixtard, India’s largest-selling human insulin brand, as part of a global strategy to prioritize newer, patented diabetes and weight loss therapies such as Ozempic and Wegovy. While vial forms of Mixtard, Actrapid, and Insulatard will remain available, pen devices (Penfills and FlexPens) are being phased out, which is expected to disrupt patient access and preference in India.
- In April 2025, Pfizer discontinued the development of danuglipron, its once-daily oral GLP-1 receptor agonist for obesity and type 2 diabetes, following a case of drug-induced liver injury and after reviewing clinical and regulatory feedback. This decision halts further clinical development for both obesity and diabetes indications.
- In March 2025, Biocon Biologics entered a strategic collaboration with Civica, Inc. to expand access to Insulin Aspart in the United States. Biocon will supply the drug substance, which Civica will formulate and commercialize after completing development and clinical trials.
- In December 2024, Lupin acquired the Huminsulin® portfolio in India from Eli Lilly and Company. The range includes Insulin Human (Huminsulin R, NPH, 50/50, and 30/70) and is indicated for type 1 and type 2 diabetes. Lupin had previously marketed these products under a distribution agreement, and the acquisition is aimed at strengthening its diabetes portfolio.
- In November 2024, MannKind’s Afrezza® (insulin human) Inhalation Powder received approval from India’s CDSCO. MannKind expects to ship product to its partner Cipla by the end of 2025.
- In October 2024, Wockhardt filed for approval of its fast-acting insulin analog, Aspart injection (ASPARAPID™), with the Drugs Controller General of India (DCGI). The product, developed indigenously, will be offered in cartridges, vials, and prefilled disposable pens. This expands Wockhardt’s diabetes biosimilars portfolio and addresses a market with limited competition.
Market Concentration & Characteristics
The Asia Pacific human insulin market is moderately concentrated, with a few dominant global players and numerous regional competitors shaping its landscape. Major companies like Novo Nordisk, Eli Lilly, and Pfizer control a significant share of the market due to their established product portfolios, strong brand presence, and extensive distribution networks. These industry leaders focus on both branded insulin and biosimilar products to cater to a broad range of consumers. However, the market also features regional players such as Biocon, Lupin, and Tonghua Dongbao Pharmaceutical Co., which have been able to capitalize on the demand for cost-effective insulin therapies, especially in emerging markets. The market is characterized by a strong focus on innovation in insulin delivery systems, including prefilled pens and insulin pumps, as well as a growing shift toward biosimilars to increase affordability. Regulatory support, strategic collaborations, and local production capacity continue to play crucial roles in determining market dynamics.
Report Coverage
The research report offers an in-depth analysis based on Device, Indication, Insulin, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for human insulin in Asia Pacific will continue to rise due to the increasing prevalence of diabetes and an aging population.
- Government initiatives aimed at improving diabetes care and affordability will expand access to insulin therapies, especially in underserved areas.
- The adoption of biosimilar insulin products will grow as they provide more affordable alternatives to branded insulin, addressing cost concerns.
- Technological advancements in insulin delivery devices, such as smart pens and pumps, will enhance patient compliance and treatment efficiency.
- Growing healthcare infrastructure in emerging markets will drive insulin demand, with improvements in diagnostics and treatment accessibility.
- The rising focus on preventive healthcare will contribute to early diabetes detection and early-stage insulin therapy initiation.
- Increased competition among global and regional insulin manufacturers will lead to greater product diversification and improved therapeutic options.
- The development and commercialization of long-acting insulin formulations and combination therapies will offer more effective and convenient treatment options.
- Expanding partnerships between multinational pharmaceutical companies and local manufacturers will enhance supply chains and expand market reach.
- Regulatory frameworks across the region will continue to evolve, ensuring faster approval processes for new insulin products and improving overall market stability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Asia Pacific Human Insulin?
What factors are driving the growth of the Asia Pacific Human Insulin?
What are the key segments within the Asia Pacific Human Insulin?
What are some challenges faced by the Asia Pacific Human Insulin?
Who are the major players in the Asia Pacific Human Insulin?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Asia Pacific Human Insulin Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Asia Pacific Human Insulin Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 6,171.90 million → 2032: USD 10,169.13 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Asia Pacific Human Insulin Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Asia Pacific Human Insulin Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Asia Pacific Human Insulin Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Asia Pacific Human Insulin Market Drivers
- 3.3 Asia Pacific Human Insulin Market Restraints & Challenges
- 3.4 Asia Pacific Human Insulin Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Asia Pacific Human Insulin Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Asia Pacific Human Insulin Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Asia Pacific Human Insulin category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Asia Pacific Human Insulin Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Asia Pacific Human Insulin Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Asia Pacific Human Insulin market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Asia Pacific Human Insulin Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Asia Pacific Human Insulin Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Asia Pacific Human Insulin Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Asia Pacific Human Insulin (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Asia Pacific Human Insulin Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Asia Pacific Human Insulin Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Asia Pacific Human Insulin Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Asia Pacific Human Insulin Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Asia Pacific Human Insulin Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Asia Pacific Human Insulin Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Asia Pacific Human Insulin Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Asia Pacific Human Insulin Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Asia Pacific Human Insulin Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
