
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Asset Performance Management (APM) market Size 2024 | USD 2.74 billion |
| Asset Performance Management (APM) market, CAGR | 9.54% |
| Asset Performance Management (APM) market Size 2032 | USD 5.67 billion |
Market Overview:
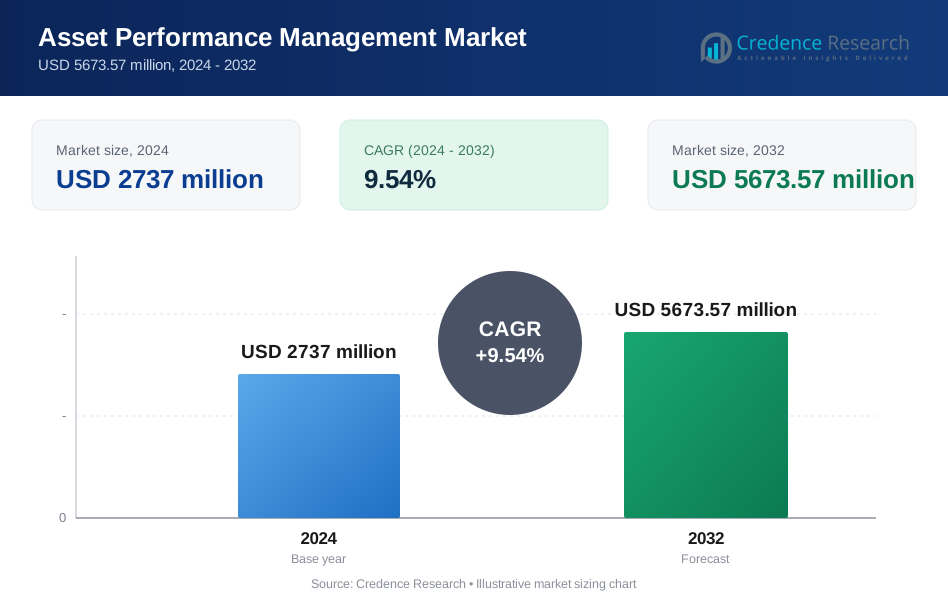
The Asset Performance Management (APM) market is projected to grow from approximately USD 2.74 billion in 2024 to USD 5.67 billion by 2032, reflecting a compound annual growth rate (CAGR) of 9.54%.
This growth is primarily driven by the increasing demand for operational efficiency and the integration of Industry 4.0 technologies. Key factors contributing to this trend include a heightened focus on predictive maintenance, which aims to minimize downtime and reduce operational costs, as well as the adoption of advanced analytics and IoT technologies for improved asset monitoring and performance.
The rise of smart infrastructure and digital twins is also significant, as these innovations provide real-time insights that enhance decision-making processes. Furthermore, regulatory pressures related to compliance and environmental sustainability are compelling organizations to adopt APM solutions. Emerging trends, particularly AI-driven predictive analytics and cloud-based platforms, are reshaping the market landscape, offering scalable and flexible solutions to meet the evolving demands of various industries.
Geographically, the APM market exhibits notable diversity, with North America, Europe, and Asia-Pacific identified as key growth regions. North America leads the market due to early technological adoption and substantial investments in infrastructure. Europe follows, motivated by stringent regulations and a commitment to operational efficiency. Meanwhile, Asia-Pacific is experiencing rapid industrialization and urbanization, presenting significant growth opportunities.
Prominent players in the APM market, such as GE Digital, IBM, and ABB Ltd., are leveraging advanced analytics and IoT technologies to enhance asset reliability and performance across multiple sectors. Overall, the APM market is characterized by its dynamic growth, driven by technological advancements and increasing industrial demands for efficient asset management solutions.
Market Drivers:
Technological Advancements:
The integration of advanced technologies such as IoT sensors and AI continues to transform asset performance management. For instance, in 2024, companies leveraging predictive maintenance technologies have achieved a 20% reduction in maintenance costs and a 25% increase in asset uptime. These technologies provide real-time monitoring and data-driven insights, enabling more proactive and efficient asset management.
Increasing Demand for Operational Efficiency:
The increasing demand for operational efficiency is a critical focus for businesses aiming to remain competitive in a rapidly evolving market. In 2024, organizations that adopt advanced asset management practices are expected to see a 15% improvement in overall equipment effectiveness (OEE). This enhancement in OEE not only boosts productivity but also significantly reduces operational costs, underscoring the importance of optimizing asset management strategies. To achieve these improvements, businesses are leveraging various strategies. Key among them is the integration of Intelligent Automation (IA) and Artificial Intelligence (AI), which streamline workflows and enhance decision-making capabilities. These technologies allow organizations to automate repetitive tasks while also handling complex processes, thereby improving efficiency across operations.
Regulatory Compliance Pressure:
As regulatory requirements evolve, companies face increasing pressure to comply with industry standards. Effective asset performance management is crucial for meeting these standards. For instance, firms that focused on regulatory adherence in 2024 have experienced up to a 30% reduction in compliance-related fines and penalties. This emphasis on compliance not only mitigates financial risks but also fosters a culture of accountability within asset management practices.
Focus on Sustainability:
The emphasis on sustainability is growing, driven by both regulatory pressures and corporate responsibility goals. In 2024, companies that adopt energy-efficient asset management practices have reported a 10% reduction in energy consumption and a 12% decrease in carbon emissions. This trend reflects global efforts to reduce environmental impact and enhances the value proposition of asset management initiatives.
Market Trends:
Enhanced Use of Predictive Analytics:
The integration of predictive analytics in asset performance management is significantly transforming the industry. For instance, in 2024, companies that have adopted predictive maintenance solutions have seen a 30% reduction in unplanned downtime. Predictive analytics uses historical data and machine learning algorithms to forecast potential equipment failures before they occur. This proactive approach not only minimizes operational disruptions but also extends asset lifespan and optimizes maintenance schedules. The increasing reliance on these advanced analytics tools underscores their growing importance in improving asset performance and operational efficiency.
Shift Away from Cash:
Another trend is the shift of investors away from cash as yields plateau. For instance, companies like Nike, Mattel, PayPal, Cisco, Levi Strauss, and UPS have announced layoffs in recent weeks, indicating a shift in their financial strategies. Furthermore, non-banking U.S. firms have increased their hoards of cash, reaching $6.9 trillion, an amount larger than the GDP of all but two countries2. Asset managers are developing new products or tweaking existing ones to compete effectively across a range of different needs. Income-generating products that replace and augment the stable cash flows created by tightening rates are favored by those in or nearing retirement. Active fixed income management is also seeing a revitalization, appealing to investors looking to diversify into non-equity sources of alpha.
Surge in Insurance Asset Management:
The APM market is also seeing a surge in the adoption of insurance asset management. According to the 13th annual Global Insurance Survey by Goldman Sachs Asset Management, insurers are adjusting to higher rates, preparing for elections, and grappling with global conflict with a risk-on mindset-from investing in alternatives to using Artificial Intelligence for risk underwriting. Alternative managers are pursuing different strategies to enter this industry, whether it be buying insurance platforms outright, investing in and then managing sidecar assets, or enhancing their operating model infrastructure to better service insurers. This includes offering holistic outsourced chief investment officer (OCIO) solutions. For example, insurers’ investments in 2024 are expected to be driven by a combination of evolving regulations and a pivot to rising rates.
Rising Adoption of Digital Twins Technology:
The use of digital twins' technology is on the rise, enhancing asset performance management by creating virtual replicas of physical assets. In 2024, the market for digital twins in asset management has grown by approximately 25%. This technology enables real-time monitoring, simulation, and optimization of asset performance through virtual models. For instance, organizations utilizing digital twins have reported a 20% improvement in asset reliability and a 15% reduction in maintenance costs. By integrating digital twins, companies can better predict and manage asset behavior, leading to more informed decision-making and strategic planning.
Market Challenges Analysis:
Integration with Legacy Systems:
A major challenge in Asset Performance Management (APM) is integrating new APM solutions with existing legacy systems. Many organizations rely on outdated technology and infrastructure that may not seamlessly interface with modern APM platforms. This integration difficulty can lead to disruptions in operations, data inconsistencies, and increased costs associated with system upgrades or custom interfaces. To overcome this challenge, organizations must carefully plan the integration process, often requiring significant investment in both time and resources. Engaging with experienced IT consultants and leveraging middleware solutions can facilitate smoother integration, but these approaches can add complexity and cost to the implementation process.
Data Management and Analytics:
Effective asset performance management heavily relies on accurate and comprehensive data. However, organizations often face challenges related to data quality, consistency, and volume. Inaccurate or incomplete data can undermine the effectiveness of APM tools, leading to unreliable performance insights and poor decision-making. To address these issues, organizations need robust data governance frameworks and advanced analytics capabilities. Implementing data validation protocols, investing in high-quality data collection tools, and leveraging sophisticated analytics platforms can help improve data accuracy and insights. Furthermore, ensuring that staff are well-trained in data management and analysis is crucial for maximizing the value derived from APM systems and enhancing overall asset performance.
Organizational Resistance to Change:
Another significant restraint is the resistance to change within organizations. Implementing APM strategies often requires a cultural shift and the re-evaluation of existing processes and roles. Employees may be hesitant to adopt new technologies or methodologies, especially if they are not adequately trained or if the benefits of change are not clearly communicated. This resistance can slow down the implementation of APM systems and diminish their potential impact on asset performance.
Budget Constraints and Economic Pressures:
Economic factors also play a crucial role in the APM market. Budget constraints can limit the ability of organizations to invest in advanced APM tools and technologies. During economic downturns, companies may prioritize immediate operational needs over long-term asset management strategies, leading to underinvestment in APM initiatives. This situation can result in a backlog of necessary upgrades and maintenance, ultimately affecting asset reliability and performance.
Market Segmentation Analysis:
By Component:
In the asset performance management (APM) market, segmentation by component reveals critical areas of focus and growth opportunities. Key components include software solutions, hardware systems, and services. Software solutions, such as predictive analytics and asset management platforms, are central to APM, as they enable real-time monitoring, data analysis, and performance optimization. Hardware systems, including sensors and data acquisition devices, support these software solutions by providing the necessary data inputs. Additionally, services such as consulting, implementation, and maintenance contribute significantly to the market, helping organizations effectively deploy and leverage APM technologies. Analyzing component-based segmentation allows companies to identify trends and opportunities for innovation within each segment, enhancing their strategic positioning and product development efforts.
By Deployment Type:
Segmentation of the asset performance management market by deployment type highlights distinct preferences and operational considerations. Deployment types include on-premises, cloud-based, and hybrid solutions. Cloud-based deployments are increasingly favored due to their scalability, lower upfront costs, and ease of access from various locations. On-premises deployments, while less flexible, offer enhanced control and data security, making them suitable for industries with stringent regulatory requirements. Hybrid solutions combine elements of both cloud and on-premises approaches, offering a balance between flexibility and control. Understanding these deployment preferences allows companies to tailor their offerings and strategies to meet the specific needs of different sectors and organizational requirements
Segmentation:
Based on Component:
- Solutions
- Asset Strategy Management
- Asset Reliability Management
- Predictive Asset Management
- Services
- Professional Services
- Support & Maintenance
- Implementation & Integration
- Consulting
- Managed Services
Based on Deployment Type:
- On-premises
- Cloud
Based on Organization Size:
- Large Enterprises
- SMEs
Based on Vertical:
- Energy & Utilities
- Manufacturing
- Government & Defense
- Chemicals
- Telecommunications
- Healthcare & Pharmaceuticals
- Consumer Goods, Food & Beverages
Based on Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
In North America, the asset performance management (APM) market is thriving due to the region's advanced industrial base and strong focus on technological innovation. The United States and Canada lead in adopting APM solutions, driven by the need for enhanced operational efficiency, reduced downtime, and maintenance cost savings across industries such as manufacturing, energy, and utilities. The presence of major APM solution providers and a mature technology ecosystem further bolster market growth. Additionally, the integration of Internet of Things (IoT) and artificial intelligence (AI) in asset management practices supports the development of sophisticated solutions. North America's emphasis on digitization and data-driven decision-making positions the region as a key player in the global APM market.
Europe
In Europe, the asset performance management market is expanding due to the region's commitment to industrial modernization and sustainability. Key countries such as Germany, the United Kingdom, and France are at the forefront of adopting APM solutions to improve asset reliability and operational efficiency. European industries, including manufacturing, energy, and transportation, are increasingly implementing APM technologies to comply with stringent regulatory requirements and enhance environmental performance. The European Union's focus on Industry 4.0 and smart manufacturing initiatives drives demand for advanced APM solutions. The region's diverse industrial landscape and regulatory environment create both opportunities and challenges, prompting companies to tailor their offerings to meet specific regional needs and standards.
Asia Pacific
The Asia Pacific region is poised for significant growth in the Asset Performance Management (APM) market, driven by several key factors that enhance its attractiveness to investors and businesses alike. The Asia Pacific region is experiencing rapid industrialization, particularly in countries like China and India. This growth is accompanied by urbanization, which necessitates the efficient management of assets across various sectors, including manufacturing, energy, and transportation. As industries expand, the need for effective asset management solutions becomes critical to ensure operational efficiency and minimize downtime. Governments across the Asia Pacific are heavily investing in infrastructure projects to support economic growth. Initiatives such as China's Belt and Road Initiative and India's National Infrastructure Pipeline are expected to create substantial demand for APM solutions. These projects require robust asset management to optimize resources and ensure timely project completion, further driving the adoption of APM technologies.
Key Players:
- AVEVA
- SAP
- GE Digital
- IBM
- ABB
- Emerson
- Bentley Systems
- Rockwell Automation
- Fluke
- DNV
Competitive Analysis:
In the asset performance management (APM) market, competition is robust, driven by the need for advanced analytics and operational efficiency. Leading companies such as IBM, Siemens, and GE Digital are prominent players, offering comprehensive APM solutions that leverage artificial intelligence and machine learning to optimize asset performance and reduce downtime. These industry leaders focus on integrating their APM platforms with existing enterprise systems and providing scalable solutions across various industries. Additionally, emerging players are introducing innovative, specialized solutions that cater to niche markets and specific operational challenges. The competitive landscape is marked by continuous advancements in technology, strategic alliances, and a strong emphasis on delivering actionable insights that enhance asset management capabilities and operational excellence.
Recent Developments:
- In January 2023, Schneider Electric acquired AVEVA. This deal would enable both the entities to have a holistic approach to digital transformation across industrial operations, while reducing energy, carbon, and resource intensity. While AVEVA will henceforth be wholly owned and part of Schneider Electric, it is intended that AVEVA’s business autonomy and future R&D investment will be preserved going forward, thereby helping to meet increasing demand for a stronger portfolio of solutions.
- April 2023, Cognite AS introduced the 2.0 version of APM software Cognite Maintain, Cognite InField, and Cognite InRobot to increase its use case applications across industries. The new solutions are powered by artificial intelligence and digitally capture asset quality observations.
- November 2023: ABB launched ABBability SmartMaster, a complete asset performance management platform for validation and condition monitoring of field devices and equipment in water, wastewater, oil & gas, chemical, and other industries. SmartMaster remotely collects, analyzes, and validates diagnostic data from instruments without interrupting the ongoing measurement tasks.
- October 2023: Oracle NetSuite introduced NetSuite Enterprise Performance Management (EPM) to help companies further integrate and automate their financial operations. NetSuite EPM integrates enterprise-wide planning, forecasting, budgeting, account reconciliation, closing, and reporting processes to increase business visibility, improve decision-making, and drive growth.
Market Concentration & Characteristics:
Market concentration and characteristics significantly impact asset performance in market management. High market concentration often indicates fewer players with larger market shares, potentially leading to higher pricing power and profitability for dominant firms. Conversely, lower concentration suggests a more competitive landscape, which can drive innovation and efficiency but may also compress margins. Key characteristics such as market volatility, liquidity, and regulatory environment further influence asset performance, dictating investment strategies and risk management practices. Analyzing these factors helps managers optimize portfolios, ensuring alignment with market dynamics and investor goals.
Report Coverage:
The research report offers an in-depth analysis based on Component, Deployment type, Organization size, Vertical and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- APM solutions will increasingly leverage AI and machine learning to enhance predictive analytics, improving decision-making and operational efficiency.
- The adoption of IoT technologies will facilitate real-time asset monitoring, enabling organizations to proactively manage asset performance and reduce downtime.
- Companies will prioritize sustainable asset management practices, integrating Environmental, Social, and Governance (ESG) criteria into their APM strategies to meet regulatory demands and corporate responsibility goals.
- With rising concerns about data privacy, APM solutions will incorporate advanced security measures, including blockchain technology, to protect sensitive asset data.
- Providers will offer more tailored APM solutions to meet the specific needs of different industries, enhancing user experience and effectiveness.
- The shift towards cloud computing will drive the demand for cloud-based APM solutions, offering scalability and flexibility to organizations.
- Industry players will increasingly engage in partnerships and collaborations to enhance their APM offerings and expand market reach.
- Organizations will invest in training employees on APM technologies to maximize the benefits of these systems.
- Companies will focus on ensuring compliance with evolving regulations, which will drive the adoption of robust APM systems.
- The APM market may see increased consolidation as larger players acquire smaller firms to enhance their technological capabilities and market presence.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Technological Advancements
The integration of IoT sensors, AI, and predictive analytics is transforming asset performance management by enabling real-time monitoring and proactive maintenance, which reduces downtime and operational costs.
Increasing Demand for Operational Efficiency
Organizations are adopting advanced APM solutions to improve overall equipment effectiveness (OEE), streamline workflows, and automate maintenance, resulting in higher productivity and lower operational expenses.
Regulatory Compliance Pressure
Evolving industry regulations and sustainability mandates are compelling companies to implement robust APM systems to ensure compliance, reduce fines, and foster a culture of accountability.
Focus on Sustainability
Growing emphasis on energy efficiency and carbon reduction is driving the adoption of APM solutions that help organizations monitor and optimize asset performance for environmental impact.
Rising Adoption of Digital Twins
The use of digital twins technology is accelerating, allowing companies to create virtual replicas of assets for real-time simulation and optimization, which improves reliability and reduces maintenance costs.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Asset Performance Management Market?
What factors are driving the growth of the Asset Performance Management Market?
What are the key segments within the Asset Performance Management Market?
What are some challenges faced by the Asset Performance Management Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Vertical
- 1.2.1 Energy & Utilities
- 1.2.2 Manufacturing
- 1.2.3 Government & Defense
- 1.2.4 Chemicals
- 1.2.5 Telecommunications
- 1.2.6 Healthcare & Pharmaceuticals
- 1.2.7 Consumer Goods, Food & Beverages
- 1.3 By Component
- 1.3.1 Solutions
- 1.3.2 Asset Strategy Management
- 1.3.3 Asset Reliability Management
- 1.3.4 Predictive Asset Management
- 1.3.5 Professional Services
- 1.3.6 Support & Maintenance
- 1.3.7 Implementation & Integration
- 1.3.8 Consulting
- 1.3.9 Managed Services
- 1.4 By Deployment Type
- 1.4.1 On-premises
- 1.4.2 Cloud
- 1.5 By Organization Size
- 1.5.1 Large Enterprises
- 1.5.2 SMEs
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2737 million → 2032: USD 5673.57 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Asset Performance Management Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Asset Performance Management Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Asset Performance Management Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Asset Performance Management Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Asset Performance Management Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Asset Performance Management Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Asset Performance Management Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Asset Performance Management Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2737 million → 2032: USD 5673.57 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Asset Performance Management Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Vertical - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Energy & Utilities
- 12.3.7.2 Manufacturing
- 12.3.7.3 Government & Defense
- 12.3.7.4 Chemicals
- 12.3.7.5 Telecommunications
- 12.3.7.6 Healthcare & Pharmaceuticals
- 12.3.7.7 Consumer Goods, Food & Beverages
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Solutions
- 12.4.7.2 Asset Strategy Management
- 12.4.7.3 Asset Reliability Management
- 12.4.7.4 Predictive Asset Management
- 12.4.7.5 Professional Services
- 12.4.7.6 Support & Maintenance
- 12.4.7.7 Implementation & Integration
- 12.4.7.8 Consulting
- 12.4.7.9 Managed Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Deployment Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 On-premises
- 12.5.7.2 Cloud
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Organization Size - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Large Enterprises
- 12.6.7.2 SMEs
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Asset Performance Management End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Asset Performance Management Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Asset Performance Management Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Asset Performance Management Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 AVEVA
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 SAP
- 18.4 GE Digital
- 18.5 IBM
- 18.6 ABB
- 18.7 Emerson
- 18.8 Bentley Systems
- 18.9 Rockwell Automation
- 18.10 Fluke
- 18.11 DNV
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

