
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Global Audio Codec Market Size 2024 | USD 6,818.50 million |
| Global Audio Codec Market, CAGR | 5.63% |
| Global Audio Codec Market Size 2032 | USD 10,532.44 million |
Market Overview:
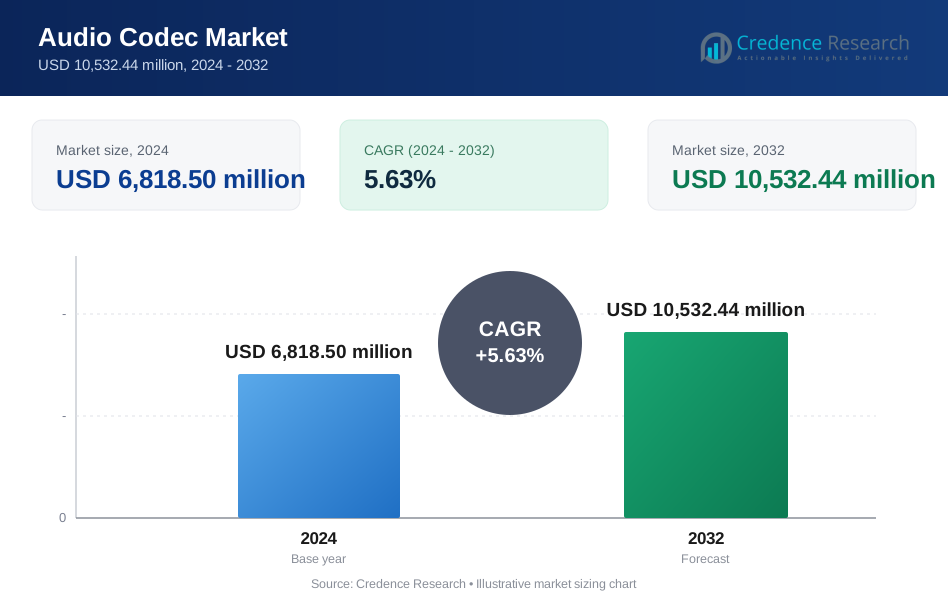
The Global Audio Codec Market is projected to grow from USD 6,818.50 million in 2024 to an estimated USD 10,532.44 million by 2032, with a compound annual growth rate (CAGR) of 5.63% from 2025 to 2032.
Key market drivers include the rapid evolution of wireless audio technologies and the growing emphasis on audio quality in portable devices. Manufacturers are focusing on developing codecs that support low power consumption while delivering superior sound clarity. Trends such as the integration of audio codecs in Internet of Things (IoT) devices and the increasing popularity of real-time communication platforms are further shaping market dynamics. Moreover, technological advancements in noise reduction, latency minimization, and high-resolution audio support are anticipated to offer growth opportunities over the forecast period.
Geographically, the Asia Pacific region dominates the Global Audio Codec Market, driven by the large consumer base and the significant presence of electronics manufacturers in countries like China, Japan, and South Korea. North America and Europe are also key markets, supported by strong demand for advanced audio systems and rapid technological adoption. Prominent players in the market include Qualcomm Technologies Inc., Cirrus Logic Inc., Realtek Semiconductor Corp., Analog Devices Inc., and Texas Instruments Inc.

Market Insights
- The Global Audio Codec Market is projected to grow steadily, reaching over USD 10.5 billion by 2032 with a CAGR of 5.63%.
- Rising demand for high-definition audio in consumer electronics and automotive infotainment systems drives market expansion.
- Increasing adoption of smartphones, smart speakers, and wearable devices fuels the need for efficient audio compression and decompression solutions.
- Technological advancements in noise reduction and latency minimization enhance audio quality, supporting market growth.
- Complex licensing structures and intellectual property issues pose challenges, potentially limiting codec adoption.
- Asia Pacific dominates the market due to its large consumer base and strong electronics manufacturing industry.
- North America and Europe remain key markets, driven by advanced audio system demand and rapid technology adoption.
Market Drivers
Rising Demand for High-Quality Audio in Consumer Electronics Boosts Market Growth
The Global Audio Codec Market is experiencing significant growth due to increasing consumer expectations for superior audio quality in smartphones, tablets, smart TVs, and wearable devices. Consumers now prioritize enhanced sound performance in their daily-use gadgets, which creates a strong demand for efficient audio codecs. Audio codecs play a vital role in compressing and decompressing digital audio signals without compromising quality. This rising requirement for high-fidelity sound across portable electronics continues to drive codec innovation and market expansion. Manufacturers are integrating advanced codecs to meet evolving audio standards in mobile and home entertainment systems. The widespread use of wireless earphones and smart speakers is further reinforcing the need for advanced audio solutions in the market.
- For instance, over 1.2 billion smartphones and 500 million smart TVs were shipped globally in a single year, with a majority featuring advanced audio codecs to deliver improved sound quality.
Growing Adoption of Audio Codecs in Automotive Infotainment Systems
The Global Audio Codec Market is expanding with the increasing deployment of sophisticated infotainment systems in modern vehicles. Automotive manufacturers are focusing on delivering seamless audio experiences that include high-definition sound and voice-controlled features. Audio codecs are critical in ensuring efficient sound processing while maintaining low power consumption in automotive environments. It supports reliable audio performance for in-car communication, navigation, and multimedia systems. The shift towards electric and connected vehicles is pushing demand for codecs that enhance audio clarity and system integration. Strong consumer preference for personalized and high-quality in-car audio is also contributing to market growth.
- For instance, a report from the International Organization of Motor Vehicle Manufacturers (OICA) noted that more than 80 million vehicles were produced globally in 2023, with a growing share equipped with advanced infotainment systems requiring high-performance audio codecs.
Expansion of Streaming Services and Real-Time Communication Drives Demand
The Global Audio Codec Market is gaining momentum due to the surge in streaming services and real-time communication platforms. Consumers increasingly access music, podcasts, and video content through streaming channels that require efficient codec performance for smooth audio transmission. Audio codecs ensure minimal latency and high-quality sound delivery, which enhances user experiences across devices. Businesses and individuals rely on real-time communication tools, which demand reliable and low-delay audio codecs. It supports clear, uninterrupted voice communication that is essential for video conferencing and online collaboration. The growth of remote work and virtual meetings continues to increase the demand for advanced codec solutions.
Technological Innovations Improve Codec Performance and Energy Efficiency
The Global Audio Codec Market is advancing through continuous technological innovation aimed at improving codec efficiency and sound quality. Companies are developing low-power codecs that extend battery life while supporting high-resolution audio standards. It enhances device performance, especially in portable and wearable electronics where energy efficiency is crucial. Advancements in noise reduction and error correction technology further improve audio playback and voice capture. New codec designs are addressing challenges related to data compression without losing audio detail. The development of codecs compatible with emerging wireless technologies is strengthening the market position of key industry players.
Market Trends
Growing Integration of Audio Codecs in Wireless and IoT Devices Shapes Market Trends
The Global Audio Codec Market is witnessing a strong trend toward the integration of audio codecs in wireless and Internet of Things (IoT) devices. Consumers increasingly prefer wireless audio solutions, including earbuds, headphones, and smart speakers that rely on efficient audio codecs for high-quality sound. It is enabling seamless wireless communication while maintaining audio clarity and low latency. IoT devices with voice control and audio feedback require advanced codecs to support reliable audio transmission. Manufacturers are embedding low-power audio codecs in smart home systems, wearables, and connected appliances. This shift is reinforcing codec demand across expanding wireless product categories.
- For instance, a 2024 survey by the Bluetooth Special Interest Group reported that over 700 million wireless audio devices with integrated audio codecs were shipped globally, with more than 250 manufacturers contributing to this volume.
Advancements in Low-Power and High-Resolution Audio Codecs Lead Innovation
The Global Audio Codec Market is progressing through a clear trend of developing low-power audio codecs that support high-resolution audio. Consumers demand superior sound quality without compromising battery performance, especially in portable devices. It is driving innovation focused on minimizing power consumption while enhancing audio fidelity. New codecs are meeting the requirements of high-resolution audio playback, which is gaining popularity among audiophiles and casual users. Companies are investing in research to produce compact, energy-efficient codecs that support advanced sound features. This focus on balancing power efficiency with audio performance is reshaping codec design strategies.
- For instance, more than 90 companies launched over 300 new low-power, high-resolution audio codec models designed specifically for portable and battery-operated devices worldwide.
Increasing Use of Audio Codecs in Voice-Controlled and AI-Based Devices
The Global Audio Codec Market is expanding through the rising use of audio codecs in voice-controlled devices and artificial intelligence (AI)-driven systems. Smart assistants, voice-enabled applications, and AI-integrated gadgets rely heavily on efficient audio processing. It ensures clear voice recognition and accurate response in real-time environments. The growing popularity of smart home ecosystems and automotive voice assistants is fueling this trend. Audio codecs that support noise suppression and echo cancellation are becoming essential for voice-command accuracy. This trend is encouraging companies to enhance codec capabilities to meet AI application demands.
Rapid Expansion of Streaming Platforms Drives Need for Advanced Audio Codecs
The Global Audio Codec Market is evolving alongside the rapid growth of streaming platforms for music, podcasts, and video content. Streaming services require advanced audio codecs to deliver consistent sound quality across various network conditions. It is supporting seamless playback with minimal buffering and optimal audio compression. Consumers expect high-quality audio experiences, regardless of streaming device or bandwidth limitations. This demand is pushing the development of codecs that provide adaptive bitrate capabilities and improved sound clarity. Companies are aligning codec solutions with the evolving requirements of digital content providers and streaming applications.
Market Challenges
Complex Licensing Structures and Compliance Issues Restrict Market Expansion
The Global Audio Codec Market faces challenges related to complex licensing structures and intellectual property constraints. Companies must navigate strict licensing agreements that often involve high costs and intricate compliance requirements. It increases operational expenses and can limit the adoption of certain advanced codecs, particularly for smaller manufacturers. The need to obtain multiple licenses for different codec formats adds financial and administrative burdens. Intellectual property disputes further complicate market entry for new players. These licensing challenges can slow innovation and restrict the availability of cost-effective codec solutions in the market.
- For instance, manufacturers are required to pay up to $100,000 per year for a single advanced codec streaming license, and the installation of multiple codec formats in consumer devices can involve negotiating with more than three separate patent pools, significantly raising both administrative workload and cost barrier
Rapid Technological Changes and Compatibility Barriers Impact Product Development
The Global Audio Codec Market must address the challenge of rapid technological changes that frequently shift consumer expectations and product standards. Manufacturers face pressure to update codec solutions to remain compatible with evolving hardware and software platforms. It creates barriers when integrating audio codecs with diverse devices and network systems. Compatibility issues can lead to increased development time and higher engineering costs. Failure to quickly adapt codecs to emerging audio formats and connectivity technologies may weaken market competitiveness. This dynamic environment demands continuous investment in research and timely product updates to meet performance and compatibility standards.
Market Opportunities
Expansion of Smart Devices and IoT Ecosystems Creates Strong Growth Potential
The Global Audio Codec Market has significant opportunities driven by the rapid expansion of smart devices and IoT ecosystems. Consumers continue to adopt smart speakers, wearables, and home automation systems that require efficient audio processing. It supports the need for low-latency, high-quality audio codecs that integrate smoothly with these devices. Growth in smart home applications and connected appliances creates new demand for voice-enabled solutions. Manufacturers can develop specialized codecs that enhance audio experiences across diverse IoT platforms. This growing ecosystem opens pathways for companies to introduce advanced, energy-efficient codecs tailored for smart environments.
Rising Demand for High-Resolution Audio in Emerging Markets Supports New Opportunities
The Global Audio Codec Market benefits from the increasing demand for high-resolution audio products in emerging economies. Rising disposable incomes and growing consumer interest in premium audio devices encourage adoption of advanced codec technologies. It offers manufacturers the chance to target new markets with cost-effective, high-performance audio solutions. Expanding access to high-speed internet and streaming services in these regions strengthens codec demand. Companies can leverage local partnerships and customized product strategies to capture market share. This growing interest in superior sound quality across emerging markets presents valuable long-term growth prospects.
Market Segmentation Analysis
By Function
The Global Audio Codec Market is segmented by function into codecs with DSP and codecs without DSP. Codecs with DSP hold a significant market share due to their ability to manage complex audio processing tasks efficiently. It offers high-performance sound quality and supports advanced features such as noise cancellation and voice enhancement. These codecs are widely used in premium consumer electronics and automotive infotainment systems. Codecs without DSP appeal to cost-sensitive applications where basic audio processing is sufficient. This segment attracts manufacturers targeting entry-level smartphones and simple audio devices. The demand for both categories continues to rise with the increasing variety of audio applications across industries.
- For instance, company shipment data from Cirrus Logic and Texas Instruments shows that more than 900 million audio codecs with DSP were integrated into smartphones and automotive systems globally in 2024.
By Component Type
The Global Audio Codec Market is divided into hardware codecs and software codecs based on component type. Hardware codecs dominate the market due to their strong presence in smartphones, televisions, and portable audio devices. It delivers reliable performance and low-latency processing, which is essential in real-time audio transmission. Software codecs are gaining traction because of their flexibility and ease of integration with various platforms. These codecs support frequent updates and customization, making them suitable for streaming applications and cloud-based audio solutions. Both hardware and software segments contribute to the market’s steady growth.
- For instance, over 1.2 billion hardware audio codecs were shipped worldwide in 2024, reflecting their widespread use in consumer electronics and communication devices.
By Application
The Global Audio Codec Market serves diverse applications, including automobiles, television sets, smartphones and tablets, desktops and laptops, headphones, headsets and wearable devices, music and media devices, home theatres, gaming consoles, and others such as AR/VR, broadcasting equipment, and smart home devices. Smartphones and tablets represent a leading application segment, driven by rising consumer demand for superior audio experiences. It supports codecs that deliver efficient audio compression and clarity. Automotive applications also show strong growth, supported by advanced infotainment and communication systems. Wearable devices, gaming consoles, and smart home products continue to create new opportunities for codec manufacturers.

Segments
Based on Function
- With DSP
- Without DSP
Based on Component Type
- Hardware Codecs
- Software Codecs
Based on Application
- Automobile
- Television Sets
- Smartphones and tablets
- Desktop and laptops
- Headphone, Headsets and Wearable devices
- Music & Media Devices and Home Theatres
- Gaming consoles
- Others (AR/VR, Broadcasting Equipment, Smart Home Devices)
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Audio Codec Market
The Audio Codec Market in North America is projected to grow from USD 2,483.47 million in 2024 to USD 3,855.45 million by 2032, registering a CAGR of 5.7% during the forecast period. North America holds the largest regional share of approximately 36.43% in 2024. It benefits from strong demand across smartphones, automotive infotainment, and smart home devices. The United States drives much of this growth with high consumer adoption of advanced audio technologies and premium sound systems. Manufacturers in this region focus on developing codecs that support low latency and superior audio clarity. The market expansion is supported by the fast growth of streaming platforms and the continuous upgrade of consumer electronics.
Europe Audio Codec Market
The Audio Codec Market in Europe is expected to increase from USD 1,866.72 million in 2024 to USD 2,714.98 million by 2032, growing at a CAGR of 4.8%. Europe accounts for a regional share of approximately 27.38% in 2024. It shows steady demand driven by the automotive sector, high-end audio systems, and rising consumer interest in smart home devices. Germany, France, and the United Kingdom remain key contributors to market growth. European manufacturers prioritize energy-efficient codecs with noise cancellation and enhanced audio processing. The region’s well-established automotive and electronics industries continue to support codec adoption.
Asia Pacific Audio Codec Market
The Audio Codec Market in Asia Pacific is forecasted to grow from USD 1,649.03 million in 2024 to USD 2,803.13 million by 2032, with the highest regional CAGR of 6.9%. Asia Pacific holds a market share of approximately 24.17% in 2024. China, Japan, and South Korea are major contributors, supported by strong manufacturing hubs and large consumer bases. It benefits from the increasing adoption of smartphones, wearable devices, and smart televisions. The growing preference for wireless audio solutions across the region drives codec demand. Expanding IoT ecosystems in Asia Pacific also support codec integration in smart applications.
Latin America Audio Codec Market
The Audio Codec Market in Latin America is projected to grow from USD 353.13 million in 2024 to USD 503.13 million by 2032, registering a CAGR of 4.6%. Latin America represents a smaller but growing market, holding a regional share of approximately 5.18% in 2024. Brazil and Mexico lead the market with increasing smartphone penetration and rising consumer interest in affordable audio devices. It shows growth potential in the automotive and smart home sectors. Latin American manufacturers are gradually adopting audio codecs that offer reliable sound quality with efficient power usage. The region’s expanding middle-class population continues to create new demand for consumer electronics.
Middle East Audio Codec Market
The Audio Codec Market in the Middle East is expected to grow from USD 235.88 million in 2024 to USD 332.76 million by 2032, at a CAGR of 4.5%. The Middle East holds a regional market share of approximately 3.46% in 2024. Countries such as the United Arab Emirates and Saudi Arabia are driving market demand, supported by increasing investments in smart cities and consumer electronics. It focuses on adopting wireless audio solutions and voice-enabled smart devices. Growth in the automotive sector and rising demand for high-quality sound in entertainment systems support codec adoption. The Middle East continues to show steady interest in advanced audio technologies.
Africa Audio Codec Market
The Audio Codec Market in Africa is projected to rise from USD 230.28 million in 2024 to USD 322.99 million by 2032, growing at a CAGR of 4.4%. Africa holds a regional share of approximately 3.38% in 2024. South Africa and Nigeria are key markets with increasing adoption of smartphones, media devices, and affordable audio solutions. It is showing gradual growth supported by improved internet connectivity and the rising popularity of streaming services. Audio codecs that deliver efficient compression and reliable sound performance are gaining attention across African markets. Manufacturers have an opportunity to introduce cost-effective and durable codecs tailored for local consumer needs.
Key players
- Cirrus Logic
- Qualcomm
- Realtek Semiconductor
- Dolby Laboratories
- Technicolor
- Analog Devices
- STMicroelectronics
- Texas Instruments
- Fraunhofer IIS
- Xiph
- Broadcom
- AMS
- Tempo Semiconductor
- Dialog Semiconductor
- CML Microcircuits
- Tieline
- AKM (Asahi Kasei Microdevices)
- Sony Corporatio
Competitive Analysis
The Global Audio Codec Market is highly competitive, with major players focusing on product innovation, energy efficiency, and improved audio quality to strengthen their market positions. It features leading companies such as Cirrus Logic, Qualcomm, and Realtek Semiconductor, which dominate with wide function portfolios and strong financial stability. Dolby Laboratories and Technicolor hold strategic positions by offering high-end audio technologies for premium applications. Texas Instruments, Analog Devices, and STMicroelectronics continue to advance codec designs that address power consumption and integration challenges. Emerging players like Tempo Semiconductor and Xiph offer niche solutions targeting specific markets. Companies compete on technology upgrades, cost efficiency, and the ability to meet growing demand across consumer electronics, automotive, and smart devices. Frequent product launches, partnerships, and regional expansions shape the market’s competitive landscape.
Recent Developments
- In January 2025, Cirrus Logic and Intel collaborated to introduce a new audio solution designed for Intel Core Ultra processors. This partnership focuses on providing enhanced audio experiences in PCs, including flexible multi-speaker support and improved audio quality. The solution is intended to benefit both mainstream and premium PCs by offering superior sound, lower power consumption, and design flexibility for manufacturers.
- In 2023–2025, Qualcomm continued advancing its aptX Adaptive wireless audio codec—offering dynamic bitrate scaling (279–420 kbps), backward compatibility with older aptX variants, and support for high-res audio formats.
Market Concentration and Characteristics
The Global Audio Codec Market shows moderate concentration with several established players holding significant market shares. It is characterized by rapid technological advancements, strong competition, and continuous demand for energy-efficient, high-quality audio solutions. Leading companies focus on integrating advanced features like low latency, noise reduction, and high-resolution audio to maintain their market edge. The market supports a mix of large multinational corporations and specialized regional players offering tailored codec solutions. It demonstrates high product differentiation driven by application-specific requirements across consumer electronics, automotive, and smart devices. Price competitiveness and intellectual property licensing remain key factors influencing market dynamics.
Report Coverage
The research report offers an in-depth analysis based on Function, Component Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Global Audio Codec Market will continue expanding driven by growing adoption of smart devices requiring advanced audio processing capabilities.
- Increasing demand for high-resolution and immersive audio experiences in consumer electronics will accelerate codec innovation and deployment.
- Integration of AI and machine learning with audio codecs will enhance noise reduction, voice recognition, and adaptive sound quality in real-time applications.
- Automotive industry growth, especially in connected and electric vehicles, will boost demand for robust audio codecs supporting infotainment and communication systems.
- The rising popularity of wireless audio products like earbuds and smart speakers will drive the development of low-power, high-efficiency codecs.
- Streaming platforms and cloud-based audio services will require codecs with superior compression and low latency to improve user experience across networks.
- Expansion of IoT ecosystems will increase the need for scalable and flexible audio codecs that integrate seamlessly into diverse smart environments.
- Emerging markets will witness increased codec adoption due to rising disposable incomes and rapid penetration of smartphones and digital media consumption.
- Ongoing research in codec standards will focus on balancing sound quality with minimal power consumption to support wearable and portable devices.
- Collaboration between codec developers and hardware manufacturers will strengthen product innovation and accelerate the commercialization of next-generation audio technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What was the market size of the Global Audio Codec Market in 2023, and what is its forecast for 2032?
How do technological advancements impact the Global Audio Codec Market?
Which regions dominate the Global Audio Codec Market?
Who are the key players in the Global Audio Codec Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Audio Codec Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Audio Codec Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 6,818.50 million → 2032: USD 10,532.44 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Audio Codec Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Audio Codec Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Audio Codec Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Audio Codec Market Drivers
- 3.3 Audio Codec Market Restraints & Challenges
- 3.4 Audio Codec Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Audio Codec Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Audio Codec Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Audio Codec category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Audio Codec Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Audio Codec Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Audio Codec market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Audio Codec Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Audio Codec Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Audio Codec Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Audio Codec (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Audio Codec Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Audio Codec Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Audio Codec Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Audio Codec Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Audio Codec Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Audio Codec Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Audio Codec Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Audio Codec Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Audio Codec Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
