
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Australia Digital Signature Market Size 2024 | USD 75.19 million |
| Australia Digital Signature Market, CAGR | 34.04% |
| Australia Digital Signature Market Size 2032 | USD 783.47 million |
Market Overview:
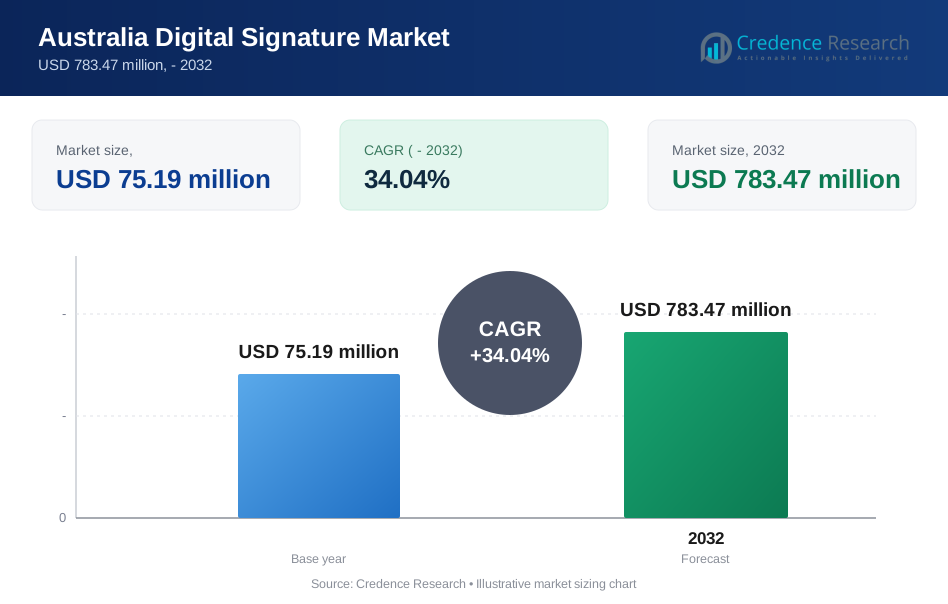
The Australia Digital Signature Market is projected to grow from USD 75.19 million in 2024 to an estimated USD 783.47 million by 2032, with a compound annual growth rate (CAGR) of 34.04% from 2024 to 2032.
The growth of the Australia Digital Signature Market is significantly driven by regulatory advancements, digital transformation initiatives, and the increasing need for cybersecurity. One of the primary enablers is the implementation of the Digital ID Act 2024, which came into effect in December 2024. This legislation provides a robust legal framework for digital identities and verifiable credentials, thereby enhancing trust in digital transactions and driving the demand for secure authentication methods like digital signatures. Additionally, the widespread adoption of mobile devices and cloud technologies has enabled organizations to seamlessly integrate digital signature solutions into existing systems, making them more accessible and efficient. Rising concerns over data breaches and cyber threats have further heightened the demand for tamper-proof, legally binding digital signatures, particularly in critical sectors such as banking, legal, government, and healthcare. Moreover, organizations are increasingly adopting digital workflows to improve operational efficiency, reduce paperwork, and accelerate document turnaround times, further fueling the market’s expansion.
Across Australia, the adoption of digital signature solutions is gaining momentum, with notable activity across key states. New South Wales (NSW), as the country’s economic powerhouse, leads in digital transformation efforts, particularly in finance, legal, and enterprise sectors that demand high levels of compliance and authentication. Victoria follows closely, with strong uptake in healthcare and education sectors, where institutions are leveraging digital signatures to enhance service delivery and reduce administrative bottlenecks. Queensland and Western Australia are also emerging as growth centers, primarily driven by government modernization efforts and the integration of digital technologies in mining, infrastructure, and public services. Overall, the national digital strategy, coupled with investments in digital infrastructure and regional policy support, is contributing to uniform growth across all major states and territories.
Market Insights:
- The Australia Digital Signature market is projected to grow from USD 75.19 million in 2024 to USD 783.47 million by 2032, registering a robust CAGR of 34.04%.
- The Global Digital Signature Market is projected to grow significantly, from USD 7,885.08 million in 2024 to USD 76,046.14 million by 2032, reflecting a strong CAGR of 32.75% during the forecast period.
- The Digital ID Act 2024 has established a secure legal framework, accelerating digital signature adoption across key industries.
- Rising cybersecurity threats are increasing the demand for tamper-proof, legally recognized digital authentication solutions.
- Cloud-based and mobile-accessible platforms are making digital signatures more scalable and user-friendly for remote and hybrid workforces.
- Key regions such as New South Wales and Victoria are leading in adoption, driven by finance, legal, education, and healthcare sectors.
- Limited awareness among SMEs and concerns over cross-platform standardization remain key barriers to full-scale adoption.
- Integration with ERP and CRM systems is enhancing operational efficiency, positioning digital signatures as a core enterprise tool.
Report Scope
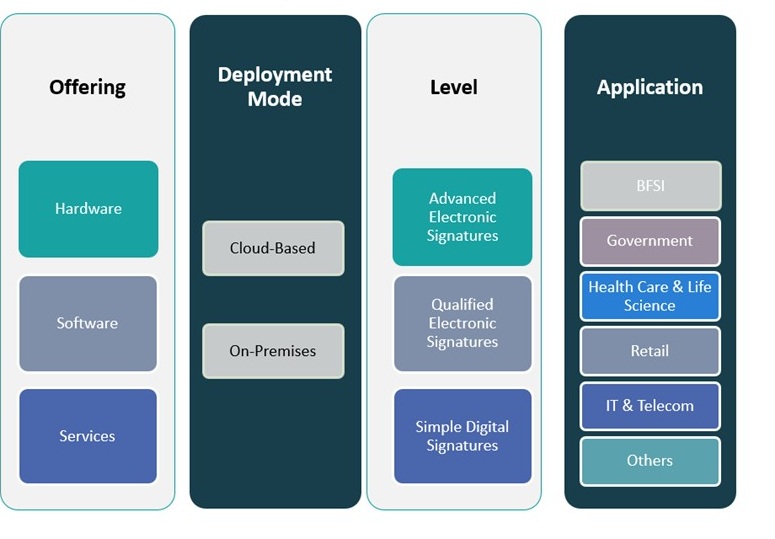
This report segments the Australia Digital Signature Market as follow
Market Drivers:
Regulatory Backing and Legal Framework
Government-led initiatives and evolving regulatory frameworks serve as foundational drivers for the digital signature market in Australia. The introduction of the Digital ID Act 2024 marks a significant milestone in establishing a cohesive digital identity ecosystem. This act provides legal validity and standardization for digital transactions, thereby increasing confidence in electronic authentication mechanisms. By formalizing the use of digital signatures under a recognized legal structure, the government has not only validated their utility but also positioned them as essential tools in regulatory compliance. This regulatory clarity encourages widespread adoption across both the public and private sectors, especially in industries where secure and verifiable documentation is paramount.
Digital Transformation Across Key Industries
Australia’s ongoing digital transformation across various sectors, including finance, legal, healthcare, and education, continues to fuel the adoption of digital signature solutions. Businesses are increasingly transitioning to paperless operations, driven by the need for faster transaction processing, reduced administrative overhead, and enhanced customer experience. In the financial services and legal domains, where documentation must meet stringent compliance and authentication standards, digital signatures provide a streamlined and legally recognized alternative to traditional pen-and-paper processes. For instance, Loan Market, a leading mortgage broker, has integrated electronic signatures with its CRM platform, enabling a fully paperless experience for clients and significantly reducing turnaround times for document execution. The healthcare sector has also embraced these solutions to securely manage patient records, prescriptions, and compliance documents, especially with the growing digitization of telemedicine and e-health platforms.
Rising Concerns Over Cybersecurity
As cyber threats become more sophisticated, organizations are seeking secure, tamper-proof methods of verifying the authenticity and integrity of digital documents. Digital signatures, enabled by public key infrastructure (PKI), offer a high level of security that assures both origin verification and content integrity. In a climate where data breaches and identity fraud can have severe reputational and financial consequences, businesses across Australia are recognizing the value of digital signatures in protecting sensitive information. This demand for enhanced security is particularly evident in sectors like banking, insurance, and government, where data privacy and secure communications are critical.
Technological Advancements and User Accessibility
Advancements in cloud computing, mobile technology, and software-as-a-service (SaaS) models have made digital signature solutions more accessible, scalable, and user-friendly. Many Australian enterprises are integrating digital signature platforms with their existing enterprise resource planning (ERP), customer relationship management (CRM), and document management systems to automate workflows and increase productivity. For instance, digital signature providers like Zoho Sign employ advanced security protocols such as AES-256 encryption and TLS/SSL to ensure data protection during transmission and storage, further enhancing user trust and adoption. Additionally, mobile compatibility and remote access have made it easier for businesses to support hybrid and remote working models without compromising on security or compliance. These technological improvements have not only enhanced user adoption but also strengthened the value proposition of digital signatures in both large enterprises and small to medium-sized businesses.
Market Trends:
Integration with Emerging Technologies
A notable trend shaping the Australia Digital Signature Market is the growing integration of digital signatures with emerging technologies such as blockchain, artificial intelligence (AI), and biometrics. These technologies are enhancing the security, traceability, and functionality of digital signing processes. PleaseSign, for example, highlights the use of AI algorithms for fraud detection and biometric verification, such as facial recognition, to increase signer authenticity and reduce the risk of unauthorized access. Blockchain-based signature solutions are gaining attention for their ability to provide immutable audit trails, particularly useful in sectors like supply chain management and cross-border transactions. AI-driven document verification tools are also being incorporated to authenticate signers in real time, further reducing fraud risk. As enterprises explore digital transformation through next-generation technologies, the fusion of digital signatures with advanced tech platforms is becoming increasingly prevalent.
Expansion of Use Cases Beyond Compliance
While early adoption of digital signatures in Australia was largely driven by compliance and legal documentation, the market is now witnessing an expansion into broader operational workflows. Businesses are utilizing digital signatures for onboarding, procurement, HR processes, internal approvals, and client communications. This shift reflects a strategic move from treating digital signatures as a regulatory tool to leveraging them as a business enabler. The trend is especially strong among small and medium-sized enterprises (SMEs) aiming to improve efficiency without investing heavily in traditional infrastructure. As organizations grow more comfortable with digital ecosystems, the use of digital signatures is becoming integral to daily business operations.
Growth in Cloud-Based Signature Platforms
The rise in demand for flexible and cost-effective digital solutions is driving a strong market shift toward cloud-based digital signature platforms in Australia. Zoho Sign, for instance, operates two Australian data centres (Sydney and Melbourne) to ensure data sovereignty, and offers AES-256 encryption at rest and SSL in transit for secure document handling. These platforms offer the advantage of rapid deployment, minimal maintenance, and seamless scalability. Businesses, particularly those embracing hybrid or remote work models, are increasingly turning to cloud-based signing solutions that allow users to securely authenticate documents from any location. The trend aligns with broader adoption of software-as-a-service (SaaS) business models and the growing reliance on cloud infrastructure across Australian industries. As organizations continue to prioritize agility, cloud-native digital signature tools are expected to dominate the market.
Consumer Awareness and Demand for User-Centric Solutions
A rising trend in the Australian digital signature landscape is the growing consumer awareness of electronic authentication and the demand for user-friendly experiences. End users now expect digital signature interfaces to be intuitive, mobile-compatible, and visually straightforward. Companies that prioritize user experience design (UXD) in their signature platforms are gaining competitive advantages. Additionally, with the proliferation of digital services among Australian consumers-ranging from real estate transactions to utility registrations-there is increasing public demand for secure and accessible digital signing options. This shift is pushing solution providers to innovate with simplified workflows and multilingual, inclusive interfaces that cater to a diverse user base.
Market Challenges Analysis:
Lack of Standardization Across Platforms
One of the primary restraints hindering the full-scale adoption of digital signature solutions in Australia is the lack of interoperability and standardization among different platforms. Despite regulatory progress, many organizations encounter challenges when integrating signature tools across various systems, especially in multi-vendor environments. Disparities in file formats, encryption protocols, and certification methods can lead to inefficiencies and compatibility issues, particularly for businesses that operate across jurisdictions or collaborate with international partners. For example, the Data and Digital Ministers’ Meeting (DDMM) has acknowledged the need for a “framework for all governments,” but current differences in file formats, encryption protocols, and certification methods persist, particularly in multi-vendor or cross-jurisdictional environments. This lack of uniformity hampers scalability and deters some enterprises from transitioning fully to digital signature frameworks.
Limited Awareness Among Small Enterprises
While large corporations and government bodies are steadily adopting digital signature technologies, small and medium-sized enterprises (SMEs) often lag due to limited awareness of the benefits and practical applications. Many SMEs still perceive digital signatures as complex or unnecessary, particularly in traditional sectors such as agriculture, local manufacturing, and construction. Without targeted education and incentives, a significant portion of the market may remain untapped, slowing the overall adoption rate. Furthermore, budget constraints and insufficient IT infrastructure in smaller firms often deter investment in such digital tools.
Concerns Over Data Privacy and Legal Jurisdiction
As digital signatures involve the processing and storage of sensitive information, concerns surrounding data privacy and compliance with evolving legal frameworks remain critical challenges. Businesses must navigate complex data residency requirements, especially when using cloud-based platforms hosted overseas. Uncertainty around cross-border data transmission, retention policies, and legal recognition of digital signatures in other jurisdictions creates hesitation among enterprises looking to engage in international transactions. Without clear, harmonized data governance policies, these concerns may continue to act as barriers to widespread adoption across the Australian digital ecosystem.
Market Opportunities:
The Australia Digital Signature Market presents significant growth opportunities as the nation accelerates its digital transformation agenda across public and private sectors. With increasing digitization of services in healthcare, legal, real estate, and government administration, there is a strong demand for secure, efficient, and compliant digital authentication solutions. The push towards a paperless economy, coupled with initiatives under the Digital Economy Strategy 2030, creates a favorable environment for digital signature providers to expand their reach. Additionally, the rising emphasis on remote work and virtual collaboration has heightened the need for secure document handling and approval mechanisms, positioning digital signatures as essential tools in maintaining operational continuity and data integrity.
Moreover, the growing adoption of advanced technologies such as blockchain, cloud computing, and AI-based identity verification in Australia enhances the scope for innovation in digital signature offerings. There is a distinct opportunity to develop localized, industry-specific solutions tailored to compliance needs and user experience expectations. Small and medium-sized enterprises, which account for a substantial portion of Australia’s business landscape, remain an underpenetrated segment with immense potential for adoption, especially as awareness and digital literacy improve. Furthermore, the demand for cross-border legal and financial documentation-especially in sectors like fintech, logistics, and education-presents a valuable opportunity for platforms offering globally recognized, legally binding signature solutions. By capitalizing on these evolving needs, market players can position themselves for long-term growth in Australia’s dynamic and increasingly digitized business environment.
Market Segmentation Analysis:
The Australia Digital Signature Market is segmented across various categories, each offering distinct growth trajectories and adoption trends.
By offering, the software segment currently dominates due to increasing demand for secure, scalable, and user-friendly signing solutions integrated into enterprise workflows. However, the services segment is gaining traction as organizations seek deployment support, customization, and compliance consulting. Hardware solutions, although more niche, continue to hold relevance in highly regulated industries where physical token-based authentication is still preferred.
By deployment mode, cloud-based digital signature solutions are witnessing faster adoption, particularly among small and medium-sized enterprises. Their ease of integration, lower upfront costs, and support for remote access make them ideal for dynamic and distributed work environments. On-premises deployment remains relevant for large institutions and government agencies with stringent data control and security policies.
By level of signature, where advanced electronic signatures are becoming the preferred choice due to their enhanced security and compliance with Australian regulatory standards. Qualified electronic signatures are gradually gaining adoption in high-assurance environments, while simple digital signatures still find use in low-risk, internal documentation processes.
By application, the BFSI sector leads the market in adoption, driven by the critical need for secure and compliant documentation. Government agencies are also major contributors due to digital governance initiatives. Healthcare & life sciences, retail, and IT & telecom sectors are progressively integrating digital signature solutions to improve efficiency, reduce paperwork, and enhance customer interactions across diverse digital touchpoints.
Segmentation:
By Offering Segment:
- Hardware
- Software
- Services
By Deployment Mode Segment:
- Cloud-Based
- On-Premises
By Level Segment:
- Advanced Electronic Signatures
- Qualified Electronic Signatures
- Simple Digital Signatures
By Application Segment:
- BFSI (Banking, Financial Services, and Insurance)
- Government
- Healthcare & Life Sciences
- Retail
- IT & Telecom
- Others
Regional Analysis:
The Australia Digital Signature Market exhibits varied growth dynamics across its regions, influenced by economic activities, technological adoption, and digital infrastructure development.
New South Wales (NSW) stands as the market leader, contributing approximately 30.7% to the national economy. Sydney, as the financial and technological hub, drives significant adoption of digital signature solutions, particularly in the banking, legal, and corporate sectors. The state's robust digital infrastructure and proactive government initiatives further bolster this growth.
Victoria, accounting for 22.7% of the national output, follows closely. Melbourne's emphasis on healthcare, education, and professional services sectors has led to increased implementation of digital signatures to streamline operations and enhance security. The state's commitment to digital transformation initiatives supports this upward trend.
Queensland, with a 19.1% share of the national economy, is witnessing accelerated adoption of digital signatures, especially in government services and the mining sector. The state's focus on improving operational efficiency and reducing paperwork in public administration contributes to this growth.
Western Australia, contributing 17.1% to the national output, is experiencing steady growth in digital signature adoption, particularly in the resources and energy sectors. The need for secure and efficient document management in these industries drives the demand for digital solutions.
South Australia and Tasmania, though smaller in economic contribution, are progressively embracing digital signatures. South Australia's focus on manufacturing and defense sectors, and Tasmania's emphasis on public services, are key areas where digital signature solutions are being integrated to enhance operational workflows.
Key Player Analysis:
- Annature
- Vault Systems
- Lawpath
- Secured Signing
- Elmo Software
Competitive Analysis:
The Australia Digital Signature Market is characterized by the presence of both global technology providers and domestic solution vendors, fostering a competitive and innovation-driven environment. Leading players such as Adobe Inc., DocuSign Inc., and OneSpan dominate the market with comprehensive digital signing platforms and enterprise-grade security features. These companies leverage cloud infrastructure, API integrations, and compliance with Australian regulations to cater to large-scale organizations across finance, government, and legal sectors. In parallel, regional firms and startups are emerging with niche, cost-effective solutions tailored for small and medium-sized enterprises (SMEs). Companies are increasingly focusing on enhancing user experience, offering multilingual interfaces, and integrating AI-powered verification tools to gain a competitive edge. Strategic partnerships, technological upgrades, and compliance-driven innovation remain core strategies among key players. As digital transformation accelerates nationwide, market competition is expected to intensify, prompting continuous product enhancements and broader adoption across industries.
Recent Developments:
- In May 2024, DocuSign agreed to acquire Lexion, an AI-powered agreement management software company, for $165 million. This acquisition is set to enhance DocuSign’s Intelligent Agreement Management (IAM) platform with advanced AI capabilities, streamlining contract workflows and centralizing agreement processes for enterprise customers. Lexion’s team will join DocuSign, further strengthening its AI and engineering expertise.
- In March 2025, Adobe launched the Adobe Experience Platform Agent Orchestrator, a tool that enables businesses to build and manage AI agents for customer experiences and marketing workflows. This launch is supported by strategic partnerships with major technology companies, including Microsoft, SAP, and ServiceNow, ensuring seamless integration and execution across various AI-driven use cases.
- In February 2025, Signaturit Group announced its plan to acquire Validated ID, a leading provider of digital identity and electronic signature solutions. This acquisition is expected to provide significant strategic advantages to Signaturit Group, further strengthening its position as a leader in the European digital trust market. The move is part of the company's broader efforts to expand its portfolio and enhance its capabilities in secure digital transactions.
Market Concentration & Characteristics:
The Australia Digital Signature Market exhibits moderate to high market concentration, with a few dominant players controlling a substantial share of the market, particularly in enterprise and government segments. Companies such as DocuSign, Adobe, and OneSpan maintain a strong presence due to their advanced technology, scalability, and compliance with Australian legal frameworks. However, the market also reflects a dynamic landscape, where smaller domestic providers and startups offer specialized, sector-specific solutions to address the diverse needs of small and medium-sized enterprises. The market is characterized by rapid technological adoption, strong regulatory support, and increasing customer demand for secure, cloud-based, and mobile-friendly signature solutions. Interoperability, user experience, and integration capabilities with existing IT systems are key product differentiators. The shift towards digital governance, remote work, and paperless operations continues to shape market characteristics, encouraging innovation and competition. As demand expands across sectors, the market is evolving toward broader accessibility and deeper vertical specialization.
Report Coverage:
The research report offers an in-depth analysis based on Offering, Deployment Mode, Level and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising adoption of digital identities under the Digital ID Act will drive long-term demand.
- Integration with blockchain and AI technologies will enhance authentication and security.
- Cloud-based signature platforms will see higher penetration across SMEs.
- Cross-border compliance will create opportunities for globally compatible solutions.
- Public sector digitization initiatives will boost procurement of verified signature tools.
- Remote and hybrid work models will sustain the need for mobile-friendly solutions.
- Increased focus on data residency will favor local cloud infrastructure providers.
- BFSI, healthcare, and legal sectors will continue leading market adoption.
- Startups offering niche, cost-effective tools will challenge large incumbents.
- Ongoing regulatory updates will shape product innovation and interoperability standards.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Regulatory Backing and Legal Framework
The implementation of the Digital ID Act 2024 provides a robust legal foundation for digital signatures, increasing trust and compliance in digital transactions and accelerating adoption across both public and private sectors.
Digital Transformation Across Key Industries
Widespread digitalization in finance, legal, healthcare, and education sectors is driving the shift to paperless operations, with digital signatures enabling faster, more secure, and compliant document workflows.
Rising Concerns Over Cybersecurity
Increasing sophistication of cyber threats and the need for tamper-proof, legally binding authentication are pushing organizations to adopt digital signatures, especially in sectors handling sensitive data such as banking and government.
Technological Advancements and User Accessibility
Advances in cloud computing, mobile technology, and SaaS models have made digital signature solutions more accessible and scalable, supporting remote and hybrid workforces and enhancing user adoption.
Integration with Emerging Technologies
The integration of digital signatures with blockchain, AI, and biometrics is enhancing security, traceability, and user authentication, making these solutions more attractive for high-assurance and innovative use cases.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Australia Digital Signature Market?
What factors are driving the growth of the Australia Digital Signature Market?
What are some challenges faced by the Australia Digital Signature Market?
Who are the major players in the Australia Digital Signature Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Level
- 1.2.1 Advanced Electronic Signatures
- 1.2.2 Qualified Electronic Signatures
- 1.2.3 Simple Digital Signatures
- 1.3 By Offering
- 1.3.1 Hardware
- 1.3.2 Software
- 1.3.3 Services
- 1.4 By Application
- 1.4.1 BFSI (Banking, Financial Services, and Insurance)
- 1.4.2 Government
- 1.4.3 Healthcare & Life Sciences
- 1.4.4 Retail
- 1.4.5 IT & Telecom
- 1.4.6 Others
- 1.5 By Deployment Mode
- 1.5.1 Cloud-Based
- 1.5.2 On-Premises
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 75.19 million → 2032: USD 783.47 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Digital Signature Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Digital Signature Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Digital Signature Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Digital Signature Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Digital Signature Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Digital Signature Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Digital Signature Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Digital Signature Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 75.19 million → 2032: USD 783.47 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Digital Signature Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Level - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Advanced Electronic Signatures
- 12.3.7.2 Qualified Electronic Signatures
- 12.3.7.3 Simple Digital Signatures
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Offering - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hardware
- 12.4.7.2 Software
- 12.4.7.3 Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 BFSI (Banking, Financial Services, and Insurance)
- 12.5.7.2 Government
- 12.5.7.3 Healthcare & Life Sciences
- 12.5.7.4 Retail
- 12.5.7.5 IT & Telecom
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Deployment Mode - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Cloud-Based
- 12.6.7.2 On-Premises
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Digital Signature End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Digital Signature Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Digital Signature Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Digital Signature Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 DocuSign
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Adobe
- 18.4 OneSpan
- 18.5 Annature
- 18.6 Vault Systems
- 18.7 Lawpath
- 18.8 Secured Signing
- 18.9 Elmo Software
- 18.10 PleaseSign
- 18.11 Zoho Sign
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

