
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Australia Functional Yogurt Market Size 2023 | USD 237.18 million |
| Australia Functional Yogurt Market, CAGR | 7.41% |
| Australia Functional Yogurt Market Size 2032 | USD 451.58 million |
Market Overview
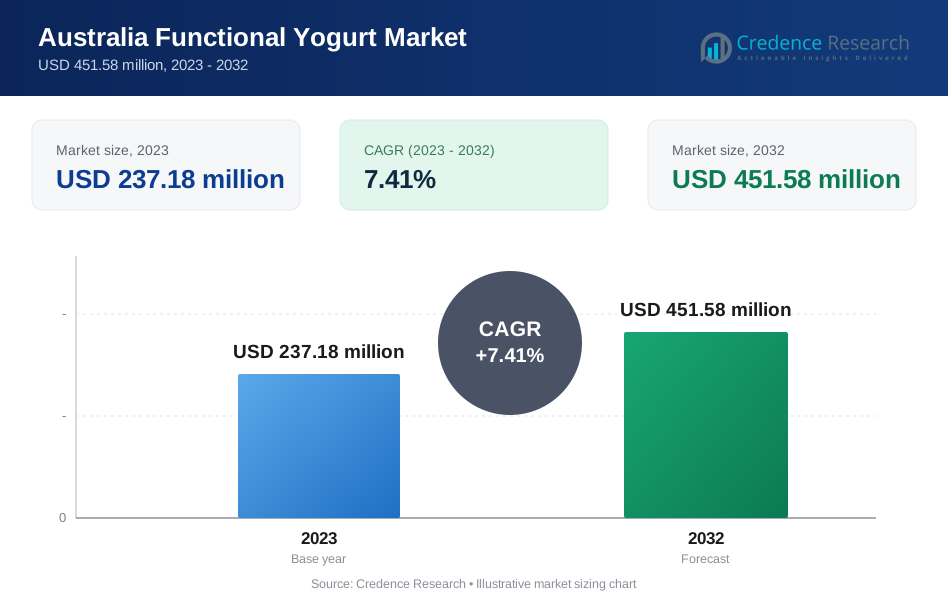
The Australia Functional Yogurt Market is projected to grow from USD 237.18 million in 2023 to USD 451.58 million by 2032, reflecting a compound annual growth rate (CAGR) of 7.41%.
The Australia Functional Yogurt market is driven by growing consumer awareness of the health benefits associated with functional foods, particularly probiotics, which are known to support digestive and immune health. Increasing demand for healthy snacks and convenient meal options, combined with a shift toward clean-label products, has further fueled market growth. Consumers are increasingly seeking yogurt products with added functional ingredients like protein, fiber, and vitamins to support overall wellness. Additionally, the rise of lactose-free, plant-based, and low-sugar variants has expanded the product range, catering to diverse dietary preferences. Innovative marketing strategies by key players and the introduction of new flavors and formulations are also driving consumer interest. The increasing popularity of wellness trends and the need for personalized nutrition are expected to continue influencing the market, creating a favorable environment for further growth in the functional yogurt segment in Australia.
The geographical landscape of the Australia Functional Yogurt market is primarily driven by regions with a strong consumer base focused on health and wellness. New South Wales and Victoria lead the market, with high demand for probiotics, low-fat, and organic yogurt options. These regions are characterized by urbanization, a health-conscious population, and a well-established retail network. Queensland and South Australia also show growth potential, driven by increasing awareness of functional foods and changing consumer lifestyles. Key players in the Australian functional yogurt market include global brands like Danone, which offers a wide range of yogurt products, and local players like SIMPLE LOVE and Huishan, catering to specific consumer preferences for organic and probiotic-rich options. Other important contributors include Mengniu, Yili, and Bright Dairy & Food Co. Ltd, which continue to expand their presence with innovative product offerings targeting diverse consumer needs in the region.
Market Insights
- The Australian Functional Yogurt market was valued at USD 237.18 million in 2023 and is expected to reach USD 451.58 million by 2032, growing at a CAGR of 7.41%.
- Rising health consciousness and increasing demand for probiotics, vitamins, and low-fat yogurts are key drivers of market growth.
- The growing trend of plant-based and organic products, along with flavored varieties, is shaping consumer preferences.
- Intense competition from both local and international brands like Danone and Mengniu is putting pressure on pricing strategies.
- Stringent health claim regulations and evolving consumer tastes pose challenges for brands trying to stay ahead of trends.
- Regions like New South Wales and Victoria dominate the market, with Queensland and South Australia showing growing demand.
- Sustainability and ethical sourcing are becoming increasingly important, influencing product development and consumer choices.
Market Drivers
Health and Wellness Focus
Consumers are increasingly focused on health and wellness, driving the demand for functional yogurts that offer various health benefits. Probiotics, a key component of many functional yogurts, are gaining popularity due to their positive effects on gut health. For instance, a review by Food & Function highlights that functional yogurt can alleviate symptoms of digestive disorders and enhance immune function. Additionally, functional yogurts fortified with vitamins and minerals are becoming a preferred choice for consumers seeking natural ways to boost immunity. Yogurts with added protein and low-fat content are also favored by those aiming for weight management solutions, reflecting the broader trend of health-conscious eating.
Diverse Product Offerings
The functional yogurt market in Australia is expanding due to a diverse range of product offerings that cater to various consumer preferences. The rising demand for plant-based alternatives has prompted the development of functional yogurts made from soy, almond, and oat milk, appealing to those with dietary restrictions or preferences. For instance, the Plant-Based Foods Association reports a significant increase in the consumption of plant-based yogurts as consumers shift towards dairy-free options. Furthermore, a variety of flavors, including exotic and seasonal options, are attracting a wide range of consumers. Health-focused yogurts targeting specific concerns such as digestive health, bone health, and stress relief are also gaining traction, further diversifying the market.
Convenience and On-the-Go Consumption
The need for convenience in today’s fast-paced lifestyle is pushing the growth of functional yogurt products that offer easy, on-the-go consumption. Single-serve cups, squeezable pouches, and other portable packaging formats are increasingly in demand as they cater to busy consumers looking for convenient and healthy snack options. Ready-to-eat varieties, such as pre-mixed yogurt with fruits, nuts, and seeds, offer an easy and nutritious meal or snack, further driving the appeal of functional yogurt for consumers with limited time.
Increasing Consumer Awareness and Government Initiatives
Consumer awareness is rising as brands actively educate their audiences about the health benefits of functional yogurt through marketing campaigns and in-store promotions. Social media platforms play a significant role in shaping consumer preferences, with influencers promoting healthy eating habits and functional foods. Additionally, government initiatives encouraging healthy eating and active lifestyles have led to greater incorporation of functional foods, such as yogurt, into consumer diets. These combined efforts are driving the growth and popularity of functional yogurt in Australia.
Market Trends
Health and Wellness Focus
Consumers are increasingly drawn to functional yogurt products due to their health benefits, particularly in supporting gut health and overall well-being. Probiotics are a key selling point, with many consumers seeking out yogurts that offer added probiotics for digestive health. Additionally, functional yogurts fortified with essential vitamins and minerals are growing in popularity as a natural way to boost immunity. For those focused on weight management, low-fat and high-protein yogurt options are highly favored, aligning with broader trends of healthier eating and nutritional mindfulness.
Plant-Based Alternatives
The rising popularity of plant-based diets is significantly influencing the yogurt market, driving demand for dairy-free alternatives. Consumers are increasingly opting for yogurt made from plant-based milks, such as soy, almond, oat, and coconut, as part of their transition to dairy-free lifestyles. These plant-based yogurts are often fortified with probiotics and other nutrients, providing similar health benefits as traditional dairy yogurt while catering to those with dietary restrictions. The expansion of plant-based options is a major trend, responding to the growing need for alternatives that align with ethical, environmental, and health-conscious values.
Innovative Flavors and Toppings
The demand for unique taste experiences is driving innovation in the functional yogurt market. Consumers are seeking out new and exciting flavors, from exotic fruits to bold spices and herbs, creating a more diverse range of yogurt products. For instance, Symrise In-Sight reports that flavors like peach-mango, honey-lavender, and orange cream are at the top of the trend list. Additionally, customizable options are becoming increasingly popular, as consumers enjoy the ability to personalize their yogurt experience with various toppings such as nuts, seeds, fruits, and honey. This trend highlights a shift toward more individualistic, enjoyable, and customizable food choices, allowing consumers to tailor their yogurt to their specific taste preferences and nutritional needs.
Convenience and Sustainability
Convenience continues to be a major driver in the functional yogurt market, with busy consumers seeking quick, easy, and healthy options. Single-serve packaging formats like cups and squeezable pouches are gaining popularity, catering to on-the-go lifestyles. For instance, the Asia Food Challenge report by Temasek indicates that rising affluence and growing incomes are driving changes in food consumption patterns in Asia, with consumers increasingly opting for premium food products. Pre-mixed yogurt with added fruits, nuts, and seeds also offers a quick, nutritious snack or meal. In addition, sustainability has become a key concern for consumers, with increasing demand for eco-friendly packaging options that reduce environmental impact. Ethical sourcing practices, including fair trade and animal welfare considerations, are also gaining importance as transparency in sourcing becomes a key factor in consumer purchasing decisions.
Market Challenges Analysis
Intense Competition and Consumer Preferences
The Australia Functional Yogurt market faces significant challenges due to intense competition from both domestic and international brands, such as Yoplait, Danone, and local players. This competitive landscape makes it difficult for new entrants to secure market share, often leading to price wars that can erode profit margins. In addition to pricing pressures, consumer preferences are constantly evolving, requiring brands to stay ahead of trends in flavor, ingredients, and health benefits. This dynamic environment makes it challenging for companies to consistently meet consumer demands. Furthermore, strict regulations on health claims limit marketing and branding strategies, preventing companies from fully capitalizing on health-related product benefits in their communications. Brands must navigate these complexities to effectively compete while maintaining profitability and consumer loyalty.
Supply Chain, Innovation, and Sustainability Challenges
Fluctuations in the cost of ingredients, such as dairy products and fruits, are a significant challenge for the functional yogurt market. Volatile ingredient costs can directly impact profitability, especially for brands that rely on premium ingredients. Additionally, potential supply chain disruptions, whether from natural disasters or global events, can affect product availability and quality, making it difficult to maintain consistent production. On the innovation front, continuously introducing new flavors, textures, and functional ingredients can be costly and time-consuming. The challenge is not only about innovation but also convincing consumers of the unique benefits of new products. Meanwhile, sustainability and ethical sourcing are becoming increasingly important to consumers. While brands must invest in eco-friendly packaging and responsible sourcing practices, these initiatives can be expensive and logistically challenging, further adding pressure to the bottom line.
Market Opportunities
The Australia Functional Yogurt market presents significant opportunities driven by increasing consumer demand for healthier, functional food options. As consumers become more health-conscious, the demand for yogurts that offer added health benefits such as probiotics, vitamins, and minerals continues to rise. There is a growing interest in products that support digestive health, immunity, and weight management, providing an opportunity for brands to develop and market functional yogurts that cater to these needs. Additionally, the rising popularity of plant-based diets presents a lucrative opportunity for dairy-free alternatives made from ingredients like soy, almond, oat, and coconut milk. Plant-based functional yogurts, often fortified with similar health benefits as their dairy counterparts, are increasingly appealing to both vegans and individuals with lactose intolerance.
Furthermore, the trend toward convenience continues to drive innovation in the market. Single-serve packaging and ready-to-eat yogurt varieties, such as those pre-mixed with fruits, nuts, and seeds, are becoming increasingly popular with busy consumers seeking quick and healthy snacks. The growing preference for customizable options also presents an opportunity, with consumers seeking personalized flavor combinations and toppings. Additionally, as sustainability and ethical sourcing become more important to consumers, brands that prioritize eco-friendly packaging and transparent sourcing practices are likely to gain a competitive edge. These opportunities allow companies to tap into emerging consumer trends while promoting health, convenience, and sustainability in their product offerings.
Market Segmentation Analysis:
By Product Type:
The Australia Functional Yogurt market is characterized by a diverse range of product types, each catering to specific consumer preferences. Probiotic yogurt is one of the leading segments, driven by the growing demand for gut health and digestive benefits. These yogurts are fortified with live cultures, making them highly popular among health-conscious consumers. Greek yogurt, known for its creamy texture and high protein content, appeals to those seeking a more indulgent yet nutritious option. Low-fat yogurt continues to be favored by consumers focused on weight management and reducing calorie intake. Organic yogurt, produced without synthetic pesticides or fertilizers, is gaining traction among consumers looking for cleaner and more natural food choices. Flavored yogurt, which includes a wide array of taste profiles from fruits to exotic spices, remains a favorite for those seeking variety and unique flavor experiences. These product types are shaping the market as brands cater to increasingly health-aware and flavor-driven consumers.
By Application:
In terms of application, functional yogurt in Australia is predominantly driven by health and wellness, sports nutrition, and weight management. Health and wellness remains the largest application segment, as consumers increasingly turn to functional foods that provide additional health benefits like probiotics, vitamins, and minerals. Sports nutrition is another key segment, where functional yogurts, often rich in protein and other nutrients, cater to athletes and active individuals looking to enhance performance and recovery. Weight management is also a significant driver, with low-fat and high-protein yogurts being popular choices for consumers seeking to maintain a balanced diet and healthy weight. Additionally, there is a growing demand for functional yogurt in other applications, including digestive health and immune support. These segments are indicative of the broader trend toward healthier, more specialized food products that meet diverse consumer needs.
Segments:
Based on Product Type:
- Probiotic Yogurt
- Greek Yogurt
- Low-fat Yogurt
- Organic Yogurt
- Flavored Yogurt
Based on Application:
- Health and Wellness
- Sports Nutrition
- Weight Management
- Others
Based on Ingredient:
- Probiotics
- Prebiotics
- Vitamins and Minerals
- Proteins
Based on Distribution Channel:
- Supermarkets/Hypermarkets
- Online Retailers
- Specialty Stores
- Convenience Stores
- Others
Based on the Geography:
- New South Wales
- Victoria
- Queensland
- Western Australia (WA)
- South Australia
Regional Analysis
New South Wales (NSW)
New South Wales (NSW) holds the largest market share, accounting for approximately 33% of the overall market. This dominance is driven by the high population density, urbanization, and a growing consumer base that prioritizes health and wellness. Victoria follows closely with a market share of 28%, bolstered by its large, diverse consumer population that is increasingly inclined toward health-conscious eating. These two regions lead in functional yogurt consumption, driven by the high demand for probiotic, organic, and low-fat variants.
Queensland
Queensland, with its growing health and wellness sector, accounts for 22% of the market share in Australia’s functional yogurt sector. The region’s expanding focus on healthy lifestyles, combined with a large tourism industry that brings in diverse consumer preferences, fuels the market demand for functional yogurt. Consumers in Queensland increasingly seek products that offer health benefits such as gut health and weight management, driving up the popularity of probiotics and low-fat yogurt. The market is further supported by the region’s strong retail presence, with supermarkets and health food stores stocking a wide variety of functional yogurt options.
South Australia
South Australia, though smaller in comparison, holds a market share of 10% in the functional yogurt market. The region has seen significant growth in consumer interest for health-focused food products, particularly organic and probiotic yogurts. The increasing number of health-conscious consumers and a shift toward cleaner, natural products are key drivers of this growth. The rise in sustainable food practices and ethical sourcing also aligns with the preferences of South Australian consumers, boosting demand for organic and environmentally friendly options. This segment of the market is expected to continue growing as more consumers turn to functional foods that promote overall well-being.
Western Australia
Western Australia holds the smallest market share, accounting for 7% of the functional yogurt market in Australia. While its share is relatively modest, the region is witnessing an increase in demand for health-oriented products, particularly among the active and outdoor-oriented population. The growth of functional yogurt in Western Australia is largely driven by the increasing awareness of the health benefits of probiotics and other functional ingredients. The region’s large agricultural industry also supports the availability of locally sourced ingredients, which appeals to consumers seeking fresh and sustainable options. Although it remains a smaller market, the potential for growth in Western Australia is promising as health trends continue to gain traction.
Key Player Analysis
- Danone
- Yili
- Mengniu
- SANYUAN
- Bright Dairy & Food Co. Ltd
- SIMPLE LOVE
- Junlebao
- Huishan
- Huaming Ranch
- Langege
- XIAOXINIU
- Terun
- New Hope Group
Competitive Analysis
The competitive landscape of the Australia Functional Yogurt market is dominated by both global and local players, each bringing unique offerings to meet the growing demand for health-focused dairy products. Key players such as Danone, Mengniu, Yili, Bright Dairy & Food Co. Ltd, SIMPLE LOVE, and Huishan lead the market with a wide range of yogurt products. Leading players in the market offer a variety of products, focusing on health benefits such as probiotics, weight management, and immune-boosting properties. For instance, many companies are increasingly emphasizing the development of low-fat, high-protein, organic, and plant-based options to meet the rising demand for functional foods. In addition to traditional dairy-based offerings, there is a growing presence of dairy-free alternatives catering to the plant-based and lactose-intolerant segments. The market also sees a push for unique flavors, packaging innovations, and targeted formulations, with many brands offering products enriched with vitamins, minerals, and functional ingredients. Despite the potential for growth, price pressure remains a challenge due to the competition from both local and international brands. Companies are focusing on enhancing consumer engagement through education and social media marketing to differentiate themselves in an increasingly crowded market. Additionally, sustainability concerns and ethical sourcing practices are becoming key differentiators, influencing both product development and brand loyalty.
Recent Developments
- In February 2024, Epigamia, a brand known for its innovative dairy products, launched a new variant of Greek yogurt that combines the creaminess of yogurt with the wholesome goodness of oats and a seed mix. This product aims to cater to health-conscious consumers looking for nutritious and satisfying snack options.
- In April 2024, Danone North America introduced REMIX, an innovative line of yogurts and dairy snacks designed to cater to diverse snacking preferences throughout the day. This launch reflects the growing trend of consumers seeking convenient, flavorful, and nutritious options for snacking.
- In March 2024, Bored Cow made waves in the dairy alternative market by launching its innovative animal-free yogurt, touted as the “first of its kind.” This groundbreaking product is crafted using fermented proteins, offering a sustainable and ethical alternative to traditional dairy yogurt without compromising on taste or texture.
- In 2023, Chobani, has introduced Chobani® Zero Sugar* Drinks. This innovative zero sugar beverage offers a healthier option for consumers looking to reduce their sugar intake while enjoying the goodness of yogurt. The launch of Chobani’s zero sugar drinks demonstrates the brand’s commitment to meeting evolving consumer preferences for healthier alternatives.
- In 2023, Chobani presents the Low-Fat Greek Yogurt Shake, tailored to meet the needs of health-conscious consumers looking for a convenient, nutritious on-the-go snack. This delectable shake harmonizes the benefits of Greek yogurt with a gratifying and delightful taste, offering individuals a wholesome choice for their fast-paced lives.
- In 2023, Califia Farms also entered the yogurt market with its Dairy-Free Yogurt Cultured Nutmilk Drink. This plant-based yogurt alternative is made from nut milk and offers a dairy-free option for consumers with specific dietary preferences or restrictions. The introduction of such dairy-free alternatives reflects the increasing demand for plant-based products in the market.
- In 2023, Morinaga launched an Aloe Yogurt Drink specifically targeting consumers looking for refreshing and hydrating yogurt options. This product combines the benefits of yogurt with the soothing properties of aloe vera, providing a unique and invigorating experience for consumers.
Market Concentration & Characteristics
The Australian Functional Yogurt market exhibits moderate market concentration, with a mix of global and local players competing for market share. While larger international brands dominate the space, local companies are carving out niches by focusing on specialized product offerings such as organic, probiotic-rich, and plant-based yogurts. This competition fosters innovation, particularly in the development of yogurt with added health benefits, including immunity support, weight management, and digestive health. The market is characterized by a diverse range of products catering to various consumer preferences, from low-fat and high-protein options to dairy-free alternatives made from soy, almond, and oat milk. Consumer demand for functional foods with clear health benefits continues to rise, encouraging brands to prioritize quality ingredients and functional additives. Additionally, convenience plays a significant role in the market, with single-serve packaging formats and ready-to-eat options gaining popularity among busy, health-conscious consumers. Sustainability is also an emerging trend, with companies focusing on eco-friendly packaging and ethical sourcing of ingredients. While price competition remains a challenge, particularly with larger multinational brands, the market continues to evolve with an increasing focus on product differentiation, health claims, and consumer engagement strategies, contributing to a dynamic and growing sector.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, Ingredient, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Australian Functional Yogurt market is expected to experience steady growth, driven by increasing health consciousness and demand for functional foods.
- Probiotic and plant-based yogurt products will continue to see rising demand as consumers prioritize digestive health and lactose-free alternatives.
- Innovation in flavors and functional ingredients will play a significant role in differentiating products and capturing consumer interest.
- Consumers will increasingly seek yogurt products fortified with additional health benefits, such as immune-boosting vitamins and minerals.
- Convenience-driven packaging, such as single-serve cups and portable pouches, will remain a key factor in product development.
- The market will see continued growth in the organic yogurt segment as consumers opt for cleaner, more natural ingredients.
- Sustainability initiatives, including eco-friendly packaging and ethical sourcing, will become critical for maintaining brand loyalty.
- Online retail platforms and direct-to-consumer models will continue to expand as e-commerce gains traction in the food and beverage industry.
- Regional preferences will drive product diversification, with some regions focusing more on plant-based or low-fat options, while others prioritize traditional dairy-based yogurts.
- Increased competition among both global and local players will foster ongoing innovation, challenging brands to stay ahead in terms of product quality and marketing strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Australia Functional Yogurt market?
What factors are driving the growth of the Australia Functional Yogurt market?
What are the key segments within the Australia Functional Yogurt market?
What are some challenges faced by the Australia Functional Yogurt market?
Who are the major players in the Australia Functional Yogurt market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Australia Functional Yogurt Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Australia Functional Yogurt Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 237.18 million → 2032: USD 451.58 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Australia Functional Yogurt Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Australia Functional Yogurt Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Australia Functional Yogurt Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Australia Functional Yogurt Market Drivers
- 3.3 Australia Functional Yogurt Market Restraints & Challenges
- 3.4 Australia Functional Yogurt Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Australia Functional Yogurt Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Australia Functional Yogurt Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Australia Functional Yogurt category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Australia Functional Yogurt Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Australia Functional Yogurt Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Australia Functional Yogurt market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Australia Functional Yogurt Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Australia Functional Yogurt Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Australia Functional Yogurt Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Australia Functional Yogurt (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Australia Functional Yogurt Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Australia Functional Yogurt Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Australia Functional Yogurt Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Australia Functional Yogurt Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Australia Functional Yogurt Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Australia Functional Yogurt Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Australia Functional Yogurt Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Australia Functional Yogurt Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Australia Functional Yogurt Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
