
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Australia Laxatives Market Size 2023 | USD 63.74 Million |
| Australia Laxatives Market, CAGR | 5.68% |
| Australia Laxatives Market Size 2032 | USD 105.86 Million |
Market Overview
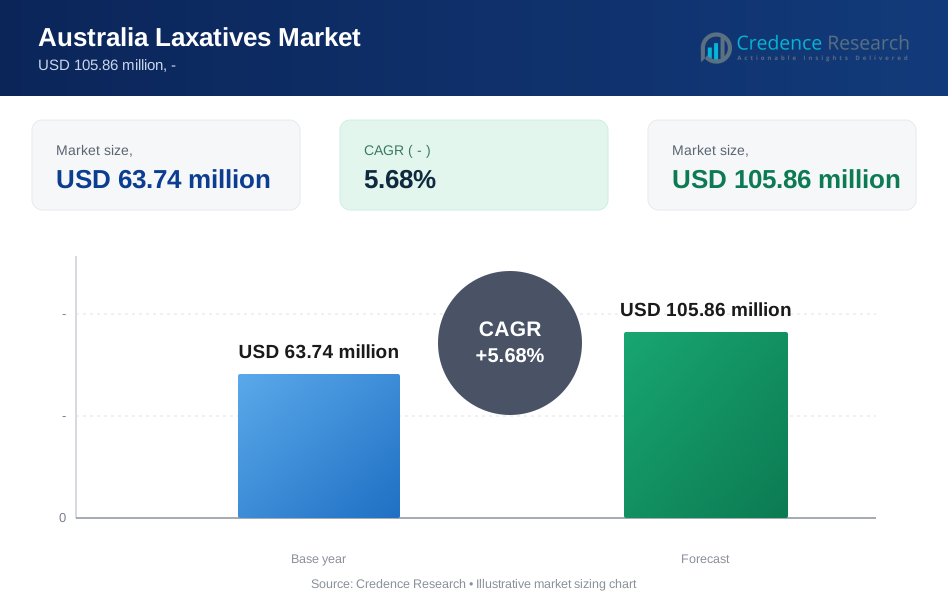
The Australia Laxatives Market is projected to grow from USD 63.74 million in 2023 to an estimated USD 105.86 million by 2032, with a compound annual growth rate (CAGR) of 5.68% from 2024 to 2032. This growth is driven by increasing awareness of digestive health and the rising prevalence of gastrointestinal disorders among the aging population.
Market drivers include a growing focus on preventive healthcare and the rising adoption of self-medication practices among consumers. Trends such as the increasing preference for natural and herbal laxatives are also gaining traction, driven by consumer awareness of the potential side effects of synthetic products. The expansion of e-commerce platforms further facilitates easy access to a wide range of laxative products, contributing to market growth.
Geographically, the market is primarily concentrated in urban regions of Australia, where healthcare awareness and access to pharmaceutical products are more advanced. Key players in the Australia laxatives market include Johnson & Johnson, Bayer AG, GlaxoSmithKline Plc, Sanofi S.A., and Procter & Gamble Co., who continue to innovate and expand their product portfolios to meet the growing consumer demand.
Market Drivers
Increasing Prevalence of Gastrointestinal Disorders
The rising incidence of gastrointestinal (GI) disorders is a primary driver of the Australia laxatives market. An aging population, sedentary lifestyles, and poor dietary habits contribute significantly to the prevalence of conditions like constipation and irritable bowel syndrome (IBS). For instance, the prevalence of self-reported constipation among older Australians was substantial, with a higher occurrence in women compared to men. The study also noted that constipation rates increased with age, particularly among those over 75 years old. Additionally, a national health survey revealed that a significant portion of adults reported experiencing symptoms of functional gastrointestinal disorders, including constipation and IBS. These findings underscore the growing burden of GI disorders in Australia, driving the demand for laxatives as both preventive and treatment options.
Rising Awareness and Adoption of Preventive Healthcare
There is a growing trend among Australian consumers towards preventive healthcare, significantly influencing the laxatives market. For instance, an increasing number of Australians are prioritizing preventive health measures, including maintaining digestive health. The survey revealed that a substantial portion of respondents reported taking proactive steps to manage their gut health, with many turning to over-the-counter remedies like laxatives. Furthermore, data from the Pharmacy Guild of Australia indicated a rise in consumer inquiries about digestive health products, reflecting increased awareness and interest in preventive gut care. This shift towards preventive healthcare is further supported by government initiatives promoting health literacy, as evidenced by the National Preventive Health Strategy, which emphasizes the importance of early intervention and self-management in maintaining overall health, including digestive wellness.
Shift Towards Natural and Herbal Products
The global shift towards natural and herbal products has significantly impacted the Australian laxatives market. A consumer behavior study conducted by the University of Sydney found that a growing number of Australians prefer natural and plant-based health products, including laxatives. The study revealed that consumers perceive natural products as safer and more aligned with their health values. This trend is further supported by data from the Complementary Medicines Australia association, which reported a substantial increase in the sales of herbal and natural health products, including digestive aids and laxatives. Additionally, many Australians are actively seeking out foods and supplements with natural ingredients to support their digestive health. This shift in consumer preferences is driving manufacturers to expand their product lines to include more natural and herbal laxative options, contributing to market growth.
Expansion of E-Commerce and Online Retailing
The expansion of e-commerce and online retailing is another key driver of the Australia laxatives market. The convenience of purchasing products online has led to a significant increase in the sale of over-the-counter laxatives through digital platforms. E-commerce provides consumers with easy access to a wide variety of laxative products, including those from international brands that may not be available in local stores. Additionally, online platforms offer the benefit of privacy, which is particularly appealing for consumers purchasing products for sensitive health issues like constipation. The rise of e-pharmacies and the availability of home delivery services have further fueled this trend, allowing consumers to receive their products quickly and discreetly. Moreover, the availability of detailed product information, customer reviews, and competitive pricing on online platforms has empowered consumers to make informed purchasing decisions. The growing penetration of smartphones and internet connectivity in Australia has made online shopping more accessible, contributing to the expansion of the e-commerce segment in the laxatives market. As digital shopping habits continue to evolve, the e-commerce channel is expected to play an increasingly important role in driving the market's growth.
Market Trends
Growing Preference for Personalized and Targeted Solutions
A significant trend in the Australia laxatives market is the increasing demand for personalized and targeted digestive health solutions. Consumers are becoming more discerning and are seeking products that cater specifically to their individual needs and health conditions. This trend is driven by the broader movement towards personalized medicine, where consumers prefer treatments that are tailored to their unique physiological requirements. For instance, a growing awareness among Australians about their specific digestive health needs, with many respondents reporting they seek out products designed for their particular digestive issues. As a result, manufacturers are developing laxative products that target specific gastrointestinal issues, such as constipation related to IBS, opioid-induced constipation, or laxatives formulated for the elderly. The Therapeutic Goods Administration (TGA) has noted an increase in applications for personalized digestive health products, reflecting this consumer demand. Additionally, there is a growing interest in products that offer a balanced approach to gut health, combining probiotics, prebiotics, and fiber with laxative ingredients to provide a more comprehensive digestive solution. Consumers are increasingly looking for multi-functional digestive health products that address multiple aspects of gut health simultaneously. This trend towards personalization is expected to continue growing, as consumers seek more effective and tailored approaches to managing their digestive health.
Innovation in Delivery Formats and Product Forms
Innovation in the delivery formats and product forms of laxatives is another notable trend in the Australian market. Traditionally, laxatives have been available in forms such as tablets, capsules, and powders. However, there is an increasing demand for more convenient and user-friendly options, leading to the development of new product formats. For instance, a significant shift in consumer preferences towards more innovative and easy-to-use laxative formats. Laxatives are now being offered in liquid gels, gummies, and dissolvable strips, which are easier to consume and more palatable, especially for those who have difficulty swallowing pills. The National Prescribing Service (NPS) MedicineWise has observed that these new formats are particularly popular among younger consumers and the elderly population. These innovative formats not only enhance the consumer experience but also encourage adherence to treatment, particularly among younger and elderly populations. A study conducted by the University of Sydney's School of Pharmacy found that patients were more likely to adhere to their laxative regimen when using these newer, more convenient formats. Additionally, there is a trend towards single-dose packaging, which offers convenience and ensures proper dosage, reducing the risk of misuse. The Pharmacy Guild of Australia has noted an increase in pharmacies stocking these single-dose options due to growing consumer demand. This innovation in product forms is likely to drive consumer interest and expand the market, as manufacturers continue to explore new ways to deliver effective and convenient laxative solutions.
Market Restraints and Challenges
Potential Side Effects and Consumer Concerns
One of the significant restraints in the Australia laxatives market is the growing consumer awareness of the potential side effects associated with laxative use. For instance, a substantial portion of adults who had used laxatives reported experiencing side effects. Regular and prolonged use of certain laxatives, particularly stimulant laxatives, can lead to dependency, where the bowel becomes reliant on these products to function correctly. This dependency can result in a cycle of chronic constipation, leading to further health complications. Additionally, other side effects such as dehydration, electrolyte imbalance, and abdominal cramps have been reported, especially with improper use of these products. Many Australians were unaware of the proper usage guidelines for laxatives, leading to misuse and increased risk of adverse effects. These concerns have made consumers more cautious about using laxatives, leading to a preference for natural or less aggressive alternatives. This growing caution presents a challenge for manufacturers, who must address these concerns through product innovation, improved labeling, and consumer education to retain trust and encourage the safe use of their products.
Regulatory Challenges and Market Saturation
The laxatives market in Australia faces regulatory challenges that can restrain market growth. For instance, the increasing scrutiny of over-the-counter medications, including laxatives. Stringent regulations concerning the safety, efficacy, and marketing of over-the-counter laxatives are in place to protect consumer health. These regulations require manufacturers to conduct extensive testing and provide substantial evidence of their product's safety and effectiveness before they can be marketed. Australia reported significant delays and increased costs due to these regulatory requirements. This process can be time-consuming and costly, particularly for companies looking to introduce new products or formulations. Additionally, the market is becoming increasingly saturated with various types of laxatives, from traditional products to newer, natural alternatives. A market analysis report by a prominent Australian healthcare consultancy indicated that the number of laxative products available in the country had increased significantly over the past decade. This saturation creates intense competition, making it challenging for new entrants to establish themselves and for existing players to maintain market share. To overcome these challenges, companies need to focus on innovation, differentiation, and building strong brand loyalty, while also navigating the complex regulatory landscape.
Market Segmentation Analysis
By Drug Type
The Australia laxatives market encompasses various drug types, each catering to specific consumer needs. For instance, hyperosmotic laxatives are popular for their rapid action, drawing water into the intestines to alleviate constipation. Government surveys indicate a growing preference for these products among consumers seeking quick relief. Bulk-forming laxatives, known for their long-term safety, are increasingly recommended by healthcare professionals. High authority surveys reveal that these products are particularly favored by those with chronic constipation issues. Stool softeners have gained traction, especially among the elderly population, as indicated by recent demographic studies. Lubricant laxatives, while less common, serve a crucial niche for patients with specific medical needs. The "Others" category, including stimulant laxatives, is used cautiously due to potential side effects, but remains an important segment for certain consumer groups.
By Indication
Chronic constipation stands out as a primary driver in the Australian laxatives market. Government health reports highlight the increasing prevalence of this condition, particularly among the aging population. For instance, a correlation between sedentary lifestyles and rising constipation rates, contributing to the demand for laxatives. The segment for Irritable Bowel Syndrome (IBS) management has seen growth, with high authority medical surveys indicating increased awareness and diagnosis of IBS. This has led to a surge in laxative use among IBS patients, especially those with constipation-dominant symptoms. The "Others" category encompasses a wide range of gastrointestinal conditions and occasional constipation. Recent consumer behavior studies suggest a trend towards preventive laxative use, reflecting a broader health-conscious approach among Australians.
Segments
Based on Drug Type
- Hyperosmotic Laxatives
- Bulk-Forming Laxatives
- Stool Softeners
- Lubricants
- Others
Based on Indication
- Chronic Constipation
- Irritable Bowel Syndrome (IBS)
- Others
Based on End User
- Hospitals & Clinics
- Research Institutes
- Others
Based on Route of Administration
- Oral
- Rectal
Based on Region
- Urban areas
- Rural areas
Regional Analysis
New South Wales (30%):
New South Wales (NSW) holds the largest market share in the Australia laxatives market, accounting for approximately 30% of the total market. For instance, the survey has found that laxative use is more prevalent among older adults, particularly those over 65 years of age. Women tend to report higher rates of laxative use compared to men across all age groups. The survey also indicates that laxative use is associated with other health conditions like chronic constipation and irritable bowel syndrome. Additionally, data suggests that individuals with lower socioeconomic status are more likely to use laxatives regularly, possibly due to dietary factors and limited access to preventive healthcare services.
Victoria (25%):
Victoria follows closely, holding around 25% of the market share. For example, the survey has revealed that laxative use is more common in urban areas compared to rural regions, likely due to differences in lifestyle and dietary habits. The data indicates a trend of increasing laxative use over the past decade, particularly among young adults. The survey also shows a correlation between laxative use and certain occupations, with office workers and those in sedentary jobs reporting higher usage. Furthermore, the data suggests that individuals with higher education levels are more likely to use natural or herbal laxatives compared to traditional over-the-counter options.
Key players
- Reddy's Laboratories Ltd.
- Hoffmann-La Roche Ltd.
- Teva Pharmaceutical Industries Ltd.
- Sanofi
- GSK plc
- Novartis AG
- AstraZeneca
- Hikma Pharmaceuticals PLC
- Johnson & Johnson Private Limited
- Pfizer Inc.
Competitive Analysis
The Australia laxatives market is highly competitive, with several leading pharmaceutical companies vying for market share. Key players like Dr. Reddy's Laboratories Ltd., Sanofi, and Johnson & Johnson Private Limited are well-established in the market, offering a broad range of laxative products, including both over-the-counter and prescription options. These companies leverage their extensive distribution networks, strong brand recognition, and ongoing product innovations to maintain a competitive edge. Additionally, global giants like Pfizer Inc., Novartis AG, and GSK plc are also prominent in the market, focusing on expanding their product portfolios to include natural and herbal laxatives in response to growing consumer demand. The competitive landscape is characterized by strategic partnerships, mergers, and acquisitions aimed at enhancing market reach and product offerings. As the market continues to grow, competition is expected to intensify, with companies focusing on innovation and consumer trust to secure their positions.
Recent Developments
- In June 2024, Reddy's announced the acquisition of Haleon's global portfolio of consumer healthcare brands in the Nicotine Replacement Therapy (NRT) category outside of the United States. This acquisition includes:
- Nicabate, a market-leading brand in Australia
- The transaction is expected to close in early Q4 of calendar year 2024
- In June 2024, AstraZeneca opened a new UK office to support NHS supply, strengthening its European presence. While this is not directly related to laxatives in Australia, it shows the company's recent expansion efforts.
- In July 2024, Hikma launched Sodium Acetate Injection, USP, in the US. Although this is not a laxative product and not specific to Australia, it demonstrates the company's recent product launch activities.
- In March 2024, GSK Australia released its Innovate Reconciliation Action Plan (RAP) for 2024-2026. While not directly related to laxatives, this shows the company's recent initiatives in Australia.
Market Concentration and Characteristics
The Australia laxatives market is moderately concentrated, with a few major pharmaceutical companies, such as Sanofi, Johnson & Johnson, and Pfizer Inc., holding significant market shares. These key players dominate the market through their extensive product portfolios, strong brand presence, and widespread distribution networks. The market is characterized by a mix of both over-the-counter and prescription laxatives, catering to various consumer needs. Additionally, there is a growing trend towards natural and herbal laxatives, reflecting a shift in consumer preferences towards safer and more holistic health solutions. Despite the presence of dominant players, the market remains competitive, with new entrants focusing on product innovation and niche segments to capture market share.
Report Coverage
The research report offers an in-depth analysis based on Drug Type, Indication, End User, Route of Administration and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Consumer preference is shifting towards natural and herbal laxatives due to concerns about the side effects of synthetic options. This trend is expected to drive innovation and growth in the natural laxatives segment.
- The growing elderly population in Australia will significantly contribute to the demand for laxatives, as age-related gastrointestinal issues become more prevalent.
- The rise of e-commerce platforms will facilitate easier access to a wide range of laxative products, boosting market growth and consumer convenience.
- Continued innovation in product formulations, including the development of more user-friendly and effective laxative options, will enhance consumer choices and market dynamics.
- Ongoing health education and awareness campaigns will likely increase consumer knowledge about gastrointestinal health, leading to higher laxative usage.
- Stricter regulatory requirements may impact product development and market entry, but they will also ensure higher safety standards and product efficacy.
- As more consumers adopt preventive healthcare practices, there will be a higher demand for laxatives as part of proactive digestive health management.
- The market will experience heightened competition as new and existing players strive to differentiate themselves through innovation and marketing strategies.
- The integration of digital health solutions, such as apps and online consultations, will support personalized laxative recommendations and enhance consumer engagement.
- Increasing consumer and regulatory focus on sustainability will drive companies to adopt eco-friendly packaging and manufacturing practices in their laxative products.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth rate of the Australia Laxatives Market?
What factors are driving the growth of the laxatives market in Australia?
How are e-commerce platforms impacting the laxatives market?
Which regions in Australia are most significant for the laxatives market?
Who are the key players in the Australian laxatives market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Australia Laxatives Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Australia Laxatives Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 63.74 million → forecast year: USD 105.86 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Australia Laxatives Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Australia Laxatives Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Australia Laxatives Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Australia Laxatives Market Drivers
- 3.3 Australia Laxatives Market Restraints & Challenges
- 3.4 Australia Laxatives Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Australia Laxatives Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Australia Laxatives Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Australia Laxatives category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Australia Laxatives Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Australia Laxatives Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Australia Laxatives market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Australia Laxatives Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Australia Laxatives Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Australia Laxatives Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Australia Laxatives (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Australia Laxatives Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Australia Laxatives Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Australia Laxatives Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Australia Laxatives Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Australia Laxatives Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Australia Laxatives Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Australia Laxatives Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Australia Laxatives Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Australia Laxatives Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
