
Market Insights
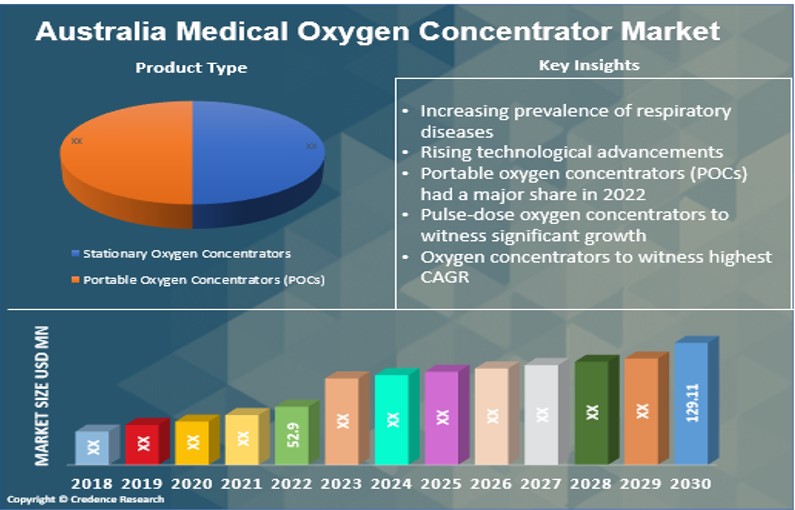
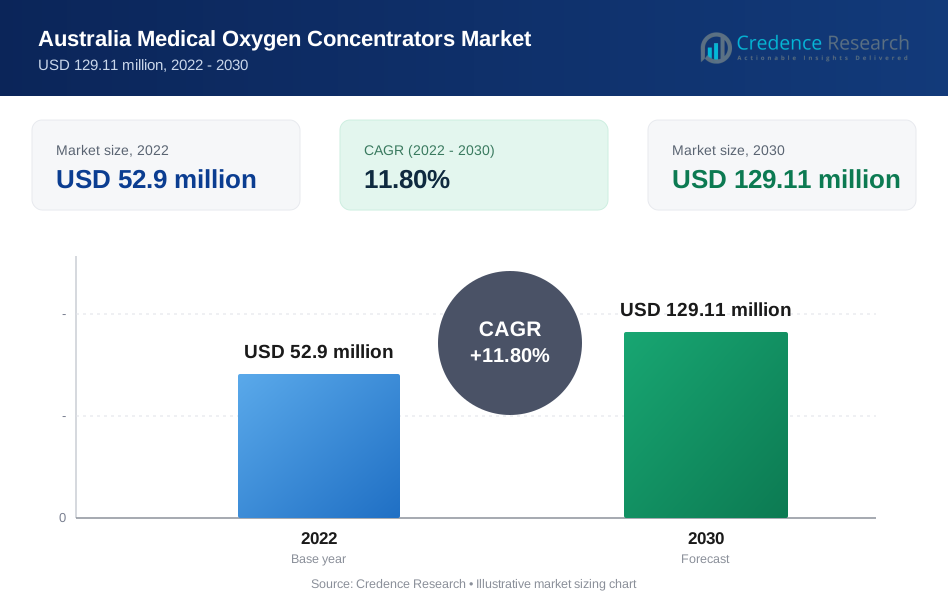
- The Australian demand for medical oxygen concentrators was valued at USD 52.9 million in 2022 and is expected to reach USD 129.11 million in 2030, growing at a CAGR of 11.80% between 2023 and 2030.
- Portable oxygen concentrators (POCs) are the leading segment by product type. On the other hand, stationary oxygen concentrators are expected to grow at a strong CAGR.
- The leading technology segment is continuous-flow oxygen concentrators.
- The CAGR for travel and ambulatory patients is expected to be the highest during the projection period.
- During the forecast time frame, the oxygen concentrators category will likely have the highest CAGR.
- The homecare settings segment is estimated to have the greatest CAGR during the forecast period.
- The direct sales segment will likely have the highest CAGR during the prediction period.
- An increase in government initiatives to raise awareness of COPD, increasing disposable incomes, rising active role of industry associations, telehealth, and remote monitoring are the key factors boosting the Australian medical oxygen concentrator market.
- Due to the escalating necessity for portable oxygen concentrators (POCs), the advancement of oxygen delivery system innovation, and the incorporation of smart home technologies, the Australian medical oxygen concentrator market has many prospects for growth.
Executive Summary
Market Definition
The Australian medical oxygen concentrator market is the economy sector focused on producing, promoting, and distributing devices to draw out and deliver concentrated oxygen for medical use. This market is crucial for supporting patients with breathing problems, such as those with persistent respiratory diseases. It comprises various manufacturers, suppliers, and healthcare service providers, encouraging the advancement and accessibility of medical oxygen concentrator technology in Australia.
Market Overview
The market for Australian medical oxygen concentrators has been expanding steadily in recent years. Between 2023 and 2030, it is anticipated to rise at a CAGR of 11.80%. The market was estimated to be worth USD 52.9 million in 2022, and it is anticipated to be worth USD 129.11 million in 2030.
Several governmental and non-governmental organisations have started offering services and programmes to educate the public about COPD and how to manage it. For instance, to increase public knowledge of COPD and help patients manage their condition, the World Health Organisation (WHO) and the National Heart, Lung, and Blood Institute (NHLBI) established the global initiative for chronic obstructive lung disease.
The Australian government also started the National Tobacco Strategy 2012–2018, a programme to lessen tobacco-related harm in Australia to increase awareness about COPD. The health ministers supported this approach to reduce smoking's negative effects on health, society, and the economy and promote the general health of Australians. In Australia, persons with mental illnesses or other drug or alcohol addictions, those from lower socioeconomic backgrounds, people with disabilities, people without housing, and those incarcerated have significantly higher smoking rates.
Tobacco usage continues to be a major cause of mortality and disability in Australia. Approximately 15,000 Australians pass away from smoking-related illnesses every year, and 3.3 million Australians are current smokers. The Australian market for medical oxygen concentrators is anticipated to expand due to the growing number of government campaigns raising awareness of COPD.
Segmentation by Product Types
- Portable oxygen concentrators (POCs) are the market leader by product type. POCs are used in outpatient settings for medical procedures that require oxygen support. Their portability allows patients to receive oxygen therapy during diagnostic tests, minor surgeries, or other medical interventions.
- The stationary oxygen concentrators category will exhibit a sizable CAGR during the projected period. Stationary oxygen concentrators are a crucial component of long-term oxygen therapy, which involves continuous oxygen administration to individuals with chronic lung diseases. This therapy helps improve survival rates and enhances the quality of life for patients with severe respiratory conditions.
Segmentation by Technology
- The main technology category is continuous-flow oxygen concentrators. CFOCs deliver a continuous and steady oxygen flow to the patient, ensuring a consistent supply of therapeutic oxygen. This is particularly beneficial for individuals who require a stable flow rate throughout their respiratory cycle.
- The pulse-dose oxygen concentrators category will likely register a significant CAGR during forecasting. POCs are designed to operate on battery power, enabling patients to use them outside traditional settings. This feature is particularly important for individuals requiring oxygen therapy during travel, outdoor activities, or emergencies.
Segmentation by Patient Segments
- The travel and ambulatory patients category will experience the highest CAGR during the projection period. Many portable oxygen concentrators are approved for aeroplane use, allowing individuals with respiratory conditions to travel by air. This feature is essential for those who need oxygen support during flights.
- Other patient segments, such as homecare patients, healthcare facilities, and high-flow oxygen therapy, also contributes to the demand for Australian medical oxygen concentrator.
Segmentation by Oxygen Source
- Oxygen concentrators will likely have the highest CAGR during the projection period. These devices produce oxygen with specified purity levels, ranging from 87% to 95% or higher. The purity level selected depends on the patient's prescribed oxygen therapy requirements.
- Other oxygen sources, such as liquid oxygen systems and compressed oxygen cylinders, also contribute to the demand for Australian medical oxygen concentrators.
Segmentation by End Users
- Homecare settings are expected to have the highest CAGR during the prediction period. Oxygen concentrators are beneficial for older people who may have age-related respiratory problems or comorbidities at home. The need for home-based oxygen therapy to improve respiratory health is growing as the population ages.
- Other end users, such as hospitals and healthcare facilities, travel and tourism, long-term care facilities, and others, also contributes to the demand for Australian medical oxygen concentrator.
Segmentation by Sales Channels
- Throughout the forecast duration, the category for direct sales is anticipated to have the greatest CAGR. Manufacturers may target speciality medical centres, such as pulmonary or respiratory care centres, that concentrate on particular medical specialities. Direct sales to these centres guarantee equipment that satisfies the particular needs of specialised care.
- Other sales channels, such as medical equipment suppliers and distributors, online retail, and rental services, also contribute to the demand for Australian medical oxygen concentrators.
Numerous technological advancements have contributed to expanding the Australian medical oxygen concentrator market. These developments improve oxygen concentrators' overall performance, portability, and efficiency, making them better tools for patient care. Oxygen concentrators that are extremely lightweight and portable have been made possible by advancements in engineering and materials. Increased mobility and flexibility in their regular activities enhance patients' quality of life. Oxygen concentrators have smart sensors that monitor oxygen concentration levels and patient usage. Alarms and notifications alert patients and caregivers in case of any deviations from prescribed settings or potential issues with the device.
One of the main factors propelling the medical oxygen concentrator market in Australia is the rising awareness of the advantages of home oxygen therapy. Increasing awareness empowers patients to take an active role in managing their respiratory conditions. Knowledge about the benefits of home oxygen therapy encourages individuals to seek prescribed treatments and adhere to therapy plans. Home-based oxygen therapy is often more cost-effective than inpatient care. The awareness of the economic benefits for both patients and the healthcare system encourages the adoption of medical oxygen concentrators for home use.
Key Highlights of the Report
The Australian medical oxygen concentrator market is segmented by product types, technology, patient segments, oxygen source, end users, and sales channels. Portable oxygen concentrators (POCs) are the market spearhead, and continuous-flow oxygen concentrators are the top technology segment. During the forecast period, the travel and ambulatory patients category is expected to grow at the highest CAGR, and the oxygen concentrators category is anticipated to experience the highest CAGR.
Medical oxygen concentrator use is highly encouraged by industry organisations, including Australia's Home Oxygen Therapy Association (HOTAA) and the Australian Association of Respiratory Care (AARC). These organisations push for laws supporting home oxygen therapy and encouraging technological improvements while offering information and assistance to patients and medical professionals. Industry associations advocate for policies that support the accessibility and affordability of medical oxygen concentrators. Their active role in influencing healthcare policies can create an environment conducive to growth in Australia's medical oxygen concentrator market. Industry associations collaborate with healthcare providers to understand their needs, challenges, and preferences. This collaboration fosters the development of tailored solutions, promoting the integration of medical oxygen concentrators into healthcare practices.
Australia's increasing healthcare expenses may significantly expand the market for medical oxygen concentrators. Higher healthcare expenditure often correlates with increased access to healthcare services, which can lead to more individuals seeking medical attention for respiratory conditions, driving the demand for medical oxygen concentrators. Furthermore, higher healthcare expenditure allows for implementing patient-centric healthcare approaches, such as personalized treatment plans that involve medical oxygen concentrators tailored to individual patient needs.
Which Key Factors Are Driving The Australian Medical Oxygen Concentrator Market?
The increasing prevalence of respiratory diseases, the rising ageing population, technological advancements, and growing awareness of the benefits of home oxygen therapy are driving the expansion of Australia's medical oxygen concentrator market.
What Are The Key Challenges In The Australian Market For Medical Oxygen Concentrators?
Several challenges, including high initial costs, stringent regulatory compliance, and limited reimbursement policies, impede the growth of the Australian medical oxygen concentrator market.
What Market Opportunities Exist For Australia Medical Oxygen Concentrator?
The expanding integration of telehealth, rising demand for customised paediatric care solutions, and remote patient monitoring. These factors create significant opportunities for the Australian medical oxygen concentrator market.
Market Drivers
Several factors influence the market for Australian medical oxygen concentrators. The main factors influencing the market for Australian medical oxygen concentrators are as follows:
Increasing Prevalence of Respiratory Diseases
The market for medical oxygen concentrators in Australia is expanding due to the rising incidence of respiratory illnesses. There's an increasing need for practical and efficient respiratory support systems as respiratory illnesses like asthma, chronic obstructive pulmonary disease (COPD), and others increase. Medical oxygen concentrators are essential for those with impaired respiratory function to ensure a steady and consistent oxygen supply. Environmental pollution, changing lifestyles, and an ageing population drive this trend and contribute to the increased prevalence of respiratory illnesses. Medical oxygen concentrators are essential for maintaining and enhancing the quality of life for patients with respiratory disorders because they are required for long-term oxygen therapy in clinical settings and at home. Healthcare providers are increasingly recognizing the benefits of oxygen concentrators in delivering targeted and personalized respiratory care. This growing awareness, coupled with advancements in technology, is expected to drive innovation in the design and functionality of these devices, further propelling market growth in response to the rising healthcare demands associated with respiratory diseases in Australia.
Market Restraints
Several challenges could prevent the expansion of the Australian market for medical oxygen concentrators. Among them are the following:
Low Use of Oxygen Concentrators for Medical Purposes
The use of medical oxygen cylinders could be higher in Australia despite the growing acceptability of oxygen therapy. Patients still choose to use portable oxygen cylinders because oxygen concentrators are associated with significant maintenance costs. Oxygen cylinders, readily available and supplying extremely pure oxygen, compete directly with oxygen concentrators for market share and customer base. Additionally, they are quite dependable, require little upkeep, and run without electricity. On the other hand, oxygen concentrators need electricity to function. Stationary medical oxygen concentrators require electricity to convert oxygen from the air into compressed oxygen, while portable oxygen concentrators use batteries. Backup oxygen cylinders must be kept on hand if the medical oxygen cylinder experiences a mechanical breakdown or there is no electricity.
Medical oxygen concentrators lose some oxygen purity when a high flow rate is needed. In addition to this, medical oxygen concentrators also come with the need for routine maintenance, heat, noise, and vibration generation. While they solve some of these issues, portable medical oxygen concentrators are highly costly. Furthermore, non-continuous oxygen flow requires a different kind of cylinder. Portable medical oxygen cylinders are appropriate for individuals with minimal oxygen requirements. Numerous businesses are working to find a solution because the challenges above with medical oxygen concentrations are impeding the growth of Australia's medical oxygen concentrator market.
Opportunities
The Australian market for medical oxygen concentrators presents significant potential opportunities. The following is an example of these:
Rising Customized Solutions for Pediatric Care
Developing and promoting customised solutions for child care presents a significant opportunity to drive market expansion for medical oxygen concentrators in Australia. A particular and underserved market area can be addressed by customising oxygen concentrators to match the specific requirements of paediatric patients. Children with respiratory problems or chronic illnesses frequently need specialised respiratory support. Designing medical oxygen concentrators specifically for pediatric use, with considerations for size, weight, and ease of use, ensures that these devices are well-suited for children, promoting better compliance and comfort. Precision in oxygen delivery is crucial for pediatric patients. Customized solutions can offer precise dosing options suitable for the unique respiratory needs of children, providing optimal therapeutic benefits while minimizing potential risks.
Competitive Landscape
Key Players
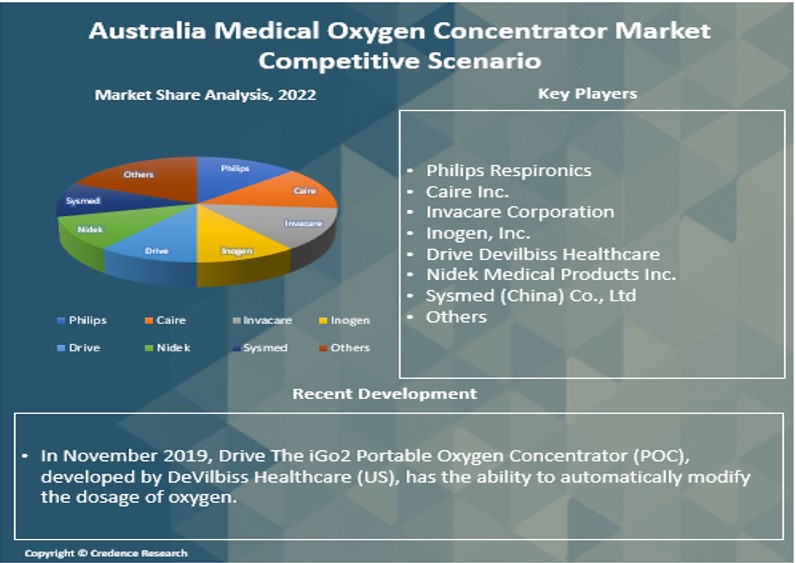
The Australian market for medical oxygen concentrators is very competitive, with many powerful players. Some of the leading market participants and their corresponding market shares are listed below:
- Philips Respironics
- Caire Inc.
- Invacare Corporation
- Inogen, Inc.
- Drive Devilbiss Healthcare
- Nidek Medical Products Inc.
- Sysmed (China) Co., Ltd
- Others
These companies prioritise mergers and acquisitions, expanding their distribution network, and developing new products to remain competitive.
The leading competitors in the Australian market for medical oxygen concentrators are constantly seeking an advantage by releasing new products and advancements.
In December 2022, The US Food and Drug Administration approved Inogen, Inc.'s (US) Rove Series portable oxygen concentrators.
In January 2021, Oxygen therapy manufacturer CAIRE Inc. introduced the SAROS 4000 Oxygen System, a portable oxygen concentrator designed specifically for military applications.
Summary of Key Findings
- The Australian medical oxygen concentrator market continues to grow due to the increasing prevalence of respiratory diseases.
- The market is segmented by product types, technology, patient segments, oxygen sources, end users, and sales channels.
- Portable oxygen concentrators (POCs) are the most preferred product types in the market.
- Continuous-flow oxygen concentrators are the most common in terms of technology.
- Regarding CAGR, travel and ambulatory patients is expected to grow fastest during the forecast period.
- The categories for oxygen concentrators will likely see the highest CAGR during the anticipated time frame.
- The Australia medical oxygen concentrator market is highly competitive, with key players including Philips Respironics, Caire Inc., Invacare Corporation, Inogen, Inc., Drive Devilbiss Healthcare, Nidek Medical Products Inc., Sysmed (China) Co., Ltd, and others.
Future Outlook
- Optimistic viewpoint for Australia's medical oxygen concentrator industry with noteworthy growth potential.
- Rising technological advancements are one of the main elements driving Australia's medical oxygen concentrator market expansion.
- During the projected period, the high initial costs for Australian medical oxygen concentrators might significantly challenge the market's expansion.
- Foremost companies must concentrate on product innovation, expanding their market reach, and maintaining competitive pricing to stay ahead.
Segmentation
- By Product Types
- Stationary Oxygen Concentrators
- Portable Oxygen Concentrators (POCs)
- By Technology
- Continuous Flow Oxygen Concentrators
- Pulse-Dose Oxygen Concentrators
- By Patient Segments
- Homecare Patients
- Healthcare Facilities
- Travel and Ambulatory Patients
- High-Flow Oxygen Therapy
- By Oxygen Source
- Oxygen Concentrators
- Liquid Oxygen Systems
- Compressed Oxygen Cylinders
- By End Users
- Hospitals and Healthcare Facilities
- Homecare Settings
- Travel and Tourism
- Long-Term Care Facilities
- Others
- By Sales Channels
- Medical Equipment Suppliers and Distributors
- Online Retail
- Direct Sales
- Rental Services
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
How big is the Australian market for medical oxygen concentrators right now?
What is the anticipated growth rate of the Australian medical oxygen concentrator market from 2023 to 2030?
Which market category is in the lead for the product types?
Which segment is leading the market in terms of technology?
Which oxygen source segment is estimated to have the highest CAGR throughout the forecast period?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Australia Medical Oxygen Concentrators Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Region & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2022; forecast to 2030)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Australia Medical Oxygen Concentrators Snapshot
- 2.1.1 Market Size – Historical (2022) & Forecast (2022-2030) (2022: USD 52.9 million → 2030: USD 129.11 million)
- 2.1.2 Volume & Revenue – Regional Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Australia Medical Oxygen Concentrators Segmentation Snapshot
- 2.2.1 Market Split by Country – 2022 vs. 2030
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2022
- 2.3.2 Top 10 Players by Volume Share – 2022 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Australia Medical Oxygen Concentrators Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Australia Medical Oxygen Concentrators Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Country
- 3.2 Australia Medical Oxygen Concentrators Drivers
- 3.3 Australia Medical Oxygen Concentrators Restraints & Challenges
- 3.4 Australia Medical Oxygen Concentrators Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Australia Medical Oxygen Concentrators Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Australia Medical Oxygen Concentrators Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regional & Country Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Australia Medical Oxygen Concentrators category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Australia Medical Oxygen Concentrators Attractiveness Analysis
- 4.1.1 By Country – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Country – Absolute Revenue Growth Through 2030
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Country – Incremental Demand Through 2030
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Country Opportunity Scorecards
- 4.5.1 Priority Country 1
- 4.5.2 Priority Country 2
- 4.5.3 Priority Country 3
- 4.5.4 Priority Country 4
Note: Priority countries are selected from within the region covered by the study. Numbered entries are indicative and are populated with relevant country names based on market size, growth potential, and strategic relevance.
Chapter 5. Australia Medical Oxygen Concentrators Cross-Border Trade & Market Access Analysis
- 5.1 Intra-Regional & Extra-Regional Trade Overview
- 5.1.1 Regional Export Value by Country (2022)
- 5.1.2 Regional Export Volume by Country (2022) (Volume Where Applicable)
- 5.1.3 Regional Import Value by Country (2022)
- 5.1.4 Regional Import Volume by Country (2022) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2022)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2022)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: Cross-border analysis applies where relevant to Australia Medical Oxygen Concentrators. Country trade flows distinguish intra-regional activity from trade with markets outside the region. Regional external trade totals exclude intra-regional flows to avoid double counting. Classifications and transaction measures follow the market scope; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Australia Medical Oxygen Concentrators Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2022
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Australia Medical Oxygen Concentrators Share Analysis – 2022
- 6.2.1 Regional Revenue Share by Company
- 6.2.2 Regional Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Country
- 6.2.4 Market Share Evolution (the historical period vs. 2022)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Regional Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Australia Medical Oxygen Concentrators Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure by Country Within the Region
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Australia Medical Oxygen Concentrators (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Australia Medical Oxygen Concentrators
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Australia Medical Oxygen Concentrators – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2022 & 2030) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2022-2030)
Chapter 8. Country Market Analysis – Regional Overview
- 8.1 Country Market Overview Within the Region
- 8.1.1 Country Volume Share Within the Region (Where Applicable)
- 8.1.2 Country Revenue Share Within the Region
- 8.1.3 Market Volume by Country (Where Applicable)
- 8.1.4 Market Revenue by Country
- 8.1.5 Country Forecasts Through 2030
- 8.2 Cross-Country Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. Australia Medical Oxygen Concentrators – Priority Country 1
Chapter 10. Australia Medical Oxygen Concentrators – Priority Country 2
Chapter 11. Australia Medical Oxygen Concentrators – Priority Country 3
Chapter 12. Australia Medical Oxygen Concentrators – Priority Country 4
Chapter 13. Australia Medical Oxygen Concentrators Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Regional Market Focus & Country Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – Country-Level Estimates & Regional Aggregation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
