
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Australia Metal Cutting Machine Market Size 2023 | USD 90.83 million |
| Australia Metal Cutting Machine Market, CAGR | 5.52% |
| Australia Metal Cutting Machine Market Size 2032 | USD 147.82 million |
Market Overview
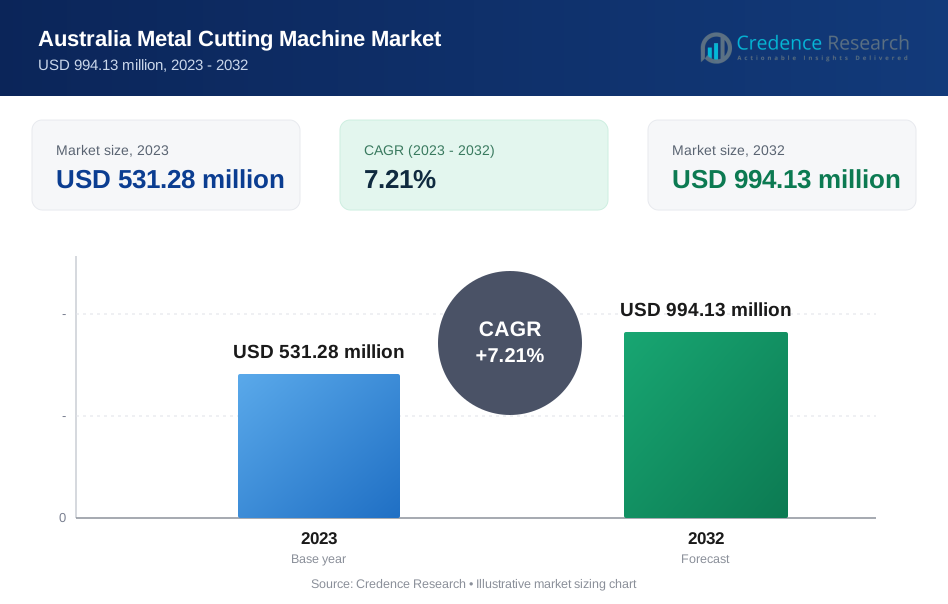
The Australia Metal Cutting Machine Market is projected to grow from USD 90.83 million in 2023 to an estimated USD 147.82 million by 2032, with a compound annual growth rate (CAGR) of 5.52% from 2024 to 2032. This growth is driven by the increasing demand for precision engineering and the expansion of the manufacturing sector in the country.
Key drivers of the market include the rising adoption of automation in manufacturing industries, which enhances productivity and efficiency. Additionally, the increasing investments in infrastructure and construction projects are fueling the demand for advanced metal cutting machines. Trends such as the integration of IoT and Industry 4.0 technologies in metal cutting machines are also contributing to market growth by providing real-time monitoring and improved operational capabilities.
Geographically, the market is segmented into regions including New South Wales, Victoria, Queensland, and others. New South Wales and Victoria are expected to hold significant market shares due to the concentration of manufacturing industries in these regions. Key players in the Australia Metal Cutting Machine Market include Amada Co., Ltd., Trumpf GmbH + Co. KG, Bystronic Laser AG, Mitsubishi Electric Corporation, and Coherent, Inc. These companies are focusing on innovation and strategic partnerships to strengthen their market positions and cater to the evolving needs of the industry.
Market Drivers
Adoption of Automation in Manufacturing Industries
The adoption of automation in manufacturing industries has become a crucial driver for the Australia Metal Cutting Machine Market. With the increasing need for precision, efficiency, and productivity, manufacturers are turning towards automated metal cutting machines. These machines offer numerous advantages, such as reducing human errors, enhancing production speed, and ensuring consistent quality. For instance, the Australian Government's first National Robotics Strategy aims to boost robotics and automation technologies to build a "Future Made in Australia," potentially adding up to $600 billion per annum to GDP and increasing productivity growth by up to 150%. Automation in metal cutting processes not only optimizes the workflow but also significantly lowers operational costs in the long run. Automated systems equipped with advanced technologies like CNC (Computer Numerical Control) enable precise cutting, drilling, and shaping of metals, which are essential for modern manufacturing requirements. Moreover, the integration of robotics with metal cutting machines allows for seamless operations, reducing the dependency on manual labor and increasing overall output. This shift towards automation is further propelled by the need for meeting stringent quality standards and reducing lead times in the competitive manufacturing sector.
Infrastructure Development and Construction Projects
The robust growth of infrastructure development and construction projects in Australia is another key driver propelling the demand for metal cutting machines. As the government and private sector invest heavily in infrastructure, including roads, bridges, commercial buildings, and residential complexes, there is a substantial increase in the requirement for metal cutting equipment. For instance, the Australian Government has allocated $4.1 billion over seven years from 2024-25 for 65 new priority infrastructure projects across the country. Metal cutting machines are integral in fabricating structural components, frameworks, and other metal parts essential for construction. The rise in urbanization and the subsequent demand for modern infrastructure have led to an upsurge in construction activities, thereby driving the market for metal cutting machines. Additionally, the development of smart cities and the refurbishment of existing infrastructure necessitate advanced metal cutting solutions that offer precision and efficiency. The construction sector's reliance on metal cutting machines for creating customized metal components further accelerates the market's growth, aligning with the ongoing and upcoming infrastructure projects across the country. For example, the total construction work done in Australia was valued at $64,032.5 million in the March quarter of 2024, highlighting the significant scale of construction activities.
Technological Advancements and Integration of IoT
Technological advancements in metal cutting machines, coupled with the integration of IoT (Internet of Things), are significantly influencing the market. The advent of Industry 4.0 has brought about a paradigm shift in manufacturing processes, with smart factories and interconnected devices becoming the norm. Metal cutting machines equipped with IoT capabilities offer real-time monitoring, predictive maintenance, and enhanced operational efficiency. For instance, Industry 4.0 technologies, such as AI and machine learning, are being utilized to analyze large datasets, optimize project timelines, and enhance risk assessment in infrastructure projects. These smart machines can collect and analyze data, providing valuable insights into machine performance, wear and tear, and potential downtimes. This predictive maintenance capability helps in minimizing unplanned disruptions and extending the lifespan of the machines. Furthermore, the integration of IoT enables remote monitoring and control of metal cutting operations, allowing for increased flexibility and reduced downtime. Manufacturers are increasingly adopting these advanced metal cutting solutions to stay competitive and meet the evolving demands of their clients. The continuous innovations in machine design, such as laser and plasma cutting technologies, also contribute to the market's growth by offering superior precision and speed compared to traditional cutting methods.
Expansion of the Aerospace and Automotive Industries
The expansion of the aerospace and automotive industries in Australia serves as a significant driver for the metal cutting machine market. Both industries require high precision and quality in metal components, which can only be achieved through advanced metal cutting machines. In the aerospace sector, the demand for lightweight yet durable metal parts necessitates the use of sophisticated cutting technologies that can handle materials like titanium, aluminum, and composites. Similarly, the automotive industry relies on metal cutting machines for producing engine components, body parts, and other critical metal assemblies. The growing focus on electric vehicles (EVs) further boosts the need for specialized metal cutting solutions to manufacture components specific to EV technology. The aerospace and automotive industries' emphasis on innovation and efficiency drives the adoption of advanced metal cutting machines that offer superior performance and accuracy. As these industries continue to expand and evolve, the demand for state-of-the-art metal cutting machines is expected to rise, supporting the market's growth.
Market Trends
Integration of Advanced Technologies and Digitalization
One of the prominent trends in the Australia Metal Cutting Machine Market is the integration of advanced technologies and the shift towards digitalization. As industries move towards Industry 4.0, the adoption of smart manufacturing practices has become increasingly prevalent. Metal cutting machines are now being equipped with advanced technologies such as Artificial Intelligence (AI), Machine Learning (ML), and the Internet of Things (IoT). These technologies enable real-time monitoring, predictive maintenance, and data-driven decision-making, enhancing the overall efficiency and productivity of metal cutting operations. For instance, the Australian Industry Group reported that the manufacturing sector's investment in digital technologies has increased by 30% since 2020, driven by the need for greater efficiency and competitiveness. IoT-enabled metal cutting machines can communicate with other smart devices, facilitating seamless operations and reducing downtime. AI and ML algorithms help in optimizing cutting processes by analyzing data and identifying patterns that can improve precision and reduce waste. Additionally, the use of computer-aided design (CAD) and computer-aided manufacturing (CAM) software has become more widespread, allowing for the creation of intricate designs and the automation of manufacturing processes. This trend towards digitalization not only improves the quality and consistency of metal cutting but also reduces operational costs and increases competitiveness in the market.
Growing Demand for Eco-Friendly and Sustainable Solutions
Another significant trend in the Australia Metal Cutting Machine Market is the growing demand for eco-friendly and sustainable solutions. As environmental concerns continue to rise, industries are increasingly focusing on adopting green manufacturing practices. Metal cutting machine manufacturers are responding to this demand by developing machines that are energy-efficient and produce minimal waste. For instance, the use of fiber laser cutting technology has gained popularity due to its lower energy consumption and reduced environmental impact compared to traditional CO2 laser cutting. According to a report by the Australian Manufacturing Forum, the adoption of fiber laser technology has increased by 25% over the past two years, driven by its efficiency and sustainability benefits. Additionally, advancements in waterjet cutting technology, which uses a high-pressure stream of water mixed with abrasive materials to cut metals, offer an eco-friendly alternative with no heat-affected zones and minimal waste production. The trend towards sustainability is also reflected in the materials used for machine components, with manufacturers opting for recyclable and biodegradable materials wherever possible. Furthermore, companies are implementing recycling programs and waste management systems to minimize their carbon footprint. The emphasis on sustainability not only helps in protecting the environment but also enhances the brand image of companies, attracting environmentally conscious customers and investors. This trend is expected to continue shaping the market, driving innovation and the development of greener metal cutting solutions.
Market Restraints and Challenges
High Initial Investment and Maintenance Costs
One of the primary restraints in the Australia Metal Cutting Machine Market is the high initial investment and ongoing maintenance costs associated with advanced metal cutting machines. Modern metal cutting technologies, such as laser cutting, plasma cutting, and waterjet cutting, require substantial capital outlay for procurement and installation. For instance, a report from the Australian Manufacturing Forum highlights that the average cost of a high-end laser cutting machine can exceed AUD 500,000, making it a significant financial burden for many businesses. Small and medium-sized enterprises (SMEs), which form a significant portion of the manufacturing sector, often find it challenging to allocate the necessary financial resources for such investments. Additionally, the complexity and sophistication of these machines necessitate regular maintenance and skilled operators, further escalating operational costs. The need for specialized training and the potential downtime during maintenance can also hinder productivity, making it difficult for smaller companies to justify the investment. These financial barriers can limit the adoption of advanced metal cutting machines, slowing down the overall market growth and restricting technological advancements within the industry.
Shortage of Skilled Labor and Technical Expertise
Another significant challenge facing the Australia Metal Cutting Machine Market is the shortage of skilled labor and technical expertise. The operation and maintenance of advanced metal cutting machines require a high level of technical knowledge and experience. However, there is a growing skills gap in the manufacturing sector, with a limited number of workers possessing the necessary qualifications to operate these sophisticated machines. For instance, a report by Jobs and Skills Australia indicates that 50% of occupations in the Technicians and Trades Workers category are experiencing national shortages, underscoring the critical need for skilled labor. This shortage is exacerbated by the rapid pace of technological advancements, which continually raise the bar for the skills required. Companies are often compelled to invest in extensive training programs to upskill their workforce, which can be both time-consuming and costly. Furthermore, the lack of skilled operators can lead to suboptimal use of metal cutting machines, reducing efficiency and increasing the likelihood of errors and machine downtime. This skills deficit not only impacts productivity but also impedes the adoption of new technologies, as companies may be reluctant to invest in advanced equipment without the assurance of having adequately trained personnel to manage them. Addressing this challenge is crucial for the sustained growth and competitiveness of the metal cutting machine market in Australia.
Market Segmentation Analysis
By Product
Laser cutting machines are gaining significant traction due to their precision, speed, and ability to cut a variety of materials with minimal thermal distortion, making them highly efficient for intricate tasks in industries like aerospace and electronics. For instance, the Australian government's investment in advanced manufacturing technologies has driven the adoption of laser cutting machines, particularly in the aerospace sector, where precision and efficiency are paramount. Waterjet cutting machines, utilizing high-pressure water mixed with abrasives, are preferred where heat generation is a concern, with rising demand in aerospace, automotive, and defense for their versatility and precision. According to a survey by the Australian Bureau of Statistics, the manufacturing sector's investment in waterjet cutting technologies has increased significantly, reflecting the industry's need for versatile and precise cutting solutions. Plasma cutting machines are valued for cutting thick metal sheets quickly and efficiently, commonly used in automotive and construction industries. For example, the construction boom in New South Wales and Victoria has led to a higher demand for plasma cutting machines, which are essential for fabricating structural components. Flame cutting machines, or oxy-fuel cutting machines, are popular for heavy-duty tasks in shipbuilding and construction. The Australian shipbuilding industry, supported by government contracts and investments, frequently utilizes flame cutting machines for their ability to handle large and thick metal sheets. Other types, such as electric discharge machines (EDM) and mechanical cutting machines, cater to niche applications with specialized capabilities, offering versatility for specific industry requirements. The Australian government's focus on supporting SMEs through grants and incentives has also encouraged the adoption of these specialized cutting technologies.
By Application
The automotive industry is a major consumer of metal cutting machines due to the need for precision in manufacturing components like engine parts, body panels, and structural components, with the trend towards electric vehicles further boosting demand for advanced solutions. For instance, the "Make in Victoria" initiative has led to increased investments in the local automotive manufacturing sector, driving demand for high-precision metal cutting machines. The defense and aerospace industries also require high precision and reliability, with metal cutting machines essential for producing complex components for aircraft, defense equipment, and space applications, driven by growing investments in these sectors. According to the Australian Department of Defence, there has been a significant increase in funding for defense projects, which in turn has spurred the demand for advanced metal cutting technologies. In the electrical and electronics industry, metal cutting machines are used to produce intricate and precise components, necessitating cutting-edge technologies. The Australian electronics manufacturing sector has seen a rise in the use of laser and waterjet cutting machines, as reported by industry surveys, to meet the high standards of precision required. The construction industry relies on these machines for fabricating structural components, frameworks, and other metal parts, with ongoing infrastructure development in Australia driving demand for high-performance solutions. For example, the Australian Infrastructure Plan highlights numerous large-scale projects that require advanced metal cutting technologies for construction and maintenance. Additionally, industries such as shipbuilding, medical device manufacturing, and general fabrication require specialized metal cutting solutions to meet their unique production needs and standards. The Australian government's support for innovation in medical device manufacturing, through initiatives like the Medical Research Future Fund, has led to increased adoption of precise metal cutting machines in the sector.
Segments
Based on Product
- Laser Cutting Machine
- Waterjet Cutting Machine
- Plasma Cutting Machine
- Flame Cutting Machine
- Others
Based on Application
- Automotive
- Defense & Aerospace
- Electrical & Electronics
- Construction
- Others
Based on Region
- New South Wales
- Victoria
- Queensland
- Others
Regional Analysis
New South Wales (35%)
New South Wales (NSW) holds the largest market share in the Australia Metal Cutting Machine Market, accounting for approximately 35% of the total market. This dominance is attributed to the region's robust industrial base and significant investments in manufacturing and infrastructure development. For instance, the NSW government has approved a major refurbishment of BlueScope's 60-year-old plate mill, injecting an estimated $650 million into the economy and increasing production capacity to 600,000 tonnes per year. The state's proactive approach to adopting advanced technologies and automation in manufacturing processes further fuels the demand for high-precision metal cutting machines. Additionally, the government's focus on infrastructure projects, such as the Sydney Metro expansion and various urban development initiatives, drives the need for efficient metal cutting solutions.
Victoria (28%)
Victoria is the second-largest market for metal cutting machines in Australia, with a market share of around 28%. The state's diverse industrial sector, encompassing automotive manufacturing, defense, aerospace, and electronics, contributes significantly to the demand for metal cutting machines. For instance, Victoria's infrastructure development projects, including transport and urban renewal initiatives, have been bolstered by significant public and private investments, leading to increased demand for metal cutting technologies. The presence of leading manufacturing companies and research institutions fosters a conducive environment for the adoption of cutting-edge metal cutting technologies. Moreover, the state's emphasis on innovation and technological advancements in manufacturing processes positions it as a key player in the market.
Key players
- TRUMPF
- AMADA Co. Ltd
- ESAB Corporation
- Bystronic Laser AG
- WARDJet
- Flow International Corporation
- Coherent Corp.
- Omax Corporation
- Boye Laser Applied Technology Co., Ltd
- Han's Laser Technology Industry Group Co., Ltd.
Competitive Analysis
The Australia Metal Cutting Machine Market is highly competitive, with key players such as TRUMPF, AMADA Co. Ltd, and ESAB Corporation leading the market. These companies are known for their innovative technologies and extensive product portfolios, catering to diverse industrial needs. Bystronic Laser AG and Coherent Corp. also hold significant market shares, offering advanced laser cutting solutions. Companies like WARDJet and Flow International Corporation specialize in waterjet cutting technology, providing eco-friendly and precise cutting options. Omax Corporation and Boye Laser Applied Technology Co., Ltd are recognized for their high-quality, cost-effective solutions. Han's Laser Technology Industry Group Co., Ltd. is notable for its broad range of laser technologies and strong market presence. The competition in the market drives continuous innovation, ensuring that advanced and efficient metal cutting machines are available to meet the evolving demands of various industries.
Recent Developments
- In October 17, 2022, ESAB Corporationannounced the acquisition of Ohio Medical, a leader in respiratory care products. This acquisition aims to expand ESAB’s portfolio in the healthcare sector, although no specific developments in tablet counting machines were reported.
- In October 17, 2023, TRUMPF launched its TruMatic 5000 manufacturing cell with the new SheetMaster at Blechexpo in Stuttgart. The system offers fully automated laser-cutting, punching, and forming capabilities, enhancing productivity and part quality while reducing energy consumption. The new SheetMaster technology enables a fully automated material flow within the manufacturing cell, from loading and unloading the machine to removing finished parts.
Market Concentration and Characteristics
The Australia Metal Cutting Machine Market exhibits a moderate level of market concentration, characterized by the presence of several key players such as TRUMPF, AMADA Co. Ltd, and ESAB Corporation, which dominate a significant portion of the market. These companies leverage their extensive product portfolios, technological advancements, and strong customer relationships to maintain their competitive edge. The market is also marked by a blend of global and local manufacturers, offering a diverse range of metal cutting solutions, from laser and plasma cutting to waterjet and flame cutting technologies. The competitive landscape fosters continuous innovation, with companies focusing on enhancing precision, efficiency, and automation in their products to cater to the evolving needs of industries such as automotive, aerospace, and construction. Despite the dominance of major players, there is ample opportunity for smaller companies and new entrants to capture market share by offering specialized and cost-effective solutions.
Report Coverage
The research report offers an in-depth analysis based on Product, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The adoption of automation in metal cutting processes is expected to rise, enhancing efficiency and reducing operational costs across various industries.
- Ongoing advancements in laser and waterjet cutting technologies will drive market growth by offering higher precision and speed.
- Integration of IoT in metal cutting machines will enable real-time monitoring and predictive maintenance, improving operational efficiency and reducing downtime.
- Growing environmental concerns will push manufacturers to develop eco-friendly cutting solutions, such as energy-efficient laser technologies and waterjet systems with minimal waste.
- The demand for high-precision metal parts in the expanding aerospace and automotive industries will continue to drive the market for advanced metal cutting machines.
- Significant investments in infrastructure development projects will boost the demand for metal cutting machines, especially in construction and urban development.
- To address the skills gap, increased focus on training programs and certifications for operators will enhance the effective use of advanced metal cutting technologies.
- Manufacturers will increasingly seek customizable and flexible metal cutting solutions to meet specific production needs, fostering innovation in machine design.
- Australian manufacturers will enhance their competitiveness in the global market by adopting state-of-the-art metal cutting technologies and improving product quality.
- New market entrants and smaller companies offering specialized and cost-effective solutions will find opportunities to capture market share in niche segments.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Australia Metal Cutting Machine Market?
What are the key drivers of market growth?
Which regions hold significant market shares?
Who are the major players in the Australia Metal Cutting Machine Market?
How is technological advancement influencing the market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Australia Metal Cutting Machine Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Australia Metal Cutting Machine Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 531.28 million → 2032: USD 994.13 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Australia Metal Cutting Machine Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Australia Metal Cutting Machine Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Australia Metal Cutting Machine Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 Australia Metal Cutting Machine Drivers
- 3.3 Australia Metal Cutting Machine Restraints & Challenges
- 3.4 Australia Metal Cutting Machine Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Australia Metal Cutting Machine Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Australia Metal Cutting Machine Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Australia Metal Cutting Machine category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Australia Metal Cutting Machine Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. Australia Metal Cutting Machine Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2023)
- 5.1.2 Export Volume by Destination Country (2023) (Where Applicable)
- 5.1.3 Import Value by Source Country (2023)
- 5.1.4 Import Volume by Source Country (2023) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to Australia Metal Cutting Machine in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Australia Metal Cutting Machine Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 Australia Metal Cutting Machine Share Analysis – 2023
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Australia Metal Cutting Machine Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Australia Metal Cutting Machine (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Australia Metal Cutting Machine
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Australia Metal Cutting Machine – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. Australia Metal Cutting Machine – Priority Domestic Market 1
Chapter 10. Australia Metal Cutting Machine – Priority Domestic Market 2
Chapter 11. Australia Metal Cutting Machine – Priority Domestic Market 3
Chapter 12. Australia Metal Cutting Machine – Priority Domestic Market 4
Chapter 13. Australia Metal Cutting Machine Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
