
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Australia Vegan Fast Food Market Size 2023 | USD 159.64 million |
| Australia Vegan Fast Food Market, CAGR | 7.50% |
| Australia Vegan Fast Food Market Size 2032 | USD 306.07 million |
Market Overview
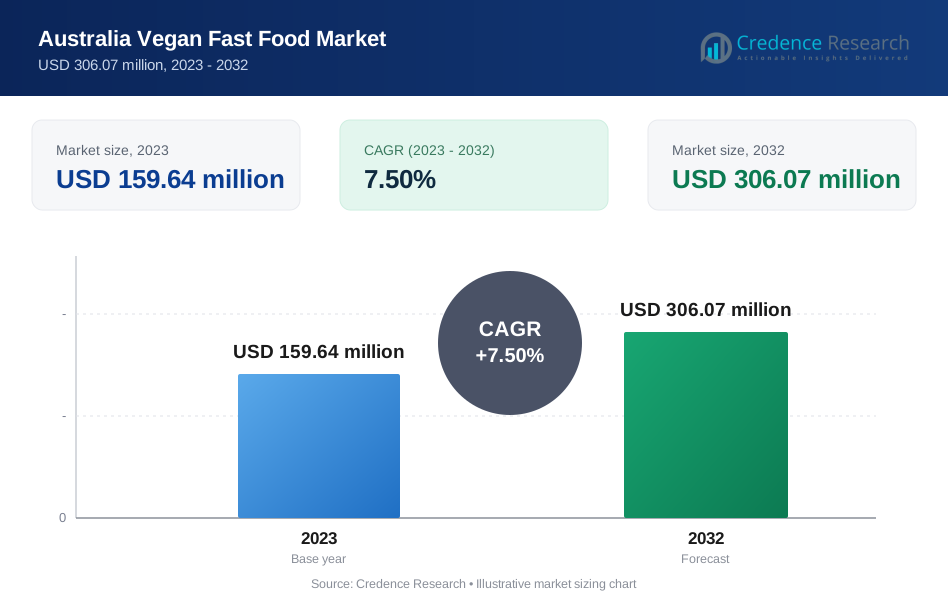
The Australia Vegan Fast Food Market is projected to grow from USD 159.64 million in 2023 to an estimated USD 306.07 million by 2032, with a compound annual growth rate (CAGR) of 7.50% from 2024 to 2032. This significant growth reflects the increasing consumer shift towards plant-based diets driven by health concerns, environmental sustainability, and animal welfare considerations. The market size expansion indicates a robust demand trajectory, underscoring the rising popularity and acceptance of vegan fast food options among Australian consumers.
Several factors drive the growth of the vegan fast food market in Australia. The primary driver is the increasing awareness and adoption of veganism and vegetarianism, influenced by health benefits such as reduced risk of chronic diseases and weight management. Additionally, the environmental impact of animal farming and ethical concerns regarding animal cruelty are compelling more consumers to choose plant-based diets. The market is also benefitting from innovative product offerings and menu diversification by major fast food chains, which now cater to the vegan demographic with appealing and tasty alternatives. Social media and influencer endorsements further boost the market, creating a trendy and positive image of veganism.
Geographically, the market's growth is prominent across major Australian cities such as Sydney, Melbourne, and Brisbane, where a higher concentration of health-conscious and environmentally aware consumers reside. These urban areas also see a proliferation of vegan-friendly restaurants and fast food outlets. Key players in the Australia Vegan Fast Food Market include international and local brands such as Subway, McDonald's, and Domino's Pizza, alongside dedicated vegan chains like Lord of the Fries and Soul Burger. These companies are continuously innovating to expand their vegan menu options and improve the taste and nutritional profile of their offerings, ensuring sustained consumer interest and market expansion.
Market Drivers
Health and Wellness Trends
One of the primary drivers of the Australia Vegan Fast Food Market is the increasing consumer awareness regarding health and wellness For instance, a growing body of scientific evidence links plant-based diets with numerous health benefits, such as reduced risks of heart disease by up to 32%, diabetes by 50%, and certain cancers by 15%. Australians are becoming more health-conscious and seeking dietary options that promote longevity and well-being. This trend is reflected in the rising demand for vegan fast food, which is often perceived as a healthier alternative to traditional fast food. Many fast food chains are capitalizing on this by offering a variety of vegan options that not only appeal to health-conscious individuals but also cater to those with specific dietary needs, such as lactose intolerance or gluten sensitivity. The emphasis on health and wellness is likely to continue driving the market as more consumers prioritize their health in their food choices.
Environmental Sustainability Concerns
Environmental sustainability is another significant driver of the Australia Vegan Fast Food Market. For instance, the environmental impact of meat production, including high greenhouse gas emissions equivalent to 7.1 Gigatonnes of CO2 per year, deforestation of about 26 million hectares per year, and excessive water usage of around 15,400 liters per kg of beef, has led to a growing awareness of the need for sustainable food choices. Vegan diets are seen as a more environmentally friendly option, as plant-based foods generally require fewer resources to produce and result in lower emissions. This environmental consciousness is particularly strong among younger Australians, who are more likely to consider the ecological footprint of their dietary choices. Fast food chains are responding to this demand by incorporating sustainable practices and promoting their vegan offerings as eco-friendly alternatives. This alignment with environmental values not only attracts environmentally conscious consumers but also enhances the brand image of these fast food companies, further driving market growth.
Ethical and Animal Welfare Considerations
Ethical concerns and animal welfare considerations play a crucial role in driving the demand for vegan fast food in Australia. For instance, a significant portion of the population is becoming increasingly aware of the ethical implications of meat consumption, including animal cruelty and the conditions in which animals are raised and slaughtered. This awareness is fueled by advocacy groups, documentaries, and social media campaigns that highlight the harsh realities of the meat industry. As a result, many consumers are choosing to reduce or eliminate animal products from their diets. Fast food chains are responding to this shift by offering more vegan options, thereby attracting ethically minded consumers. The availability of vegan fast food allows these consumers to enjoy convenient and tasty meals without compromising their ethical beliefs. This ethical dimension is a powerful driver of market growth, as it taps into deeply held values and convictions.
Innovation and Product Development
Innovation and product development are key drivers that significantly influence the Australia Vegan Fast Food Market. The fast food industry is highly competitive, and companies are constantly striving to differentiate themselves and capture consumer interest. This drive for innovation has led to the development of a wide range of vegan products that mimic the taste and texture of traditional meat-based fast food items. Advances in food technology have enabled the creation of plant-based burgers, sausages, and nuggets that closely resemble their meat counterparts. These products appeal not only to vegans and vegetarians but also to flexitarians and meat-eaters looking to reduce their meat consumption. Additionally, fast food chains are experimenting with new flavors and ingredients to cater to diverse consumer preferences. The continuous introduction of innovative vegan products keeps the market dynamic and attracts a broad customer base. This focus on innovation ensures that consumers have access to appealing and varied vegan fast food options, driving sustained market growth.
Market Trends
Expansion of Vegan Menus by Major Fast Food Chains
Major fast food chains in Australia, such as McDonald's, Subway, and Domino's, are expanding their vegan menu options to cater to the growing demand. For instance, these companies are introducing plant-based versions of popular items like burgers, sandwiches, and pizzas, making it easier for consumers to choose vegan options without compromising on taste or convenience. This trend is driven by the need to appeal to a broader audience, including vegans, vegetarians, and flexitarians.
Rise of Dedicated Vegan Fast Food Outlets
In addition to traditional fast food chains offering vegan options, there is a notable rise in dedicated vegan fast food outlets. For instance, brands such as Lord of the Fries and Soul Burger are gaining popularity by providing exclusively vegan menus. These establishments focus on delivering high-quality, delicious plant-based meals that cater specifically to the vegan community, creating a niche market within the broader fast food industry.
Innovative Plant-Based Ingredients
The use of innovative plant-based ingredients is a significant trend in the Australian vegan fast food market. Companies are leveraging advancements in food technology to create plant-based proteins that mimic the texture and flavor of meat. For instance, ingredients like pea protein, soy, and even lab-grown meat alternatives are being incorporated into fast food products. This innovation not only enhances the appeal of vegan fast food but also attracts curious consumers looking to try new and exciting food options.
Healthier Vegan Fast Food Options
As consumers become more health-conscious, there is a growing demand for healthier vegan fast food options. Fast food chains are responding by offering items that are lower in calories, fat, and sodium while still providing the convenience and taste that consumers expect For instance, salads, smoothie bowls, and baked rather than fried options are becoming more prevalent on vegan fast food menus, catering to those who want to indulge without compromising their health goals. This trend aligns with the fact that approximately 60% of Australians are trying to lose weight, indicating a strong market for healthier fast food options.
Sustainability and Eco-Friendly Practices
Environmental sustainability is a major trend influencing the vegan fast food market. Fast food companies are adopting eco-friendly practices, such as using biodegradable packaging and reducing food waste. Additionally, the promotion of plant-based foods as a sustainable alternative to meat aligns with the growing consumer awareness of environmental issues. This commitment to sustainability not only attracts environmentally conscious consumers but also enhances the overall brand image.
Localization of Vegan Fast Food
Localization of vegan fast food is becoming increasingly important as companies strive to cater to local tastes and preferences. Fast food chains are incorporating traditional Australian flavors and ingredients into their vegan offerings. This trend not only makes vegan food more accessible to a wider audience but also supports local agriculture and reduces the carbon footprint associated with imported ingredients.
Social Media and Influencer Marketing
Social media and influencer marketing play a crucial role in the promotion of vegan fast food. Influencers and food bloggers are increasingly showcasing vegan options on platforms like Instagram and YouTube, driving awareness and interest. Fast food chains collaborate with influencers to reach a wider audience and create buzz around new vegan products. This trend leverages the power of social media to shape consumer perceptions and drive market growth.
Market Restraints and Challenges
High Cost of Vegan Ingredients
One of the primary restraints on the growth of the Australia Vegan Fast Food Market is the relatively high cost of vegan ingredients compared to traditional meat and dairy products. Plant-based proteins, such as soy, pea, and lab-grown meat alternatives, often require more complex production processes, leading to higher prices. This cost is passed on to consumers, making vegan fast food items more expensive than their non-vegan counterparts. The price disparity can deter price-sensitive consumers, limiting the market’s reach and slowing its growth.
Limited Consumer Awareness and Acceptance
While awareness of veganism is increasing, there is still a significant portion of the Australian population that is either unaware of or skeptical about vegan diets. Misconceptions about the taste, nutritional value, and variety of vegan food can pose challenges for market growth. Some consumers may perceive vegan fast food as less satisfying or less nutritious compared to traditional fast food options. Overcoming these perceptions requires substantial marketing efforts and educational campaigns to highlight the benefits and appeal of vegan fast food.
Supply Chain Challenges
The vegan fast food market faces several supply chain challenges, including the sourcing of high-quality, consistent plant-based ingredients. The demand for vegan products is growing rapidly, sometimes outpacing the ability of suppliers to keep up. This can lead to shortages or variability in the quality of ingredients, impacting the ability of fast food chains to offer consistent menu items. Additionally, the need for specialized storage and handling of plant-based ingredients adds complexity to the supply chain, increasing operational costs.
Competition from Traditional Fast Food Options
The vegan fast food market must compete with well-established traditional fast food options that have a loyal customer base. Many consumers are accustomed to the taste and convenience of meat-based fast food, making it challenging for vegan alternatives to gain traction. Fast food giants with extensive marketing budgets and established brand loyalty can overshadow smaller vegan brands, making it difficult for them to compete on a level playing field.
Regulatory and Labeling Issues
Regulatory and labeling issues can pose challenges for the vegan fast food market. Ensuring that vegan products meet stringent labeling requirements and food safety standards can be complex and costly. Additionally, there is ongoing debate over the labeling of plant-based products, such as whether they can be labeled as "meat" or "milk." These regulatory challenges can create uncertainty and additional hurdles for companies in the vegan fast food sector.
Consumer Taste Preferences
Adapting to consumer taste preferences is a significant challenge for the vegan fast food market. While plant-based alternatives have made significant strides in mimicking the taste and texture of meat, they may still fall short of satisfying all consumers. Continuous innovation and improvement are necessary to ensure that vegan fast food options meet the high taste expectations of a diverse customer base. Failure to do so can limit repeat purchases and overall market growth.
Market Segmentation Analysis
By Product
The Australia Vegan Fast Food Market is experiencing rapid growth across various segments due to increasing consumer awareness and demand for plant-based diets. Meat and seafood substitutes, including burgers, sausages, and seafood alternatives, are seeing significant investment in innovation and flavor. Vegan creamers, primarily soy, almond, and oat-based, are becoming popular in both coffee shops and homes. Dairy-free ice creams and frozen treats made from coconut, almond, and cashew are attracting a broad audience with diverse flavors. Plant-based yogurts from almond, coconut, and soy are gaining traction as healthy alternatives to dairy yogurt. The vegan cheese market is expanding with cashew and almond-based options that closely mimic traditional cheese. Vegan butter, particularly almond, coconut, and soy-based, is growing in popularity due to health consciousness. Pre-packaged vegan meals, such as salads, wraps, and bowls, are highly demanded by busy, health-conscious consumers. Protein bars, favored by fitness enthusiasts, cater to the need for on-the-go nutrition with innovative flavors and nutrient profiles. Additionally, the market for vegan snacks, sauces, and condiments is expanding due to the increasing variety and consumer interest in plant-based lifestyles.
By Distribution Channel
The online segment of the Australia Vegan Fast Food Market is experiencing rapid growth due to its convenience and wide range of products, with e-commerce platforms and direct-to-consumer brands leading the way. This growth is further fueled by effective digital marketing and social media influence. Meanwhile, the offline segment, dominated by supermarkets and specialty stores, remains crucial for reaching a broader customer base. Physical stores provide consumers with the opportunity to explore and taste new products, making them an essential part of the market's distribution strategy.
Segments
Based on Product
- Meat & Seafood Substitutes
- Creamer
- Ice Cream and Frozen Novelties
- Yogurt
- Cheese
- Butter
- Meals
- Protein Bars
- Others
Based on Distribution Channel
- Online
- Offline
Regional Analysis
New South Wales (30%):
New South Wales, particularly Sydney, is a significant market for vegan fast food in Australia, holding approximately 30% of the market share. Sydney, being the most populous city, has a diverse and health-conscious population that drives the demand for vegan options. The city's vibrant food culture, coupled with a high concentration of cafes, restaurants, and quick-service outlets, makes it a hotspot for vegan fast food. The presence of numerous vegan festivals and events also boosts market awareness and consumer interest in plant-based diets. Major fast food chains and dedicated vegan eateries thrive in this region, continuously expanding their vegan offerings to cater to the growing demand.
Victoria (25%):
Victoria, with Melbourne as its cultural and culinary hub, accounts for around 25% of the vegan fast food market share. Melbourne's progressive and trendy population is highly receptive to veganism, driven by health, environmental, and ethical considerations. The city's renowned food scene includes a plethora of vegan-friendly establishments and fast food outlets, making it a central player in the market. Melbourne hosts various vegan markets and food festivals, further promoting vegan fast food options. The local government's support for sustainable and ethical food practices also encourages the growth of vegan fast food businesses in the region.
Queensland (20%):
Queensland holds approximately 20% of the market share, with Brisbane being the focal point. The state's warm climate and outdoor lifestyle contribute to a strong interest in health and wellness, including plant-based diets. Brisbane and other major cities in Queensland are witnessing a steady rise in vegan fast food outlets, driven by consumer demand for healthier and environmentally friendly options. The expansion of food delivery services in the region has also facilitated greater access to vegan fast food, supporting market growth.
Key players
- Bob's Red Mill Natural Foods
- The Hain Celestial Group, Inc.
- Upfield B.V.
- Johars Group
- One Good (Goodmylk)
- Rakyan Beverages
- Hebei Yangyuan Zhihui Beverage Co. Ltd.
- Namaste Foods
- Australian Organic Food Co.
- Beyond Meat Inc.
Competitive Analysis
The Australia Vegan Fast Food Market is characterized by intense competition among both global and local players. Beyond Meat Inc. leads the market with its innovative plant-based meat alternatives, driving consumer interest and adoption. Upfield B.V. and The Hain Celestial Group, Inc. leverage their extensive product portfolios and established brand presence to maintain strong market positions. Bob's Red Mill Natural Foods and Namaste Foods focus on high-quality, organic ingredients, appealing to health-conscious consumers. Local companies like Australian Organic Food Co. and One Good (Goodmylk) emphasize sustainability and local sourcing, catering to eco-conscious consumers. Rakyan Beverages and Hebei Yangyuan Zhihui Beverage Co. Ltd. diversify the market with their vegan beverage offerings. The competitive landscape is dynamic, with companies continuously innovating to meet evolving consumer preferences and capture market share.
Recent Developments
In March 2024, The Kraft Heinz Not Company LLC unveiled NotHotDogs and NotSausages, marking the first plant-based products under the Oscar Mayer brand. This launch is the initial plant-based innovation from the joint venture between The Kraft Heinz Company and The NotCompany, Inc. These new offerings deliver the signature savory and smoky flavors that have made Oscar Mayer a household name for over 140 years. The Kraft Heinz Not Company aims to attract both long-time fans and new customers seeking delicious plant-based alternatives.
In March 2024, dsm-firmenich, leaders in nutrition, health, and beauty innovation, inaugurated a new pilot plant in Plainsboro, New Jersey. This facility, part of the Taste, Texture & Health Business Unit, is designed to foster collaboration with customers. The new pilot plant exemplifies dsm-firmenich's commitment to advancing global dietary transformation, equipping food and beverage brands with the tools to create enjoyable, healthier, and more sustainable eating and drinking experiences. This initiative highlights the company’s dedication to improving the quality and sustainability of the global food supply.
In 2024, Burger King Germany introduced a new range of plant-based meals, priced lower than their meat-based counterparts. This strategic initiative addresses the increasing consumer demand for plant-based food options and demonstrates the fast-food industry's adaptation to changing dietary preferences. The new menu items are designed to be both affordable and appealing to health-conscious customers seeking sustainable and environmentally friendly choices. This effort underscores Burger King's commitment to making plant-based meals more accessible and attractive to a broader audience.
In 2023, Papa John’s UK launched a vegan BBQ "chicken" pizza as part of the annual Veganuary campaign. This pizza features a plant-based chicken substitute topped with BBQ sauce, onions, green peppers, and dairy-free cheese. The new addition aims to meet the rising demand for vegan food options and caters to customers seeking more plant-based choices. Papa John’s UK, already known for its range of vegan pizzas, sides, and desserts, anticipates the vegan BBQ "chicken" pizza will be popular among both vegans and non-vegans.
In March 2023, Daiya, a leader in the plant-based cheese market in North America, announced a multi-million-dollar investment in fermentation technology. This investment aims to improve the taste, melt, and stretchiness of their plant-based cheese, setting it apart from other options on the market. Daiya’s commitment to advancing their product offerings through cutting-edge technology underscores their leadership and innovation in the plant-based food industry, establishing a new standard for quality and consumer satisfaction in plant-based cheese.
Market Concentration and Characteristics
The Australia Vegan Fast Food Market is characterized by moderate market concentration, with a mix of established global fast food chains and emerging local vegan eateries driving competition. Key players such as McDonald’s, Subway, and Domino’s dominate the market by expanding their plant-based menu offerings, while dedicated vegan chains like Lord of the Fries and Soul Burger gain traction with niche, high-quality vegan options. The market is defined by rapid innovation, with companies leveraging advances in food technology to develop appealing plant-based alternatives. Consumer demand is fueled by growing health consciousness, environmental sustainability concerns, and ethical considerations, creating a dynamic and evolving marketplace.
Report Coverage
The research report offers an in-depth analysis based on Product and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Australia vegan fast food market is expected to continue its robust growth, driven by increasing consumer awareness of health, environmental, and ethical issues.
- Major fast food chains are likely to expand their vegan menus further, introducing new plant-based products to attract a broader customer base.
- Ongoing innovations in food technology will enhance the taste, texture, and nutritional profile of plant-based foods, making them more appealing to consumers.
- Companies will focus on reducing the cost of vegan ingredients and products, making plant-based fast food more affordable and accessible to a wider audience.
- There will be a trend towards sourcing plant-based ingredients locally, promoting sustainability and supporting local agriculture.
- Marketing efforts and educational campaigns will intensify to dispel myths about vegan diets and highlight the benefits of plant-based fast food options.
- Social media and influencer marketing will continue to play a crucial role in promoting vegan fast food, driving consumer interest and adoption.
- Dedicated vegan fast food chains are expected to expand their presence, offering diverse and high-quality plant-based options to meet growing demand.
- Environmental sustainability will remain a key focus, with companies adopting eco-friendly practices in sourcing, production, and packaging of vegan fast food.
- Increased government support and favorable regulations for plant-based food production and marketing will facilitate market growth and innovation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth rate of the Australia Vegan Fast Food Market?
What are the main factors driving the growth of the vegan fast food market in Australia?
Which Australian cities are seeing the most significant growth in the vegan fast food market?
Who are some of the key players in the Australia Vegan Fast Food Market?
What are some challenges facing the vegan fast food market in Australia?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Australia Vegan Fast Food Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Australia Vegan Fast Food Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 159.64 million → 2032: USD 306.07 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Australia Vegan Fast Food Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Australia Vegan Fast Food Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Australia Vegan Fast Food Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 Australia Vegan Fast Food Drivers
- 3.3 Australia Vegan Fast Food Restraints & Challenges
- 3.4 Australia Vegan Fast Food Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Australia Vegan Fast Food Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Australia Vegan Fast Food Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Australia Vegan Fast Food category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Australia Vegan Fast Food Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. Australia Vegan Fast Food Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2023)
- 5.1.2 Export Volume by Destination Country (2023) (Where Applicable)
- 5.1.3 Import Value by Source Country (2023)
- 5.1.4 Import Volume by Source Country (2023) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to Australia Vegan Fast Food in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Australia Vegan Fast Food Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2023
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 Australia Vegan Fast Food Share Analysis – 2023
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution (the historical period vs. 2023)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Australia Vegan Fast Food Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Australia Vegan Fast Food (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Australia Vegan Fast Food
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Australia Vegan Fast Food – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. Australia Vegan Fast Food – Priority Domestic Market 1
Chapter 10. Australia Vegan Fast Food – Priority Domestic Market 2
Chapter 11. Australia Vegan Fast Food – Priority Domestic Market 3
Chapter 12. Australia Vegan Fast Food – Priority Domestic Market 4
Chapter 13. Australia Vegan Fast Food Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
