
Market Overview
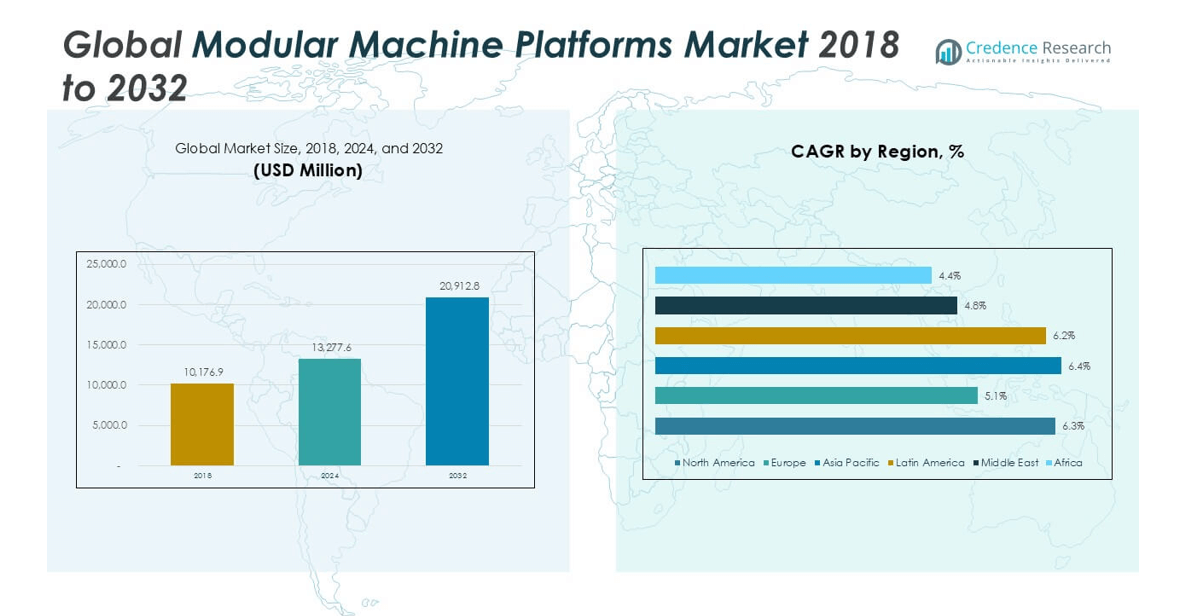
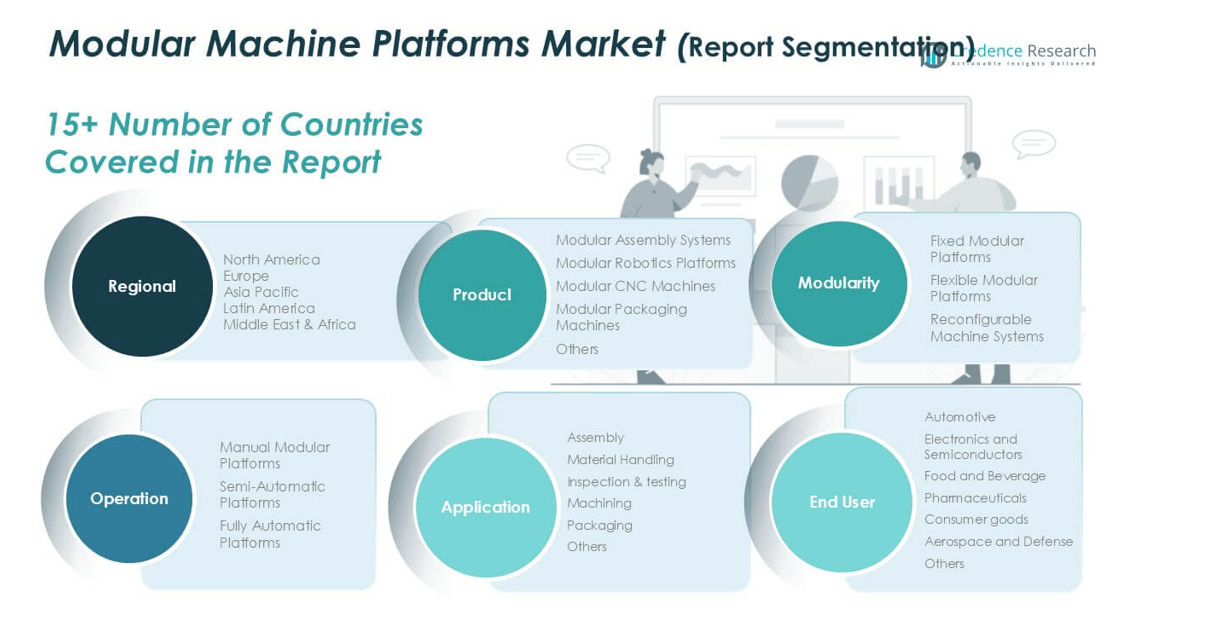
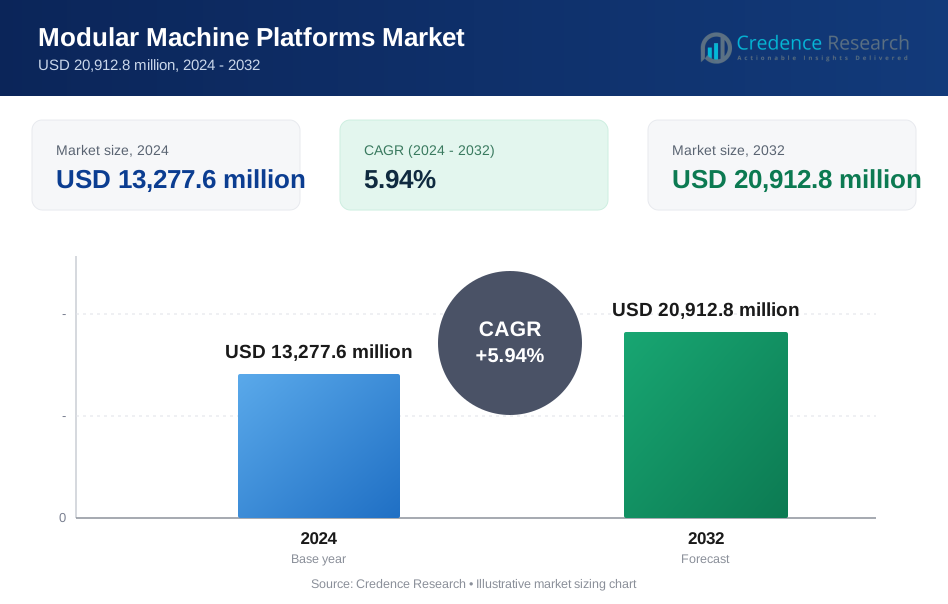
Global Modular Machine Platforms market size was valued at USD 10,176.9 million in 2018 to USD 13,277.6 million in 2024 and is anticipated to reach USD 20,912.8 million by 2032, at a CAGR of 5.94% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Modular Machine Platforms Market Size 2024 | USD 13,277.6 million |
| Modular Machine Platforms Market, CAGR | 5.94% |
| Modular Machine Platforms Market Size 2032 | SD 20,912.8 million |
The Global Modular Machine Platforms market features strong competition among ABB Ltd., Rockwell Automation, Mitsubishi Electric Corporation, Bosch Rexroth, KUKA AG, Beckhoff Automation, B&R Industrial Automation, Festo AG & Co. KG, ATS Automation, and Schunk GmbH. These players lead through broad modular portfolios and automation expertise. Asia Pacific leads the market with an exact share of 36%, driven by large-scale manufacturing in China, Japan, and South Korea. Europe follows with a 28% share, supported by advanced industrial automation adoption. North America holds a 24% share, backed by automotive and electronics manufacturing strength. Leading companies maintain regional dominance through strong service networks, flexible platforms, and continuous technology upgrades.
Market Insights
- The market was valued at USD 10,176.9 million in 2018 and reached USD 13,277.6 million in 2024. It is projected to reach USD 20,912.8 million by 2032, growing at a CAGR of 5.94%. Asia Pacific holds 36% share, Europe 28%, and North America 24%.
- Demand rises due to flexible and scalable manufacturing needs. Modular assembly systems hold the largest product share. Automotive and electronics sectors drive adoption. Manufacturers prefer reduced downtime and faster line reconfiguration.
- Key trends include reconfigurable manufacturing systems and Industry 4.0 integration. Flexible modular platforms dominate the modularity segment. Packaging and assembly remain leading applications due to high SKU variation.
- Competition remains moderate with global players focusing on standardized modules. Companies compete on system compatibility, automation integration, and lifecycle cost efficiency. Strong service networks support customer retention.
- High integration complexity restrains adoption for smaller manufacturers. Capital cost sensitivity slows uptake in emerging regions. Africa and the Middle East together hold under 6% share but show gradual growth.
Market Segmentation Analysis:
By Product
The Product segment shows strong adoption across modular assembly systems, robotics platforms, CNC machines, and packaging machines. Modular Assembly Systems dominate this segment, accounting for the largest market share. Manufacturers favor these systems due to fast changeovers, standardized modules, and reduced downtime. Automotive and electronics plants rely on modular assembly for high-volume, repeatable tasks. Modular Robotics Platforms follow, driven by flexible automation needs. Modular CNC Machines gain traction in precision machining. Demand grows as factories seek scalable platforms that lower integration cost and support rapid production line upgrades.
- For instance, Bosch Rexroth’s TS 2plus modular transfer system supports loads up to 240 kg per workstation and conveyor speeds of up to 18 m/min (or up to 180 m/min with the optional TS 2 Booster linear motor components), enabling rapid line reconfiguration.
By Modularity
The Modularity segment highlights clear preference patterns among fixed, flexible, and reconfigurable platforms. Flexible Modular Platforms hold the dominant market share due to adaptability across product variants. These platforms support frequent layout changes without major hardware replacement. Electronics, consumer goods, and packaging plants drive demand for flexibility. Reconfigurable Machine Systems show steady growth, supported by mass customization trends. Fixed Modular Platforms remain relevant in stable, high-volume operations. The segment benefits from rising focus on production agility, shorter product life cycles, and reduced capital reinvestment needs.
- For instance, MAG IAS (now FFG Europe & Americas) manufactures highly flexible, reconfigurable machining systems designed to minimize production disruption through modular components, fast tool changes, and rapid setup times.
By Application
The Application segment reflects broad usage across assembly, material handling, inspection, machining, and packaging operations. Assembly represents the leading application, holding the highest market share. Manufacturers deploy modular platforms to streamline multi-step assembly tasks. Packaging follows closely, driven by SKU diversity and automation upgrades. Material handling adoption rises with warehouse automation trends. Inspection and testing benefit from modular sensor integration. Machining applications grow steadily in precision industries. Growth drivers include demand for efficient workflows, consistent quality output, and scalable automation across diverse manufacturing environments.
Key Growth Drivers
Rising Demand for Flexible and Scalable Manufacturing
Manufacturers increasingly demand flexible production systems to manage product variety. Modular machine platforms support fast line changes and scalable capacity. These platforms allow module replacement without full system redesign. Automotive and electronics sectors drive this shift strongly. Shorter product life cycles increase the need for rapid reconfiguration. Modular platforms reduce downtime during upgrades. They also lower capital risk during demand uncertainty. Plants expand capacity in phases instead of full investments. This approach improves return on capital. Standardized modules simplify engineering and commissioning. Companies respond faster to customer-specific orders. The driver remains strong across discrete manufacturing industries. Flexibility becomes a core competitiveness factor. Modular systems align well with lean manufacturing goals. This demand sustains long-term adoption across global production facilities.
- For instance, the Bosch Rexroth TS 2plus modular conveyor system supports workstation loads up to 240 kg and conveyor speeds of up to 150 m/min (3 m/s), enabling rapid line scaling without full rebuilds.
Accelerating Industrial Automation and Smart Factory Adoption
Industrial automation continues expanding across global manufacturing sites. Modular machine platforms integrate easily with automated environments. These platforms support robotics, sensors, and control systems. Manufacturers deploy them to improve throughput consistency. Smart factories require modular layouts for data-driven optimization. Modular machines simplify integration with MES and PLC systems. Automation investments favor systems with upgrade paths. Modular designs extend equipment life cycles. Labor shortages further accelerate automation demand. Companies seek machines that adapt without heavy retraining. Modular platforms reduce complexity during automation expansion. Industries prioritize predictable performance and uptime. This driver gains strength across both developed and emerging economies. Automation strategies increasingly depend on modular machine architectures.
- For instance, Siemens SIMATIC S7-1500 modular PLCs support up to 32 local modules and manage thousands of I/O points within one controller, enabling scalable automation expansion.
Cost Efficiency and Reduced Time-to-Market
Cost control remains a priority for manufacturing operations. Modular machine platforms lower engineering and installation costs. Reusable modules reduce custom design requirements. Faster deployment shortens production ramp-up time. Manufacturers launch products more quickly with modular systems. Reduced commissioning time improves operational readiness. Maintenance teams benefit from standardized spare parts. This reduces inventory and service costs. Modular upgrades avoid full machine replacement. Capital efficiency improves across long-term operations. The driver supports adoption among mid-sized manufacturers. Cost predictability attracts contract manufacturers. Time-to-market pressure strengthens this driver across competitive industries. Modular platforms deliver measurable operational savings.
Key Trends & Opportunities
Growth of Reconfigurable Manufacturing Systems
Reconfigurable manufacturing gains attention across high-mix production environments. Modular machine platforms form the foundation for this trend. Manufacturers adjust capacity and functions on demand. This supports mass customization strategies. Reconfigurable systems reduce dependency on dedicated equipment. Industries adopt these systems for volatile demand patterns. Aerospace and electronics show strong interest. Modular platforms enable fast functional retooling. Software-driven controls enhance reconfiguration speed. This trend opens opportunities for advanced module suppliers. OEMs develop plug-and-play machine units. The opportunity aligns with digital manufacturing roadmaps. Reconfigurable systems improve asset utilization. Adoption expands as customization demand rises globally.
- For instance, the principles of reconfigurable manufacturing systems (RMS), a field explored by companies like MAG IAS (now part of FFG Werke), allow for rapid function changes in theory, often using modular designs.
Integration with Digital and Industry 4.0 Technologies
Digital integration shapes future modular machine designs. Platforms now support real-time monitoring and analytics. Sensors embed directly into modular units. This improves predictive maintenance capabilities. Manufacturers gain better equipment visibility. Modular platforms simplify digital retrofitting. Data-driven optimization improves productivity outcomes. Industry 4.0 strategies favor modular architectures. OEMs offer smart modules with built-in connectivity. This trend creates value-added upgrade opportunities. End users prefer future-ready equipment. Digital compatibility extends machine relevance. The opportunity supports long-term service revenues. Modular platforms become central to smart factory ecosystems.
Key Challenges
High Initial System Integration Complexity
Despite benefits, integration complexity challenges adoption. Modular platforms still require careful system engineering. Compatibility issues arise across vendors. Customization needs increase integration effort. Smaller manufacturers face skill gaps. Software and hardware alignment adds complexity. Integration timelines may extend unexpectedly. This increases project risk perception. Lack of universal standards limits interchangeability. End users hesitate without proven integrators. Training requirements increase during early deployment. The challenge affects first-time adopters most. Vendors address this through standardized interfaces. Integration complexity remains a restraint on faster penetration.
Capital Cost Sensitivity in Price-Constrained Markets
Modular machine platforms often carry higher upfront costs. Price-sensitive markets delay adoption decisions. Smaller factories prioritize basic automation solutions. Return expectations vary across regions. Budget constraints limit investment flexibility. Modular benefits require long-term planning. Short-term cost focus reduces acceptance. Financing access affects purchasing behavior. Emerging markets show slower uptake. OEM pricing strategies influence demand patterns. Cost comparison with conventional machines impacts decisions. This challenge persists despite lifecycle savings. Vendors respond with phased deployment models. Capital sensitivity continues shaping market adoption rates.
Regional Analysis
North America
North America held a strong market share in 2018, valued at USD 2,408.87 million. The region accounted for roughly 24% of global revenue that year. Advanced automation adoption supported steady growth. The market reached USD 3,211.65 million in 2024 and is projected to reach USD 5,203.10 million by 2032. The region is expected to grow at a CAGR of 6.3%. Automotive, aerospace, and electronics manufacturing drive demand. Manufacturers favor modular platforms for flexibility and productivity. High investment capacity and early technology adoption sustain regional leadership.
Europe
Europe represented a significant market share of about 28% in 2018, with a value of USD 2,815.94 million. Strong industrial bases in Germany, France, and Italy support demand. The market grew to USD 3,509.45 million in 2024. It is projected to reach USD 5,182.18 million by 2032, registering a CAGR of 5.1%. Focus on smart manufacturing and energy efficiency supports adoption. Modular platforms help European manufacturers meet customization needs. Regulatory emphasis on productivity and sustainability further strengthens long-term growth across the region.
Asia Pacific
Asia Pacific dominated the global market in 2018 with the largest share of around 36%. The market was valued at USD 3,630.09 million that year. Rapid industrialization and factory expansion drive strong demand. The market reached USD 4,868.69 million in 2024. It is forecast to reach USD 7,946.85 million by 2032, growing at a CAGR of 6.4%. China, Japan, and South Korea lead adoption. Electronics and automotive manufacturing fuel growth. Cost-efficient production and capacity expansion remain key regional drivers.
Latin America
Latin America accounted for nearly 7.5% of global market share in 2018, with a value of USD 758.18 million. The market expanded to USD 1,001.70 million in 2024. It is expected to reach USD 1,604.01 million by 2032, registering a CAGR of 6.2%. Manufacturing modernization supports growth. Automotive and consumer goods industries adopt modular platforms steadily. Companies focus on flexible production to manage demand shifts. Gradual automation investment and regional industrial development sustain positive long-term prospects.
Middle East
The Middle East held a modest market share of about 3.3% in 2018, valued at USD 328.71 million. The market reached USD 403.26 million in 2024. It is projected to reach USD 581.38 million by 2032, growing at a CAGR of 4.8%. Industrial diversification programs drive adoption. Manufacturing growth outside oil sectors supports demand. Modular platforms appeal due to scalability and lower long-term costs. Government-backed industrial zones improve investment activity. The region shows steady but moderate expansion over the forecast period.
Africa
Africa accounted for roughly 2.3% of the global market in 2018, with a value of USD 235.09 million. The market increased to USD 282.81 million in 2024. It is expected to reach USD 395.25 million by 2032, at a CAGR of 4.4%. Growth remains gradual due to limited automation penetration. Industrial development initiatives support adoption. Food processing and basic manufacturing lead demand. Modular platforms attract interest for phased investment capability. Infrastructure improvements and policy support gradually strengthen regional market presence
Market Segmentations:
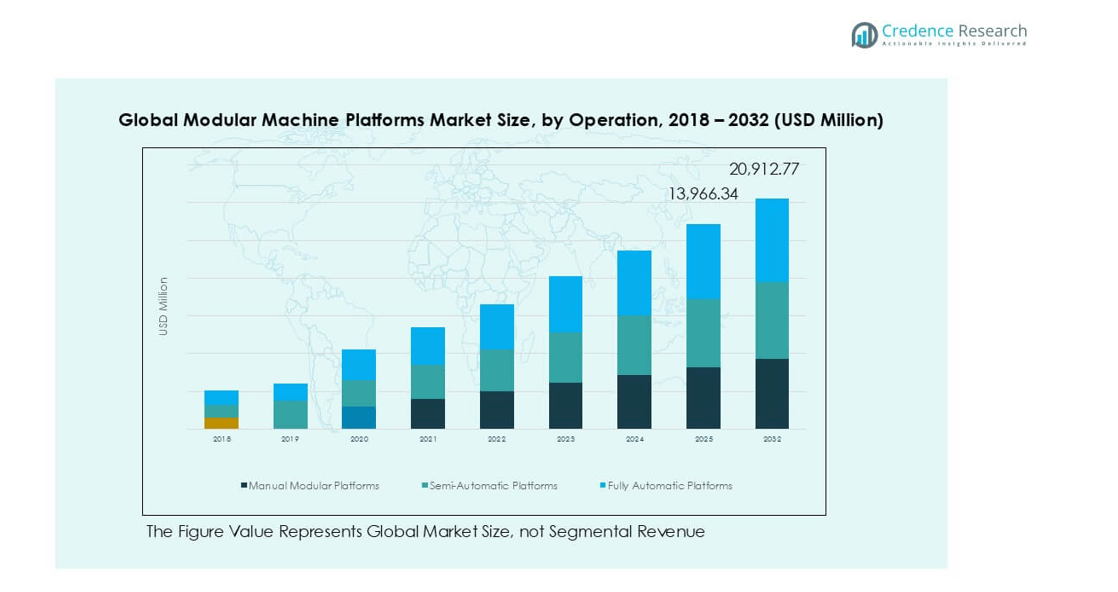
By Product
- Modular Assembly Systems
- Modular Robotics Platforms
- Modular CNC Machines
- Modular Packaging Machines
- Others
By Modularity
- Fixed Modular Platforms
- Flexible Modular Platforms
- Reconfigurable Machine Systems
By Application
- Assembly
- Material Handling
- Inspection and Testing
- Machining
- Packaging
- Others
By End User Type
- Automotive
- Electronics and Semiconductors
- Food and Beverage
- Pharmaceuticals
- Consumer Goods
- Aerospace and Defense
- Others
By Operation
- Manual Modular Platforms
- Semi-Automatic Platforms
- Fully Automatic Platforms
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Global Modular Machine Platforms market remains moderately consolidated. Leading players focus on modular architecture depth and system compatibility. Companies compete through flexible platform design and automation integration. Strong portfolios cover assembly, robotics, and motion control modules. Market leaders invest in standardized interfaces to reduce integration complexity. Strategic partnerships support turnkey project delivery. Firms expand software capabilities to enhance machine intelligence. Product differentiation relies on scalability and lifecycle cost benefits. Global players leverage strong service networks for customer retention. Regional firms compete on customization and pricing flexibility. Continuous product upgrades sustain competitive positioning. Vendors target automotive, electronics, and packaging sectors. Competitive intensity increases with smart factory adoption. Innovation and system reliability define long-term success. The market rewards suppliers offering fast deployment and upgrade paths.
Key Player Analysis
- ABB Ltd.
- ATS Automation
- B&R Industrial Automation
- Beckhoff Automation
- Bosch Rexroth
- Festo AG & Co. KG
- Mitsubishi Electric Corporation
- KUKA AG
- Rockwell Automation
- Schunk GmbH
Recent Developments
- In 2024, Rockwell Automation announced plans to increase its presence in India by expanding its technology workforce and opening more factories, including a new plant in Tamil Nadu.
- In 2024, Bosch Rexroth presented its vision for the future of automation at SPS 2024, highlighting open, modular solutions and a Linux-based operating system that fosters co-creation and partner integration. The company emphasized the importance of openness and collaboration in developing comprehensive automation solutions.
Report Coverage
The research report offers an in-depth analysis based on Product, Modularity, Application, End User Type, Operation and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will see wider adoption of flexible and reconfigurable machine architectures.
- Manufacturers will prioritize modular platforms to support product diversity.
- Automation expansion will strengthen demand across assembly and packaging operations.
- Integration with digital manufacturing systems will become standard practice.
- Demand from automotive and electronics sectors will remain strong.
- Modular robotics platforms will gain higher deployment across factories.
- Companies will focus on reducing system integration complexity.
- Emerging economies will increase investment in modular production lines.
- Service, upgrade, and retrofit offerings will grow in importance.
- Competition will intensify around scalability, reliability, and lifecycle efficiency.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Flexible and Scalable Manufacturing Needs
Manufacturers are increasingly adopting modular machine platforms to enable rapid production line changes, support product variety, and scale capacity efficiently. This flexibility reduces downtime and capital risk, making modular systems attractive for industries with frequent product updates and high-mix production.
Accelerating Industrial Automation and Smart Factory Adoption
The integration of modular platforms with robotics, sensors, and control systems is essential for smart factory initiatives. These platforms simplify automation expansion, support data-driven optimization, and enable seamless integration with MES and PLC systems, driving adoption across both developed and emerging markets.
Cost Efficiency and Reduced Time-to-Market
Modular machine platforms lower engineering, installation, and maintenance costs by utilizing standardized, reusable modules. This enables faster deployment, reduces commissioning time, and allows manufacturers to bring products to market more quickly, which is critical in competitive industries.
Growth of Reconfigurable Manufacturing Systems
The trend toward mass customization and high-mix, low-volume production is fueling demand for reconfigurable modular platforms. These systems allow manufacturers to adjust capacity and functions on demand, improving asset utilization and supporting rapid adaptation to changing market requirements.
Integration with Digital and Industry 4.0 Technologies
Modular platforms are increasingly designed for real-time monitoring, analytics, and predictive maintenance through embedded sensors and connectivity. This digital compatibility extends equipment life cycles, supports future-ready manufacturing, and creates opportunities for value-added upgrades and services.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Modular Machine Platforms Market?
At what Compound Annual Growth Rate is the Global Modular Machine Platforms market projected to grow between 2024 and 2032?
What factors are driving the growth of the Modular Machine Platforms Market?
What are the key segments within the Modular Machine Platforms Market?
What are some challenges faced by the Modular Machine Platforms Market?
Who are the major players in the Modular Machine Platforms Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Modular Assembly Systems
- 1.2.2 Modular Robotics Platforms
- 1.2.3 Modular CNC Machines
- 1.2.4 Modular Packaging Machines
- 1.2.5 Others
- 1.3 By Modularity
- 1.3.1 Fixed Modular Platforms
- 1.3.2 Flexible Modular Platforms
- 1.3.3 Reconfigurable Machine Systems
- 1.4 By Application
- 1.4.1 Assembly
- 1.4.2 Material Handling
- 1.4.3 Inspection and Testing
- 1.4.4 Machining
- 1.4.5 Packaging
- 1.4.6 Others
- 1.5 By End User Type
- 1.5.1 Automotive
- 1.5.2 Electronics and Semiconductors
- 1.5.3 Food and Beverage
- 1.5.4 Pharmaceuticals
- 1.5.5 Consumer Goods
- 1.5.6 Aerospace and Defense
- 1.5.7 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 13,277.6 million → 2032: USD 20,912.8 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Modular Machine Platforms Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Modular Machine Platforms Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Modular Machine Platforms Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Modular Machine Platforms Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Modular Machine Platforms Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Modular Machine Platforms Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Modular Machine Platforms Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Modular Machine Platforms Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 13,277.6 million → 2032: USD 20,912.8 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Modular Machine Platforms Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Modular Assembly Systems
- 12.3.7.2 Modular Robotics Platforms
- 12.3.7.3 Modular CNC Machines
- 12.3.7.4 Modular Packaging Machines
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Modularity - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Fixed Modular Platforms
- 12.4.7.2 Flexible Modular Platforms
- 12.4.7.3 Reconfigurable Machine Systems
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Assembly
- 12.5.7.2 Material Handling
- 12.5.7.3 Inspection and Testing
- 12.5.7.4 Machining
- 12.5.7.5 Packaging
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End User Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Automotive
- 12.6.7.2 Electronics and Semiconductors
- 12.6.7.3 Food and Beverage
- 12.6.7.4 Pharmaceuticals
- 12.6.7.5 Consumer Goods
- 12.6.7.6 Aerospace and Defense
- 12.6.7.7 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Modular Machine Platforms End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Modular Machine Platforms Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Modular Machine Platforms Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Modular Machine Platforms Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 ABB Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Rockwell Automation
- 18.4 Mitsubishi Electric Corporation
- 18.5 Bosch Rexroth
- 18.6 KUKA AG
- 18.7 Beckhoff Automation
- 18.8 B&R Industrial Automation
- 18.9 Festo AG & Co. KG
- 18.10 ATS Automation
- 18.11 Schunk GmbH
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

