
Market Overview
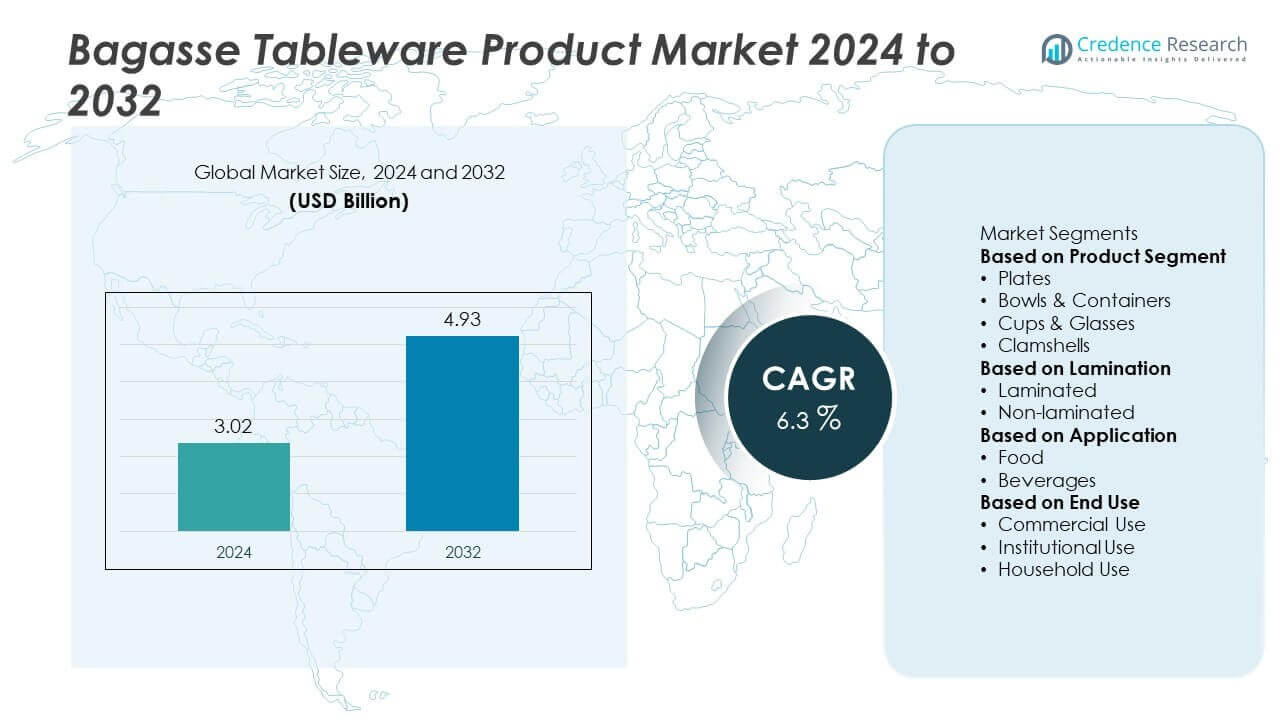
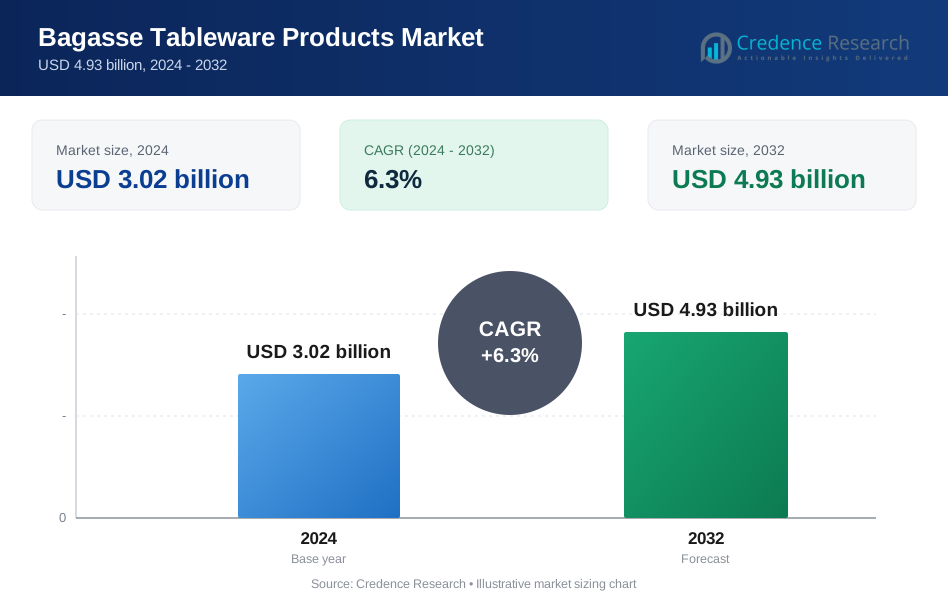
Bagasse Tableware Product Market size was valued at USD 3.02 billion in 2024 and is projected to reach USD 4.93 billion by 2032, growing at a CAGR of 6.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Bagasse Tableware Product Market Size 2024 | USD 3.02 Billion |
| Bagasse Tableware Product Market, CAGR | 6.3% |
| Bagasse Tableware Product Market Size 2032 | USD 4.93 Billion |
Top players in the Bagasse Tableware Product market include Genpak, Ecoware, CPM Industries, World Centric, Albea, Biotrem, Huhtamaki, Dart Container Corporation, Biopac, and International Paper. These companies focus on developing durable, compostable, and cost-effective bagasse plates, bowls, clamshells, and trays to meet rising demand from foodservice and retail sectors. They invest in product innovation, coating technology, and regional manufacturing to ensure compliance with global sustainability standards. Asia-Pacific leads the market with 33% share, driven by plastic bans and rapid growth of food delivery services. Europe follows with 29% share, supported by strong regulatory frameworks, while North America accounts for 27% share, driven by increasing adoption in quick-service restaurants and institutional catering.
Market Insights
- Bagasse Tableware Product market was valued at USD 3.02 billion in 2024 and is projected to reach USD 4.93 billion by 2032, growing at a CAGR of 6.3% during the forecast period.
- Rising bans on single-use plastics and growing consumer preference for eco-friendly products drive demand, with plates holding over 35% share and food applications contributing more than 70% of total usage.
- Trends include innovations in bio-based coatings, moisture-resistant finishes, and increasing adoption in retail and household segments through e-commerce and supermarkets.
- The market is moderately competitive with key players such as Huhtamaki, Dart Container Corporation, World Centric, and Genpak investing in product development, capacity expansion, and partnerships with foodservice providers.
- Asia-Pacific leads with 33% share, followed by Europe at 29% and North America at 27%, supported by strong regulations, urbanization, and rapid growth of food delivery and takeaway services.
Market Segmentation Analysis:
By Product Segment
Plates dominate the bagasse tableware product market with over 35% market share, driven by strong demand from quick-service restaurants, catering services, and institutional dining. Plates made from bagasse offer durability, heat resistance, and compostability, aligning with global sustainability goals and single-use plastic bans. Bowls & containers and cups & glasses follow closely, supported by rising takeout and beverage service trends. Clamshells see increasing adoption in food delivery and meal packaging, particularly in urban areas. Expanding foodservice infrastructure and the shift toward eco-friendly packaging materials continue to fuel growth across all product categories.
- For instance, Bioleader® supplies single-use, compostable bagasse tableware plates that can withstand hot food at 95 °C without deformation. These products are durable and microwave-safe, but they are not designed for repeated use in a commercial dishwasher.
By Lamination
Non-laminated bagasse tableware holds the largest share, accounting for more than 60% of the market due to its complete biodegradability and cost efficiency. These products are preferred by environmentally conscious consumers and organizations aiming to reduce their plastic footprint. Laminated variants, which use bio-based or thin polyethylene coatings, serve niche applications requiring moisture and grease resistance. Growing demand from quick-service restaurants and takeaway chains supports laminated product adoption. However, increasing regulations favoring fully compostable products are expected to strengthen the market position of non-laminated bagasse tableware in the coming years.
- For instance, Gracz (formerly BPE, Thailand) produces 100% natural, non-laminated plates and cups from plant fibers like bagasse and bamboo. These products are certified to be fully compostable, with industrial decomposition typically occurring within 45 to 60 days under optimal conditions.
By Application
Food applications lead the market with more than 70% share, as bagasse plates, clamshells, and trays are widely used for serving and packaging meals. Rising adoption by restaurants, cloud kitchens, and catering services fuels demand in this segment. Beverages contribute a smaller but growing share, driven by the use of cups, glasses, and drink carriers for hot and cold drinks. The growth in takeaway culture, on-the-go consumption, and sustainability-driven procurement policies further boost both segments. Increasing preference for compostable alternatives over plastic packaging continues to expand the market for bagasse tableware products.
Key Growth Drivers Bans on Single-Use Plastics and Regulatory Support
The market is expanding due to strict government bans on single-use plastics and supportive regulations for sustainable packaging. Many countries have introduced policies encouraging adoption of biodegradable alternatives, driving demand for bagasse-based plates, bowls, and clamshells. Foodservice operators and institutional buyers are shifting to bagasse tableware to meet compliance and corporate sustainability goals. This regulatory push strengthens market penetration across quick-service restaurants, catering services, and retail. Growing consumer preference for eco-friendly packaging further accelerates adoption, positioning bagasse products as a mainstream solution for disposable tableware.
- For instance, Aaryadi International LLP in India offers bagasse plates rated for temperature usage from -20 °C to 120 °C, and their bagasse cups and containers fully compost in 90 days in commercial composting facilities.
Growth of Food Delivery and Takeaway Services
Rising food delivery and takeaway demand is a major driver for bagasse tableware. E-commerce food platforms, cloud kitchens, and quick-service restaurants increasingly use compostable containers, trays, and clamshells for packaging. These products offer strength, temperature resistance, and leak-proof properties suitable for transporting meals. Urbanization and busy lifestyles further fuel the growth of on-the-go consumption, boosting demand for disposable, sustainable packaging. Partnerships between food aggregators and packaging manufacturers are increasing, creating consistent demand and expanding the customer base for bagasse tableware products globally.
- For instance, Sumkoka Technology manufactures a bagasse burger clamshell container (approximately 153×153×43 mm) that is freezer-safe and commonly used in takeaway and food delivery applications. This size is a standard offering within the eco-friendly food service packaging market.
Increasing Consumer Focus on Sustainability
Consumers are increasingly aware of the environmental impact of packaging waste and prefer products that are biodegradable and compostable. Bagasse tableware provides a sustainable option that supports circular economy initiatives by utilizing sugarcane waste. Retailers and brands highlight eco-friendly packaging to attract environmentally conscious buyers. Rising awareness campaigns and eco-label certifications strengthen consumer confidence in these products. This shift in consumer behavior is driving consistent market growth and motivating manufacturers to expand production capacity and innovate product designs for better performance and cost efficiency.
 Key Trends & Opportunities
Innovation in Coatings and Barrier Solutions
Manufacturers are developing bio-based coatings and water-resistant finishes to enhance performance of bagasse products. These innovations expand applications in greasy, moist, or liquid-heavy foods where conventional uncoated products may fail. Advancements in microwave-safe and heat-resistant properties are improving adoption in restaurants and catering services. The opportunity lies in replacing PE-laminated items with fully compostable barrier-coated alternatives that meet global sustainability standards. Such innovation supports compliance with regulations and strengthens the market appeal of bagasse tableware for both hot and cold food packaging.
- For instance, InNature Pack produces compostable tableware from sugarcane fibres using a high-pressure thermoforming process to create a dense, sturdy product. The high heat and pressure create strong natural bonds between the cellulose fibres, forming a low-porosity structure that resists water and oil without the need for synthetic liners or additives like AKD.
Expansion into Retail and Household Segments
Retail adoption is increasing as supermarkets, e-commerce platforms, and specialty stores offer bagasse plates, bowls, and cutlery for home use. Rising popularity of sustainable party supplies and disposable dinnerware for events boosts household consumption. Packaging in smaller, convenient packs is making these products more attractive to residential buyers. Manufacturers are leveraging online sales channels and branding initiatives to reach eco-conscious consumers. This trend is creating new revenue streams beyond the commercial and institutional segments, expanding overall market potential and strengthening brand presence.
- For instance, Bioleader, lists bagasse tableware items (plates, trays, cups) that fully compost in industrial composting conditions between 60 and 90 days, while being certified for microwave and freezer safety.
Key Challenges Higher Production and Procurement Costs
Bagasse tableware generally costs more than conventional plastic alternatives, which can hinder adoption in price-sensitive markets. The production process involves specialized equipment, molding technology, and sometimes bio-coatings, driving up costs. Small food vendors and low-margin businesses may hesitate to shift to bagasse due to these price differences. Manufacturers are working to optimize processes and achieve economies of scale to bring prices down. Wider regulatory enforcement and subsidies will be critical to overcome cost barriers and encourage broader market penetration.
Limited Awareness and Supply Chain GapsIn several developing regions, awareness about bagasse products and their benefits remains low. Inconsistent availability and limited distribution networks also restrict adoption. Small-scale suppliers face challenges in meeting large volume requirements from institutional buyers. This creates reliance on imports, which may raise costs and delay procurement. Strengthening local production capacity, building efficient logistics, and conducting awareness campaigns will be essential to overcome these challenges and ensure steady growth of the bagasse tableware product market globally.
Regional Analysis
North America
North America holds 27% market share, driven by strict single-use plastic bans and rising adoption of eco-friendly tableware in the U.S. and Canada. Quick-service restaurants, institutional caterers, and retail chains are major consumers of bagasse plates, clamshells, and trays. Government regulations and corporate sustainability programs encourage the switch to biodegradable packaging. Growing popularity of online food delivery platforms further boosts demand for durable and compostable containers. Manufacturers invest in local production facilities and distribution networks to meet increasing consumption. The region’s strong regulatory framework and consumer awareness support steady and long-term market growth.
Europe
Europe accounts for 29% market share, supported by stringent EU directives on plastic waste reduction and high consumer preference for sustainable packaging. Countries like Germany, France, and the U.K. lead in adopting bagasse tableware across foodservice and retail sectors. Institutional buyers, including schools and corporate cafeterias, are key demand drivers due to compliance with green procurement policies. Innovation in barrier coatings and compostable laminations is advancing adoption in moisture-heavy applications. Expansion of retail channels and private label offerings is fueling residential consumption. Europe’s emphasis on circular economy principles continues to drive investment in biodegradable packaging solutions.
Asia-Pacific
Asia-Pacific leads with 33% market share, making it the largest and fastest-growing regional market. China and India dominate consumption due to government-led plastic bans, rapid urbanization, and rising disposable incomes. Food delivery and quick-service restaurant growth create consistent demand for bagasse-based plates, cups, and clamshells. Local manufacturers are scaling production capacity to serve both domestic and export markets. Japan and South Korea show strong adoption in retail and institutional sectors, favoring high-quality compostable tableware. Expansion of organized retail and e-commerce further drives penetration, making Asia-Pacific the key growth engine for global bagasse tableware products.
Latin America
Latin America captures 6% market share, led by Brazil and Mexico, where regulatory actions are encouraging the transition away from plastics. The foodservice industry and catering businesses are adopting bagasse plates and containers to meet sustainability goals and consumer demand. Local sugarcane production ensures abundant raw material availability, supporting cost-effective manufacturing. The rise of casual dining chains and event catering also contributes to market expansion. Increasing export opportunities for eco-friendly products and government awareness campaigns are expected to accelerate adoption. However, price sensitivity remains a challenge, driving demand for competitively priced solutions.
Middle East & Africa
Middle East & Africa represents 5% market share, showing steady growth as governments promote sustainable packaging initiatives. GCC countries are early adopters due to rising hospitality sector demand and events catering. Bagasse trays and clamshells are gaining traction in quick-service restaurants and institutional catering services. South Africa leads in Africa with expanding retail availability and consumer awareness campaigns. Harsh climate conditions encourage the use of sturdy, heat-resistant tableware, giving bagasse products a competitive edge. Ongoing infrastructure development and growing preference for eco-friendly solutions are expected to create long-term opportunities for market players.
Market Segmentations:
By Product Segment
- Plates
- Bowls & Containers
- Cups & Glasses
- Clamshells
By Lamination
- Laminated
- Non-laminated
By Application
- Food
- Beverages
By End Use
- Commercial Use
- Institutional Use
- Household Use
By Geography
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Bagasse Tableware Product market features leading players such as Genpak, Ecoware, CPM Industries, World Centric, Albea, Biotrem, Huhtamaki, Dart Container Corporation, Biopac, and International Paper. These companies focus on expanding their product portfolios with biodegradable plates, bowls, clamshells, and cutlery to address rising demand for sustainable tableware. Major players invest in advanced molding technologies, bio-based coatings, and compostable laminations to improve durability and performance in both hot and cold food applications. Strategic partnerships with quick-service restaurants, food delivery platforms, and institutional buyers are strengthening market reach. Manufacturers also focus on scaling local production facilities to reduce logistics costs and ensure consistent supply. Competitive differentiation is increasingly based on innovation, price competitiveness, and compliance with global plastic ban regulations. Sustainability certifications, such as BPI and EN13432, are becoming critical to brand positioning, driving companies to enhance product quality and align with circular economy initiatives.
Key Player Analysis
- Genpak
- Ecoware
- CPM Industries
- World Centric
- Albea
- Biotrem
- Huhtamaki
- Dart Container Corporation
- Biopac
- International Paper
Recent Developments
- In July 2025, Huhtamaki launched new compostable ice cream cups that combine home and industrial compostability.
- In June 2025, Albea announced new eco-friendly packaging solutions for the cosmetics and foodservice sectors, spotlighting bagasse tableware and coated bagasse trays within its "Responsible Packaging" commitment to make 100% of packaging reusable, recyclable, or compostable by end-2025.
- In February 2025, World Centric earned NSF Compostability Claim verification for its disposable foodservice products, confirming compliance with rigorous compostability standards.
Report Coverage
The research report offers an in-depth analysis based on Product Segment, Lamination, Application, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for biodegradable and compostable tableware will continue to grow with stricter plastic bans.
- Plates and clamshells will remain the top-selling products due to high use in foodservice.
- Innovation in moisture and grease-resistant coatings will expand applications in hot and oily foods.
- Retail and household consumption will rise as sustainable party and home-use tableware gains popularity.
- Manufacturers will invest in automation and capacity expansion to meet rising global demand.
- Partnerships with quick-service restaurants and food delivery platforms will strengthen product adoption.
- Asia-Pacific will remain the fastest-growing region, driven by rapid urbanization and regulatory support.
- Europe will see growth fueled by strong circular economy policies and green procurement initiatives.
- Price competitiveness and economies of scale will make bagasse products more accessible in emerging markets.
- Sustainability certifications and eco-labeling will become key differentiators for market players.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Bagasse Tableware Product market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Bagasse Tableware Product market projected to grow between 2025 and 2032?
Which Bagasse Tableware Product market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Bagasse Tableware Product market?
Who are the leading companies in the Bagasse Tableware Product market?
Which region commanded the largest share of the Bagasse Tableware Product market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Bagasse Tableware Products Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Bagasse Tableware Products Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3.02 billion → 2032: USD 4.93 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Bagasse Tableware Products Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Bagasse Tableware Products Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Bagasse Tableware Products Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Bagasse Tableware Products Market Drivers
- 3.3 Bagasse Tableware Products Market Restraints & Challenges
- 3.4 Bagasse Tableware Products Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Bagasse Tableware Products Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Bagasse Tableware Products Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Bagasse Tableware Products category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Bagasse Tableware Products Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Bagasse Tableware Products Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Bagasse Tableware Products market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Bagasse Tableware Products Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Bagasse Tableware Products Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Bagasse Tableware Products Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Bagasse Tableware Products (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Bagasse Tableware Products Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Bagasse Tableware Products Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Bagasse Tableware Products Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Bagasse Tableware Products Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Bagasse Tableware Products Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Bagasse Tableware Products Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Bagasse Tableware Products Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Bagasse Tableware Products Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Bagasse Tableware Products Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
