
Market Overview:
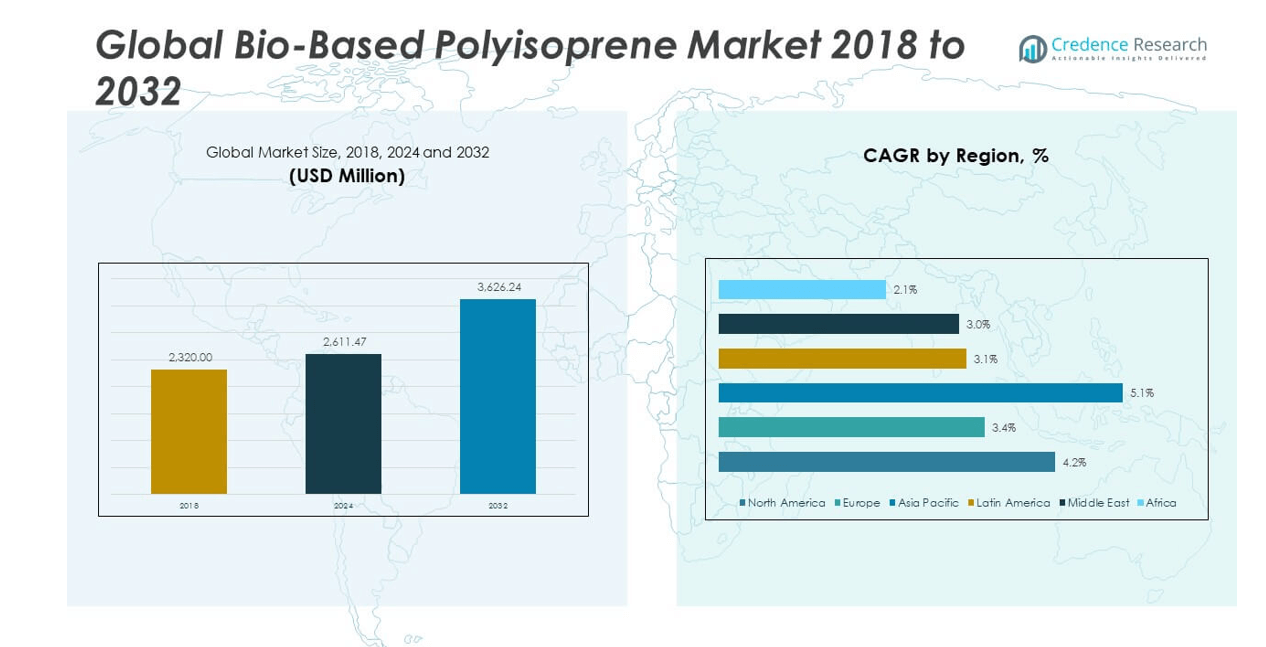
The Bio-Based Polyisoprene Market size was valued at USD 2,320.00 million in 2018 to USD 2,611.47 million in 2024 and is anticipated to reach USD 3,626.24 million by 2032, at a CAGR of 4.24% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Bio-Based Polyisoprene Market Size 2024 | USD 2,611.47 million |
| Bio-Based Polyisoprene Market, CAGR | 4.24% |
| Bio-Based Polyisoprene Market Size 2032 | USD 3,626.24 million |
Growing environmental awareness and regulatory pressure to reduce dependence on petroleum-based materials have propelled demand for bio-based polyisoprene. The market benefits from rising adoption in medical, automotive, and consumer goods sectors, where natural rubber alternatives with consistent quality and performance are essential. Continuous R&D investments by manufacturers and collaborations with biotech firms are driving innovations in bio-feedstock production. The material’s ability to deliver mechanical strength, elasticity, and low allergenicity further supports its uptake across critical end-use applications.
North America leads the bio-based polyisoprene market, driven by strong investments in sustainable materials and the presence of major manufacturers focused on biopolymer innovation. Europe follows closely due to stringent environmental regulations and consumer demand for eco-friendly products. Asia-Pacific is emerging rapidly, supported by expanding manufacturing bases, favorable government initiatives, and rising demand in automotive and healthcare sectors. Countries such as China and India are expected to contribute significantly to market growth due to increasing industrialization and bioeconomy policies.
Market Insights:
- The Bio-Based Polyisoprene Market was valued at USD 2,611.47 million in 2024 and is projected to reach USD 3,626.24 million by 2032, growing at a CAGR of 4.24%.
- Rising demand for latex-free medical products and green tires is a key driver accelerating market expansion.
- Technological advancements in microbial fermentation are improving isoprene yields and reducing production time.
- High production costs and limited industrial-scale infrastructure are restraining widespread adoption.
- North America holds 27.95% of the market share, supported by regulatory incentives and strong healthcare demand.
- Asia Pacific leads with 38.65% market share, driven by industrial growth and bioeconomy initiatives in China, India, and Japan.
- Europe maintains steady demand through strict environmental policies and consistent investments in sustainable manufacturing.
Market Drivers:
Surging Demand for Sustainable and Renewable Alternatives in Industrial Applications
The Bio-Based Polyisoprene Market is gaining traction due to growing demand for sustainable alternatives to synthetic rubber. Industrial sectors are under pressure to reduce environmental footprints, prompting a shift toward renewable feedstock materials. Bio-based polyisoprene offers similar mechanical properties to petroleum-based variants while supporting circular economy goals. It appeals to manufacturers seeking to reduce dependency on crude oil and mitigate price volatility risks. Major industries, including automotive and construction, are integrating it to meet green compliance standards. Regulatory bodies in North America and Europe are promoting biopolymer adoption across production pipelines. Increasing awareness among end-users about carbon neutrality boosts its inclusion in various applications.
- For example, Bridgestone Corporation, in partnership with Ajinomoto Co., successfully polymerized high-cis polyisoprene synthetic rubber using bio-based isoprene produced from biomass via microbial fermentation. This approach directly targets the need for sustainable, renewable raw materials in tire production.
Rising Adoption in Healthcare and Medical Device Manufacturing Due to Allergy Concerns
Healthcare sectors worldwide are shifting to bio-based polyisoprene to avoid latex allergies and maintain product safety standards. Surgical gloves, catheters, and other disposable medical products require biocompatible materials that do not compromise performance. The Bio-Based Polyisoprene Market addresses the need for a non-allergenic rubber substitute while delivering excellent elasticity and tensile strength. Hospitals and clinics are adopting these products to align with patient safety protocols and reduce clinical complications. Bio-based versions comply with strict FDA and EU regulations, allowing rapid adoption in regulated markets. Growing healthcare infrastructure in emerging regions further supports volume uptake. It improves reliability in sterile and sensitive environments where traditional latex poses health risks.
Increased Investment in R&D and Biotech Integration to Boost Production Efficiency
Technological advancements are accelerating bio-isoprene synthesis using microbial fermentation and renewable sugars. Companies are investing heavily in R&D partnerships with biotech firms to enhance cost-efficiency and scale-up. The Bio-Based Polyisoprene Market is benefiting from innovations that reduce energy consumption and improve process yield. Start-ups and established players are jointly developing genetically modified organisms for higher isoprene output. These advancements improve production economics and reduce dependence on traditional harvesting methods. It also supports greater customization for performance-specific applications. Strategic patenting and licensing deals are becoming common, fostering competitive differentiation. Government R&D funding in clean materials encourages broader innovation pipelines.
- For example, Kraton Corporation, a major innovator in specialty polymers, publicly states it maintains over 180 global R&D team members and operates seven innovation centers worldwide, as confirmed in its July 2025 press releases and corporate history.
Automotive Sector Push for Green Tires and Lightweight Materials Fuels Consumption
Global automotive OEMs are seeking green tire solutions that enhance sustainability without sacrificing performance. Bio-based polyisoprene plays a critical role in this transformation due to its durability, flexibility, and reduced environmental impact. Tire manufacturers are shifting focus to renewable materials to comply with evolving fuel-efficiency norms. The Bio-Based Polyisoprene Market benefits from growing EV production, where lightweight and eco-friendly materials are prioritized. Supply chain partners are forming alliances to ensure feedstock availability and cost-effective integration. It supports enhanced wet grip, reduced rolling resistance, and lower emissions. Automakers are incorporating it into design specifications for future vehicles. Demand from logistics fleets and public transport sectors adds to the momentum.
Market Trends
Expansion of Biorefinery Infrastructure and Regional Bioeconomy Programs
Global investments in biorefineries are enabling the production of isoprene from diverse renewable sources, including biomass and agricultural waste. Countries with strong bioeconomy agendas are supporting new facilities that enhance feedstock security and processing capacity. The Bio-Based Polyisoprene Market benefits from government-backed incentives that encourage commercial-scale deployment. These developments reduce regional dependence on imports and create self-reliant supply chains. Advanced fermentation techniques integrated with automated production are driving operational efficiency. Biorefineries also promote job creation in rural areas by sourcing local raw materials. The trend supports long-term scalability and energy transition goals. It positions bio-based polyisoprene as a key component of future sustainable industries.
- For instance, in 2025, Eni began converting its Livorno refinery in Tuscany, Italy, into a state-of-the-art biorefinery with a €500million investment supported by the European Investment Bank. The upgraded facility is designed to produce up to 500,000tonnes per year of hydrogenated biofuels using renewable raw materials such as used cooking oil and agrifood waste, powered by proprietary Ecofining™ technology.
Rise in Brand-Led Sustainability Commitments Across Consumer Goods Sectors
Global consumer brands are incorporating bio-based materials into product lines to meet internal sustainability goals. Companies in footwear, apparel, and sporting goods sectors are using bio-based polyisoprene in soles, bands, and elastic materials. The Bio-Based Polyisoprene Market is seeing increased demand from lifestyle and fashion brands prioritizing eco-conscious sourcing. Marketing strategies now highlight renewable content and biodegradability to attract environmentally aware consumers. Product differentiation through green credentials influences purchasing behavior. Companies are partnering with material innovators to gain early access to certified bio-materials. Retailers are also setting supplier mandates to increase renewable content. This trend elevates market visibility and adoption across non-industrial segments.
Emergence of Certified and Traceable Bio-Based Supply Chains
The need for traceability and certification is becoming prominent in the biopolymer space. Buyers seek assurance regarding the sustainability of raw materials used in their end products. The Bio-Based Polyisoprene Market is aligning with standards such as USDA BioPreferred and ISCC Plus to meet traceability requirements. Companies are integrating blockchain tools and digital tagging for real-time supply chain transparency. Certification improves trust among OEMs and end-users, especially in regulated industries. It helps businesses comply with ESG reporting and global sustainability frameworks. Verified sourcing supports stronger brand reputation and stakeholder confidence. Certification also unlocks access to new export markets with strict environmental mandates.
- For instance, BASF, in partnership with the Pragati Castor Program, provides certified traceability for bio-based polyurethane used in footwear, using the SuCCESS (Sustainable Castor Caring for Environmental and Social Standards) code.
Development of High-Purity Grades for Precision and Niche Applications
High-purity bio-based polyisoprene variants are being developed to address performance-critical needs in aerospace, electronics, and biomedical devices. These segments require consistent molecular structure, low extractables, and enhanced mechanical stability. The Bio-Based Polyisoprene Market is evolving to offer tailored solutions that exceed conventional rubber performance in niche conditions. Controlled polymerization processes and proprietary catalysts enable such customization. Manufacturers are building application-specific R&D labs to simulate extreme environments and optimize formulations. Collaborations with OEMs ensure technical alignment and faster product validation cycles. Specialized products command higher margins and expand revenue potential. This trend reinforces the shift toward premiumization in the market.
Market Challenges Analysis
Limited Commercial-Scale Production and Supply Constraints Impacting Market Penetration
Despite increasing demand, large-scale production of bio-based polyisoprene remains constrained by limited feedstock availability and underdeveloped processing infrastructure. The Bio-Based Polyisoprene Market faces bottlenecks in fermentation and downstream separation stages, restricting output volume. High initial capital investment and complex fermentation technology discourage new entrants. Manufacturers struggle to ensure consistent supply at competitive prices. It makes the transition from petrochemical to bio-based alternatives slower across mass-use sectors. Transport and storage costs for biomass feedstock further impact profitability. The gap between lab-scale innovation and industrial production limits cost parity. These challenges hinder scalability and broader adoption.
High Production Costs and Price Sensitivity Across End-Use Segments
Bio-based polyisoprene production is still more expensive than conventional alternatives due to costly feedstock, biocatalysts, and fermentation media. The market competes with synthetic rubber that benefits from decades of process optimization and economies of scale. The Bio-Based Polyisoprene Market must navigate resistance from cost-sensitive sectors such as packaging and consumer goods. Margins remain tight for manufacturers aiming to offer competitive pricing without compromising quality. It also limits market reach in developing regions where affordability outweighs environmental considerations. Manufacturers face pressure to reduce costs while ensuring product performance and certification. Market volatility in agricultural inputs affects production planning and cost modeling.
Market Opportunities
Expansion in Emerging Economies with Supportive Policies and Local Feedstock
Emerging markets in Asia-Pacific, Latin America, and Africa present growth avenues due to rising environmental regulations and local availability of agricultural residues. Governments are launching bioeconomy frameworks to reduce fossil fuel reliance and promote value-added exports. The Bio-Based Polyisoprene Market can leverage these opportunities to establish decentralized production hubs. It allows companies to minimize logistics costs and benefit from local incentives. Regional customization supports market-specific applications and performance needs. This approach accelerates technology transfer and innovation partnerships.
Opportunity to Innovate Across High-Performance and Functional Material Domains
There is growing demand for bio-based polymers that deliver both sustainability and superior mechanical attributes. The Bio-Based Polyisoprene Market can expand into premium sectors like aerospace, performance sportswear, and implantable medical devices. It encourages R&D to develop multi-functional composites and high-spec formulations. Collaboration with end-users enhances material alignment and adoption. Such segments offer higher returns and strategic long-term contracts.
Market Segmentation Analysis:
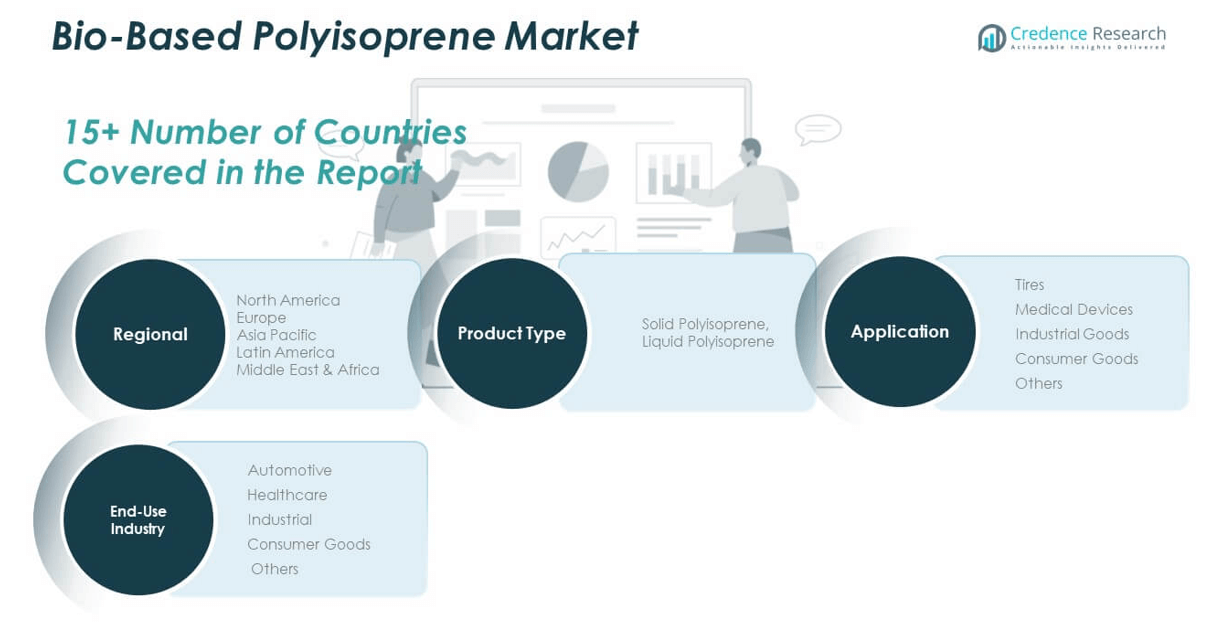
The Bio-Based Polyisoprene Market is segmented
By product type into solid and liquid polyisoprene. Solid polyisoprene dominates the segment due to its widespread application in high-performance tires, medical gloves, and technical rubber goods requiring elasticity and strength. Liquid polyisoprene, though smaller in volume, is gaining attention for specialty coatings, adhesives, and sealants where flowability and rapid curing are essential. Manufacturers are tailoring formulations to meet sector-specific needs and enhance mechanical consistency.
- For example, Kuraray’s Liquid Polyisoprene Rubber (L-IR) is tailored for specialty adhesives, automotive sealants, hot melts, and coatings, with functionalized grades such as Carboxylated L-IR-410 developed to enhance adhesion to metals and ensure high reactivity in fast-curing environments.
By application, the market spans tires, medical devices, industrial goods, consumer goods, and others. Tire applications lead due to rising demand for sustainable materials in automotive manufacturing. Medical devices are the next major segment, driven by increasing adoption of latex-free alternatives to reduce allergenic risks. Industrial and consumer goods follow, benefiting from regulatory shifts and sustainability goals in product packaging and wearables.
- For example, Teknor Apex supplies IR elastomers for premium consumer goods like fitness bands and footwear, offering enhanced elasticity and clarity for wearable electronics and apparel while maintaining durability and safety standards
By end-user, the Bio-Based Polyisoprene Market serves the automotive, healthcare, industrial, consumer goods, and other sectors. Automotive remains the leading end-user, leveraging bio-based polymers for green tires and lightweight components. Healthcare applications are expanding through disposable gloves, catheters, and tubing, especially in developed economies. Industrial users incorporate it in conveyor belts and dampening systems. Consumer goods include footwear, apparel, and lifestyle accessories, where eco-friendly materials support brand differentiation. It aligns with environmental regulations and evolving user preferences across each segment.
Segmentation:
By Product Type
- Solid Polyisoprene
- Liquid Polyisoprene
By Application
- Tires
- Medical Devices
- Industrial Goods
- Consumer Goods
- Others
By End-user
- Automotive
- Healthcare
- Industrial
- Consumer Goods
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The North America Bio-Based Polyisoprene Market size was valued at USD 658.88 million in 2018 to USD 730.15 million in 2024 and is anticipated to reach USD 1,012.09 million by 2032, at a CAGR of 4.2% during the forecast period. North America accounts for 27.95% of the global market share. It leads in technological adoption and regulatory support for sustainable materials. The U.S. drives demand through robust healthcare and automotive sectors adopting eco-friendly substitutes for latex and synthetic rubber. Research collaborations between biotech firms and material innovators enhance production efficiency and product quality. Bio-based polyisoprene adoption in tire manufacturing aligns with federal fuel-efficiency norms. Medical device manufacturers are incorporating latex-free gloves and tubing to meet safety guidelines. Demand for certified bio-based goods from government procurement adds further momentum. It benefits from an integrated supply chain and consumer awareness of green materials.
The Europe Bio-Based Polyisoprene Market size was valued at USD 512.72 million in 2018 to USD 550.43 million in 2024 and is anticipated to reach USD 713.47 million by 2032, at a CAGR of 3.4% during the forecast period. Europe holds 21.07% of the global market share. It is driven by stringent environmental regulations such as REACH and the Green Deal framework. Countries like Germany, France, and the Netherlands are pushing industrial sectors toward bio-based sourcing to meet carbon neutrality targets. The Bio-Based Polyisoprene Market in Europe benefits from growing demand for sustainable medical disposables, especially in the wake of regulatory bans on allergenic latex. Leading automakers are integrating bio-materials into tire and seal applications. Funding from EU Horizon programs supports R&D in green chemistry. It experiences steady uptake across packaging and lifestyle sectors. Market participants prioritize traceability and certification to meet evolving consumer expectations.
The Asia Pacific Bio-Based Polyisoprene Market size was valued at USD 869.07 million in 2018 to USD 1,006.58 million in 2024 and is anticipated to reach USD 1,493.65 million by 2032, at a CAGR of 5.1% during the forecast period. Asia Pacific holds the largest market share at 38.65%. The region is driven by rapid industrialization, expanding automotive production, and healthcare infrastructure development. China, Japan, and India are investing in bioeconomy frameworks and sustainable manufacturing. The Bio-Based Polyisoprene Market in Asia Pacific benefits from government incentives to reduce petroleum dependency. Domestic tire producers are increasingly sourcing renewable rubber alternatives. Healthcare facilities are scaling up procurement of biocompatible materials for gloves and catheters. Export-oriented manufacturing boosts demand for globally certified eco-friendly materials. Regional R&D hubs and foreign investments support growth across product innovation and scale.
The Latin America Bio-Based Polyisoprene Market size was valued at USD 127.14 million in 2018 to USD 141.52 million in 2024 and is anticipated to reach USD 180.12 million by 2032, at a CAGR of 3.1% during the forecast period. Latin America contributes 5.45% to the global market share. Brazil and Mexico lead regional adoption, driven by agricultural feedstock availability and favorable renewable energy policies. The Bio-Based Polyisoprene Market in Latin America sees growing use in healthcare and light manufacturing. Expansion of domestic biotech capabilities encourages local production and innovation. Imports of sustainable raw materials are decreasing due to regional investments in green refineries. Consumer goods manufacturers target biodegradable alternatives to meet environmental mandates. Industrial rubber users explore renewable sourcing for conveyor belts and molded components. Public–private partnerships play a key role in developing supply chain resilience.
The Middle East Bio-Based Polyisoprene Market size was valued at USD 95.58 million in 2018 to USD 101.31 million in 2024 and is anticipated to reach USD 128.03 million by 2032, at a CAGR of 3.0% during the forecast period. The Middle East accounts for 3.53% of the global market share. Adoption remains gradual but is supported by diversification policies in countries like the UAE and Saudi Arabia. The Bio-Based Polyisoprene Market is gaining attention in the region’s industrial and healthcare modernization agendas. Domestic initiatives to reduce carbon reliance are fostering demand for biopolymers in infrastructure and public health projects. It is influenced by import substitution strategies and sustainability targets under Vision 2030. Urban growth fuels demand for green construction materials and flexible rubber goods. Regional partnerships with international biotech firms improve technology access. Certification and cost competitiveness remain critical for wider adoption.
The Africa Bio-Based Polyisoprene Market size was valued at USD 56.61 million in 2018 to USD 81.49 million in 2024 and is anticipated to reach USD 98.88 million by 2032, at a CAGR of 2.1% during the forecast period. Africa represents 3.35% of the global market share. Growth is slow but improving as awareness of sustainable alternatives expands. The Bio-Based Polyisoprene Market in Africa benefits from donor-backed green development initiatives and healthcare procurement reform. Countries like South Africa and Kenya are exploring bio-materials in public health and light industry. Access to local biomass and sugar-based feedstocks supports early-stage production. Challenges include limited industrial capacity and higher costs of certified raw materials. NGOs and trade partnerships drive product trials in gloves, footwear, and consumer goods. Regional policy reforms could accelerate adoption across utilities and public sectors.
Key Player Analysis:
- The Goodyear Tire & Rubber Company
- Bridgestone Corporation
- Michelin Group
- Kuraray Co., Ltd.
- Sibur International GmbH
- JSR Corporation
- Versalis S.p.A.
- Zeon Corporation
- Sumitomo Chemical Co., Ltd.
- Firestone Polymers, LLC
- Trinseo S.A.
- Arlanxeo
- Sinopec (China Petroleum & Chemical Corporation)
- ExxonMobil Chemical Company
- Lanxess AG
- Asahi Kasei Corporation
- LG Chem Ltd.
- Reliance Industries Limited
- TSRC Corporation
- Nizhnekamskneftekhim PJSC
Competitive Analysis:
The Bio-Based Polyisoprene Market features a concentrated landscape with key players focusing on technological innovation, strategic alliances, and sustainable production methods. Companies such as Goodyear, Michelin, Kraton Corporation, and Bridgestone are investing in renewable feedstock sourcing and fermentation technologies to achieve consistent polymer quality. It sees rising collaboration between chemical producers and biotechnology firms to improve isoprene yields and reduce production costs. Leading players are pursuing certifications like ISCC PLUS and REDcert² to enhance product credibility in regulated sectors. Mergers and licensing agreements enable access to patented microbial strains and scalable bioprocessing platforms. Competitors aim to secure long-term contracts with automotive and healthcare clients to ensure market stability. Entry barriers remain high due to capital intensity and technical expertise requirements. It supports innovation-driven competition while favoring vertically integrated firms that control both upstream bio-feedstock and downstream processing capabilities. The market continues to evolve through global partnerships and product-specific performance enhancements.
Recent Developments:
- In May 2025, The Goodyear Tire & Rubber Company announced it had entered into a definitive agreement to sell the majority of its Goodyear Chemical business-including facilities in Houston and Beaumont, Texas, and an R&D facility in Akron, Ohio-to Gemspring Capital Management, LLC. The transaction forms part of Goodyear’s strategic transformation, with a long-term supply agreement accompanying the divestiture of its major synthetic rubber and chemical production units.
- In February 2025, Bridgestone Corporation partnered with Komatsu to launch a proof of concept aimed at improving fuel efficiency and extending tire life for mining trucks. The collaboration integrates Komatsu’s vehicle monitoring technology with Bridgestone’s tire pressure management system to provide value-added solutions for mining customers.
- In April 2025, Kuraray Co., Ltd. acquired Nelumbo Inc., a U.S.-based technology company specializing in polymer surface modifications. This acquisition supports Kuraray’s innovation initiatives and aims to enhance the environmental performance of its polymer products.
Market Concentration & Characteristics:
The Bio-Based Polyisoprene Market is moderately concentrated, with a limited number of players holding significant technological and production capabilities. It is characterized by high entry barriers due to capital requirements, proprietary microbial strains, and advanced fermentation infrastructure. Companies focus on vertical integration to control feedstock sourcing, process optimization, and end-product customization. The market emphasizes certification, traceability, and performance consistency to meet regulatory and industrial standards. Long development cycles and dependence on bio-based raw material availability shape investment strategies. It attracts firms that specialize in sustainable materials and high-spec applications. Innovation remains a key differentiator, with leading participants leveraging partnerships to scale production and expand geographic presence. The market maintains stable growth due to demand from automotive, medical, and consumer sectors.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Application and End-user. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Growing demand for sustainable materials will drive increased adoption across automotive, medical, and consumer applications.
- Advancements in microbial engineering are expected to improve isoprene yield and reduce production costs.
- Strategic partnerships between chemical and biotech companies will accelerate commercial-scale deployment.
- Expansion of certified supply chains will enhance credibility and enable broader acceptance in regulated markets.
- Government incentives for bioeconomy initiatives will support regional production and innovation hubs.
- Rising environmental regulations will push traditional rubber manufacturers toward renewable alternatives.
- Emerging economies will offer new growth avenues through localized feedstock sourcing and supportive policies.
- Product customization for high-performance sectors like aerospace and electronics will unlock premium opportunities.
- Certification standards and mass-balance tracking will become critical in shaping procurement and compliance.
- Investment in R&D and infrastructure will remain essential for maintaining competitiveness and long-term market viability.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Surging Demand for Sustainable and Renewable Alternatives in Industrial Applications
Industrial sectors are under increasing pressure to reduce their environmental footprint, prompting a shift toward renewable feedstock materials like bio-based polyisoprene. This material offers similar mechanical properties to petroleum-based variants while supporting circular economy goals and reducing dependency on crude oil.
Rising Adoption in Healthcare and Medical Device Manufacturing Due to Allergy Concerns
Healthcare providers are transitioning to bio-based polyisoprene for products such as gloves and catheters to avoid latex allergies and comply with strict safety standards. The material’s low allergenicity and biocompatibility make it a preferred alternative in regulated medical markets.
Automotive Sector Push for Green Tires and Lightweight Materials
Automotive OEMs are increasingly incorporating bio-based polyisoprene in green tires and lightweight components to meet evolving fuel-efficiency norms and sustainability targets. This trend is further accelerated by the growth of electric vehicles and regulatory mandates for eco-friendly materials.
Increased Investment in R&D and Biotech Integration
Manufacturers are investing in advanced microbial fermentation and partnerships with biotech firms to improve isoprene yields and reduce production costs. These innovations are making bio-based polyisoprene more competitive and scalable for industrial adoption.
Expansion of Biorefinery Infrastructure and Regional Bioeconomy Programs
Government-backed incentives and investments in biorefineries are enhancing feedstock security and processing capacity, especially in regions with strong bioeconomy agendas. This supports commercial-scale deployment and reduces reliance on imported raw materials.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Bio-Based Polyisoprene Market?
What are the key segments within the Bio-Based Polyisoprene Market?
What are some challenges faced by the Bio-Based Polyisoprene Market?
Who are the major players in the Bio-Based Polyisoprene Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-user
- 1.2.1 Automotive
- 1.2.2 Healthcare
- 1.2.3 Industrial
- 1.2.4 Consumer Goods
- 1.2.5 Others
- 1.3 By Application
- 1.3.1 Tires
- 1.3.2 Medical Devices
- 1.3.3 Industrial Goods
- 1.3.4 Consumer Goods
- 1.3.5 Others
- 1.4 By Product Type
- 1.4.1 Solid Polyisoprene
- 1.4.2 Liquid Polyisoprene
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,611.47 million → 2032: USD 3,626.24 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Bio-Based Polyisoprene Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Bio-Based Polyisoprene Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Bio-Based Polyisoprene Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Bio-Based Polyisoprene Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Bio-Based Polyisoprene Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Bio-Based Polyisoprene Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Bio-Based Polyisoprene Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Bio-Based Polyisoprene Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,611.47 million → 2032: USD 3,626.24 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Bio-Based Polyisoprene Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-user - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Automotive
- 12.3.7.2 Healthcare
- 12.3.7.3 Industrial
- 12.3.7.4 Consumer Goods
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Tires
- 12.4.7.2 Medical Devices
- 12.4.7.3 Industrial Goods
- 12.4.7.4 Consumer Goods
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Solid Polyisoprene
- 12.5.7.2 Liquid Polyisoprene
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Bio-Based Polyisoprene End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Bio-Based Polyisoprene Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Bio-Based Polyisoprene Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Bio-Based Polyisoprene Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 The Goodyear Tire & Rubber Company
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Bridgestone Corporation
- 18.4 Michelin Group
- 18.5 Kuraray Co., Ltd.
- 18.6 Sibur International GmbH
- 18.7 JSR Corporation
- 18.8 Versalis S.p.A.
- 18.9 Zeon Corporation
- 18.10 Sumitomo Chemical Co., Ltd.
- 18.11 Firestone Polymers, LLC
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

