
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
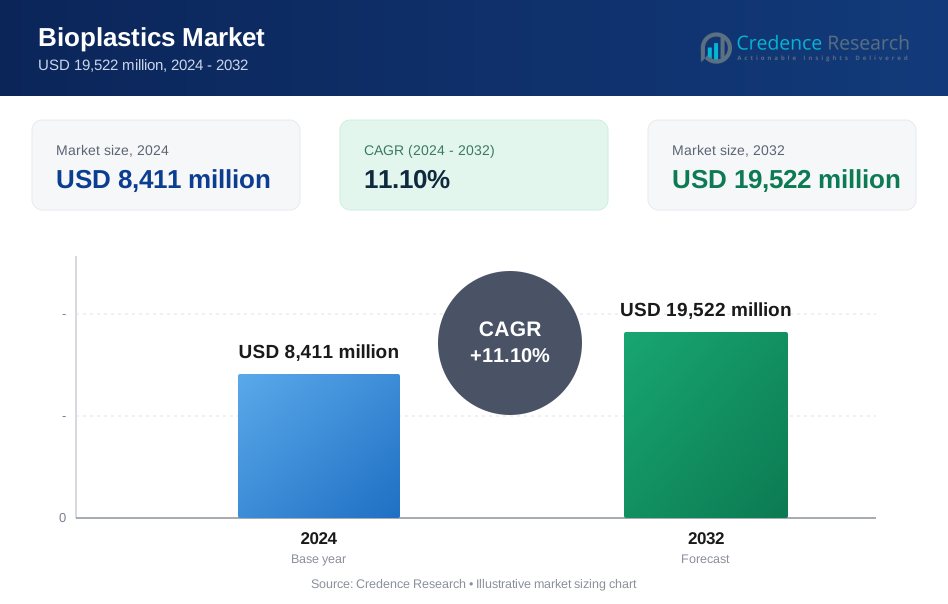
| Bioplastics Market Size 2024 | USD 8,411 Million |
| Bioplastics Market, CAGR | 11.1% |
| Bioplastics Market Size 2032 | USD 19,522 Million |
Market Overview:
The Bioplastics Market is projected to grow significantly from USD 8,411 million in 2024 to USD 19,522 million by 2032, reflecting a compound annual growth rate (CAGR) of 11.1% over the forecast period. This growth is driven by increasing demand for eco-friendly alternatives to conventional plastics, particularly in industries such as packaging, automotive, and consumer goods. Bioplastics, derived from renewable sources such as corn starch, sugarcane, and cellulose, offer the advantage of reduced carbon emissions and biodegradability, aligning with global sustainability goals and consumer preferences for environmentally friendly products.
Key market drivers include growing environmental awareness and stringent regulations aimed at reducing plastic waste. Governments worldwide are implementing policies to reduce reliance on petroleum-based plastics, which contribute to pollution and climate change. For instance, the European Union’s Single-Use Plastics Directive encourages the adoption of bioplastics in packaging and other applications. Additionally, advancements in bioplastic production technologies, coupled with increasing investments in research and development, are further fueling market growth. Major corporations like Coca-Cola and Nestlé have committed to increasing the use of bioplastics in their packaging, further boosting demand.
Regionally, Europe holds the largest share of the bioplastics market, driven by strong regulatory frameworks and the region’s focus on sustainability. Countries like Germany, France, and the Netherlands are leading the adoption of bioplastics across various industries. North America is also experiencing significant growth due to increasing consumer demand for eco-friendly products and supportive government initiatives. Meanwhile, the Asia-Pacific region, particularly China and India, is emerging as a crucial market, driven by rapid industrialization and growing awareness of environmental issues. As these regions continue to adopt bioplastics, the global market is expected to witness sustained growth in the coming years.
Market Drivers:
Increasing Environmental Awareness:
One of the primary drivers of the bioplastics market is the growing awareness of environmental issues associated with traditional petroleum-based plastics. Consumers and businesses alike are increasingly concerned about plastic pollution and its impact on ecosystems. For instance, a recent survey conducted by the European Commission revealed that 79% of Europeans consider plastic waste a significant environmental concern. In response, companies are shifting towards bioplastics as a sustainable alternative, with firms like Coca-Cola introducing bottles made from 30% plant-based materials to align with consumer preferences for eco-friendly products.
Regulatory Support and Initiatives:
Government regulations are playing a crucial role in promoting the adoption of bioplastics. Many countries are implementing stringent policies to reduce single-use plastics and encourage the use of biodegradable alternatives. For example, the U.S. has set ambitious goals under its 2030 Food Loss and Waste Reduction Initiative, which aims to increase composting infrastructure and promote compostable packaging solutions. This regulatory environment is driving demand for bioplastics, as manufacturers seek compliant materials to meet these new standards.
Technological Advancements:
Technological advancements in bioplastic production are significantly enhancing their viability and performance, further driving market growth. Innovations in polymer development have led to improved properties such as heat resistance and durability, making bioplastics more competitive with traditional materials. For instance, researchers have engineered biomass-derived polymers that can withstand temperatures up to 150°C, suitable for various applications including food packaging and consumer goods. These developments are critical as they enable manufacturers to produce high-quality bioplastics that meet industry standards.
Expanding Applications Across Industries:
The versatility of bioplastics is another key driver of market growth, as they find applications across multiple sectors including packaging, agriculture, automotive, and textiles. The packaging segment alone accounted for approximately 43% of the total bioplastics market in 2023. Companies like NatureWorks LLC are actively expanding their product lines to cater to diverse applications, reinforcing the idea that bioplastics can effectively replace conventional plastics in various contexts. This broadening scope not only enhances market opportunities but also aligns with global sustainability goals, making bioplastics an attractive option for manufacturers across industries.
Market Trends:
Rising Demand for Flexible Packaging:
A significant trend in the bioplastics market is the increasing demand for flexible packaging solutions, particularly in the food and beverage sector. Companies are recognizing the environmental benefits of using bioplastics, which can reduce reliance on traditional plastics. For instance, a 2023 survey by the European Bioplastics Association found that flexible packaging accounted for 43% of bioplastics applications, highlighting its importance in sustainable packaging initiatives. Major brands, such as Unilever and Nestlé, are actively transitioning to bioplastic materials for their packaging needs to meet consumer expectations for eco-friendly options.
Innovations in Bioplastic Materials:
The development of advanced bioplastic materials is another key trend shaping the market. Research and innovation are leading to new polymer formulations that enhance performance characteristics such as durability and heat resistance. For example, NatureWorks LLC has introduced Ingeo™, a polylactic acid (PLA) product that offers improved thermal stability and is suitable for a wider range of applications. This innovation allows manufacturers to utilize bioplastics in sectors previously dominated by traditional plastics, further expanding market opportunities.
Expansion into Automotive and Electronics:
Bioplastics are increasingly being adopted in the automotive and electronics industries due to their lightweight properties and potential for reducing carbon footprints. Companies like Ford have begun integrating bioplastic components into vehicle interiors, citing a commitment to sustainability and reduced environmental impact. A 2022 report indicated that 15% of automotive manufacturers are exploring bioplastics for various applications, reflecting a growing trend towards sustainable materials in manufacturing processes.
Government Initiatives and Support:
Government initiatives aimed at promoting sustainable practices are significantly influencing the bioplastics market. Policies encouraging the reduction of single-use plastics and promoting biodegradable alternatives are gaining traction globally. For instance, the U.S. Department of Agriculture has launched programs supporting the development of compostable materials, which directly benefits the bioplastics sector. A recent survey indicated that 68% of manufacturers believe government support is crucial for enhancing bioplastics adoption, underscoring how regulatory frameworks can drive market growth.
Market Challenges Analysis:
High Production Costs:
One of the primary challenges facing the bioplastics market is the high production costs associated with bioplastic materials compared to traditional petroleum-based plastics. The raw materials used in bioplastics, often derived from agricultural sources, can be significantly more expensive. A recent report indicated that bioplastics can cost up to 30% more than conventional plastics, making it challenging for manufacturers to compete on price. This financial barrier can deter companies from transitioning to bioplastics, particularly in price-sensitive markets.
Limited Availability of Feedstock:
The availability of suitable feedstock for bioplastic production presents another significant restraint. As the demand for bioplastics grows, competition for agricultural resources intensifies, potentially impacting food supply chains. Government authorities, such as the U.S. Department of Agriculture, have noted concerns regarding the allocation of land and resources for bioplastic feedstock versus food production. This competition may limit the scalability of bioplastic production and hinder market growth.
Regulatory Complexity:
Navigating the complex regulatory landscape surrounding bioplastics poses a considerable challenge. Different countries and regions have varying definitions and standards for what qualifies as a bioplastic, leading to confusion among manufacturers and consumers alike. For example, the European Union's stringent regulations on compostability and biodegradability can complicate compliance for producers. A lack of harmonization in regulations can create barriers to entry for new players in the market, as they must navigate these inconsistencies to achieve certification and market acceptance.
Waste Management Challenges:
Finally, effective waste management remains a critical challenge for the bioplastics market. While bioplastics are designed to be more environmentally friendly, their disposal and recycling processes are not yet fully established. Many existing waste management systems are not equipped to handle bioplastics properly, leading to potential contamination with conventional plastics during recycling processes. Government initiatives aimed at improving waste management infrastructure are essential; however, until these systems are in place, widespread adoption of bioplastics may be hindered.
Market Segmentation Analysis:
By Type
The Bioplastics Market is segmented by type into biodegradable and non-biodegradable bioplastics. Biodegradable bioplastics, including polylactic acid (PLA) and polyhydroxyalkanoates (PHA), are gaining popularity due to their ability to decompose naturally. These materials are primarily used in short-term applications such as food packaging and disposable items. Non-biodegradable bioplastics, such as bio-based polyethylene (PE) and bio-based PET, are more durable and are used in long-lasting applications like automotive components and consumer goods packaging. Their resistance to environmental degradation makes them ideal for industries requiring durable solutions.
By Technology
In terms of technology, bioplastics are produced using fermentation and polymerization methods. Fermentation is commonly used for the production of biodegradable plastics such as PLA, which are derived from renewable sources like corn and sugarcane. Polymerization, on the other hand, is widely employed to produce non-biodegradable bioplastics like bio-based PE and PET, offering similar characteristics to conventional plastics while reducing the carbon footprint.
By End User
The market is also segmented by end user into packaging, automotive, agriculture, textiles, and consumer goods. The packaging industry is the largest consumer of bioplastics due to the growing demand for sustainable packaging solutions. The automotive and agriculture sectors are also experiencing increased adoption, as bioplastics offer lightweight and eco-friendly alternatives to traditional materials, enhancing fuel efficiency and reducing environmental impact.
Segmentations:
By Type
- Biodegradable
- Starch Blends
- Polylactic Acid (PLA)
- Polybutylene Adipate Terephthalate (PBAT)
- Polybutylene Succinate (PBS)
- Polyhydroxyalkanoates (PHA)
- Other Biodegradables
- Non-Biodegradable
- Bio-Polyethylene Terephthalate (Bio-PET)
- Bio-Polyamide (Bio-PA)
- Bio-Polyethene (Bio-PE)
- Bio-Polytrimethylene Terephthalate (Bio-PTT)
- Other Non-Biodegradables
By Application
- Rigid Packaging
- Bottles & Jars
- Trays
- Others
- Flexible Packaging
- Pouches
- Shopping / Waste Bags
- Others
- Textiles
- Automotive & Transportation
- Agriculture & Horticulture
- Consumer Goods
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Europe
Europe holds the largest share of the global bioplastics market, accounting for approximately 40% of the total market. This dominance is driven by the region's strong regulatory environment, which encourages the adoption of sustainable materials through policies such as the European Union’s Single-Use Plastics Directive. Countries like Germany, France, and the Netherlands are leading in bioplastic production and consumption, particularly in the packaging industry, where sustainability is a key concern. European manufacturers are heavily investing in research and development, making the region a hub for bioplastic innovation. Additionally, government support for bio-based industries further propels market growth in the region.
North America
North America accounts for around 25% of the global bioplastics market. The United States leads this growth, supported by increasing consumer demand for environmentally friendly products and corporate commitments to sustainability. Companies in industries like packaging, automotive, and consumer goods are transitioning to bioplastics to reduce their carbon footprint. Government initiatives such as the U.S. Plastics Pact, which aims to ensure 100% of plastic packaging is reusable, recyclable, or compostable by 2025, are further driving the adoption of bioplastics. The region is also seeing significant investment in technological advancements to enhance bioplastic production capabilities.
Asia-Pacific
The Asia-Pacific region holds a significant share, around 30%, and is emerging as a key growth market for bioplastics. Countries like China, India, and Japan are increasingly adopting bioplastics, driven by government policies to reduce plastic waste and curb pollution. For instance, China’s ban on single-use plastics in major cities has accelerated the demand for sustainable alternatives, pushing industries to shift toward bioplastics. Rapid industrialization, combined with growing environmental awareness, is contributing to the region’s growth, especially in sectors like packaging, agriculture, and textiles.
Latin America and Middle East & Africa
Latin America and the Middle East & Africa account for smaller shares of the bioplastics market, but they are witnessing gradual growth. In Latin America, countries like Brazil are focusing on bioplastics due to their rich availability of agricultural feedstocks like sugarcane, which are used in bioplastic production. The Middle East & Africa are seeing increasing interest in sustainable materials, driven by economic diversification efforts and environmental concerns. Though these regions currently hold around 5% of the global market, investments in bioplastic technologies and infrastructure are expected to fuel future growth.
Key Player Analysis:
- NatureWorks LLC
- BASF SE
- Braskem
- TotalEnergies Corbion
- Danimer Scientific
- Novamont S.p.A.
- Biome Bioplastics
- FKuR Kunststoff GmbH
- Biotech GmbH
- Arkema S.A.
Competitive Analysis:
The Bioplastics Market is marked by intense competition among key players striving for innovation and market expansion. Leading companies like NatureWorks, BASF SE, and Braskem dominate the landscape, driven by their robust research and development efforts to improve bioplastic performance and scalability. These companies leverage advanced technologies to produce both biodegradable and non-biodegradable bioplastics, catering to industries such as packaging, automotive, and consumer goods. Meanwhile, companies like Novamont and TotalEnergies Corbion focus on expanding their bio-based product portfolios, with an emphasis on compostable materials. Competition is also fueled by increasing regulatory pressures and consumer demand for eco-friendly alternatives to conventional plastics. Smaller players, such as Biome Bioplastics and FKuR Kunststoff GmbH, are making strides by offering niche, high-performance bioplastic solutions, particularly in specialized applications. Strategic collaborations and acquisitions are common as companies seek to strengthen their market positions and drive global growth.
Recent Developments:
- BASF announced in 2024 that it would shift its entire Ethyl Acrylate (EA) production to bio-based materials. Starting in Q4 2024, BASF will offer exclusively bio-based EA, which reduces carbon emissions by 30% compared to traditional EA. This product will target industries such as coatings and adhesives, helping them meet sustainability goals.
- Braskem expanded its bio-based ethylene production capacity by 30% in 2023, following an investment of USD 87 million. The facility in Brazil now operates at 260,000 tons per year, supporting Braskem’s commitment to increase biopolymer production and achieve carbon neutrality by 2050.
- In 2023, BASF launched a biomass-balanced version of ecoflex®, a biodegradable biopolymer that supports the packaging industry by reducing the consumption of fossil resources. This product contributes to the circular economy and offers a drop-in solution that requires no new investment from manufacturers.
- BASF also celebrated the 25th anniversary of its ecoflex® biopolymer in 2023, highlighting its role in the creation of certified compostable packaging solutions. The company continues to innovate in biopolymers, helping the food packaging and agricultural sectors reduce plastic waste and enhance composting practices.
Market Concentration & Characteristics:
The Bioplastics Market is moderately concentrated, with key players such as BASF SE, Braskem, NatureWorks, and Novamont leading the industry. These companies dominate due to their extensive production capabilities, global reach, and continuous investment in research and development. They are driving innovation in both biodegradable and bio-based non-biodegradable plastics, catering to various sectors including packaging, automotive, and consumer goods. The market is characterized by a strong focus on sustainability, with increasing consumer demand for eco-friendly products and stringent government regulations encouraging the use of renewable materials. Smaller players are also emerging, offering niche solutions and competing through technological advancements and sustainable product offerings. Overall, the market is highly competitive, with companies striving to develop bioplastics that meet performance standards similar to conventional plastics while reducing environmental impact.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for bioplastics will continue to grow, driven by increasing environmental regulations and sustainability goals worldwide.
- Advancements in production technologies will make bioplastics more cost-effective, allowing broader adoption across industries such as packaging, automotive, and consumer goods.
- Companies will increase investment in research and development to improve the durability and performance of bioplastics, matching or exceeding traditional plastic standards.
- Biodegradable and compostable bioplastics will see heightened demand, especially in sectors like food packaging, as consumers and businesses seek eco-friendly alternatives.
- The shift towards a circular economy will boost the use of bio-based materials, with bioplastics playing a key role in reducing plastic waste and promoting recyclability.
- Government initiatives, such as the European Union’s Single-Use Plastics Directive, will further encourage the shift toward bioplastics in packaging and manufacturing.
- The Asia-Pacific region, particularly China and India, will emerge as crucial markets due to rapid industrialization and growing environmental awareness.
- Strategic partnerships between bioplastic manufacturers and major brands will accelerate the commercialization of new bioplastic products.
- Corporate sustainability initiatives will drive the use of bioplastics, with companies aiming to meet carbon reduction targets and reduce their environmental footprints.
- Consumer demand for sustainable and eco-friendly products will continue to pressure industries to adopt bioplastics, creating new opportunities for growth and innovation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Bioplastics Market?
What factors are driving the growth of the Bioplastics Market?
What are some challenges faced by the Bioplastics Market?
Who are the major players in the Bioplastics Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Bioplastics Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Bioplastics Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 8,411 million → 2032: USD 19,522 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Bioplastics Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Bioplastics Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Bioplastics Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Bioplastics Market Drivers
- 3.3 Bioplastics Market Restraints & Challenges
- 3.4 Bioplastics Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Bioplastics Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Bioplastics Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Bioplastics category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Bioplastics Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Bioplastics Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Bioplastics market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Bioplastics Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Bioplastics Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Bioplastics Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Bioplastics (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Bioplastics Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Bioplastics Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Bioplastics Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Bioplastics Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Bioplastics Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Bioplastics Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Bioplastics Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Bioplastics Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Bioplastics Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
