
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Blood Glucose Monitoring Devices Market Size 2024 | USD 16202.5 million |
| Blood Glucose Monitoring Devices Market, CAGR | 10.8% |
| Blood Glucose Monitoring Devices MarketSize 2032 | USD 36804.43 million |
Market Overview:
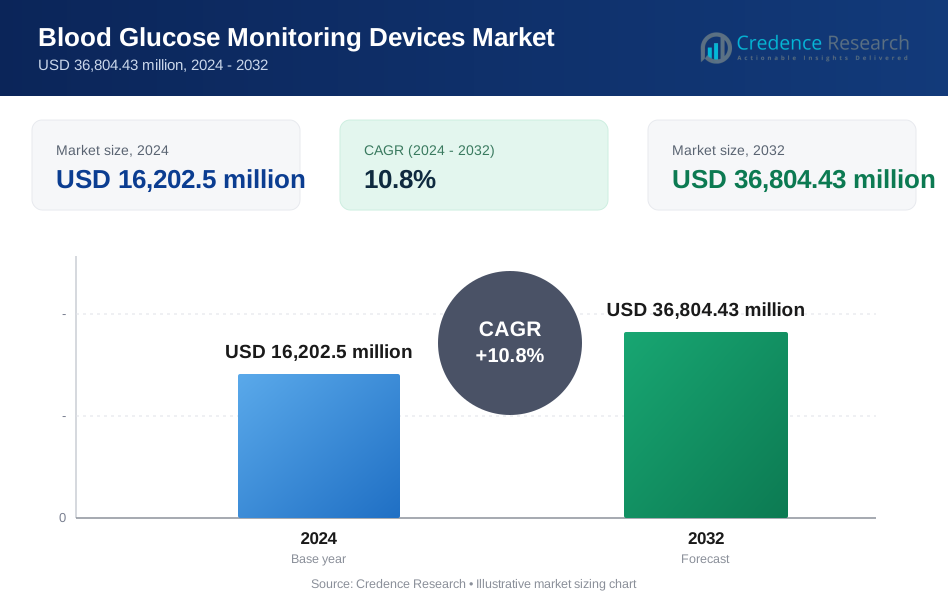
The Blood Glucose Monitoring Devices Market is projected to grow from USD 16202.5 million in 2024 to an estimated USD 36804.43 million by 2032, with a compound annual growth rate (CAGR) of 10.8% from 2024 to 2032.
Growth is driven by the rising global prevalence of diabetes, including Type 1 and Type 2. Sedentary lifestyles, poor diets and obesity continue to increase disease incidence. Demand for accurate and efficient glucose monitoring solutions has expanded in response. The market reflects strong technological progress, including continuous glucose monitoring systems that provide real-time data. Advances in noninvasive monitoring and integration with smartphone applications have improved ease of use. Higher health awareness, better access to care and the expansion of home diagnostics support adoption. Broader use of advanced monitoring devices supports improved disease management and quality of life.
North America holds the largest share of the blood glucose monitoring devices market. High diabetes prevalence, advanced health care infrastructure and strong investment in medical technology support regional growth. The presence of leading companies in the United States and Canada, along with supportive reimbursement policies, strengthens market position. Europe follows, supported by rising health care spending, an aging population and government initiatives focused on diabetes care. Asia-Pacific is expected to record the fastest growth during the forecast period, led by expanding patient populations in China and India. Improved access to care, rising incomes and public health initiatives support expansion. Latin America and the Middle East and Africa are projected to post moderate growth, supported by infrastructure improvements and increased investment in diabetes management.
Market Insights:
- The blood glucose monitoring devices market is projected to grow from USD 16,202.5 million in 2024 to USD 36,804.43 million by 2032, with a CAGR of 10.8%.
- Rising diabetes prevalence, particularly Type 2 diabetes, is driving demand for glucose monitoring solutions globally.
- Technological advancements such as continuous glucose monitoring (CGM) systems and non-invasive devices are revolutionizing diabetes management.
- The growing focus on patient empowerment and home diagnostics is increasing the adoption of glucose monitoring devices.
- North America leads the market, accounting for approximately 40% of the global share, driven by high diabetes rates and advanced healthcare infrastructure.
- Europe follows with 30% of the market share, bolstered by an aging population and strong government initiatives promoting diabetes care.
- Asia-Pacific is the fastest-growing region, expected to see substantial growth due to rising diabetes awareness, healthcare access, and disposable incomes.
Market Drivers:
Rising Prevalence of Diabetes
One of the key drivers of the blood glucose monitoring devices market is the rising prevalence of diabetes globally, particularly Type 2 diabetes. The increasing rates of obesity, sedentary lifestyles, and unhealthy eating habits have contributed to the growing incidence of diabetes, leading to a higher demand for glucose monitoring solutions. According to the World Health Organization (WHO), the global diabetes population is expected to reach 700 million by 2045. This widespread health issue is increasing the need for accurate and efficient blood glucose monitoring devices to manage the disease and prevent complications. As more people are diagnosed with diabetes, both the demand for home-based monitoring solutions and advanced technologies like continuous glucose monitoring (CGM) systems is rising, further expanding the market.
Technological Advancements in Monitoring Devices
Technological innovations in blood glucose monitoring devices have significantly driven the growth of the market. Advancements such as continuous glucose monitoring systems, non-invasive glucose meters, and smartphone-integrated devices have transformed diabetes management. For instance, Abbott's FreeStyle Libre 2 system provides real-time glucose readings and reduces the need for frequent fingerstick testing. hese technologies allow for real-time glucose monitoring, reducing the need for frequent fingerstick testing and providing more accurate data to patients and healthcare providers. Non-invasive devices, in particular, have generated interest by offering painless alternatives to traditional glucose monitoring methods, enhancing the user experience. These advancements are making diabetes management more efficient, accessible, and convenient, especially for individuals who require constant monitoring. The integration of mobile apps with glucose monitors is also improving adherence to treatment plans and offering personalized insights, contributing to the market's growth.
Increasing Healthcare Awareness and Patient Empowerment
Another significant driver of the blood glucose monitoring devices market is the increasing awareness surrounding diabetes management and patient empowerment. As awareness about the risks and complications associated with diabetes grows, patients are more proactive in managing their condition, leading to an increase in the adoption of blood glucose monitoring devices. For example, BeatO, a digital care ecosystem, combines proprietary IoT hardware with an app ecosystem to help people manage their condition. BeatO's AI triaging system, HealthNeuron, provides actionable insights and real-time intervention through personalized nudges, connecting users to health coaches and doctors. With more information available about diabetes management, patients are seeking advanced, user-friendly devices that provide real-time data and enhance their control over their health. Additionally, healthcare providers are increasingly recommending home-based monitoring solutions to enable patients to better manage their condition between medical visits. The shift towards patient-centric care is empowering individuals to take an active role in monitoring their blood glucose levels, further fueling the demand for blood glucose monitoring devices.
Government Initiatives and Support for Diabetes Care
Governments around the world are recognizing the growing burden of diabetes and are implementing policies and initiatives to improve diabetes care. These include funding for public health campaigns, national diabetes management programs, and increased reimbursement for diabetes-related treatments and technologies. For example, the Medicare program in the United States expanded access to continuous glucose monitoring systems like the FreeStyle Libre 2 for insulin-using beneficiaries. Governments are also encouraging the adoption of innovative healthcare technologies to improve patient outcomes and reduce the long-term economic impact of diabetes. In regions such as North America and Europe, government support is facilitating access to glucose monitoring devices for both diabetic patients and healthcare providers. As healthcare systems invest in better diabetes management tools, the demand for advanced glucose monitoring devices continues to rise, further driving the market's growth.
Market Trends:
Growing Popularity of Continuous Glucose Monitoring (CGM) Systems
A significant trend in the blood glucose monitoring devices market is the increasing adoption of Continuous Glucose Monitoring (CGM) systems. These devices provide real-time glucose readings and offer more consistent monitoring compared to traditional fingerstick tests. CGMs are becoming increasingly popular among patients with Type 1 and Type 2 diabetes who need to manage their blood glucose levels more effectively. For instance, Dexcom's G6 CGM system provides real-time glucose data every five minutes and alerts users of high or low glucose levels. These systems not only enhance the accuracy of glucose tracking but also help reduce the risks of hypoglycemia and hyperglycemia by providing immediate feedback, enabling patients to make timely adjustments to their treatment regimen. As CGM technology continues to improve, it is expected to further revolutionize diabetes management, with more patients opting for these devices over traditional methods due to their convenience and superior monitoring capabilities.
Integration with Mobile Health Applications
The integration of blood glucose monitoring devices with mobile health applications is another prominent trend that is shaping the market. This trend is driven by the growing use of smartphones and wearable devices in healthcare. Many modern glucose monitors now sync with mobile apps, allowing users to track their blood glucose levels in real-time and share this data with healthcare providers. For example, Abbott's FreeStyle LibreLink app allows users to scan their FreeStyle Libre sensor with their smartphone to get real-time glucose readings and trends. These apps often provide additional functionalities such as trend analysis, reminders for testing, and customized recommendations. This shift towards a more connected healthcare ecosystem is improving patient engagement and adherence to treatment plans. By enabling patients to monitor their condition more easily, mobile-enabled blood glucose monitors are contributing to better long-term health outcomes and more effective disease management.
Rise of Non-Invasive Blood Glucose Monitoring Technologies
Non-invasive blood glucose monitoring technologies are gaining traction as a market trend, driven by the desire to provide painless alternatives to traditional fingerstick methods. Several companies are focusing on developing glucose monitors that do not require blood samples, instead using techniques such as infrared spectroscopy, electromagnetic sensing, and sweat analysis. For example, DiaMonTech GmbH has developed a non-invasive glucose monitoring device that uses infrared light to measure glucose levels through the skin. The potential to eliminate the discomfort associated with traditional testing methods makes these devices highly attractive to patients, particularly those who require frequent glucose monitoring. As non-invasive technologies continue to improve in accuracy and reliability, their adoption is expected to increase, expanding the market for these innovative solutions. While challenges remain, such as regulatory approval and device calibration, advancements in these technologies are paving the way for more accessible and user-friendly blood glucose monitoring options.
Expanding Market for Smart and Wearable Devices
Another key trend in the blood glucose monitoring devices market is the increasing popularity of smart and wearable devices designed for diabetes management. These devices, often integrated with sensors and data analytics, allow for continuous monitoring of glucose levels while offering a more discrete and convenient way to manage diabetes. Wearable devices, such as smartwatches and fitness trackers with integrated glucose monitoring capabilities, are becoming a part of everyday life for many people with diabetes. For instance, the Apple Watch Series 7, when paired with the Dexcom G6 CGM, allows users to view their glucose levels directly on their watch. The ability to track glucose levels seamlessly throughout the day, without the need for invasive testing, is enhancing the patient experience and empowering individuals to take a more active role in managing their health. As wearable technology continues to advance, its integration with blood glucose monitoring solutions is expected to grow, providing even more opportunities for market expansion
Market Challenges Analysis:
High Cost of Advanced Monitoring Devices
One of the primary restraints in the blood glucose monitoring devices market is the high cost associated with advanced monitoring technologies. Continuous glucose monitoring (CGM) systems and non-invasive glucose meters, while offering numerous benefits in terms of accuracy and real-time tracking, can be prohibitively expensive for many patients, especially in developing markets. The upfront cost of these devices, along with ongoing costs such as sensors, batteries, and maintenance, poses a significant barrier to widespread adoption. While insurance coverage may offset some of the costs in certain regions, high out-of-pocket expenses remain a challenge for many individuals. The financial burden associated with these advanced devices limits their accessibility, especially among cost-sensitive populations, thereby hindering overall market growth.
Regulatory and Compliance Barriers
The blood glucose monitoring devices market faces challenges related to stringent regulatory requirements and approval processes. In many countries, devices must undergo extensive clinical trials and testing to meet the standards set by regulatory bodies such as the FDA, EMA, and others. The process can be lengthy and expensive, particularly for new technologies like non-invasive glucose monitoring devices, which require additional validation to ensure their accuracy and safety. Regulatory approval delays or rejections can slow down the market entry of innovative products and increase the costs for manufacturers. Companies must also ensure ongoing compliance with changing regulations, further complicating the development and commercialization of new devices. These barriers pose challenges to both established players and new entrants seeking to innovate in the space.
Technological Limitations and Accuracy Concerns
Despite advancements in glucose monitoring technology, some devices still face challenges related to accuracy and reliability. While continuous glucose monitoring systems provide real-time data, they are not always as accurate as traditional fingerstick methods, especially in certain conditions, such as during rapid changes in blood sugar levels. Non-invasive glucose monitoring technologies, although promising, have not yet reached the level of precision required to replace traditional testing methods for all patients. These technological limitations can affect patient trust and acceptance, slowing the adoption of newer devices. Manufacturers continue to face the challenge of improving the accuracy and reliability of these devices to ensure they meet the clinical standards necessary for widespread use.
Limited Adoption in Emerging Markets
Another significant challenge is the limited adoption of blood glucose monitoring devices in emerging markets, where healthcare infrastructure and affordability remain obstacles. In regions such as Latin America, the Middle East, and parts of Asia-Pacific, the high cost of advanced devices, along with limited healthcare insurance coverage, reduces the accessibility of these products. Additionally, lack of awareness and education about diabetes management in some areas leads to lower adoption rates. While the incidence of diabetes is rising in these regions, the market for blood glucose monitoring devices remains underpenetrated. Addressing these barriers will require efforts to lower costs, improve distribution networks, and increase patient education to promote the adoption of glucose monitoring solutions in these underserved markets.
Market Opportunities:
A significant opportunity in the blood glucose monitoring devices market lies in the growing demand from emerging markets, particularly in regions such as Asia-Pacific, Latin America, and the Middle East & Africa. The increasing prevalence of diabetes in these regions, driven by factors like urbanization, dietary changes, and aging populations, creates a substantial need for blood glucose monitoring solutions. Although these markets face challenges related to cost and healthcare infrastructure, there is a growing trend toward improving healthcare access and increasing diabetes awareness. As governments and private sectors invest in healthcare infrastructure and initiatives to combat diabetes, there is considerable potential for market expansion. Offering affordable and accessible blood glucose monitoring devices tailored to the needs of these regions presents a significant growth opportunity for manufacturers.
Another key opportunity for the blood glucose monitoring devices market lies in the continuous advancements in technology, which are making glucose monitoring more accurate, convenient, and user-friendly. The development of non-invasive glucose monitors and wearable devices, such as smartwatches integrated with glucose monitoring capabilities, is poised to expand the market. These innovations cater to a growing demand for more comfortable and efficient monitoring solutions, especially among patients who require frequent testing. Furthermore, as patients become more empowered to manage their health, there is an increasing demand for personalized and integrated solutions, such as apps that sync with glucose meters to provide real-time data and insights. Manufacturers that focus on developing and enhancing these patient-centric technologies have significant opportunities to capture a larger share of the market.
Market Segmentation Analysis:
The blood glucose monitoring devices market is segmented by product type and end-use, each catering to different patient needs and healthcare settings.
By Product, the market is divided into self-monitoring devices and continuous blood glucose monitoring (CGM) devices. Self-monitoring devices include blood glucose meters, testing strips, and lancets, which are widely used by individuals with diabetes for daily monitoring of their blood glucose levels. These devices are commonly used in home care settings, providing patients with an accessible and affordable way to manage their condition. On the other hand, continuous blood glucose monitoring devices comprise sensors, transmitters & receivers, and insulin pumps. These advanced devices offer real-time, continuous monitoring of blood glucose levels, enabling more precise management, especially for individuals with Type 1 diabetes or those requiring intensive insulin therapy. The increasing adoption of CGM systems is driven by the growing demand for more accurate and real-time glucose monitoring solutions.
By End-use, the market is divided into hospitals, home care, and diagnostic centers. Hospitals and diagnostic centers are primary users of advanced glucose monitoring devices, especially for patients requiring frequent monitoring due to critical conditions. The home care segment is the largest end-use segment, driven by the growing preference for home-based diabetes management solutions. The demand for self-monitoring devices in the home care setting is rising as patients become more empowered to manage their condition with minimal healthcare intervention. Additionally, the increasing prevalence of diabetes is fueling growth in all segments of the market.
Segmentation:
By Product
- Self-monitoring Devices
- Blood Glucose Meter
- Testing Strips
- Lancets
- Continuous Blood Glucose Monitoring Devices
- Sensors
- Transmitter & Receiver
- Insulin Pumps
By End-use
- Hospitals
- Home Care
- Diagnostic Centers
By Regional
- North America
- United States
- Canada
- Europe
- Germany
- United Kingdom
- France
- Italy
- Asia-Pacific
- China
- India
- Japan
- Australia
- Latin America
- Brazil
- Mexico
- Argentina
- Middle East and Africa
- South Africa
- UAE
- Saudi Arabia
Regional Analysis:
The global blood glucose monitoring devices market is experiencing varied growth trends across different regions, driven by factors such as the prevalence of diabetes, healthcare infrastructure, technological adoption, and regulatory standards. Each region exhibits distinct characteristics influencing market dynamics.
North America holds the largest market share, accounting for approximately 40% of the global market. The region’s dominance is primarily due to the high prevalence of diabetes, particularly in the United States, where diabetes rates have been rising steadily. In addition, the presence of a well-established healthcare system, strong regulatory frameworks, and high healthcare expenditure contribute to the widespread adoption of advanced glucose monitoring devices, including continuous glucose monitoring (CGM) systems. The robust research and development landscape in North America fosters innovation, and government policies that support diabetes management further enhance market growth. As the population ages and more people are diagnosed with diabetes, the demand for both home-use and clinical glucose monitoring solutions is expected to continue rising.
Europe follows closely, holding about 30% of the global market share. The demand for blood glucose monitoring devices in Europe is driven by a combination of an aging population, increasing diabetes prevalence, and the growing adoption of advanced monitoring technologies. The European market is also supported by healthcare policies that promote diabetes care and management. Countries like Germany, the UK, and France are leading the region in terms of market size, with increasing investments in digital health solutions and diabetes management programs. Moreover, European regulatory standards, which emphasize patient safety and quality control, encourage the adoption of high-performance glucose monitoring devices, further boosting market growth.
Asia-Pacific is the fastest-growing region, capturing around 20% of the global market share. The rapid rise in the prevalence of diabetes in countries like China, India, and Japan, coupled with expanding healthcare infrastructure, is driving the demand for blood glucose monitoring devices. Additionally, increasing disposable income and a growing middle class are making advanced healthcare solutions more accessible in these regions. As diabetes awareness rises and technology adoption increases, the demand for both conventional and advanced glucose monitoring systems is expected to accelerate. Innovations in non-invasive glucose monitoring technologies and wearable devices are expected to further fuel market expansion in this region.
Key Player Analysis:
- Abbott
- Ascensia Diabetes Care Holdings AG
- Dexcom, Inc.
- F. Hoffmann-La Roche Ltd
- Glysens Incorporated
- Insulet Corporation
- Medtronic plc
- Novo Nordisk
- Sanofi
- Thermo Fisher Scientific (Patheon)
- Ypsomed Holdings
Competitive Analysis:
The blood glucose monitoring devices market is highly competitive, with several key players dominating the global landscape. Leading companies such as Abbott Laboratories, Medtronic, Roche Diagnostics, Dexcom, and Johnson & Johnson are at the forefront, offering a wide range of glucose monitoring solutions, including continuous glucose monitoring (CGM) systems and traditional blood glucose meters. These companies benefit from strong brand recognition, extensive distribution networks, and robust research and development (R&D) capabilities that allow them to introduce innovative solutions that meet the evolving needs of diabetic patients. In addition to these industry giants, a growing number of smaller players and startups are entering the market, offering specialized solutions like non-invasive glucose monitors and wearable devices. The competitive landscape is also shaped by strategic partnerships, acquisitions, and collaborations, as companies seek to expand their technological offerings and strengthen their market positions. Innovation in glucose monitoring technologies and patient-centric solutions remains a key differentiator in this dynamic market.
Recent Developments:
- In October 2025, OSR Holdings announced it signed a definitive agreement to acquire Woori IO, a developer of noninvasive glucose monitoring technology, via a share exchange.
- In September 2024, Senseonics and Ascensia Diabetes Care announced U.S. FDA clearance of Eversense 365, describing it as a 365-day implantable CGM, with a U.S. launch expected in Q4 2024.
- In July 2024, Roche announced it received CE Mark for its Accu-Chek SmartGuide CGM solution (AI-enabled predictions) and said it planned to launch in selected European markets in the coming months.
- In June 2024, Abbott announced U.S. FDA clearance for two over-the-counter CGM systems-Lingo and Libre Rio-targeting wellness users and adults with type 2 diabetes not using insulin, respectively.
Market Concentration & Characteristics:
The blood glucose monitoring devices market is moderately concentrated, with a few major players commanding a significant share of the market. Leading companies such as Abbott Laboratories, Medtronic, Roche Diagnostics, Dexcom, and Johnson & Johnson dominate the market by offering a broad range of glucose monitoring solutions, including continuous glucose monitoring (CGM) systems, traditional meters, and wearable devices. These companies benefit from established brand recognition, extensive distribution networks, and robust research and development capabilities that allow them to innovate and maintain competitive advantages. Despite the dominance of these global players, the market is characterized by increasing competition from smaller companies and startups that specialize in non-invasive glucose monitoring solutions and smart wearable devices. Additionally, there is growing innovation in the sector, with an emphasis on improving the accuracy, comfort, and convenience of glucose monitoring, which is creating new opportunities for both established and emerging players to differentiate themselves in the market.
Report Coverage:
The research report offers an in-depth analysis based on By Product and By End-use . It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market is expected to grow steadily due to the increasing prevalence of diabetes worldwide.
- Technological advancements in continuous glucose monitoring (CGM) systems will drive adoption across various patient segments.
- Non-invasive glucose monitoring devices are anticipated to gain traction as they offer a more comfortable and user-friendly alternative.
- Wearable devices integrated with glucose monitoring capabilities will continue to gain popularity among health-conscious consumers.
- The rise of personalized medicine will lead to a higher demand for advanced and customizable glucose monitoring solutions.
- Emerging markets, particularly in Asia-Pacific and Latin America, will experience rapid growth due to rising diabetes rates and improving healthcare infrastructure.
- Healthcare providers will increasingly promote home-based glucose monitoring solutions, enhancing patient convenience and management.
- Mobile health applications paired with glucose monitoring devices will further enhance patient engagement and adherence to treatment plans.
- Governments and regulatory bodies will play a critical role in encouraging the adoption of glucose monitoring technologies through favorable policies and reimbursement programs.
- The growing shift toward preventive healthcare will drive demand for early detection and continuous monitoring devices to manage diabetes more effectively.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Diabetes
The increasing global incidence of diabetes, particularly Type 2, is fueling demand for blood glucose monitoring devices as more patients require regular monitoring to manage their condition and prevent complications.
Technological Advancements in Monitoring Devices
Innovations such as continuous glucose monitoring (CGM) systems, non-invasive meters, and smartphone integration are making glucose monitoring more accurate, convenient, and user-friendly, driving higher adoption rates.
Increasing Healthcare Awareness and Patient Empowerment
Greater awareness of diabetes management and the benefits of proactive monitoring are encouraging patients to adopt home-based and advanced monitoring solutions, supporting market growth.
Government Initiatives and Support for Diabetes Care
Policies, reimbursement programs, and public health campaigns by governments worldwide are improving access to blood glucose monitoring devices and encouraging their adoption in both clinical and home settings.
Expansion in Emerging Markets
Rising diabetes rates, improving healthcare infrastructure, and increasing disposable incomes in regions like Asia-Pacific and Latin America are creating significant new opportunities for market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the blood glucose monitoring devices market
What is driving the growth of the blood glucose monitoring devices market?
Which region leads the blood glucose monitoring devices market?
What challenges does the blood glucose monitoring devices market face?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-use
- 1.2.1 Hospitals
- 1.2.2 Home Care
- 1.2.3 Diagnostic Centers
- 1.3 By Product
- 1.3.1 Self-monitoring Devices
- 1.3.2 Continuous Blood Glucose Monitoring Devices
- 1.4 By Self-monitoring Device Type
- 1.4.1 Blood Glucose Meter
- 1.4.2 Testing Strips
- 1.4.3 Lancets
- 1.5 By Continuous Glucose Monitoring Device Type
- 1.5.1 Sensors
- 1.5.2 Transmitter & Receiver
- 1.5.3 Insulin Pumps
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 16,202.5 million → 2032: USD 36,804.43 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Blood Glucose Monitoring Devices Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Blood Glucose Monitoring Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Blood Glucose Monitoring Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Blood Glucose Monitoring Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Blood Glucose Monitoring Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Blood Glucose Monitoring Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Blood Glucose Monitoring Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Blood Glucose Monitoring Devices Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 16,202.5 million → 2032: USD 36,804.43 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Blood Glucose Monitoring Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Home Care
- 12.3.7.3 Diagnostic Centers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Self-monitoring Devices
- 12.4.7.2 Continuous Blood Glucose Monitoring Devices
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Self-monitoring Device Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Blood Glucose Meter
- 12.5.7.2 Testing Strips
- 12.5.7.3 Lancets
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Continuous Glucose Monitoring Device Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Sensors
- 12.6.7.2 Transmitter & Receiver
- 12.6.7.3 Insulin Pumps
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Blood Glucose Monitoring Devices End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Blood Glucose Monitoring Devices Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Blood Glucose Monitoring Devices Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Blood Glucose Monitoring Devices Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Abbott
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Dexcom, Inc.
- 18.4 F. Hoffmann-La Roche Ltd
- 18.5 Medtronic plc
- 18.6 Ascensia Diabetes Care Holdings AG
- 18.7 Insulet Corporation
- 18.8 Glysens Incorporated
- 18.9 Ypsomed Holdings
- 18.10 Sanofi
- 18.11 Thermo Fisher Scientific (Patheon)
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

