
Market Overview:
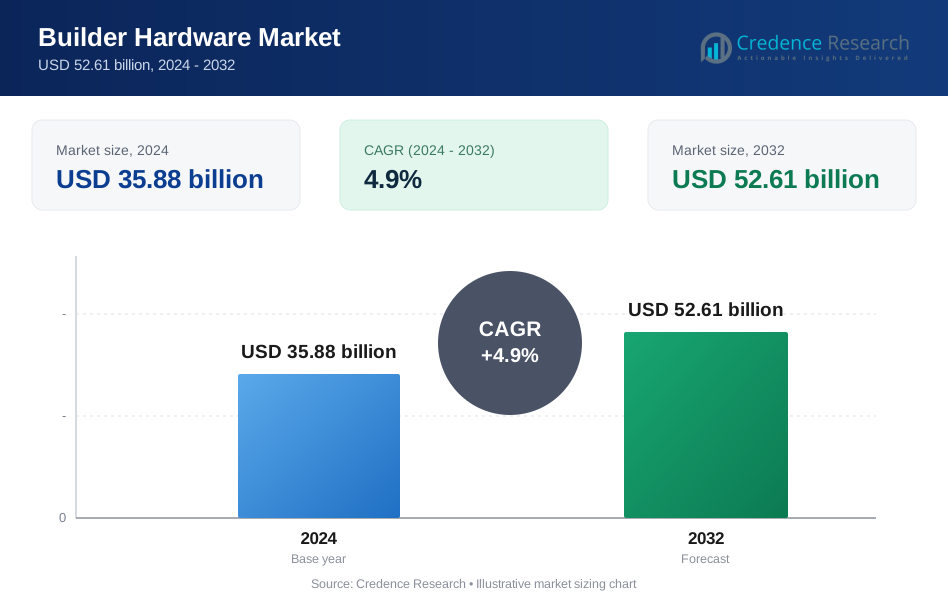
The builder hardware market size was valued at USD 35.88 billion in 2024 and is anticipated to reach USD 52.61 billion by 2032, at a CAGR of 4.9% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Builder Hardware Market Size 2024 | USD 35.88 Billion |
| Builder Hardware Market, CAGR | 4.9% |
| Builder Hardware Market Size 2032 | USD 52.61 Billion |
Growth in the builder hardware market is strongly supported by drivers such as rapid urbanization, rising disposable incomes, and expanding real estate development. Increasing emphasis on energy-efficient, durable, and aesthetic hardware products has created new opportunities for manufacturers. Furthermore, advancements in product design, integration of smart technologies, and growing renovation and remodeling activities are fueling demand across both developed and emerging economies.
Regionally, Asia-Pacific dominates the builder hardware market due to rapid urbanization, large-scale housing demand, and robust government infrastructure investments, particularly in China and India. North America and Europe remain significant markets, driven by modernization of existing buildings, smart home adoption, and stringent quality standards. Meanwhile, the Middle East, Latin America, and Africa are emerging growth regions, supported by expanding construction projects and rising focus on modern housing and commercial spaces. This diverse regional spread ensures a strong and sustained global growth outlook.
 Market Insights:
- The builder hardware market size was USD 35.88 billion in 2024 and is projected to reach USD 52.61 billion by 2032, growing at a CAGR of 4.9% during the forecast period.
- Rapid construction and infrastructure development across residential, commercial, and industrial projects continue to drive demand for doors, windows, locks, and fittings.
- Renovation and remodeling activities are boosting sales of premium, durable, and customizable hardware products in developed economies.
- Smart and energy-efficient hardware solutions, including connected locks and eco-friendly fittings, are witnessing strong consumer adoption.
- Volatility in raw material prices and supply chain disruptions remain critical challenges for manufacturers, impacting profitability and production stability.
- Asia-Pacific leads with 42% market share in 2024, driven by urbanization, housing projects, and infrastructure investments in China and India.
- North America and Europe together hold nearly half of the global market, supported by renovation demand, strict regulations, and strong adoption of sustainable and premium hardware solutions.
Market Drivers:
Rising Construction and Infrastructure Development:
The builder hardware market is fueled by rapid growth in residential, commercial, and industrial projects worldwide. Urbanization and large-scale infrastructure investments create significant demand for doors, windows, locks, and fittings. Governments and private players are heavily investing in housing, smart cities, and transportation projects. This expansion drives continuous growth in hardware consumption across multiple applications.
- For Instance, ASSA ABLOY regularly deploys its Aperio electromechanical door locks in various large-scale European projects, including university campus modernizations and smart-building upgrades. For example, a recent project involved installing over 400 Aperio online wireless locks at Luminy University in France to upgrade security.
Increasing Focus on Renovation and Remodeling :
The builder hardware market benefits from the steady rise in renovation and remodeling activities. Homeowners and commercial property owners are upgrading fixtures to improve durability, aesthetics, and energy efficiency. Demand for premium and customizable hardware is also expanding in developed economies. It creates strong opportunities for manufacturers offering innovative and design-driven solutions.
- For Instance, In 2023, the U.S. Census Bureau reported over 1.5 million residential building permits were issued.
Rising Consumer Preference for Smart and Energy-Efficient Products:
The builder hardware market is shaped by growing adoption of smart and energy-efficient hardware solutions. Consumers are choosing products that integrate with digital systems to enhance security and convenience. Energy-efficient doors, windows, and locks are gaining traction due to stricter regulations and environmental concerns. It drives manufacturers to innovate and align with sustainability trends.
Expanding Retail and Distribution Networks:
The builder hardware market gains momentum from the expansion of global retail and distribution channels. Online platforms and specialty stores provide easier access to a wide range of hardware products. Strong dealer networks and partnerships ensure timely supply for both large-scale and small-scale projects. It strengthens product reach and supports competitive growth across regions.
Market Trends:
Adoption of Smart and Sustainable Hardware Solutions:
The builder hardware market is witnessing a clear shift toward smart and sustainable solutions. Consumers prefer hardware that integrates with digital ecosystems to improve safety and convenience. Smart locks, automated door systems, and IoT-enabled products are gaining significant traction in residential and commercial spaces. Growing environmental concerns and regulatory standards are pushing demand for eco-friendly, durable, and recyclable materials. Manufacturers are focusing on energy-efficient designs that reduce long-term operational costs for property owners. It is also driving innovation in product aesthetics, with demand for modern, sleek finishes rising across urban markets.
- For instance, N-iX, with over 23 years of IoT software development experience, partners with technology leaders like Nordic Semiconductor and Microsoft to deliver robust IoT-based smart hardware solutions across multiple industries including building hardware, enhancing both user experience and operational efficiency.
Expansion of E-commerce and Customization Demand:
The builder hardware market is influenced by the rapid expansion of online platforms and evolving consumer expectations. E-commerce channels offer wider product visibility and faster delivery, which strengthens brand competition. Buyers now expect hardware products that can be tailored to individual preferences, driving growth in customizable designs and premium finishes. Manufacturers are responding by investing in advanced manufacturing techniques to meet unique size, design, and performance requirements. Strong growth in the do-it-yourself (DIY) segment further supports demand for easy-to-install and user-friendly hardware. It creates opportunities for companies to expand product ranges and strengthen customer engagement.
- For instance, ECI's Spruce eCommerce system, launched to support lumber and hardware retailers, integrates advanced inventory management and ecommerce systems, enabling retailers to manage online sales with no in-house IT expertise and process thousands of SKUs effectively, supporting faster product delivery and wider visibility.
Market Challenges Analysis:
Fluctuating Raw Material Costs and Supply Chain Disruptions:
The builder hardware market faces challenges from volatility in raw material prices, particularly steel, aluminum, and polymers. Frequent cost fluctuations strain profit margins and make pricing strategies difficult for manufacturers. Supply chain disruptions caused by geopolitical tensions, transportation delays, and trade restrictions add further pressure. It often leads to inconsistent availability of key components, affecting production timelines. Smaller players are especially vulnerable due to limited bargaining power with suppliers. Companies must adopt efficient sourcing strategies and diversify supplier networks to minimize risks.
Intense Competition and Counterfeit Product Penetration:
The builder hardware market is highly competitive, with global and regional players striving for market share. Price wars and the entry of low-cost manufacturers create downward pressure on margins. Counterfeit and substandard products also pose a significant challenge by reducing consumer trust and affecting brand reputation. It impacts sales of premium and genuine products in both offline and online channels. Rapid technological changes demand constant innovation, which increases R&D and operational costs. Firms must balance affordability with quality and innovation to sustain growth in a crowded marketplace.
Market Opportunities:
Rising Demand for Smart Homes and Sustainable Construction:
The builder hardware market holds strong opportunities in the growth of smart home adoption and sustainable building practices. Consumers seek hardware that enhances security, energy efficiency, and convenience through digital integration. Smart locks, automated doors, and eco-friendly fittings are becoming mainstream in residential and commercial spaces. Governments promoting green buildings and energy regulations create added demand for sustainable hardware solutions. It positions manufacturers to expand portfolios with recyclable and low-carbon materials. Companies focusing on innovation in both function and design are well-placed to capture this evolving demand.
Expansion in Emerging Markets and E-commerce Channels:
The builder hardware market benefits from rapid urbanization and construction growth in emerging economies across Asia-Pacific, the Middle East, and Africa. Rising disposable incomes and infrastructure investments are creating steady demand for modern hardware solutions. E-commerce platforms are opening new channels to reach wider consumer bases, especially in tier-2 and tier-3 cities. It offers opportunities for manufacturers to scale efficiently while providing affordable, customizable options. Growth in the DIY segment further supports adoption of easy-to-install products, boosting retail sales. Players leveraging online platforms and expanding regional distribution networks can secure long-term growth potential.
Market Segmentation Analysis:
By Type:
The builder hardware market is segmented into doors, windows, cabinets, locks, and others. Locks and security hardware dominate due to rising demand for safety in residential and commercial spaces. Doors and windows also contribute significantly, supported by urban housing expansion and smart building projects. It continues to see growth in cabinet hardware, driven by remodeling and interior upgrades.
- For Instance, Andersen Corporation continued to expand its product portfolio in 2020 through a brand evolution and the launch of new product extensions related to contemporary design and indoor/outdoor living.
By Material Type:
Segments include steel, aluminum, brass, plastic, and composites. Steel leads the segment due to its durability, strength, and widespread use in high-traffic applications. Aluminum is gaining ground for its lightweight and corrosion-resistant qualities, especially in modern housing. It is also supported by growth in eco-friendly and recyclable plastic materials for cost-effective solutions.
- For Instance, In 2024, ArcelorMittal reported total crude steel production of 57.9 million metric tonnes, and steel shipments of 54.3 million metric tonnes, for a diverse range of sectors, including construction.
By Application:
Applications cover residential, commercial, and industrial sectors. Residential construction dominates due to rapid urbanization and renovation projects across global markets. Commercial use is expanding with demand from office spaces, retail outlets, and hospitality projects. It is further supported by industrial applications where durable and energy-efficient fittings are required for long-term use.
Segmentations:
By Type:
- Doors
- Windows
- Cabinets
- Locks
- Others
By Material Type:
- Steel
- Aluminum
- Brass
- Plastic
- Composites
By Application:
- Residential
- Commercial
- Industrial
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
Asia-Pacific:
Asia-Pacific accounts for 42% market share in the builder hardware market in 2024. It is driven by rapid urbanization, large-scale housing demand, and infrastructure investments in China, India, and Southeast Asia. Government-backed smart city projects and rising disposable incomes continue to strengthen demand for modern fittings and energy-efficient hardware. Local manufacturers are expanding portfolios to meet cost-sensitive segments, while global players focus on premium categories. It benefits from a robust retail presence, expanding e-commerce, and growing DIY adoption in urban households. Rising focus on sustainable construction materials further enhances opportunities in this region.
North America:
North America holds 28% market share in the builder hardware market in 2024. It is supported by high spending on home renovation, remodeling, and adoption of smart home solutions. Consumers demand hardware with advanced safety, energy efficiency, and integration with digital ecosystems. Strong presence of leading manufacturers and established retail networks ensures wide product availability. It is also boosted by stringent building regulations that drive innovation in design and durability. Growth in the DIY segment and preference for premium finishes create added opportunities in this region.
Europe:
Europe accounts for 21% market share in the builder hardware market in 2024. It is influenced by strict energy regulations, rising preference for sustainable materials, and strong adoption of premium fixtures. Consumers favor eco-friendly and durable solutions that align with environmental standards. Established players dominate through innovative designs, customization, and expanding online sales. It benefits from steady demand across residential and commercial renovation projects in Germany, France, and the UK. Continuous investment in modern housing and smart building technologies sustains the region’s growth momentum.
Key Player Analysis:
- ASSA ABLOY
- Spectrum Brands (HHI)
- Allegion
- Masco Corporation
- DORMA
- Siegenia-aubi
- Roto Frank
- GretschUnitas
- Sobinco
- Roto
- Tyman Plc.
Competitive Analysis:
The builder hardware market is highly competitive with strong participation from global and regional players. Key companies include ASSA ABLOY, Spectrum Brands (HHI), Allegion, Masco Corporation, DORMA, Siegenia-aubi, and Roto Frank. These firms focus on innovation, product quality, and expanding distribution networks to maintain their market positions. It is influenced by growing demand for smart hardware, which encourages players to integrate digital and security technologies into traditional product lines. Strategic partnerships with real estate developers and investments in e-commerce platforms strengthen visibility across consumer segments. Companies are also prioritizing sustainability by introducing eco-friendly and energy-efficient materials to align with regulatory standards and customer preferences. Competitive pressure remains intense, with both established brands and local manufacturers competing on price, design, and customization. It drives continuous product development, ensuring that companies remain agile in meeting the evolving needs of residential, commercial, and industrial applications.
Recent Developments:
- In January 2025, ASSA ABLOY acquired InVue, a US-based connected asset protection and access control solutions provider.
- In Feb 2025, Allegion acquired Lemaar Pty Ltd, a manufacturer of electronic locks and access control products.
Report Coverage:
The research report offers an in-depth analysis based on Type, Material Type, Application and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- Growing urbanization will continue to drive demand for builder hardware across residential and commercial sectors.
- Rising investments in infrastructure projects will expand opportunities for hardware manufacturers globally.
- Sustainable and eco-friendly materials will gain traction as regulations push green construction practices.
- Smart hardware solutions, including connected locks and automated fittings, will see rising adoption.
- Expansion of e-commerce platforms will strengthen product accessibility and brand visibility across regions.
- DIY trends will support demand for user-friendly, easy-to-install builder hardware products.
- Premium and customizable designs will attract urban consumers seeking both functionality and aesthetics.
- Emerging economies in Asia-Pacific, the Middle East, and Africa will serve as high-growth markets.
- Stronger focus on product innovation and design efficiency will help manufacturers maintain competitiveness.
- Collaborations and partnerships with real estate developers will boost large-scale adoption of modern hardware.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Builder Hardware Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Builder Hardware Market projected to grow between 2024 and 2032?
Which Builder Hardware Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Builder Hardware Market?
Who are the leading companies in the Builder Hardware Market?
Which region commanded the largest share of the Builder Hardware Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Builder Hardware Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Builder Hardware Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 35.88 billion → 2032: USD 52.61 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Builder Hardware Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Builder Hardware Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Builder Hardware Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Builder Hardware Market Drivers
- 3.3 Builder Hardware Market Restraints & Challenges
- 3.4 Builder Hardware Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Builder Hardware Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Builder Hardware Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Builder Hardware category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Builder Hardware Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Builder Hardware Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Builder Hardware market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Builder Hardware Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Builder Hardware Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Builder Hardware Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Builder Hardware (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Builder Hardware Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Builder Hardware Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Builder Hardware Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Builder Hardware Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Builder Hardware Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Builder Hardware Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Builder Hardware Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Builder Hardware Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Builder Hardware Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
