
Market Overview:
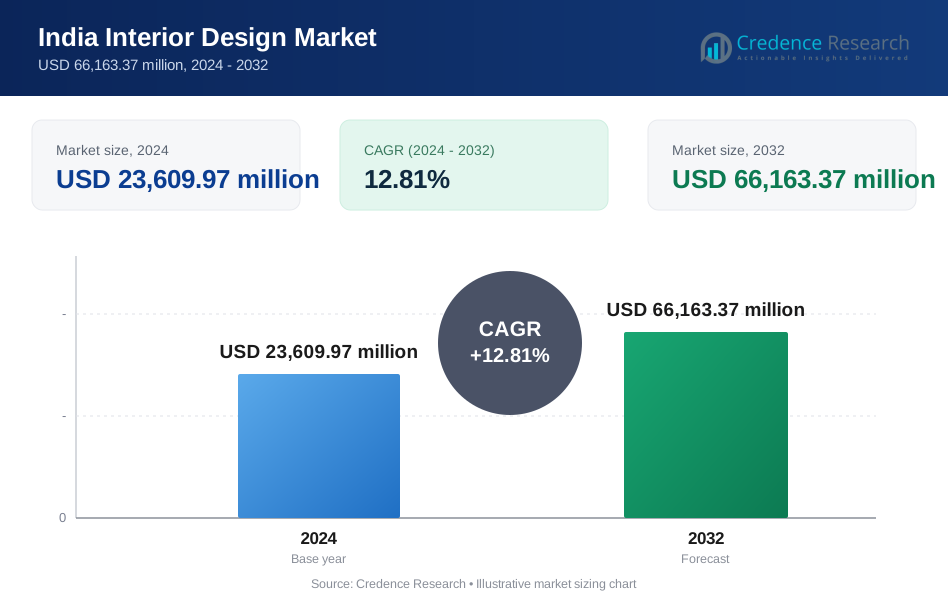
The India Interior Design Market size was valued at USD 12,130.76 million in 2018 to USD 23,609.97 million in 2024 and is anticipated to reach USD 66,163.37 million by 2032, at a CAGR of 12.81% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| India Interior Design Market Size 2024 | USD 23,609.97 million |
| India Interior Design Market, CAGR | 12.81% |
| India Interior Design Market Size 2032 | USD 66,163.37 million |
Rising urbanization drives steady demand for professional interior services across cities. Residential construction growth supports strong project pipelines for designers. Home renovation activity increases due to lifestyle upgrades and nuclear families. Commercial offices seek modern layouts to improve productivity and brand image. Retail chains invest in store aesthetics to attract footfall. Hospitality expansion boosts demand for themed interiors. Rising disposable income supports premium design adoption. Digital visualization tools improve client confidence and project conversion. Organized players gain trust through standardized delivery and design quality.
Tier I cities lead demand due to high income and dense real estate activity. Mumbai, Delhi NCR, and Bengaluru anchor premium residential projects. Corporate offices in technology hubs support commercial interior demand. Tier II cities show fast adoption due to urban migration. Cities like Pune, Ahmedabad, and Coimbatore emerge as strong markets. Southern and western regions benefit from planned housing growth. Northern markets gain from infrastructure and retail expansion. Eastern regions show gradual uptake with improving urban development.

Market Insights:
- The India Interior Design Market was valued at USD 12,130.76 million in 2018, reached USD 23,609.97 million in 2024, and is projected to hit USD 66,163.37 million by 2032, expanding at a CAGR of 12.81% during the forecast period.
- South India (30%), West India (28%), and North India (27%) dominate regional demand due to strong urban housing activity, high disposable income, and large concentrations of organized interior design players.
- East India, holding around 15% share, emerges as the fastest-growing region, supported by urban infrastructure development, rising housing construction, and increasing acceptance of professional interior services.
- By service model, Turnkey Interiors (Design + Execution) account for nearly 45% share, driven by demand for end-to-end delivery, while Modular Interiors contribute about 35% share due to faster installation and standardized quality.
- Hybrid and Project-Based Design Services together represent close to 20% share, supported by renovation projects and clients seeking partial customization with controlled budgets.
Market Drivers:
Rapid Urban Housing Development And Lifestyle-Oriented Residential Demand Expansion
Urban housing growth supports sustained demand for professional design services. Homebuyers seek functional layouts and visual appeal. Rising apartment supply creates steady interior fit-out needs. Nuclear family structures influence compact design preferences. Premium housing projects demand customized interior solutions. Developers integrate design services to improve property value. The India Interior Design Market benefits from this structural housing shift. It supports consistent project inflow across metro regions.
- For instance, Lodha Group reported over 70% of new launches as apartments below 1,200 sq. ft., pushing compact design demand.
Commercial Real Estate Growth And Corporate Workspace Modernization Needs
Corporate expansion fuels demand for modern office interiors. Firms prioritize employee comfort and space efficiency. Technology companies adopt collaborative layouts and flexible designs. Brand-focused interiors support corporate identity and culture. Office refurbishments increase with lease renewals. Co-working spaces invest in aesthetic differentiation. It drives repeat contracts for design firms. Demand remains stable across business districts.
- For instance, WeWork India expanded beyond 8 million sq. ft. across major cities, driving recurring interior refurbishment projects.
Rising Disposable Income And Consumer Spending On Home Improvement
Income growth encourages spending on home aesthetics. Middle-class households invest in personalized interiors. Renovation cycles shorten due to lifestyle upgrades. Consumers seek modular kitchens and storage systems. Design services gain preference over unorganized carpentry. Financing options ease budget constraints for households. The India Interior Design Market gains depth from this shift. It supports demand across income segments.
Hospitality And Retail Infrastructure Expansion Across Urban Centers
Hotel construction boosts demand for thematic interiors. Boutique hotels seek unique design identities. Retail chains focus on immersive store layouts. Mall expansions create demand for tenant fit-outs. Food and beverage outlets adopt branded interiors. Franchise models rely on standardized design execution. It creates recurring revenue for designers. Urban tourism growth sustains this driver.
Market Trends:
Growing Adoption Of Digital Design Visualization And Client Engagement Tools
Design firms adopt 3D visualization and virtual walkthroughs. Clients gain clarity before project execution. Digital tools reduce approval cycles and revisions. Design accuracy improves material planning. Remote consultations support wider client reach. Smaller firms adopt affordable design software. The India Interior Design Market reflects this digital shift. It improves transparency and client trust.
- For instance, Livspace uses 3D visualization tools that cut design finalization time by nearly 30%.
Rising Preference For Modular And Factory-Finished Interior Solutions
Consumers prefer modular furniture for faster installation. Factory finishes ensure consistent quality standards. Modular kitchens gain strong urban acceptance. Wardrobes and storage systems shift to modular formats. Standardized units reduce on-site labor dependency. Design firms partner with modular suppliers. It supports scalable project delivery. Cost predictability improves client confidence.
- For instance, IKEA India offers modular kitchen systems with standardized components and installation within weeks.
Increasing Focus On Sustainable And Eco-Friendly Interior Materials
Clients show interest in sustainable design concepts. Designers specify low-VOC paints and materials. Natural lighting optimization gains attention. Recycled wood and eco laminates see higher use. Green interiors align with wellness goals. Commercial projects adopt sustainability certifications. The India Interior Design Market reflects this preference shift. It supports value-based design differentiation.
Professionalization And Brand-Led Positioning Among Design Firms
Design firms invest in brand identity and portfolios. Organized players adopt standardized processes. Service quality becomes a key differentiator. Online presence influences client acquisition. Firms showcase completed projects digitally. Design consultancies expand multi-city operations. It increases market structure and visibility. Client expectations shift toward professional delivery.
Market Challenges Analysis:
High Project Cost Sensitivity And Budget Volatility Among Clients
Clients often revise budgets during execution phases. Material price fluctuations affect cost estimates. Design firms face margin pressure on fixed contracts. Value engineering impacts design scope. Price-sensitive customers delay decision cycles. Negotiations extend project timelines. The India Interior Design Market faces execution risk from this factor. It affects smaller firms more strongly.
Fragmented Market Structure And Skilled Labor Availability Constraints
Unorganized players dominate local markets. Quality inconsistency affects client perception. Skilled labor shortages impact project schedules. Training gaps limit design execution quality. Labor mobility disrupts continuity on sites. Compliance with safety standards remains uneven. It creates operational challenges for firms. Scaling operations becomes complex.

Market Opportunities:
Expansion Potential In Tier II And Tier III Urban Markets
Smaller cities witness rising real estate development. Urban migration supports housing demand growth. Consumers seek professional design support. Organized design firms enter untapped regions. Lower competition improves margin potential. Digital platforms enable remote project management. The India Interior Design Market gains expansion scope here. It supports long-term geographic diversification.
Integration Of Design Services With Real Estate And Furniture Brands
Developers bundle interior services with housing sales. Furniture brands offer end-to-end design solutions. Strategic partnerships improve client acquisition. Cross-selling increases average project value. Design firms gain stable project pipelines. Integrated offerings reduce customer effort. It strengthens ecosystem collaboration. Revenue visibility improves for organized players.
Market Segmentation Analysis:
By Service Model
Design consultancy focuses on concept planning and layout advisory. This segment suits clients who manage execution independently. Turnkey interior solutions deliver end-to-end project responsibility. Developers and homeowners prefer this model for time certainty. Modular interior solutions support faster installation and consistent quality. Urban apartments drive strong demand for modular kitchens and wardrobes. Project-based design services cater to short-term or renovation needs. The India Interior Design Market benefits from flexible service adoption across customer types.
- For instance, Asian Paints offers turnkey interior solutions covering design, materials, and execution under one contract.
By Revenue Model
Design fee-based models attract budget-conscious clients seeking professional guidance. This approach limits execution risk for firms. Design plus execution generates higher contract value per project. Clients prefer bundled pricing for cost clarity. Commission-based models link designer revenue to vendor partnerships. This model suits furniture and material-driven projects. Subscription or package-based offerings gain traction for repeat services. It supports predictable cash flow and client retention.
- For instance, Urban Company provides packaged interior services with fixed pricing, improving repeat customer retention.
By Price Positioning
Mass market interiors focus on affordability and standard layouts. This segment gains traction in mid-income housing. Mid-range interiors balance customization and cost control. Urban families drive steady demand here. Premium interiors emphasize bespoke design and high-end materials. Luxury residences and hospitality projects support this segment. Price positioning reflects lifestyle preferences and budget capacity.
By Operational Structure
Organized players offer standardized processes and warranties. Brand trust supports client acquisition at scale. Unorganized and independent designers rely on local networks. This segment competes on flexibility and personalized service. It remains prominent in smaller cities and renovation projects.
Segmentation:
By Service Model- Design Consultancy
- Turnkey Interior Solutions
- Modular Interior Solutions
- Project-Based Design Services
- Design Fee-Based
- Design + Execution
- Commission-Based
- Subscription or Package-Based
- Mass Market
- Mid-Range
- Premium
- Organized Players
- Unorganized / Independent Designers
- North India
- South India
- West India
- East India

Regional Analysis:
South India Regional Outlook
South India holds nearly 30% share of national demand. The region benefits from strong urban housing growth. Bengaluru, Hyderabad, and Chennai drive steady residential projects. Technology-sector employment supports premium interior spending. Consumers prefer turnkey and modular solutions. Organized players show strong presence across metro cities. Repeat renovation demand remains high.
West And North India Regional Outlook
West India accounts for around 28% share of the market. Mumbai and Pune lead high-value residential and office interiors. Gujarat cities support mid-range housing demand. North India contributes close to 27% share, led by Delhi NCR. Corporate offices and hospitality projects drive growth. Luxury housing supports premium design demand. Both regions show balanced adoption across price segments.
East India Regional Outlook
East India represents nearly 15% of total demand. Kolkata anchors residential and retail interior projects. Bhubaneswar and Patna show emerging activity. Budget sensitivity supports independent designers. Organized firms expand through modular formats. Urban infrastructure improves market access. Professional interior adoption continues to rise.
Key Player Analysis:
- Livspace
- HomeLane
- Bonito Designs
- Decorpot
- Pepperfry (Interiors)
- DesignCafe
- Wudzo
- Spacewood
- Godrej Interio (Residential Modular & Turnkey)
- Asian Paints
Competitive Analysis:
The India Interior Design Market shows a fragmented yet fast-organizing competitive structure. Organized players compete on brand trust, delivery timelines, and standardized execution. Digital platforms support customer acquisition and design transparency. Turnkey service providers gain share through end-to-end offerings. Modular specialists focus on speed, quality control, and scalability. Independent designers retain relevance through local presence and customization. Partnerships with developers improve project visibility. Technology adoption strengthens design accuracy and cost planning. It favors firms with strong supply chain control. Competition intensifies through pricing discipline and service differentiation.
Recent Developments:
- Nagpur-based modular furniture manufacturer Spacewood received a ₹300 crore investment from A91 Partners in November 2025 for a 25 percent stake, valuing the overall business at ₹1,200 crore. The capital infusion is intended to accelerate brand building, strengthen manufacturing capabilities, upgrade technology, automate processes, and support talent acquisition as Spacewood aims to expand its retail presence from 35 exclusive stores to over 100 stores pan-India within the next few years. The company reported revenue of ₹600 crore in FY25 and expects to reach ₹700 crore in FY26, targeting 25-30 percent annual growth while maintaining profitability. Spacewood is also eyeing a public listing within 4-5 years as part of its long-term growth strategy.
- In a significant acquisition announcement in September 2025, TCC Concept Limited, a Pune-based real estate and technology services company, signed a term sheet to acquire up to 100 percent stake in Pepperfry, India's leading omnichannel furniture and home goods marketplace. The board approval came in November 2025 for the acquisition of 98.98 percent stake valued at ₹661.47 crore, to be executed through a share-swap arrangement where TCC Concept issues approximately 1.18 crore equity shares to Pepperfry shareholders. The deal has already been completed as of mid-December 15, 2025, subject to shareholder and regulatory approvals, marking a strategic expansion of TCC Concept's presence in the e-commerce and digital marketplace space. This acquisition represents a significant chapter for Pepperfry, which was once valued at $350 million (₹3,100 crore) and had been preparing for an IPO in 2023 before facing market challenges.
- Bonito Designs, India's largest full-homes interior design brand, extended its premium partnership with iconic interior designer Gauri Khan and celebrated fashion designer Manish Malhotra in August 2023, creating an exclusive design collaboration that promises to revolutionize the world of interior design for discerning homeowners in Mumbai and Bengaluru. In July 2025, the company secured ₹81 crore (approximately $9.5 million) in fresh funding from its existing investor and holding company Tomorrow Capital, marking the company's first major funding in two years. This funding was approved in May 2025 with ₹51 crore already received and the remaining amount expected shortly. Despite the company's strong growth trajectory with operating revenue increasing 50 percent to ₹153.4 crore in FY24 from ₹104 crore in FY23, the new funding round valued Bonito Designs at ₹531 crore, an 18 percent decrease from its previous ₹650 crore valuation in 2023.
Report Coverage:
The research report offers an in-depth analysis based on service model, revenue model, price positioning, operational structure, and geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Organized interior design firms will expand their footprint through standardized delivery and brand-led models.
- Modular interior solutions will gain wider acceptance due to faster installation and quality consistency.
- Digital design visualization tools will become a core requirement across client engagement workflows.
- Tier II and Tier III cities will generate new demand as urban housing activity continues to rise.
- Real estate developer partnerships will create steady project pipelines for interior service providers.
- Brand trust and after-sales support will influence customer selection decisions more strongly.
- Sustainable materials and eco-friendly design concepts will see higher adoption across residential projects.
- Subscription and package-based service offerings will attract repeat customers seeking cost clarity.
- Supply chain integration will help firms control timelines and improve execution efficiency.
- Skilled workforce development will remain essential to support scalable growth in the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rapid Urban Housing Development and Lifestyle-Oriented Residential Demand
Accelerated urbanization and a surge in residential construction, especially in metro and Tier II/III cities, are driving demand for professional interior design services. Compact apartments and nuclear family structures are increasing the need for functional, customized, and visually appealing interiors.
Commercial Real Estate Growth and Workspace Modernization
Expansion of corporate offices, technology hubs, and co-working spaces is fueling demand for modern, collaborative, and brand-focused interior solutions. Frequent office refurbishments and lease renewals create recurring opportunities for design firms.
Rising Disposable Income and Consumer Spending on Home Improvement
Growing middle-class incomes and lifestyle aspirations are leading to increased investment in home aesthetics, modular kitchens, and personalized interiors. Shorter renovation cycles and financing options are making professional design services more accessible.
Hospitality and Retail Infrastructure Expansion
Growth in hotel construction, boutique hospitality, and organized retail chains is boosting demand for thematic and branded interiors. Mall expansions and franchise models are generating steady project pipelines for interior designers.
Digital Visualization Tools and Technology Adoption
The adoption of 3D visualization, virtual walkthroughs, and digital client engagement platforms is improving project conversion rates and client confidence. These tools streamline design approvals, reduce revisions, and enable remote consultations, supporting market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for India Interior Design Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the India Interior Design Market projected to grow between 2024 and 2032?
Which India Interior Design Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the India Interior Design Market?
Who are the leading companies in the India Interior Design Market?
Which region commanded the largest share of the India Interior Design Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Revenue Model
- 1.2.1 Design Fee-Based
- 1.2.2 Design + Execution
- 1.2.3 Commission-Based
- 1.2.4 Subscription or Package-Based
- 1.3 By Service Model
- 1.3.1 Design Consultancy
- 1.3.2 Turnkey Interior Solutions
- 1.3.3 Modular Interior Solutions
- 1.3.4 Project-Based Design Services
- 1.4 By Price Positioning
- 1.4.1 Mass Market
- 1.4.2 Mid-Range
- 1.4.3 Premium
- 1.5 By Operational Structure
- 1.5.1 Organized Players
- 1.5.2 Unorganized / Independent Designers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 23,609.97 million → 2032: USD 66,163.37 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 India Interior Design Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 India Interior Design Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 India Interior Design Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 India Interior Design Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 India Interior Design Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 India Interior Design Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 India Interior Design Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 India Interior Design Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 23,609.97 million → 2032: USD 66,163.37 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 India Interior Design Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Revenue Model - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Design Fee-Based
- 12.3.7.2 Design + Execution
- 12.3.7.3 Commission-Based
- 12.3.7.4 Subscription or Package-Based
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Service Model - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Design Consultancy
- 12.4.7.2 Turnkey Interior Solutions
- 12.4.7.3 Modular Interior Solutions
- 12.4.7.4 Project-Based Design Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Price Positioning - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Mass Market
- 12.5.7.2 Mid-Range
- 12.5.7.3 Premium
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Operational Structure - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Organized Players
- 12.6.7.2 Unorganized / Independent Designers
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 India Interior Design Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 India Interior Design Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 India Interior Design Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Livspace
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 HomeLane
- 17.4 Bonito Designs
- 17.5 Decorpot
- 17.6 Pepperfry (Interiors)
- 17.7 DesignCafe
- 17.8 Wudzo
- 17.9 Spacewood
- 17.10 Godrej Interio
- 17.11 Asian Paints
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

