
Market Overview:
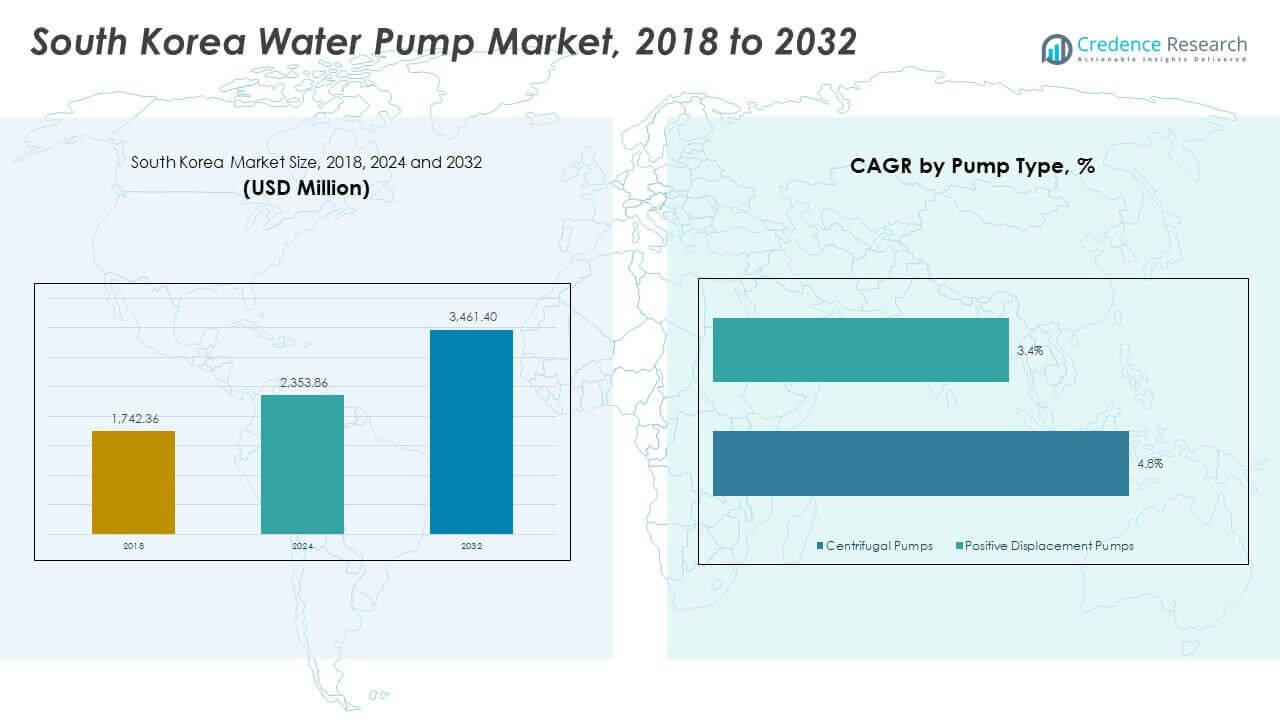
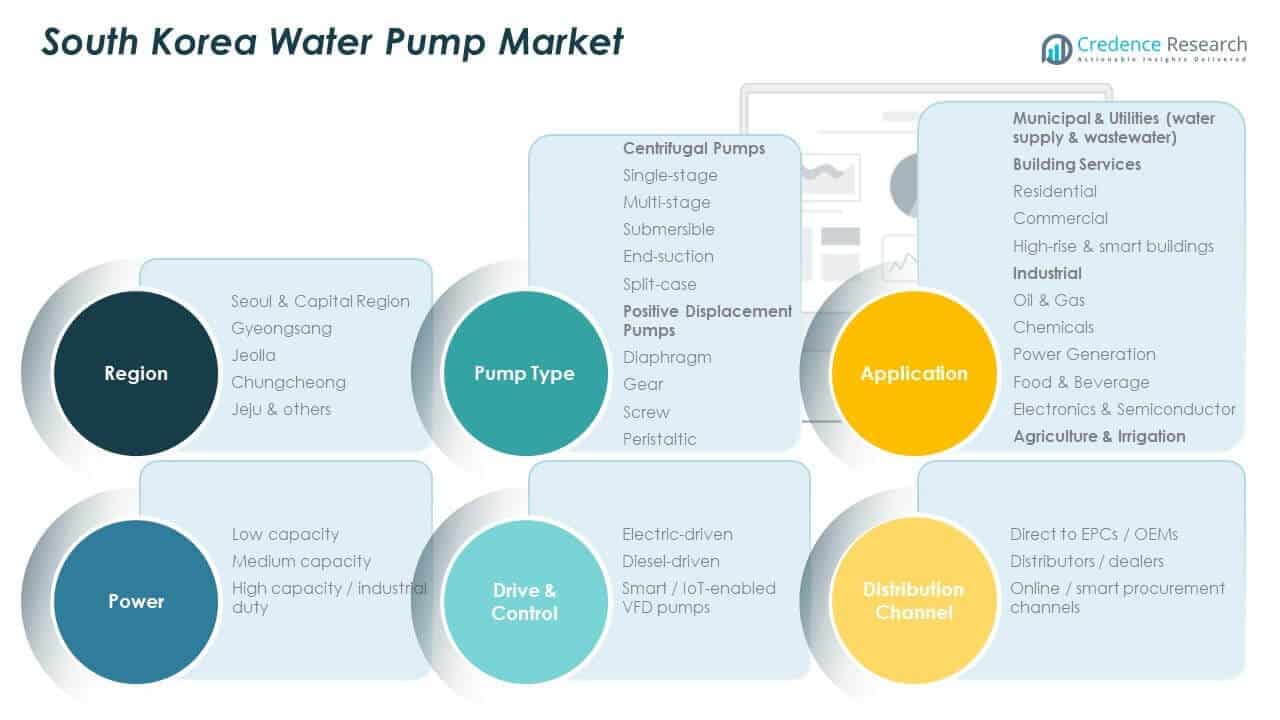
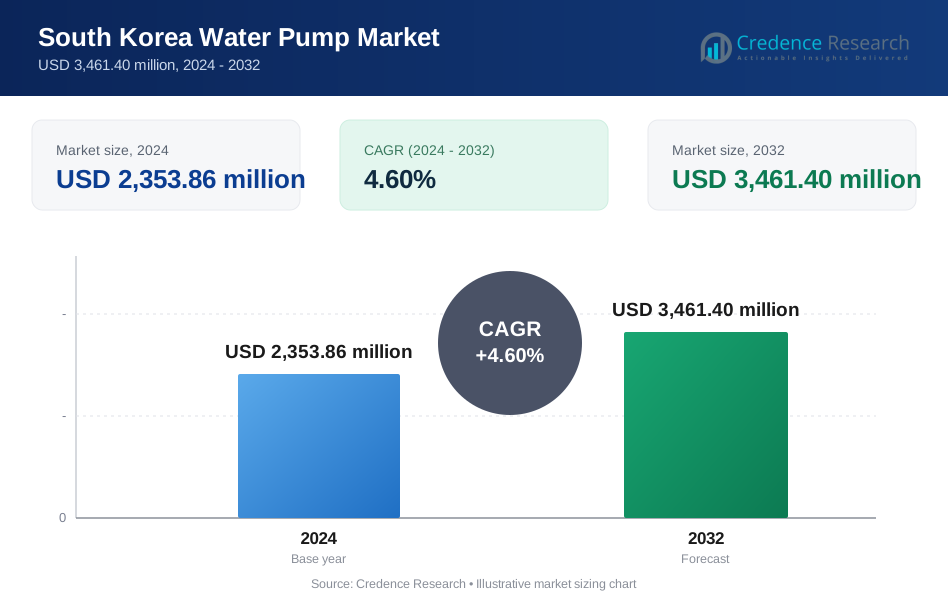
The South Korea Water Pump Market size was valued at USD 1,742.36 million in 2018 to USD 2,353.86 million in 2024 and is anticipated to reach USD 3,461.40 million by 2032, at a CAGR of 4.60% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| South Korea Water Pump Market Size 2024 | USD 2,353.86 Million |
| South Korea Water Pump Market, CAGR | 4.60% |
| South Korea Water Pump Market Size 2032 | USD 3,461.40 Million |
Strong infrastructure investments, urban development, and smart building upgrades continue to push demand across municipal, residential, and commercial sectors. Industrial sectors including power generation, chemicals, and semiconductors require specialized high-performance pumps for process cooling and water treatment. Government-backed water conservation and reuse projects also increase the use of energy-efficient and IoT-enabled pump systems. Agricultural modernization expands pump usage in rural regions, supported by subsidies and solar integration. Public utilities and private operators focus on replacing outdated systems with variable-speed and high-efficiency models. The market benefits from both new installations and recurring replacement cycles.
Seoul and the Capital Region lead the South Korea Water Pump Market, driven by high-rise infrastructure, dense urban utilities, and smart city programs. Gyeongsang and Chungcheong provinces form a strong industrial base, demanding large-scale pumps for manufacturing and wastewater use. These regions also attract foreign investment in automotive and electronics sectors. Jeolla, Jeju, and other outer provinces see growing adoption through agricultural irrigation, public infrastructure, and off-grid solutions. Grid-independent and diesel-driven pumps gain traction in rural areas, while compact electric pumps dominate urban residential applications. Each sub-region contributes to the market with sector-specific demand and regulatory focus.
Market Insights
- The South Korea Water Pump Market was valued at USD 1,742.36 million in 2018, USD 2,353.86 million in 2024, and is projected to reach USD 3,461.40 million by 2032, with a CAGR of 4.60%.
- Seoul & Capital Region held 38% of the market in 2024, followed by Gyeongsang and Chungcheong at 33%, driven by industrial hubs and smart utility projects.
- Jeolla and Jeju regions accounted for 29% share in 2024, emerging due to agriculture-driven pump deployment and grid-independent solutions.
- Centrifugal pumps accounted for nearly 67% of the total market share in 2024, with slower growth at 3.4% CAGR.
- Positive displacement pumps, though smaller in base, are growing faster at a 4.8% CAGR, contributing nearly 33% share in 2024.
Market Drivers
Urbanization, Infrastructure Modernization, and Growing Utility Water Demand Across Cities and Industrial Zones
Rapid urban growth across South Korea continues to drive water infrastructure expansion. High-rise housing and mixed-use developments increase domestic water consumption. Municipal utilities need reliable pumps for water treatment, supply, and drainage. Industrial zones in Incheon, Ulsan, and Busan adopt high-capacity systems for cooling, processing, and effluent treatment. Aging water supply lines are being replaced with pressure-stable pump networks. Residential areas now require energy-efficient booster pumps to support vertical plumbing. Smart cities promote intelligent water circulation systems. Demand for low-noise and compact units has risen in urban construction. The South Korea Water Pump Market benefits from consistent investment across these verticals.
- For instance, in 2025 the Ministry of Environment announced water-supply systems delivering 1.07 million tons/day to the Yongin Semiconductor Complex and 21,000 tons/day to the Pohang battery cluster, supported by new pumping stations and storage infrastructure upgrades.
Regulatory Push for Energy Efficiency and Integration of High-Performance Pumping Systems
South Korea’s government mandates energy-efficiency standards for water-intensive sectors. Industries are switching to inverter-based pump systems to reduce operational costs. Compliance with MEPS and IE3 motor norms boosts advanced pump replacement. Utilities prioritize high-efficiency centrifugal and submersible variants in new installations. Pressure to reduce emissions encourages variable-speed drives and solar-powered pumps. Green building certifications require optimized water systems. Pump manufacturers are redesigning models to meet smart energy codes. Efficiency metrics have become key evaluation criteria in procurement bids. These regulatory and environmental factors strongly influence demand patterns.
Expansion of Smart Manufacturing and Integration of Industrial IoT in Water Handling Applications
Industrial users deploy connected pumping systems to streamline operations. Smart factories integrate pump monitoring tools with predictive maintenance analytics. Flow meters and real-time alerts prevent downtime and ensure continuity. Water recycling units rely on multi-stage pump setups for closed-loop processing. Industry 4.0 practices promote use of AI-enabled diagnostics in large pump networks. Remote control and scheduling features reduce labor dependency. Data centers and pharma units use intelligent pumps to manage cooling loads. Integration of IIoT in water infrastructure improves asset performance. The South Korea Water Pump Market supports this digital shift with upgraded product lines.
Agri-Technology Adoption and Government Support for Rural Water Security Projects
Agricultural pump demand grows with the mechanization of farming practices. Government irrigation programs deploy electric and diesel pumps across farmlands. Subsidies support smallholder access to solar and hybrid systems. Groundwater management plans prioritize precision irrigation pumps. Crop diversification requires adaptable flow rates and suction depths. Water scarcity in drier provinces prompts use of drip-compatible pumps. Smart irrigation uses weather-linked control for pumping cycles. Efficient pumps help farmers reduce water use and electricity costs. These rural sector policies extend the market beyond cities into agrarian zones.
- For instance, in 2025 the Ministry of Environment advanced 12 groundwater reservoir dam projects and expanded desalination, including a 100,000 tons/day facility in Daesan, relying on pump systems for lifting and distributing water to industrial and drought-prone rural areas.
Market Trends
Product Innovations in Vertical Multistage, Magnetic Drive, and Solenoid-Based Pump Technologies
Manufacturers are introducing compact, noise-reducing, and corrosion-resistant pumps. Vertical multistage pumps offer consistent pressure in high-rise buildings. Magnetic drive pumps reduce leak risks and require less maintenance. Solenoid-based mini pumps are gaining traction in appliances and labs. Chemical industries prefer seal-less options for hazardous fluids. OEMs focus on material innovation using ceramics and composites. Local brands develop variants to suit cold climate operations. The South Korea Water Pump Market adopts these technologies across utilities, labs, and factories. Product upgrades align with application-specific demand.
- For instance, Grundfos' CRNE series vertical multistage pumps deliver up to 25 bar pressure with 70-72% efficiency across models like CRNE 15, handling flow rates from 18 m³/h in compact stainless steel designs suitable for high-rise buildings.
Rise in Retrofit Demand for Pump Replacements in Aging Public and Industrial Installations
A large installed base of old pumping systems is due for upgrade. Public utilities in Seoul and Daegu run water lines over 30 years old. Older centrifugal models consume more power and suffer mechanical wear. Retrofit programs aim to improve flow efficiency with new impellers and motors. Industries replace outdated units to meet noise and emission norms. Remote mountain villages update community water systems with compact units. Hospitals and schools replace low-pressure pumps to meet safety codes. It creates recurring demand for mid-range pumps with standard dimensions. The South Korea Water Pump Market sees strong momentum in this segment.
Smart Integration of Pumps with Building Automation, Water Meters, and Cloud Platforms
Buildings integrate pump systems into central control panels for better oversight. Remote alerts notify operators about leakage, failure, or performance drops. AI engines analyze flow data to adjust motor speeds dynamically. Embedded sensors allow pump fleets to be managed remotely via apps. Integration with digital water meters supports usage tracking. Cloud-based monitoring simplifies utility maintenance in commercial buildings. Facilities use pump data to optimize energy use across assets. The South Korea Water Pump Market aligns with this shift through digitized offerings. Pump OEMs bundle software dashboards with hardware sales.
- For instance, LS Electric offers IoT-enabled pump control systems with app-based monitoring and performance alerts, supporting predictive maintenance. Its smart solutions integrate temperature sensors like PT100 through motor control panels to enhance protection and efficiency.
Localized Manufacturing and Component Sourcing for Supply Chain Risk Mitigation
Manufacturers localize production to cut lead times and protect from import delays. Pump assembly units in Chungcheong and Gyeonggi reduce dependence on Chinese imports. Local foundries produce impellers and castings for domestic assembly. Korea’s FTA network supports component trade with Japan and ASEAN. Regional players compete by offering faster service and region-specific warranties. COVID-19 supply issues triggered policy shifts toward local self-sufficiency. Public projects favor suppliers with Korean-made equipment tags. The South Korea Water Pump Market benefits from this reshoring trend.
Market Challenges Analysis
Rising Energy Costs and Pressure on Pump Efficiency Across Industrial and Utility Applications
Electricity prices in South Korea have risen steadily over recent years. Industries face rising costs for running large-scale pump systems. Older models lack energy-saving features and drive up utility bills. Transitioning to variable-speed drives involves upfront capital investment. Water utilities also face budget constraints in rural installations. Grid-dependent pumps struggle during power outages in isolated areas. Energy cost volatility affects long-term planning for both public and private buyers. Balancing performance, cost, and sustainability poses a major challenge. The South Korea Water Pump Market must deliver higher efficiency without pricing out small users.
Fragmented Competitive Landscape and Challenges in Differentiation Across Mid-Market Segments
Local pump suppliers compete heavily in residential and agricultural segments. Many offer similar specifications, making product differentiation difficult. Price competition reduces margins and delays investment in R&D. Buyers often prioritize cost over long-term lifecycle value. Imported brands dominate high-end industrial applications. Certification and compliance processes slow time to market for new entrants. Building loyalty in a fragmented distribution network takes time. Regional dealers influence buyer choices through discounts and bundled services. It forces vendors in the South Korea Water Pump Market to adapt their go-to-market strategies.
Market Opportunities
Growth in Desalination, Water Reuse, and Greywater Recovery Projects Supporting Long-Term Pump Demand
Government initiatives to manage water stress promote treatment infrastructure. Desalination plants along the southern coast use multistage pumping for brine and fresh water flows. Greywater reuse in buildings drives demand for compact booster pumps. Industrial water recycling plants require rugged, continuous-duty pump systems. Environmental policies back reuse strategies with funding and pilot programs. It creates new avenues for specialized pump variants in treatment chains. The South Korea Water Pump Market aligns with this shift toward circular water use.
Expansion of Data Centers, Semiconductor Clusters, and Biomedical Zones Driving Specialized Pump Adoption
South Korea’s hyperscale data centers need chilled water pumps for liquid cooling. Semiconductor plants require ultrapure water systems with high-precision pumps. Biomedical parks integrate low-vibration units for lab-grade flow control. Cleanroom facilities rely on chemical dosing and vacuum-assisted pumps. The convergence of tech, pharma, and data creates demand for niche applications. OEMs developing vertical-specific solutions can gain premium market positions. It presents a long-term growth path within the South Korea Water Pump Market.
Market Segmentation Analysis
By Pump Type
The South Korea Water Pump Market includes centrifugal and positive displacement pumps. Centrifugal variants dominate utility and building services due to efficient flow handling. Sub-segments such as submersible and split-case pumps serve wastewater and industrial cooling needs. Positive displacement pumps-gear, diaphragm, screw, and peristaltic-find use in food, pharma, and chemical dosing applications. Diaphragm pumps are preferred for hazardous and viscous fluids, while screw types support agricultural irrigation.
- For instance, Iwaki’s MD series magnetic drive pumps are used in semiconductor chemical dosing, offering zero-leakage operation and long service life, with models rated around 0.75 kW for handling corrosive and viscous fluids.
By Application
It supports diverse use cases including municipal utilities, building services, industrial processes, and agriculture. Water supply and wastewater management drive high-volume demand in public infrastructure. Residential and commercial buildings use booster and circulation pumps. Industrial demand is high in oil & gas, semiconductors, and power generation. The agriculture sector deploys pumps for irrigation and water reuse systems, particularly in rural and semi-urban zones.
- For instance, South Korea data centers consumed 74.40 billion liters of water in 2025 for cooling operations, supported by high-capacity circulation pumps to manage thermal loads efficiently.
By Power
Low-capacity pumps are dominant in domestic and light-commercial buildings. Medium-capacity pumps serve mid-size industries, institutional buildings, and greenhouses. High-capacity and industrial-duty units are deployed in heavy processing industries, power plants, and regional water treatment plants where durability and volume handling are critical.
By Drive & Control
Electric-driven pumps are the most widely deployed due to stable power availability. Diesel-driven systems are used in off-grid and emergency applications. Smart/IoT-enabled VFD pumps are gaining traction across smart cities, enabling better energy control, diagnostics, and automation.
By Distribution Channel
Distribution is led by EPCs and OEMs in infrastructure and industrial sectors. Dealers and distributors support mid-tier and agricultural sales. Online procurement platforms are emerging for small and medium buyers seeking faster replacement and price comparison.
Segmentation
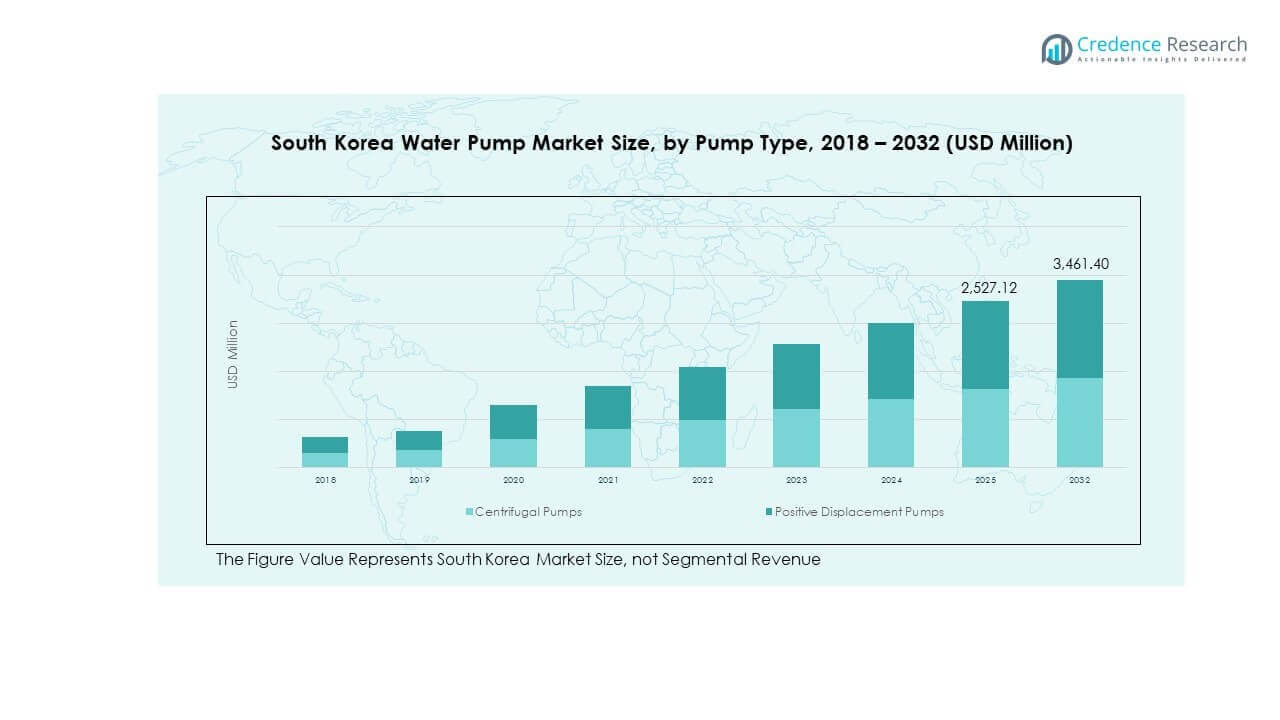
By Pump Type
- Centrifugal Pumps
- Single-stage
- Multi-stage
- Submersible
- End-suction
- Split-case
- Positive Displacement Pumps
- Diaphragm
- Gear
- Screw
- Peristaltic
By Application
- Municipal & Utilities (Water Supply & Wastewater)
- Building Services (Residential, Commercial, High-rise & Smart Buildings)
- Industrial (Oil & Gas, Chemicals, Power Generation, Food & Beverage, Electronics & Semiconductor)
- Agriculture & Irrigation
By Power
- Low Capacity
- Medium Capacity
- High Capacity / Industrial Duty
By Drive & Control
- Electric-driven
- Diesel-driven
- Smart / IoT-enabled VFD Pumps
By Distribution Channel
- Direct to EPCs / OEMs
- Distributors / Dealers
- Online / Smart Procurement Channels
By Region
- Seoul & Capital Region
- Gyeongsang
- Jeolla
- Chungcheong
- Jeju & Others
Regional Analysis
Seoul & Capital Region – 38% Market Share
The Seoul and Capital Region dominates the South Korea Water Pump Market with a 38% revenue share. Urban infrastructure, smart building developments, and dense residential zones drive pump demand. The region also houses major industrial parks and government-backed smart city projects. Public utilities invest in advanced water circulation, pressure boosting, and drainage systems. Retrofit activity in aging pipelines supports recurring replacement demand. Commercial buildings and data centers adopt high-efficiency and IoT-integrated pumps to meet sustainability targets. It remains the country’s primary consumption and procurement hub.
Gyeongsang and Chungcheong – 33% Market Share Combined
Gyeongsang and Chungcheong provinces collectively account for 33% of the South Korea Water Pump Market. These regions feature large-scale manufacturing facilities in electronics, automotive, and semiconductors. Industrial pumps with high capacity and durability are widely used in process cooling and wastewater treatment. Cities like Ulsan, Daegu, and Daejeon serve as industrial corridors with constant demand for high-duty pumping systems. Municipal infrastructure upgrades and regional water reuse projects expand pump installations. Medium-capacity and customized pumps see strong uptake in industrial estates and mid-size buildings across both provinces.
Jeolla, Jeju & Others – 29% Market Share Combined
Jeolla, Jeju, and other outlying regions contribute 29% of the market share. These areas focus on agricultural irrigation, rural water supply, and distributed wastewater systems. The South Korea Water Pump Market here is driven by farming communities, eco-tourism infrastructure, and public sector procurement. Government support for irrigation efficiency and renewable-powered pumping boosts adoption in agricultural districts. Small cities and islands invest in compact, solar-compatible, and diesel-driven pumps due to grid limitations. Product durability and ease of maintenance are key purchase factors across these regions.
Key Player Analysis
Competitive Analysis
The South Korea Water Pump Market features a mix of global and regional manufacturers competing across industrial, utility, and residential segments. Grundfos, Wilo, and Xylem lead in energy-efficient and smart pump systems, serving urban infrastructure and commercial facilities. KSB and Ebara focus on industrial, chemical, and power applications, offering high-capacity and corrosion-resistant pumps. Korean firms compete aggressively in low and medium-capacity segments with localized production and price flexibility. OEMs partner with EPCs to secure public contracts and smart city tenders. Global players offer integrated IoT platforms and modular systems, while local firms prioritize service, customization, and availability. It remains a price-sensitive yet innovation-driven market where efficiency and compliance shape vendor preference. Distribution networks, aftersales service, and warranty terms strongly influence customer loyalty and repeat business. Strategic collaborations and product localization drive differentiation in this fragmented landscape.
Recent Developments
- In January 2026, GMB Korea secured a supply contract with Hyundai Motor Group for electric water pumps used in cooling systems for hydrogen vehicles. This collaboration strengthens the company’s presence in high‑performance pump applications linked to advanced automotive technologies and signals increased demand for electric pumping solutions in South Korea’s evolving industrial landscape.
- In August 2025, Grundfos established a groundwater pump assembly plant in South Korea in collaboration with local partner Bando Submersible Pump. The new facility aims to enhance production capacity for pumps tailored to regional water management needs and support faster delivery and service in the South Korean market.
Report Coverage
The research report offers an in-depth analysis based on Pump Type, Application, Power, Drive & Control and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Smart water pumps with IoT and VFD integration will become standard in commercial and municipal segments.
- Retrofit and replacement demand will grow due to aging infrastructure across urban and industrial zones.
- Agricultural modernization programs will drive rural demand for energy-efficient and solar-powered pumps.
- Data centers and semiconductor facilities will push adoption of high-precision, low-vibration pumping systems.
- New building codes and LEED standards will favor low-noise, high-efficiency pump installations in metros.
- Price-competitive local manufacturers will expand in residential and medium-duty applications.
- Growth in desalination and water reuse facilities will support demand for corrosion-resistant multistage pumps.
- Digital procurement channels will gain traction among small and mid-sized buyers seeking fast delivery.
- Public utility investments in water security and pressure stabilization will favor advanced control systems.
- The South Korea Water Pump Market will see steady growth across segments driven by sustainability, efficiency, and compliance.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Urbanization and Infrastructure Modernization
Rapid urban growth and ongoing infrastructure upgrades in South Korea are driving demand for water pumps in municipal, residential, and commercial sectors. High-rise developments and smart city projects require advanced, energy-efficient pump systems for water supply, drainage, and pressure boosting.
Industrial Expansion and Smart Manufacturing
Growth in power generation, chemicals, semiconductors, and data centers is increasing the need for specialized, high-performance pumps. The integration of Industrial IoT and smart monitoring in factories and utilities is boosting adoption of intelligent, connected pump solutions.
Government Policies for Energy Efficiency and Water Security
Regulatory mandates for energy-efficient equipment and government-backed water conservation projects are accelerating the replacement of outdated pumps with high-efficiency, inverter-based, and solar-powered models. Public investments in water reuse, desalination, and rural irrigation further support market growth.
Agricultural Modernization and Rural Water Projects
Mechanization of agriculture and government subsidies for irrigation and solar-powered pumps are expanding pump usage in rural and semi-urban regions. Precision irrigation and groundwater management initiatives are increasing demand for adaptable and efficient pump systems.
Retrofit and Replacement Demand in Aging Installations
A large installed base of aging pump systems in public utilities, industrial facilities, and buildings is generating recurring demand for retrofits and replacements. Upgrading to modern, low-noise, and high-efficiency pumps is essential to meet new regulatory, safety, and sustainability standards.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for South Korea Water Pump Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the South Korea Water Pump Market projected to grow between 2024 and 2032?
Which South Korea Water Pump Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the South Korea Water Pump Market?
Who are the leading companies in the South Korea Water Pump Market?
Which region commanded the largest share of the South Korea Water Pump Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Pump Type
- 1.2.1 Centrifugal Pumps
- 1.2.2 Single-stage
- 1.2.3 Multi-stage
- 1.2.4 Submersible
- 1.2.5 End-suction
- 1.2.6 Split-case
- 1.2.7 Positive Displacement Pumps
- 1.2.8 Diaphragm
- 1.2.9 Gear
- 1.2.10 Screw
- 1.2.11 Peristaltic
- 1.3 By Application
- 1.3.1 Municipal & Utilities (Water Supply & Wastewater)
- 1.3.2 Building Services (Residential, Commercial, High-rise & Smart Buildings)
- 1.3.3 Industrial (Oil & Gas, Chemicals, Power Generation, Food & Beverage, Electronics & Semiconductor)
- 1.3.4 Agriculture & Irrigation
- 1.4 By Drive & Control
- 1.4.1 Electric-driven
- 1.4.2 Diesel-driven
- 1.4.3 Smart / IoT-enabled VFD Pumps
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,353.86 million → 2032: USD 3,461.40 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 South Korea Water Pump Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 South Korea Water Pump Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 South Korea Water Pump Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 South Korea Water Pump Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 South Korea Water Pump Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 South Korea Water Pump Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 South Korea Water Pump Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 South Korea Water Pump Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,353.86 million → 2032: USD 3,461.40 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 South Korea Water Pump Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Pump Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Centrifugal Pumps
- 12.3.7.2 Single-stage
- 12.3.7.3 Multi-stage
- 12.3.7.4 Submersible
- 12.3.7.5 End-suction
- 12.3.7.6 Split-case
- 12.3.7.7 Positive Displacement Pumps
- 12.3.7.8 Diaphragm
- 12.3.7.9 Gear
- 12.3.7.10 Screw
- 12.3.7.11 Peristaltic
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Municipal & Utilities (Water Supply & Wastewater)
- 12.4.7.2 Building Services (Residential, Commercial, High-rise & Smart Buildings)
- 12.4.7.3 Industrial (Oil & Gas, Chemicals, Power Generation, Food & Beverage, Electronics & Semiconductor)
- 12.4.7.4 Agriculture & Irrigation
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Drive & Control - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Electric-driven
- 12.5.7.2 Diesel-driven
- 12.5.7.3 Smart / IoT-enabled VFD Pumps
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 South Korea Water Pump End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 South Korea Water Pump Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 South Korea Water Pump Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 South Korea Water Pump Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Grundfos
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Wilo
- 18.4 Xylem
- 18.5 KSB
- 18.6 Ebara
- 18.7 GMB Korea
- 18.8 Bando Submersible Pump
- 18.9 LS Electric
- 18.10 Iwaki
- 18.11 Hyosung Goodsprings
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

