
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Business Process Outsourcing (BPO) Market Size 2024 | USD 316,894.35 million |
| Business Process Outsourcing (BPO) Market, CAGR | 9.8% |
| Business Process Outsourcing (BPO) Market Size 2032 | USD 669,473.2 million |
Market Overview:
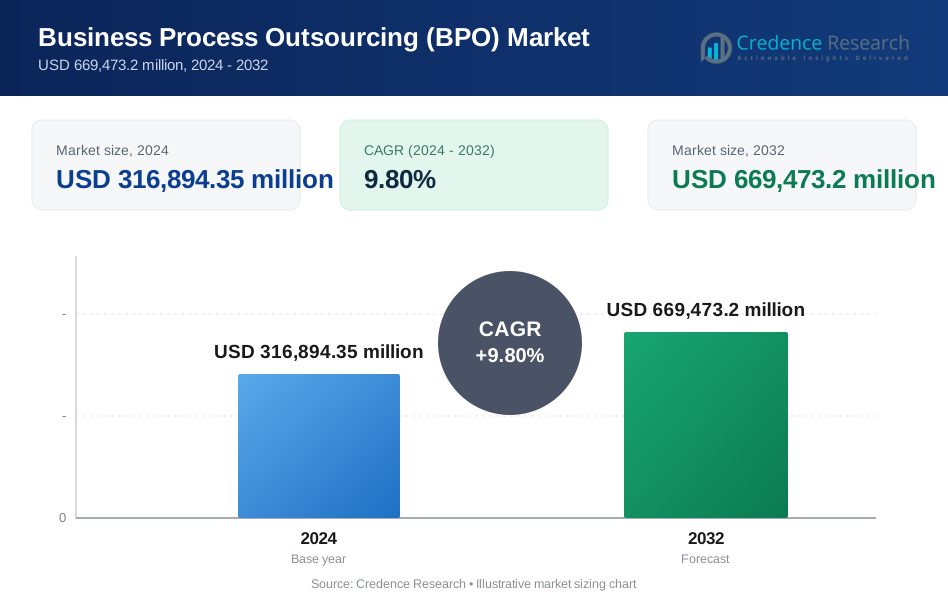
The Business Process Outsourcing (BPO) market is projected to grow from USD 316,894.35 million in 2024 to USD 669,473.2 million by 2032, registering a compound annual growth rate (CAGR) of 9.8%.
The Business Process Outsourcing (BPO) market is experiencing significant growth driven by increasing demand for cost efficiency, enhanced operational flexibility, and access to a global talent pool. Companies are increasingly outsourcing non-core functions such as customer service, IT services, and finance to focus on core competencies and improve productivity. The rise of digital transformation, automation, and artificial intelligence is further reshaping the BPO landscape, enabling faster turnaround times and improved service quality. Additionally, the growing adoption of cloud-based solutions supports scalability and remote service delivery, catering to the needs of a globally distributed workforce. Emerging markets in Asia-Pacific and Latin America are attracting BPO investments due to their skilled labor force and favorable economic conditions. The trend toward strategic partnerships, rather than traditional vendor-client relationships, is also gaining traction, with providers offering value-added services and innovation-led solutions. These factors collectively contribute to the robust expansion of the BPO market, positioning it as a critical component of modern business strategy.
The Business Process Outsourcing (BPO) market shows diverse growth across key regions, with North America leading at 35% market share in 2024, driven by technological advancements and high demand for outsourcing services. Asia-Pacific follows closely with a 30% share, benefiting from cost-effective labor and skilled workforces in countries like India and the Philippines. Europe holds 20% of the market, with strong growth in nearshore outsourcing, particularly in Eastern Europe. Latin America captures 10% of the market, with countries like Mexico and Brazil serving as key nearshore hubs. The Middle East & Africa accounts for 5%, with emerging BPO destinations like South Africa and the UAE gaining traction. Leading players such as Accenture, Amdocs, Infosys, HCL Technologies, and Wipro dominate across these regions, offering a broad spectrum of services tailored to local and global needs.
Market Insights:
- The Business Process Outsourcing (BPO) market is expected to grow from USD 316,894 million in 2024 to USD 669,473 million by 2032, with a CAGR of 9.8%.
- Companies are increasingly outsourcing non-core functions like customer service, IT services, and finance, allowing them to focus on core activities and improve productivity.
- Technological advancements in AI, robotic process automation (RPA), and cloud computing are transforming the BPO landscape, driving higher efficiency and value-added services.
- BPO services are in demand for their ability to offer cost efficiency, access to skilled talent, and greater business agility, with reduced risks associated with compliance and security.
- Data security and regulatory compliance have become critical concerns, with BPO providers focusing on advanced security frameworks and adhering to stringent data protection regulations like GDPR and CCPA.
- Asia-Pacific leads the global BPO market with a 30% share, driven by cost-effective labor and skilled talent in countries like India, the Philippines, and China.
- North America holds the largest market share at 35%, with strong demand for outsourcing in customer service, IT support, finance, and digital transformation services.
Market Drivers:
Cost Efficiency and Focus on Core Competencies:
One of the primary drivers of the Business Process Outsourcing (BPO) market is the persistent need for cost reduction. Organizations across various sectors are leveraging BPO services to minimize operational expenses associated with in-house staffing, infrastructure, and technology. Outsourcing allows businesses to convert fixed costs into variable costs, creating a more agile financial model. For instance, in November 2023, Vodafone partnered with Accenture to streamline and commercialize its shared operations, leveraging Accenture’s expertise to optimize costs and improve service delivery across multiple markets. At the same time, it enables companies to redirect their internal resources toward strategic and revenue-generating activities, enhancing overall productivity and competitiveness.
Access to Skilled Talent and Global Workforce:
The global nature of BPO provides companies with access to a vast and diverse talent pool that may not be readily available in their local markets. This access to specialized expertise in areas such as customer service, IT support, finance, and human resources enables organizations to maintain high service standards without investing heavily in recruitment and training. As the demand for multilingual support and domain-specific skills grows, BPO providers continue to offer a competitive advantage through talent scalability and flexibility.
Technological Advancements and Digital Transformation:
The integration of advanced technologies such as artificial intelligence (AI), robotic process automation (RPA), and cloud computing has significantly transformed the BPO landscape. These innovations enhance service delivery by improving accuracy, speed, and efficiency while reducing dependency on manual processes. For instance, Health Fidelity, a U.S. healthcare company, utilized UiPath’s RPA platform to extract over 1.2 million medical records in a HIPAA-compliant manner, overcoming workflow bottlenecks, enhancing security, and reducing operational costs. The adoption of digital tools also supports real-time analytics and data-driven decision-making, enabling BPO providers to deliver more value-added services. This trend aligns with the digital transformation goals of client organizations seeking to modernize their operations.
Growing Demand for Business Agility and Risk Mitigation:
In an increasingly dynamic and uncertain business environment, companies seek agility to respond quickly to market changes. BPO services offer scalable solutions that allow businesses to adjust their operations without incurring long-term commitments or overhead. Additionally, outsourcing helps mitigate risks related to compliance, security, and continuity by leveraging the expertise and infrastructure of established BPO partners. This strategic approach ensures operational resilience and supports sustainable growth.
Market Trends:
Adoption of Automation and Artificial Intelligence:
The Business Process Outsourcing (BPO) market is witnessing a strong shift toward automation and the integration of artificial intelligence (AI) to streamline operations. These technologies are being deployed to handle repetitive tasks such as data entry, transaction processing, and customer support through chatbots and virtual assistants. By reducing manual intervention, BPO providers are improving accuracy, reducing turnaround times, and lowering operational costs. This automation-driven transformation is also enabling predictive analytics and proactive service delivery, adding strategic value to client organizations.
Expansion of Cloud-Based Service Models:
Cloud computing continues to play a pivotal role in reshaping BPO services, offering scalable, secure, and cost-effective infrastructure. Cloud-based platforms facilitate real-time collaboration, seamless data sharing, and remote service delivery. This trend supports a distributed workforce and ensures business continuity across geographies. For instance, Reitmans Limited, a Canadian specialty retailer, migrated its data management and applications to the cloud using Informatica, which enabled seamless buyer journeys, real-time order tracking, and increased ecommerce revenues. As demand for agile and on-demand solutions grows, cloud integration is becoming a standard offering among BPO providers, helping clients rapidly adapt to evolving business needs.
Emphasis on Customer Experience and Personalization:
Delivering superior customer experience has become a key differentiator in the BPO industry. Service providers are increasingly focusing on personalized customer interactions by leveraging customer data and advanced analytics. This customer-centric approach allows for tailored solutions that enhance satisfaction and loyalty. In sectors like retail, finance, and healthcare, BPO partners are aligning their services with the end-user journey, emphasizing quality, responsiveness, and emotional intelligence in communication.
Rise of Nearshoring and Multilingual Support:
As global businesses seek to optimize service quality and reduce time zone challenges, there is a growing trend toward nearshoring—outsourcing to nearby countries with cultural and linguistic compatibility. For example, a leading U.S. healthcare provider facing staffing shortages and language barriers in offshore locations leveraged Auxis’ nearshore platform in Costa Rica. Additionally, the demand for multilingual support continues to rise, especially in regions with diverse consumer bases. BPO providers are expanding their global footprint and workforce capabilities to meet these evolving client expectations.
Market Challenges Analysis:
Data Security and Regulatory Compliance:
Data security and regulatory compliance present significant challenges in the Business Process Outsourcing (BPO) market. As BPO providers manage vast volumes of sensitive information on behalf of clients—ranging from personal identification and financial data to healthcare records—they are prime targets for cyber threats. Increasing incidents of data breaches and ransomware attacks have heightened the need for advanced security frameworks. Additionally, global regulatory environments are becoming more stringent, with governments enforcing rigorous data protection laws such as the EU's General Data Protection Regulation (GDPR), the California Consumer Privacy Act (CCPA), and various other regional mandates. BPO providers must therefore navigate complex legal landscapes to ensure compliance across jurisdictions. This requires significant investment in cybersecurity infrastructure, regular audits, and employee training on data handling practices. For instance, CNA Insurance, one of the largest U.S. insurers, suffered a ransomware attack that encrypted data on 15,000 devices and exposed the personal information of 75,000 employees, ultimately resulting in a $40 million ransom payment—demonstrating the high stakes for data security in outsourced operations. Failure to adhere to these regulations can result in heavy fines, litigation, and damage to client relationships. As such, regulatory compliance has become both a strategic priority and a competitive differentiator in the BPO industry.
Talent Management and Workforce Challenges:
Talent management is a persistent and evolving challenge in the BPO industry, particularly due to its labor-intensive nature. High employee attrition rates, especially in customer service and back-office roles, lead to constant recruitment cycles, increased costs, and decreased productivity. Furthermore, the dynamic nature of client requirements demands a workforce that is not only skilled but also adaptable to new technologies and business models. The rise of automation, artificial intelligence, and digital platforms has created a pressing need for upskilling and reskilling employees to remain relevant and efficient. Managing remote or hybrid teams has added complexity, with issues around employee engagement, performance tracking, and data confidentiality becoming more pronounced. Additionally, cultural differences, language barriers, and time zone variations impact communication and service quality, especially in offshore models. To address these issues, BPO providers must implement robust human resource strategies, foster inclusive workplace cultures, and prioritize continuous professional development to maintain workforce effectiveness and client satisfaction.
Market Opportunities:
The Business Process Outsourcing (BPO) market presents substantial growth opportunities driven by the increasing adoption of digital transformation across industries. As companies seek to streamline operations and reduce costs, there is a rising demand for value-added BPO services that go beyond traditional outsourcing. This includes knowledge process outsourcing (KPO), legal process outsourcing (LPO), and analytics-driven solutions that offer strategic insights. The integration of artificial intelligence, robotic process automation, and machine learning within BPO operations opens avenues for innovation and efficiency. These technologies enable providers to deliver more intelligent, responsive, and scalable solutions, thereby attracting clients from high-growth sectors such as healthcare, finance, e-commerce, and technology. Moreover, the widespread shift to remote work models has made cloud-based and virtual BPO services more attractive, especially for small and mid-sized enterprises seeking flexible and scalable outsourcing options.
Emerging markets also offer untapped potential for BPO expansion. Regions such as Southeast Asia, Eastern Europe, and Latin America are becoming increasingly favorable for BPO investments due to their growing skilled labor force, cost advantages, and improving digital infrastructure. These locations are strategically positioned to support multilingual and nearshore outsourcing services, which are gaining importance among companies seeking better time zone alignment and cultural compatibility. Additionally, governments in these regions are actively supporting the BPO industry through favorable policies, tax incentives, and investment in education and technology. As client expectations evolve, there is also an opportunity for BPO firms to offer more personalized, end-to-end customer experience solutions that integrate digital channels, data analytics, and human-centric service. Providers that can align with these evolving needs and offer innovative, tech-enabled, and customer-focused solutions are well-positioned to capture a larger share of the growing global BPO market.
Market Segmentation Analysis:
By Service
The BPO market is segmented by services such as finance and accounting, human resources, knowledge process outsourcing (KPO), procurement and supply chain, and customer services. Customer services and finance and accounting lead the segment due to their widespread adoption, while KPO is gaining traction for its value-added, expertise-driven offerings.
By End-User
Key end-user industries driving BPO demand include banking, financial services and insurance (BFSI), healthcare, manufacturing, IT and telecommunications, and retail. BFSI and IT sectors dominate due to their high-volume, process-intensive operations, while healthcare and retail are witnessing growing demand for tailored, customer-centric outsourcing solutions to enhance efficiency and service delivery.
By Outsourcing Type
The BPO market is categorized into onshore, nearshore, and offshore outsourcing. Offshore outsourcing remains the most prevalent due to cost efficiency and scalability, particularly in regions like Asia-Pacific. However, nearshore models are gaining popularity for their cultural alignment and time zone advantages, improving communication and operational responsiveness.
Segments:
Based on Service
- Finance and Accounting
- Human Resources
- KPO
- Procurement and Supply Chain
- Customer Services
Based on End-User
- Banking and Financial Services and Insurance (BFSI)
- Healthcare
- Manufacturing
- IT and Telecommunications
- Retail
Based on Outsourcing Type
- Onshore
- Nearshore
- Offshore
Based on Deployment
- On premise
- Cloud
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a significant share in the global Business Process Outsourcing (BPO) market, accounting for the largest regional market share at 35% in 2024. The region's dominance is driven by the presence of established enterprises, widespread adoption of advanced technologies, and a strong focus on optimizing operational efficiency. The United States plays a pivotal role in this market, with high demand for outsourcing in customer service, IT support, and finance. Additionally, businesses in North America increasingly leverage BPO providers for digital transformation and strategic consulting services. The maturity of the outsourcing ecosystem and high awareness of process automation further support regional growth.
Asia-Pacific
Asia-Pacific holds the second-largest share in the BPO market, capturing 30% of the global market in 2024. This growth is largely fueled by countries such as India, the Philippines, and China, which offer a large pool of skilled labor, cost-effective services, and robust technological infrastructure. India continues to be a global hub for IT and customer service outsourcing, while the Philippines has carved a niche in voice-based services. Governments in the region are supporting the sector through favorable policies, infrastructure development, and education initiatives. The combination of language proficiency, cultural adaptability, and scalability makes Asia-Pacific a preferred destination for offshore outsourcing.
Europe
Europe accounted for 20% of the BPO market in 2024, driven by the increasing need for cost reduction and process efficiency among enterprises. The region has shown steady growth in nearshore outsourcing, particularly in Eastern European countries such as Poland, Romania, and Hungary, where companies benefit from geographic proximity and multilingual capabilities. The demand for knowledge-intensive services and data protection compliance, such as GDPR, has led to the rise of high-value BPO offerings in finance, legal, and healthcare sectors.
Latin America and Middle East & Africa (MEA)
Latin America contributed 10% to the global BPO market in 2024. Countries such as Mexico, Brazil, and Colombia are emerging as attractive nearshore destinations, especially for North American companies seeking time zone alignment and cultural similarities. The region is experiencing growth in multilingual support services and customer experience management. The Middle East & Africa region held a 5% share in 2024, with increasing investments in BPO hubs like South Africa and the UAE. These regions are gradually developing outsourcing capabilities in IT, telecom, and finance, supported by government initiatives and digital infrastructure improvements.
Key Player Analysis:
- Capgemini
- CBRE Group Inc.
- NCR Corporation
- Accenture
- TTEC Holdings, Inc.
- Wipro Limited
- Infosys Limited
- Amdocs
- HCL Technologies Limited
- Sodexo
Competitive Analysis:
The Business Process Outsourcing (BPO) market is highly competitive, with leading players such as Accenture, Amdocs, Infosys Limited, HCL Technologies Limited, CBRE Group Inc., Wipro Limited, Capgemini, TTEC Holdings, Inc., NCR Corporation, and Sodexo dominating the landscape. These companies maintain a strong market presence through their comprehensive service portfolios, technological advancements, and global reach. Accenture, Capgemini, and Infosys leverage their expertise in IT and consulting services, integrating automation and AI to deliver cutting-edge solutions. In contrast, Wipro and HCL focus on delivering specialized services across IT, customer support, and finance. Companies like Amdocs and TTEC are focusing on customer experience management, while CBRE Group Inc. and NCR Corporation cater to industry-specific needs in real estate and technology solutions. Sodexo stands out by offering a combination of food services and facilities management, positioning itself uniquely in the BPO sector. As these companies continue to innovate and expand globally, they drive competitive differentiation in a rapidly evolving market.
Recent Developments:
- In November 2023, a new TTEC customer experience delivery center opened in Cape Town, South Africa, offering business process outsourcing services to a diverse customer base across industries such as automotive, healthcare, telecoms, and manufacturing. The center, with the capacity to accommodate several hundred employees, is strategically positioned to meet growing demand from various parts of the world.
- In June 2023, TTEC announced the integration of Conversational AI into its BPO services. This cutting-edge technology, utilizing machine learning algorithms and natural language processing, enables more human-like interactions with consumers, enhancing the overall customer experience.
- Delta BPO Solutions expanded its business model in April 2023 by introducing a franchise opportunity that allows business owners to establish their own Fiji BPO businesses under the FOCO model. This approach is particularly advantageous for entrepreneurs seeking a ready-made business setup, offering a lucrative way to run BPO services.
- In December 2023, Capgemini SE entered into a partnership with InPost Group, a public logistics company in Poland. This collaboration aims to implement operational changes across several European countries, optimizing business processes for improved efficiency and service delivery.
Market Concentration & Characteristics:
The Business Process Outsourcing (BPO) market exhibits moderate concentration, with a few dominant players holding significant market shares, while numerous smaller and niche providers contribute to the competitive landscape. Major global companies such as Accenture, Infosys, and Wipro continue to lead the market, benefiting from established brand recognition, advanced technological capabilities, and extensive global delivery networks. However, the market also includes a large number of regional and specialized providers focusing on specific industry verticals or service areas, such as customer service, finance, and IT support. This segmentation allows for tailored solutions and increased competition. BPO providers are increasingly offering integrated, end-to-end services driven by automation, artificial intelligence, and cloud-based platforms. The market’s dynamic nature fosters continuous innovation, as players differentiate themselves through value-added services, cost efficiency, and strategic partnerships. As businesses seek more agile and scalable solutions, the market is characterized by ongoing technological advancements and evolving client expectations.
Report Coverage:
The research report offers an in-depth analysis based on Service, Outsourcing Type, End-User, Deployment Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The BPO market will continue to expand as companies increasingly seek cost-effective solutions for non-core functions.
- The integration of artificial intelligence and automation will drive enhanced service efficiency and reduce manual intervention.
- Cloud-based outsourcing solutions will become more prevalent, offering flexibility, scalability, and remote service delivery.
- Businesses will prioritize digital transformation through BPO, adopting advanced technologies to stay competitive and improve operational performance.
- The demand for data security and regulatory compliance will remain a key focus for BPO providers across various industries.
- Emerging markets, particularly in Asia-Pacific and Latin America, will attract more BPO investments due to cost advantages and skilled labor availability.
- Nearshore outsourcing models will gain traction as companies look for improved time zone alignment and cultural compatibility.
- The trend toward strategic partnerships, rather than traditional vendor-client relationships, will continue to rise in the BPO sector.
- Talent management and workforce development will become increasingly important to address the challenges of high turnover and evolving client needs.
- BPO providers will place more emphasis on delivering specialized, high-value services to meet the growing demands of industry-specific sectors.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Business Process Outsourcing (BPO) Market?
What factors are driving the growth of the Business Process Outsourcing (BPO) Market?
What are some challenges faced by the Business Process Outsourcing (BPO) Market?
Who are the major players in the Business Process Outsourcing (BPO) Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Business Process Outsourcing (BPO) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Business Process Outsourcing (BPO) Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 316,894.35 million → 2032: USD 669,473.2 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Business Process Outsourcing (BPO) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Business Process Outsourcing (BPO) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Business Process Outsourcing (BPO) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Business Process Outsourcing (BPO) Market Drivers
- 3.3 Business Process Outsourcing (BPO) Market Restraints & Challenges
- 3.4 Business Process Outsourcing (BPO) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Business Process Outsourcing (BPO) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Business Process Outsourcing (BPO) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Business Process Outsourcing (BPO) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Business Process Outsourcing (BPO) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Business Process Outsourcing (BPO) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Business Process Outsourcing (BPO) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Business Process Outsourcing (BPO) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Business Process Outsourcing (BPO) Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Business Process Outsourcing (BPO) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Business Process Outsourcing (BPO) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Business Process Outsourcing (BPO) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Business Process Outsourcing (BPO) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Business Process Outsourcing (BPO) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Business Process Outsourcing (BPO) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Business Process Outsourcing (BPO) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Business Process Outsourcing (BPO) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Business Process Outsourcing (BPO) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Business Process Outsourcing (BPO) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Business Process Outsourcing (BPO) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
