
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Canada Biopharmaceuticals Contract Manufacturing Market Size 2023 | USD 529.37 Million |
| Canada Biopharmaceuticals Contract Manufacturing Market, CAGR | 14.77% |
| Canada Biopharmaceuticals Contract Manufacturing Market Size 2032 | USD 1,828.61 Million |
Market Overview
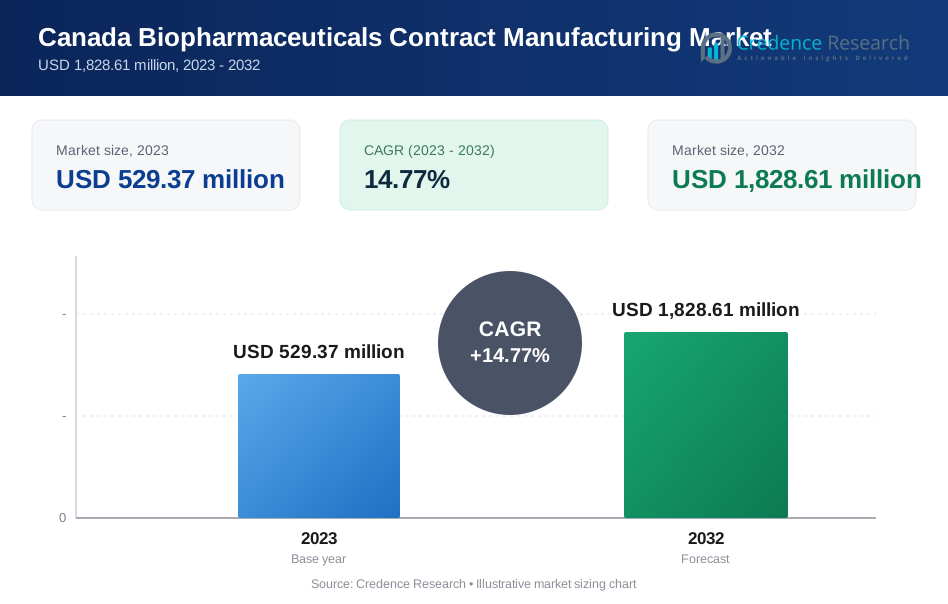
The Canada Biopharmaceuticals Contract Manufacturing Market is projected to grow from USD 529.37 million in 2023 to USD 1,828.61 million by 2032, reflecting a robust compound annual growth rate (CAGR) of 14.77%.
The Canada Biopharmaceuticals Contract Manufacturing market is driven by the increasing demand for cost-effective and efficient production solutions, as well as the growing need for advanced biologic therapies. The rise in outsourcing by pharmaceutical companies, coupled with the ability to scale production quickly and meet regulatory standards, is propelling market growth. Furthermore, advancements in biologics and biosimilars, including monoclonal antibodies and gene therapies, are contributing to the demand for specialized manufacturing services. The government's favorable policies and investment in healthcare infrastructure also support market expansion. As the biopharmaceutical sector continues to evolve, manufacturers are adopting cutting-edge technologies such as single-use systems and continuous manufacturing to improve efficiency and reduce costs. This is driving a shift toward more agile and flexible manufacturing processes, helping companies meet the rapidly changing needs of the global biopharmaceutical industry. These trends are expected to fuel the market's growth in the coming years.
Canada's Biopharmaceuticals Contract Manufacturing market is geographically concentrated in key regions such as Ontario and Quebec, where the majority of manufacturing facilities and research institutions are located. Ontario, with its robust pharmaceutical infrastructure, is a major hub for biopharmaceutical outsourcing, while Quebec also plays a significant role with its strong biotech sector and favorable business environment. Western Canada, including British Columbia, is emerging as a growing center for biopharmaceutical manufacturing, driven by increased investment in biotechnology and life sciences. Key players in the Canadian market include global companies such as Boehringer Ingelheim GmbH, Lonza, WuXi Biologics, Thermo Fisher Scientific, and Pfizer Inc. These industry leaders are leveraging the country’s advanced manufacturing capabilities, regulatory expertise, and skilled workforce to meet the growing demand for biologic and biosimilar drugs. Their presence in Canada ensures continued growth and innovation in the biopharmaceutical contract manufacturing sector.
Market Insights
- The Canada Biopharmaceuticals Contract Manufacturing market was valued at USD 529.37 million in 2023 and is projected to reach USD 1,828.61 million by 2032, growing at a CAGR of 14.77%.
- Increasing demand for biologics and biosimilars is driving the market, with contract manufacturers leveraging Canada’s advanced infrastructure.
- The shift toward outsourcing production and focus on cost-effective solutions is a key market trend, with companies looking to reduce operational costs.
- Technological advancements such as automation, single-use technologies, and continuous manufacturing are transforming the production process.
- Strong competition from both local and international manufacturers is putting price pressure on contract manufacturers.
- Strict regulatory standards and compliance requirements remain significant restraints for manufacturers seeking to expand operations.
- Ontario and Quebec are leading regions in the market, while Western Canada and Atlantic Canada are growing in importance due to expanding biotech sectors.
Market Drivers
Advancements in Biotechnology and Manufacturing Technologies
Technological advancements, such as single-use technologies, continuous manufacturing, and automation, are transforming the biopharmaceutical contract manufacturing landscape. These innovations allow for more efficient, scalable, and flexible production processes. Canada’s contract manufacturers are at the forefront of adopting these technologies, which not only reduce production costs but also improve the speed to market for new drugs. For instance, the Canadian government has invested over $1.2 billion to enhance the country's biomanufacturing capacity, including the development of RNA vaccine production facilities. As biopharmaceuticals become increasingly complex, these technological advancements are crucial for meeting the growing demand for high-quality, cost-effective products.
Growing Demand for Biopharmaceuticals
The increasing prevalence of chronic diseases, such as cancer, diabetes, and autoimmune disorders, is driving the demand for advanced biopharmaceutical products. As the need for biologic therapies rises, pharmaceutical companies are increasingly outsourcing their manufacturing processes to contract manufacturers in Canada. For instance, the Canadian biopharmaceutical sector has seen a significant increase in the number of biologic drug approvals, with over 50 new biologics approved by Health Canada in the past five years. This trend is attributed to the expertise and infrastructure available within the country to handle complex biologic production, thus enabling drug developers to scale up quickly and meet global demands without the heavy investment in in-house facilities.
Cost-Effectiveness and Operational Efficiency
Outsourcing biopharmaceutical manufacturing offers companies significant cost savings and operational efficiencies. By partnering with contract manufacturers, pharmaceutical firms can avoid the capital expenditure required to build and maintain production facilities. This arrangement also allows companies to focus on their core competencies, such as drug development and marketing, while benefiting from the specialized capabilities of contract manufacturers. Canada’s well-established manufacturing ecosystem, coupled with a highly skilled workforce, provides a cost-effective solution for pharmaceutical companies to maintain high production standards while controlling costs.
Regulatory Expertise and Compliance
Canada’s strict regulatory environment, overseen by Health Canada, ensures that contract manufacturers comply with international quality standards. This robust regulatory framework enhances the reliability and safety of the biopharmaceutical products manufactured within the country. The ability of Canadian contract manufacturers to navigate complex regulations efficiently makes them an attractive option for pharmaceutical companies looking to enter global markets. With the increasing complexity of biologic drugs, manufacturers that can ensure regulatory compliance while maintaining product integrity are crucial to meeting market demand.
Market Trends
Expansion of Contract Manufacturing Capabilities
To meet the evolving needs of the biopharmaceutical sector, contract manufacturers in Canada are expanding their capabilities to support a wider range of drug products. This includes increasing capacity for the production of large-scale biologics and the development of specialized facilities for gene therapies and personalized medicines. By enhancing their capabilities, Canadian contract manufacturers are positioning themselves to serve a broader range of pharmaceutical companies and tap into emerging markets. For instance, BioVectra received nearly $28 million from the Canadian government to expand its biopharmaceutical manufacturing capabilities. This trend of expanding service offerings is helping to strengthen Canada's position as a key player in the global biopharmaceutical contract manufacturing landscape.
Shift Towards Outsourcing
A significant trend in the Canada Biopharmaceuticals Contract Manufacturing market is the increasing shift towards outsourcing production. Pharmaceutical companies are focusing on their core competencies, such as research and development, while outsourcing manufacturing to specialized contract manufacturers. This trend is driven by the need for high-quality, scalable, and flexible production capabilities that can meet the growing demand for biologic drugs. Outsourcing allows pharmaceutical companies to reduce operational costs and improve efficiency by leveraging the expertise and infrastructure of established contract manufacturers in Canada.
Focus on Biologics and Biosimilars
The growing focus on biologics and biosimilars is another key trend in the market. Biologic drugs, including monoclonal antibodies and gene therapies, have become a major area of focus due to their effectiveness in treating various complex diseases. As the demand for these therapies continues to rise, biopharmaceutical companies are increasingly turning to contract manufacturers in Canada that have the necessary facilities and expertise to produce these complex biologics. Additionally, the growing market for biosimilars, which are more cost-effective alternatives to branded biologics, is driving demand for contract manufacturing services, as companies look for reliable and efficient production options.
Adoption of Advanced Manufacturing Technologies
Another notable trend is the adoption of advanced manufacturing technologies, such as continuous manufacturing and single-use systems. These technologies allow for more flexible, efficient, and cost-effective production processes, making them highly attractive to biopharmaceutical companies. Canadian contract manufacturers are at the forefront of incorporating these technologies, which help improve production speed, reduce waste, and enhance product consistency. The trend towards adopting innovative manufacturing technologies is expected to drive further growth in the market, as it enables manufacturers to meet the increasing demand for biologic drugs while optimizing production costs.
Market Challenges Analysis
Regulatory Complexities and Compliance Challenges
One of the primary challenges faced by the Canada Biopharmaceuticals Contract Manufacturing market is navigating complex regulatory requirements. Although Canada has a well-established regulatory framework overseen by Health Canada, the biopharmaceutical sector is subject to stringent compliance standards. Contract manufacturers must adhere to these standards to ensure the safety and efficacy of the products they produce. For instance, Health Canada conducts over 200 inspections annually to ensure compliance with Good Manufacturing Practices (GMP). The increasing complexity of biologic drugs, including gene therapies and personalized medicines, further intensifies the regulatory burden. Manufacturers must ensure that they not only meet local regulations but also comply with international standards, which can vary across markets. This ongoing need for compliance and regulatory updates can delay product timelines and add significant costs, making it a critical challenge for contract manufacturers to manage effectively.
Rising Competition and Price Pressure
Another challenge in the market is the rising competition and price pressure from both local and international contract manufacturers. As demand for biopharmaceuticals continues to grow, the market is becoming more competitive, with new entrants seeking to establish themselves in the contract manufacturing space. This increased competition often leads to downward pressure on pricing, which can affect profit margins for contract manufacturers. Additionally, the need to offer high-quality production while keeping costs low has led to a focus on cost-cutting measures such as automation and process optimization. While these strategies are essential for maintaining competitiveness, they can also require significant upfront investment in advanced technologies, which can be a barrier for some manufacturers. Balancing the need for innovation and cost-efficiency remains a persistent challenge in the sector.
Market Opportunities
Expanding Demand for Biologics and Biosimilars
The growing demand for biologics and biosimilars presents significant market opportunities for contract manufacturers in Canada. With the increasing prevalence of chronic diseases and the rising adoption of biologic therapies, there is a need for efficient and scalable production capabilities. Canadian contract manufacturers, with their advanced facilities and regulatory expertise, are well-positioned to support the growing demand for biologics, including monoclonal antibodies and gene therapies. Additionally, the expanding market for biosimilars, as cost-effective alternatives to branded biologics, creates further opportunities for contract manufacturers to offer production services for these high-demand therapies. This trend is expected to drive long-term growth in the biopharmaceutical contract manufacturing sector in Canada.
Adoption of Advanced Manufacturing Technologies
The adoption of advanced manufacturing technologies presents another key opportunity in the market. Continuous manufacturing, single-use technologies, and automation are revolutionizing biopharmaceutical production by improving efficiency, reducing costs, and enabling flexible, scalable production. Canadian contract manufacturers can leverage these technologies to enhance production capabilities, reduce turnaround times, and maintain high-quality standards. As the biopharmaceutical industry continues to evolve, manufacturers who invest in these innovations will be able to meet the increasing demand for high-quality, cost-effective biologic therapies. Moreover, the growing trend of personalized medicine and gene therapies offers an opportunity for Canadian contract manufacturers to expand their service offerings and cater to this niche but rapidly growing segment, positioning themselves as leaders in the global contract manufacturing market.
Market Segmentation Analysis:
By Source:
The Canada Biopharmaceuticals Contract Manufacturing market is segmented by source into mammalian and non-mammalian systems. Mammalian cell systems dominate the market due to their ability to produce complex biologics, such as monoclonal antibodies and therapeutic proteins, which require eukaryotic cell environments to fold properly. This makes mammalian systems particularly suitable for biologic drug production. Non-mammalian systems, including microbial and insect cell-based production, are gaining traction due to their cost-effectiveness and faster production times. These systems are often utilized for simpler proteins and biosimilars, offering a more economical option compared to mammalian cells. As the biopharmaceutical landscape continues to shift towards biologics and biosimilars, both mammalian and non-mammalian systems are expected to see growth, with mammalian systems catering to more complex drug candidates and non-mammalian systems meeting the demand for faster, cost-efficient production.
By Service:
The market is also segmented based on service offerings, which include process development, downstream, upstream, fill & finish operations, analytical & QC studies, packaging & labeling, and others. Process development services are crucial in the early stages of drug production, focusing on optimizing production techniques for biologic drugs. Upstream services involve the cultivation and growth of cells, while downstream services focus on purification and harvesting of the final product. Fill & finish operations are essential for packaging and ensuring the sterility of the final drug product. Analytical & QC studies ensure that the produced biologics meet safety, efficacy, and regulatory standards. Additionally, packaging & labeling services are critical for ensuring compliance with regulatory requirements and providing clear information to end-users. As biopharmaceutical companies increasingly seek end-to-end solutions, demand for these services is expected to rise, providing significant growth opportunities for contract manufacturers in Canada.
Segments:
Based on Source:
- Mammalian
- Non-mammalian
Based on Service:
- Process Development
- Downstream
- Upstream
- Fill & Finish Operations
- Analytical & QC studies
- Packaging & Labelling
- Others
Based on Drug Type:
- Biologics
- Monoclonal antibodies (mAbs)
- Recombinant Proteins
- Vaccines
- Antisense, RNAi, & Molecular Therapy
- Others
- Biosimilars
Based on Type:
- Drug Substance
- Finished Drug Product
Based on Scale of Operation:
- Clinical
- Commercial
Based on Therapeutic Area:
- Oncology
- Autoimmune Diseases
- Cardiovascular Diseases
- Infectious Diseases
- Others
Based on the Geography:
- Ontario
- Quebec
- Western Canada
- British Columbia
- Atlantic Canada
Regional Analysis
Ontario
Ontario holds approximately 40% of the market share, primarily due to its well-established pharmaceutical infrastructure, proximity to major biotech companies, and access to skilled labor. Ontario is the dominant region for biopharmaceutical contract manufacturing in Canada, accounting for the largest market share. The province boasts a robust pharmaceutical and biotechnology sector, supported by numerous research institutions, universities, and an extensive network of manufacturing facilities. Toronto, in particular, serves as a hub for life sciences and biopharmaceutical companies, providing contract manufacturers with easy access to cutting-edge technologies and research. The region’s favorable business environment, skilled workforce, and well-established infrastructure make it a prime location for pharmaceutical outsourcing. As the demand for biologic and biosimilar products continues to rise, Ontario’s contract manufacturing sector is poised to maintain its dominant position in the market.
Quebec
Quebec holds a strong second position in the Canada Biopharmaceuticals Contract Manufacturing market, with a market share of around 30%. The province is home to a well-developed biopharmaceutical sector, with several key players operating in the region. Montreal serves as a major biotech and pharmaceutical hub, providing access to a large talent pool and state-of-the-art manufacturing facilities. Quebec’s regulatory environment, combined with its favorable tax incentives for biopharmaceutical companies, makes it an attractive destination for both local and international contract manufacturers. The region’s strategic location, combined with its advanced capabilities in biologics production, positions it as a key player in the Canadian contract manufacturing landscape.
Western Canada, British Columbia, and Atlantic Canada
Western Canada, which includes provinces such as Alberta and Saskatchewan, accounts for approximately 15% of the market share in the Canada Biopharmaceuticals Contract Manufacturing sector. While not as large as Ontario and Quebec, Western Canada is emerging as a competitive player due to the growing presence of pharmaceutical companies in the region. British Columbia, with its focus on biotechnology and life sciences, is seeing increased investment in contract manufacturing. The region benefits from proximity to international markets, a skilled workforce, and ongoing support for the biotech sector. Meanwhile, Atlantic Canada, with a market share of around 10%, is gradually expanding its presence in the contract manufacturing industry. Although smaller in size, the region is home to growing biopharmaceutical firms that provide specialized services and cater to niche markets, contributing to the overall growth of the sector.
Key Player Analysis
- Boehringer Ingelheim GmbH
- Lonza
- JRS PHARMA
- AGC Biologics
- ProBioGen
- Samsung Biologics
- Thermo Fisher Scientific, Inc.
- Binex Co., Ltd.
- WuXi Biologics
- Catalent, Inc.
- Cambrex Corporation
- Pfizer Inc.
- Siegfried Holding AG
Competitive Analysis
The Canada Biopharmaceuticals Contract Manufacturing market is highly competitive, with several leading players driving innovation and growth. Major companies in the sector include Boehringer Ingelheim GmbH, Lonza, JRS PHARMA, AGC Biologics, ProBioGen, Samsung Biologics, Thermo Fisher Scientific, Inc., Binex Co., Ltd., WuXi Biologics, Catalent, Inc., Cambrex Corporation, Pfizer Inc., and Siegfried Holding AG. Leading players are increasingly investing in technological advancements such as continuous manufacturing, automation, and single-use technologies, which help improve efficiency, reduce production costs, and meet the rising demand for biologics and biosimilars. These innovations are critical for maintaining competitiveness, as companies seek to offer comprehensive end-to-end services, from process development to packaging and labeling. For instance, the Canadian Research Council has launched initiatives to support the adoption of advanced manufacturing technologies, such as AI and digitization, in the biopharmaceutical sector. Strategic partnerships and collaborations are common, with many firms aligning with research institutions or biopharmaceutical companies to expand their capabilities and enhance their service offerings. In addition, regulatory compliance is a significant factor, and companies that can navigate complex regulatory environments while maintaining high-quality standards gain a competitive edge. As the demand for personalized medicine and biologics continues to rise, the competitive landscape will likely see further consolidation, with companies focusing on scalability and flexibility in production to stay ahead of market trends.
Recent Developments
- In Nov 2024, FUJIFILM Diosynth Biotechnologies signed a multi-year manufacturing agreement with TG Therapeutics for BRIUMVI® production at their new Holly Springs, North Carolina facility.
- In October 2024, Lonza extended collaboration with a major biopharmaceutical partner for ADC manufacturing.
- In October 2024, Thermo Fisher Scientific launched comprehensive CDMO and CRO drug development solutions..
- In July 2024, Rentschler Biopharma opened new state-of-the-art production line in Milford, Massachusetts.
- In May 2024, AGC Biologics offering end-to-end biopharmaceutical development and manufacturing capabilities.
Market Concentration & Characteristics
The Canada Biopharmaceuticals Contract Manufacturing market exhibits moderate concentration, with a mix of large multinational players and regional companies contributing to its growth. The market is characterized by a few key players that dominate the sector, leveraging their extensive experience, advanced technologies, and global reach. These large players typically offer comprehensive services across the entire biopharmaceutical production process, from early-stage development to final fill-and-finish operations, catering to the growing demand for biologics and biosimilars. However, the market also contains numerous smaller and mid-sized firms, which specialize in niche services or cater to specific client needs, providing flexibility and personalized service. The increasing complexity of biologic drugs, along with the rising demand for personalized medicine, is driving companies to innovate and adapt, often investing heavily in state-of-the-art manufacturing technologies such as single-use systems and continuous manufacturing. Regulatory compliance is another key characteristic of this market, with companies needing to meet stringent health and safety standards, both domestically and internationally. As a result, the market remains highly dynamic, with continued consolidation and partnerships expected, as larger players acquire or collaborate with smaller companies to expand their service offerings and geographic reach.
Report Coverage
The research report offers an in-depth analysis based on Source, Service, Drug Type, Type, Scale of Operation, Therapeutic Area and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Canada Biopharmaceuticals Contract Manufacturing market is expected to grow significantly, driven by the increasing demand for biologics and biosimilars.
- Technological advancements, including automation and continuous manufacturing, will enhance production efficiency and scalability.
- Investment in state-of-the-art manufacturing facilities will remain a priority for companies to meet the growing demand for complex biologic therapies.
- Regulatory compliance will continue to be a key factor for success, with manufacturers focusing on adhering to both local and international standards.
- The demand for personalized medicine will drive the need for more flexible and specialized manufacturing services.
- Strategic partnerships and acquisitions are anticipated to accelerate, allowing companies to expand their capabilities and market presence.
- Contract manufacturers will increasingly offer end-to-end services, from early development stages to final product packaging and labeling.
- Canada’s favorable business environment and skilled workforce will continue to attract investment in the biopharmaceutical sector.
- The growing trend of outsourcing production by biopharmaceutical companies will provide further opportunities for contract manufacturers.
- As the market matures, there will be a focus on sustainability and cost-effective solutions to ensure long-term growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Canada Biopharmaceuticals Contract Manufacturing Market?
What factors are driving the growth of the Canada Biopharmaceuticals Contract Manufacturing Market?
What are the key segments within the Canada Biopharmaceuticals Contract Manufacturing Market?
What are some challenges faced by the Canada Biopharmaceuticals Contract Manufacturing Market?
Who are the major players in the Canada Biopharmaceuticals Contract Manufacturing Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Canada Biopharmaceuticals Contract Manufacturing Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Canada Biopharmaceuticals Contract Manufacturing Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 529.37 million → 2032: USD 1,828.61 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Canada Biopharmaceuticals Contract Manufacturing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Canada Biopharmaceuticals Contract Manufacturing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Canada Biopharmaceuticals Contract Manufacturing Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Canada Biopharmaceuticals Contract Manufacturing Market Drivers
- 3.3 Canada Biopharmaceuticals Contract Manufacturing Market Restraints & Challenges
- 3.4 Canada Biopharmaceuticals Contract Manufacturing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Canada Biopharmaceuticals Contract Manufacturing Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Canada Biopharmaceuticals Contract Manufacturing Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Canada Biopharmaceuticals Contract Manufacturing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Canada Biopharmaceuticals Contract Manufacturing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Canada Biopharmaceuticals Contract Manufacturing Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Canada Biopharmaceuticals Contract Manufacturing market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Canada Biopharmaceuticals Contract Manufacturing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Canada Biopharmaceuticals Contract Manufacturing Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Canada Biopharmaceuticals Contract Manufacturing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Canada Biopharmaceuticals Contract Manufacturing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Canada Biopharmaceuticals Contract Manufacturing Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Canada Biopharmaceuticals Contract Manufacturing Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Canada Biopharmaceuticals Contract Manufacturing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Canada Biopharmaceuticals Contract Manufacturing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Canada Biopharmaceuticals Contract Manufacturing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Canada Biopharmaceuticals Contract Manufacturing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Canada Biopharmaceuticals Contract Manufacturing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Canada Biopharmaceuticals Contract Manufacturing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Canada Biopharmaceuticals Contract Manufacturing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
