
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
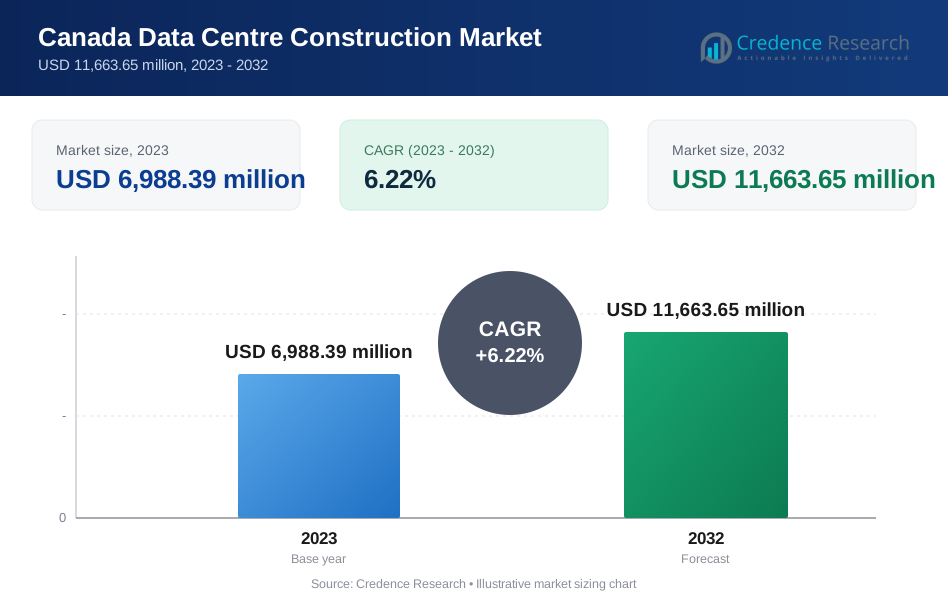
| Canada Data Centre Construction Market Size 2023 | USD 6,988.39 million |
| Canada Data Centre Construction Market, CAGR | 6.22% |
| Canada Data Centre Construction Market Size 2032 | USD 11,663.65 million |
Market Overview
The Canada Data Centre Construction Market is projected to grow from USD 6,988.39 million in 2023 to USD 11,663.65 million by 2032, reflecting a compound annual growth rate (CAGR) of 6.22%.
The Canada Data Centre Construction Market is driven by increasing demand for cloud services, data storage, and processing capabilities, fueled by the digital transformation across various industries. Government support for digital infrastructure development, along with favorable tax incentives, further stimulates market growth. The rise of e-commerce, remote work, and online education has also amplified the need for robust data center facilities. Additionally, advancements in technologies such as artificial intelligence, big data analytics, and IoT are propelling the demand for scalable and energy-efficient data centers. These trends are shaping the market towards adopting sustainable practices and innovative solutions to meet evolving needs.
The Canada Data Centre Construction Market is concentrated in key regions such as Ontario and British Columbia, driven by strong digital infrastructure, connectivity, and access to renewable energy sources. Ontario, particularly Toronto, serves as a major data center hub due to its strategic location and proximity to business and financial institutions. British Columbia, with Vancouver as a key city, benefits from its cooler climate and access to hydroelectric power, making it attractive for sustainable data center developments. Major players in the market include DPR Construction, Inc., Schneider Electric SE, Fortis Construction Inc., and Turner Construction Co., who leverage their expertise to meet growing demand.
Market Drivers
Government Initiatives and Regulatory Environment
Government initiatives and regulations are playing a pivotal role in shaping the data center landscape in Canada. The Canadian government's emphasis on data sovereignty and security is encouraging businesses to invest in local data centers to ensure that sensitive data is stored within national borders. For instance, the Canadian government has implemented policies aimed at enhancing digital infrastructure, such as improving broadband connectivity and expanding data center capacity. This focus on data sovereignty is driven by the need to protect national security and comply with international data protection standards. Additionally, government-led initiatives aimed at enhancing digital infrastructure, such as improving broadband connectivity and expanding data center capacity, are further propelling market growth. These policies create a favorable environment for the development of secure and reliable data centers.
Foreign Investment, Geographic Advantages, and Sustainability
Foreign investment and competition are increasing in the Canadian data center market, with global data center providers expanding their presence to capitalize on the growing demand. Canada's strategic geographic location, offering strong connectivity to the United States and Europe, makes it an attractive destination for data centers. Investments in submarine cable infrastructure are enhancing connectivity between Canada and other regions, facilitating seamless data transfer and communication. Furthermore, there is a growing focus on sustainability, driven by environmental concerns and government incentives. For instance, there are close to 12 submarine cable systems connecting Canada, many of which are under construction. Canada's abundant renewable energy resources, such as hydro and wind power, provide a significant advantage, making the country an ideal location for sustainable data center development. This focus on renewable energy not only reduces the carbon footprint of data centers but also aligns with global trends towards greener operations. As a result, the Canadian data center market is set for continued growth, driven by the convergence of digital transformation, economic expansion, and sustainable practices.
Digital Transformation and Cloud Adoption
The Canada Data Centre Construction Market is significantly driven by digital transformation and the growing adoption of cloud computing services. As businesses and organizations increasingly migrate their operations to the cloud, the demand for data center capacity continues to rise. This shift towards cloud-based solutions enables companies to scale their IT infrastructure efficiently, supporting a wide range of digital services and applications. Additionally, the growth of data-intensive applications such as artificial intelligence (AI), machine learning (ML), and big data analytics is further fueling the need for advanced data centers. These technologies require substantial data storage and processing capabilities, making robust and scalable data center infrastructure essential for businesses looking to remain competitive in the digital economy.
Economic Growth and Technological Advancements
Canada's strong economic growth is another critical driver of the data center construction market. Economic expansion fuels demand for digital services and infrastructure, including data centers, as businesses and consumers seek faster and more reliable access to information. Technological advancements, such as the rollout of 5G networks, the rise of the Internet of Things (IoT), and the increasing implementation of edge computing, are creating new requirements for data storage and processing. These innovations demand more localized data processing to minimize latency and improve performance, further driving the need for state-of-the-art data center facilities that can handle the complexities of modern technology.
Market Trends
Expansion of Hyper-Scale and Edge Computing Data Centers
The Canada Data Centre Construction Market is witnessing substantial investments from global technology giants, focusing on developing hyper-scale data centers to meet the growing demand for cloud services and content delivery. These large-scale facilities are not only about size but also about sustainability, with many hyper-scale data centers prioritizing the incorporation of renewable energy sources and energy-efficient technologies. For instance, American Tower is deploying edge data centers to provide disaster recovery and network redundancy, enhancing performance for real-time applications. This focus on sustainability helps reduce the environmental impact and operating costs, making these facilities attractive to businesses looking to enhance their green credentials. In parallel, the rise of edge computing is driving the development of smaller, distributed data centers closer to end-users. These edge data centers are strategically located in urban areas and industrial zones to minimize latency, improve performance for real-time applications, and cater to specific regional needs. The shift towards edge computing supports the growing demand for low-latency processing required by applications such as IoT, autonomous vehicles, and real-time analytics, making it a critical component of the evolving data center landscape in Canada.
Adoption of Modular Data Centers and Enhanced Interconnectivity
Modular data centers are gaining popularity in Canada due to their scalability, flexibility, and rapid deployment capabilities. These prefabricated modules can be quickly assembled and deployed to meet changing demands, making them ideal for companies that require fast scalability or disaster recovery solutions. The modular approach allows organizations to efficiently manage their IT resources, scaling up or down as needed without significant infrastructure investment. This flexibility is particularly valuable in a market where technological advancements and business requirements are constantly evolving. Alongside modular developments, there is a growing emphasis on data center interconnectivity, with significant investments being made in network infrastructure, such as submarine cables and fiber optic networks. These investments are enhancing connectivity between data centers in Canada and other regions, enabling seamless data transfer and communication. Major cities are emerging as data hubs, attracting data center investments and fostering innovation. Enhanced connectivity and the development of data hubs are crucial for supporting the growth of the digital economy, facilitating efficient data management, and providing businesses with the infrastructure needed to thrive in an interconnected world. This trend towards modular construction and enhanced interconnectivity reflects Canada’s commitment to building a resilient, adaptable, and forward-looking data center landscape.
Market Challenges Analysis
Land and Energy Challenges
The Canada Data Centre Construction Market faces significant challenges related to land availability and energy costs, both of which are critical for the development and operation of data centers. Limited availability of suitable land in urban areas, where proximity to fiber networks and access to a skilled workforce are crucial, poses a considerable challenge for data center developers. For instance, a search for 20 acres in key markets like Toronto and Montreal often yields no available land for sale. High land prices, especially in metropolitan regions, further complicate the development of new facilities, as these costs can significantly increase the overall budget of data center projects. Additionally, rising energy prices present another major concern, impacting the operational expenses of data centers. This issue is particularly challenging in areas with limited access to renewable energy options, where reliance on traditional energy sources can lead to higher costs. Ensuring grid stability and having the capacity to meet the energy demands of large-scale data centers is also critical, as the growing number of data centers increases the strain on existing energy infrastructure. These land and energy challenges necessitate substantial investments in both real estate and energy infrastructure, as well as the exploration of alternative, more sustainable power sources.
Talent Shortages and Regulatory Complexities
Talent shortages and regulatory complexities present additional hurdles in the Canada Data Centre Construction Market. The industry requires specialized skills in IT infrastructure, engineering, and operations management, but competition for such talent is intense, particularly in major cities where the demand outpaces supply. This shortage of skilled professionals can impact the efficiency and effectiveness of data center operations, making it challenging for companies to maintain optimal performance. Moreover, navigating the complex regulatory landscape adds to the difficulties faced by data center operators. Regulations related to zoning laws, environmental standards, and data privacy requirements can be intricate and vary widely across different regions. Complying with these regulations can be time-consuming and costly, often requiring extensive legal and compliance expertise. Obtaining necessary permits and approvals for data center construction can also be a lengthy process, further delaying project timelines and increasing costs. Addressing these regulatory and talent challenges is crucial for sustaining the growth and competitiveness of the data center market in Canada. Companies must invest in workforce development, regulatory compliance, and strategic planning to navigate these challenges effectively.
Market Segmentation Analysis:
By Type:
The Canada Data Centre Construction Market is segmented by data center type into Tier 1, Tier 2, Tier 3, and Tier 4 facilities. Tier 1 and Tier 2 data centers offer basic infrastructure with limited redundancy, primarily serving small businesses and less critical applications that do not require high levels of availability. These lower-tier data centers provide cost-effective solutions but may not meet the demands of larger enterprises or applications that require stringent uptime. In contrast, Tier 3 and Tier 4 data centers provide high levels of redundancy and availability, ensuring minimal downtime and continuous operation even during maintenance or unexpected disruptions. These advanced facilities are essential for large enterprises, financial institutions, and government agencies that manage sensitive and mission-critical data. The demand for Tier 3 and Tier 4 data centers is increasing in Canada due to the growing need for secure, reliable, and compliant data infrastructure that supports the expanding digital economy and the adoption of advanced technologies.
By Infrastructure:
The market is also categorized based on infrastructure components, including IT Infrastructure, Power Distribution and Cooling (PD&C) Infrastructure, and Miscellaneous Infrastructure. IT Infrastructure forms the core of data center operations, encompassing networking equipment, servers, and storage solutions essential for efficient data processing, storage, and management. The rising adoption of cloud services, big data analytics, and IoT applications drives the demand for advanced IT infrastructure capable of supporting scalable and high-performance computing. PD&C Infrastructure is critical for maintaining data center efficiency, focusing on power distribution systems and innovative cooling solutions to manage the heat generated by high-performance equipment. As energy efficiency becomes a priority, there is a growing emphasis on sustainable cooling technologies to reduce operational costs and environmental impact. Miscellaneous Infrastructure includes essential components such as fire suppression systems, security solutions, and building management systems, ensuring the safety, security, and optimal performance of data centers. These infrastructure components collectively contribute to the robust growth of the Canada Data Centre Construction Market.
Segments:
Based on Type:
- Tier 1
- Tier 2
- Tier 3
- Tier 4
Based on Infrastructure:
- IT Infrastructure
- Networking Equipment
- Server
- Storage
- PD & Cooling Infrastructure
- Power Distribution
- Cooling
- Miscellaneous Infrastructure
Based on Vertical:
- IT & Telecom
- BFSI
- Government & Defense
- Healthcare
- Energy
- Others
Based on the Geography:
- Western Provinces (British Columbia, Alberta, Saskatchewan, Manitoba)
- Ontario
- Eastern Provinces (Quebec, Nova Scotia, New Brunswick, Prince Edward Island, Newfoundland and Labrador)
- Northern Territories (Yukon, Northwest Territories, Nunavut)
Regional Analysis
Ontario
Ontario holds the largest market share in the Canada Data Centre Construction Market, accounting for approximately 40% of the total market. As Canada’s most populous province and a major economic hub, Ontario has become a prime location for data center development. The region benefits from robust digital infrastructure, a skilled workforce, and strong connectivity to major cities in Canada and the United States. Toronto, in particular, is a key data center hub due to its strategic location, access to abundant renewable energy sources, and a favorable business environment. The Ontario government’s commitment to enhancing digital infrastructure and promoting economic growth through technology initiatives further drives the demand for data centers in the province. Additionally, Ontario's proximity to significant financial and business institutions contributes to the need for high-tier data centers that can support the stringent data security and compliance requirements of these sectors.
British Columbia
British Columbia represents around 15% of the market share, emerging as another critical region for data center construction in Canada. The province's appeal lies in its cooler climate, which offers natural cooling advantages, potentially reducing operational costs for data center facilities. Vancouver, the largest city in British Columbia, serves as a key data center hub, driven by its strong connectivity to the Asia-Pacific region and access to renewable energy sources like hydroelectric power. The provincial government’s focus on sustainability and clean energy further supports the development of green data centers in the region. British Columbia's strategic location on the west coast also makes it an attractive destination for international data center operators looking to expand their footprint in North America, particularly those targeting markets in Asia. The combination of environmental sustainability, strategic geographic location, and access to renewable energy makes British Columbia a vital player in the Canada Data Centre Construction Market.
Key Player Analysis
- DPR Construction, Inc.
- Schneider Electric SE
- Fortis Construction Inc.
- HITT Contracting Inc.
- Clune Construction Company LP
- Nabholz Construction Corporation
- Hensel Phelps Construction Co. Inc.
- Holder Construction Company
- Turner Construction Co.
Competitive Analysis
The Canada Data Centre Construction Market is characterized by intense competition among leading players such as DPR Construction, Inc., Schneider Electric SE, Fortis Construction Inc., HITT Contracting Inc., Clune Construction Company LP, Nabholz Construction Corporation, Hensel Phelps Construction Co. Inc., Holder Construction Company, and Turner Construction Co. These companies dominate the market by leveraging their advanced construction capabilities, technological expertise, and comprehensive service offerings. They focus on delivering high-quality, scalable, and energy-efficient data center solutions that meet the growing needs for cloud services, data storage, and processing capabilities. Strategic partnerships, investment in sustainable building practices, and innovation in data center design and construction are key strategies employed by these players to maintain their competitive edge. Additionally, their ability to offer end-to-end solutions from design and construction to maintenance and operations enables them to cater to the diverse requirements of businesses across various sectors, solidifying their positions in the expanding Canadian market.
Recent Developments
- In July 2024, DPR Construction announced new projects awarded as of July 2024, including data center projects.
- In June 2024, Fortis Construction opened a new office in Utah and received two top-project awards.
- In November 2023, Schneider Electric expanded its partnership with Compass Datacenters with a $3 billion multi-year data center technology agreement.
Market Concentration & Characteristics
The Canada Data Centre Construction Market exhibits moderate market concentration, with a few key players holding significant shares. Companies such as DPR Construction, Schneider Electric SE, Fortis Construction Inc., and Turner Construction Co. dominate the market due to their extensive experience, advanced technological capabilities, and comprehensive service offerings. These leading firms benefit from high entry barriers, including substantial capital investment, regulatory compliance, and the need for specialized construction and engineering expertise. The market is characterized by a strong emphasis on sustainability, with a growing focus on integrating renewable energy sources and implementing energy-efficient cooling solutions. Additionally, the market is driven by the increasing demand for scalable and resilient data center infrastructure to support the expanding needs of cloud services, data storage, and processing. This focus on quality, reliability, and sustainability ensures that the dominant players maintain their competitive advantage, meeting the evolving demands of businesses and government agencies in Canada’s rapidly advancing digital economy.
Report Coverage
The research report offers an in-depth analysis based on Type, Infrastructure, Vertical and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Canada data centre construction market is expected to grow significantly due to increasing demand for cloud services and digital infrastructure.
- Government initiatives focusing on data sovereignty and digital transformation will continue to drive investments in local data centre facilities.
- There will be a rising emphasis on sustainability, with data centres increasingly adopting renewable energy sources and energy-efficient technologies.
- The market will see increased investments in hyper-scale data centres to meet the growing demand for large-scale data storage and processing.
- Edge computing will gain prominence, leading to the development of smaller, localized data centres closer to end-users to reduce latency.
- Modular data centres will become more popular due to their scalability, flexibility, and faster deployment times.
- Enhanced connectivity through investments in submarine cables and fiber optic networks will make Canada an attractive destination for global data centre investments.
- The competition is likely to intensify, with both domestic and international players expanding their presence in the Canadian market.
- Talent shortages in specialized areas such as IT infrastructure and engineering will remain a challenge, emphasizing the need for workforce development.
- Continuous innovation and strategic partnerships will be crucial for companies to maintain their competitive edge and meet the evolving demands of the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Canada Data Centre Construction Market?
What factors are driving the growth of the Canada Data Centre Construction Market?
What are the key segments within the Canada Data Centre Construction Market?
Who are the major players in the Canada Data Centre Construction Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Canada Data Centre Construction Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Canada Data Centre Construction Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 6,988.39 million → 2032: USD 11,663.65 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Canada Data Centre Construction Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Canada Data Centre Construction Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Canada Data Centre Construction Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Canada Data Centre Construction Market Drivers
- 3.3 Canada Data Centre Construction Market Restraints & Challenges
- 3.4 Canada Data Centre Construction Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Canada Data Centre Construction Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Canada Data Centre Construction Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Canada Data Centre Construction category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Canada Data Centre Construction Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Canada Data Centre Construction Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Canada Data Centre Construction market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Canada Data Centre Construction Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Canada Data Centre Construction Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Canada Data Centre Construction Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Canada Data Centre Construction (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Canada Data Centre Construction Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Canada Data Centre Construction Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Canada Data Centre Construction Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Canada Data Centre Construction Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Canada Data Centre Construction Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Canada Data Centre Construction Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Canada Data Centre Construction Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Canada Data Centre Construction Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Canada Data Centre Construction Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
