
Winter rules and a large vehicle fleet drive tire buying
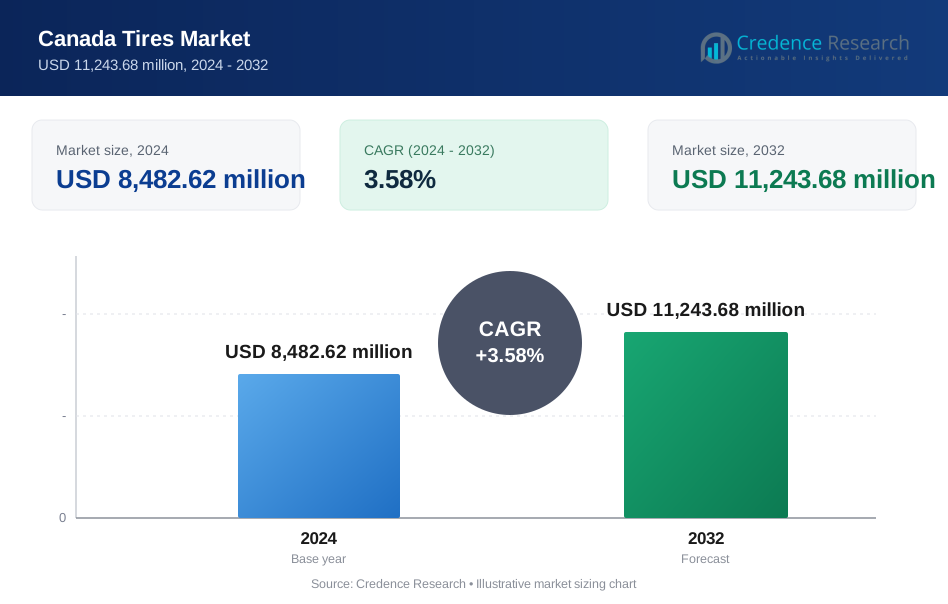
The Canada tire market was valued at USD 8.79 billion in 2025 and is projected to increase from USD 9.10 billion in 2026 to USD 12.49 billion by 2035, registering a CAGR of 3.58% during 2026–2035. Demand comes mostly from the replacement needs of a large light vehicle fleet, from provincial winter tire rules and from freight fleets that wear out truck tires on long highway routes. Ontario held the largest regional share, 35.0% in 2025, because the province registers more light-duty vehicles than any other. The Prairie Provinces are the fastest-growing region at 4.0% a year, as winter tire use in Alberta, Manitoba and Saskatchewan keeps climbing from a lower base. The main commercial change is product mix, because buyers are moving from all-season tires toward all-weather tires and larger fitments for SUVs and pickups. Local supply is also changing, as Goodyear, Bridgestone and Michelin modernize their Canadian plants for electric vehicle and larger-rim tires.
How large is the Canadian tire industry and who buys tires?
The report counts the value of new passenger car, light truck, truck and bus, motorcycle and specialty tires sold in Canada, both as replacement tires and as original fitment on vehicles built in the country. Statistics Canada counted 26.8 million road motor vehicles registered in 2024, and the Tire and Rubber Association of Canada found that 80% of drivers fitted winter tires in 2025. Buyers purchase through national retailers, independent dealers, car dealerships, wholesale distributors and online stores.
Retreaded casings, used tires, tubes, wheels and installation labor are excluded from the market value. The value chain runs from three domestic tire makers, Michelin in Nova Scotia, Bridgestone in Joliette, Quebec and Goodyear in Napanee, Ontario and from importers, through distributors to retail chains such as Canadian Tire, Kal Tire and Fountain Tire that sell and fit tires.
Canada Tire Market Insights
- The market reached USD 8.79 billion in 2025 and should reach USD 12.49 billion by 2035, growing at a 3.58% CAGR during 2026–2035 as the vehicle fleet and premium fitments expand.
- Ontario leads with 35.0% of 2025 value because it held 8.8 million light-duty vehicles in 2024, or 35.9% of the national total.
- Winter tires led seasonality with 41.0% of 2025 value, and the Tire and Rubber Association of Canada found 80% of drivers used them in 2025.
- Goodyear announced a C$575 million Napanee plant expansion on Aug. 13, 2024, to make EV and all-terrain tires by mid-2027.
- The CBSA opened dumping and subsidy investigations into Chinese truck and bus tires on Aug. 31, 2026, after a complaint by Michelin and retreaders.
Passenger car and winter tires hold the largest shares
Why do passenger car tires take most of the value?
Based on vehicle type, the market is categorized into passenger car tires, light truck tires, truck and bus tires, and motorcycle and other tires. Passenger Car Tires led with 62.0% of 2025 value because cars, crossovers and minivans make up most of the fleet, and Statistics Canada counted 10.3 million multipurpose vehicles among 24.6 million light-duty vehicles in 2024. Light Truck Tires grow fastest at 4.5% a year, as Statistics Canada reported that light truck sales rose 3.7% in 2025 while passenger car sales fell 5.2%, which moves buyers toward larger and more expensive fitments.
Why do winter tires lead and all-weather tires grow fastest?
Based on tire seasonality, the market is categorized into winter tires, all-season tires, all-weather tires and summer tires. Winter Tires led with 41.0% of 2025 value because many drivers keep a second set for the cold months, and a Bridgestone product manager told Autosphere that winter tires made up about 42% of Canadian tire sales in 2025. All-Weather Tires grow fastest at 5.8% a year, as the same estimate put all-weather tires at about 22% of sales against 35% for all-season tires, with the category expanding steadily since 2017.
Why do retailers and dealers sell most tires?
Based on distribution channel, the market is categorized into tire retailers and dealers, wholesale and distributors, and online retail. Tire Retailers and Dealers led with 72.0% of 2025 value because buyers need fitting and seasonal changeovers, and Kal Tire alone runs more than 270 retail and commercial stores across Canada. Canadian Tire Corporation also reported record annual Automotive Service sales in 2025. Online Retail grows fastest at 6.6% a year, as Statistics Canada reported that e-commerce reached 6.1% of total retail trade in December 2025, up from 5.8% in November.
Why does consumer replacement lead while fleets grow faster?
Based on end user, the market is categorized into consumer replacement, commercial fleets and original equipment manufacturer buyers. Consumer Replacement led with 68.0% of 2025 value because private owners replace worn and seasonal tires on a fleet of 24.6 million light-duty vehicles, while Canadian light vehicle assembly fell to about 1.2 million units in 2025, Canadian Auto Dealer reported in March 2026. Commercial Fleets grow fastest at 4.0% a year, as the CBSA put truck and bus tire sales at about C$1.2 billion a year in September 2026 and the complainants in the CBSA case reported a 19.7% rise in imports of Chinese truck and bus tires from 2024 to 2025.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Vehicle Type | Passenger Car Tires | 62.0% | Light Truck Tires | 4.5% |
| By Tire Seasonality | Winter Tires | 41.0% | All-Weather Tires | 5.8% |
| By Distribution Channel | Tire Retailers and Dealers | 72.0% | Online Retail | 6.6% |
| By End User | Consumer Replacement | 68.0% | Commercial Fleets | 4.0% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Vehicle parc, winter rules and SUVs lift replacement sales
A growing vehicle fleet keeps replacement volume high
The size of the vehicle fleet sets the base for replacement demand, because every vehicle on the road needs new tires every few years. Statistics Canada counted 26.8 million road motor vehicles registered in 2024, up 4.2% from 2023, and light-duty vehicles reached 24.6 million. Multipurpose vehicles rose 9.3% to 10.3 million, which raises average tire size and price. New vehicle sales then rose 2.1% to 1,958,582 units in 2025, Statistics Canada reported in March 2026, adding vehicles that will need first replacements later in the decade. As a result, consumer replacement holds 68.0% of 2025 value in the Canada tire market.
Winter tire rules and insurance discounts sustain second sets
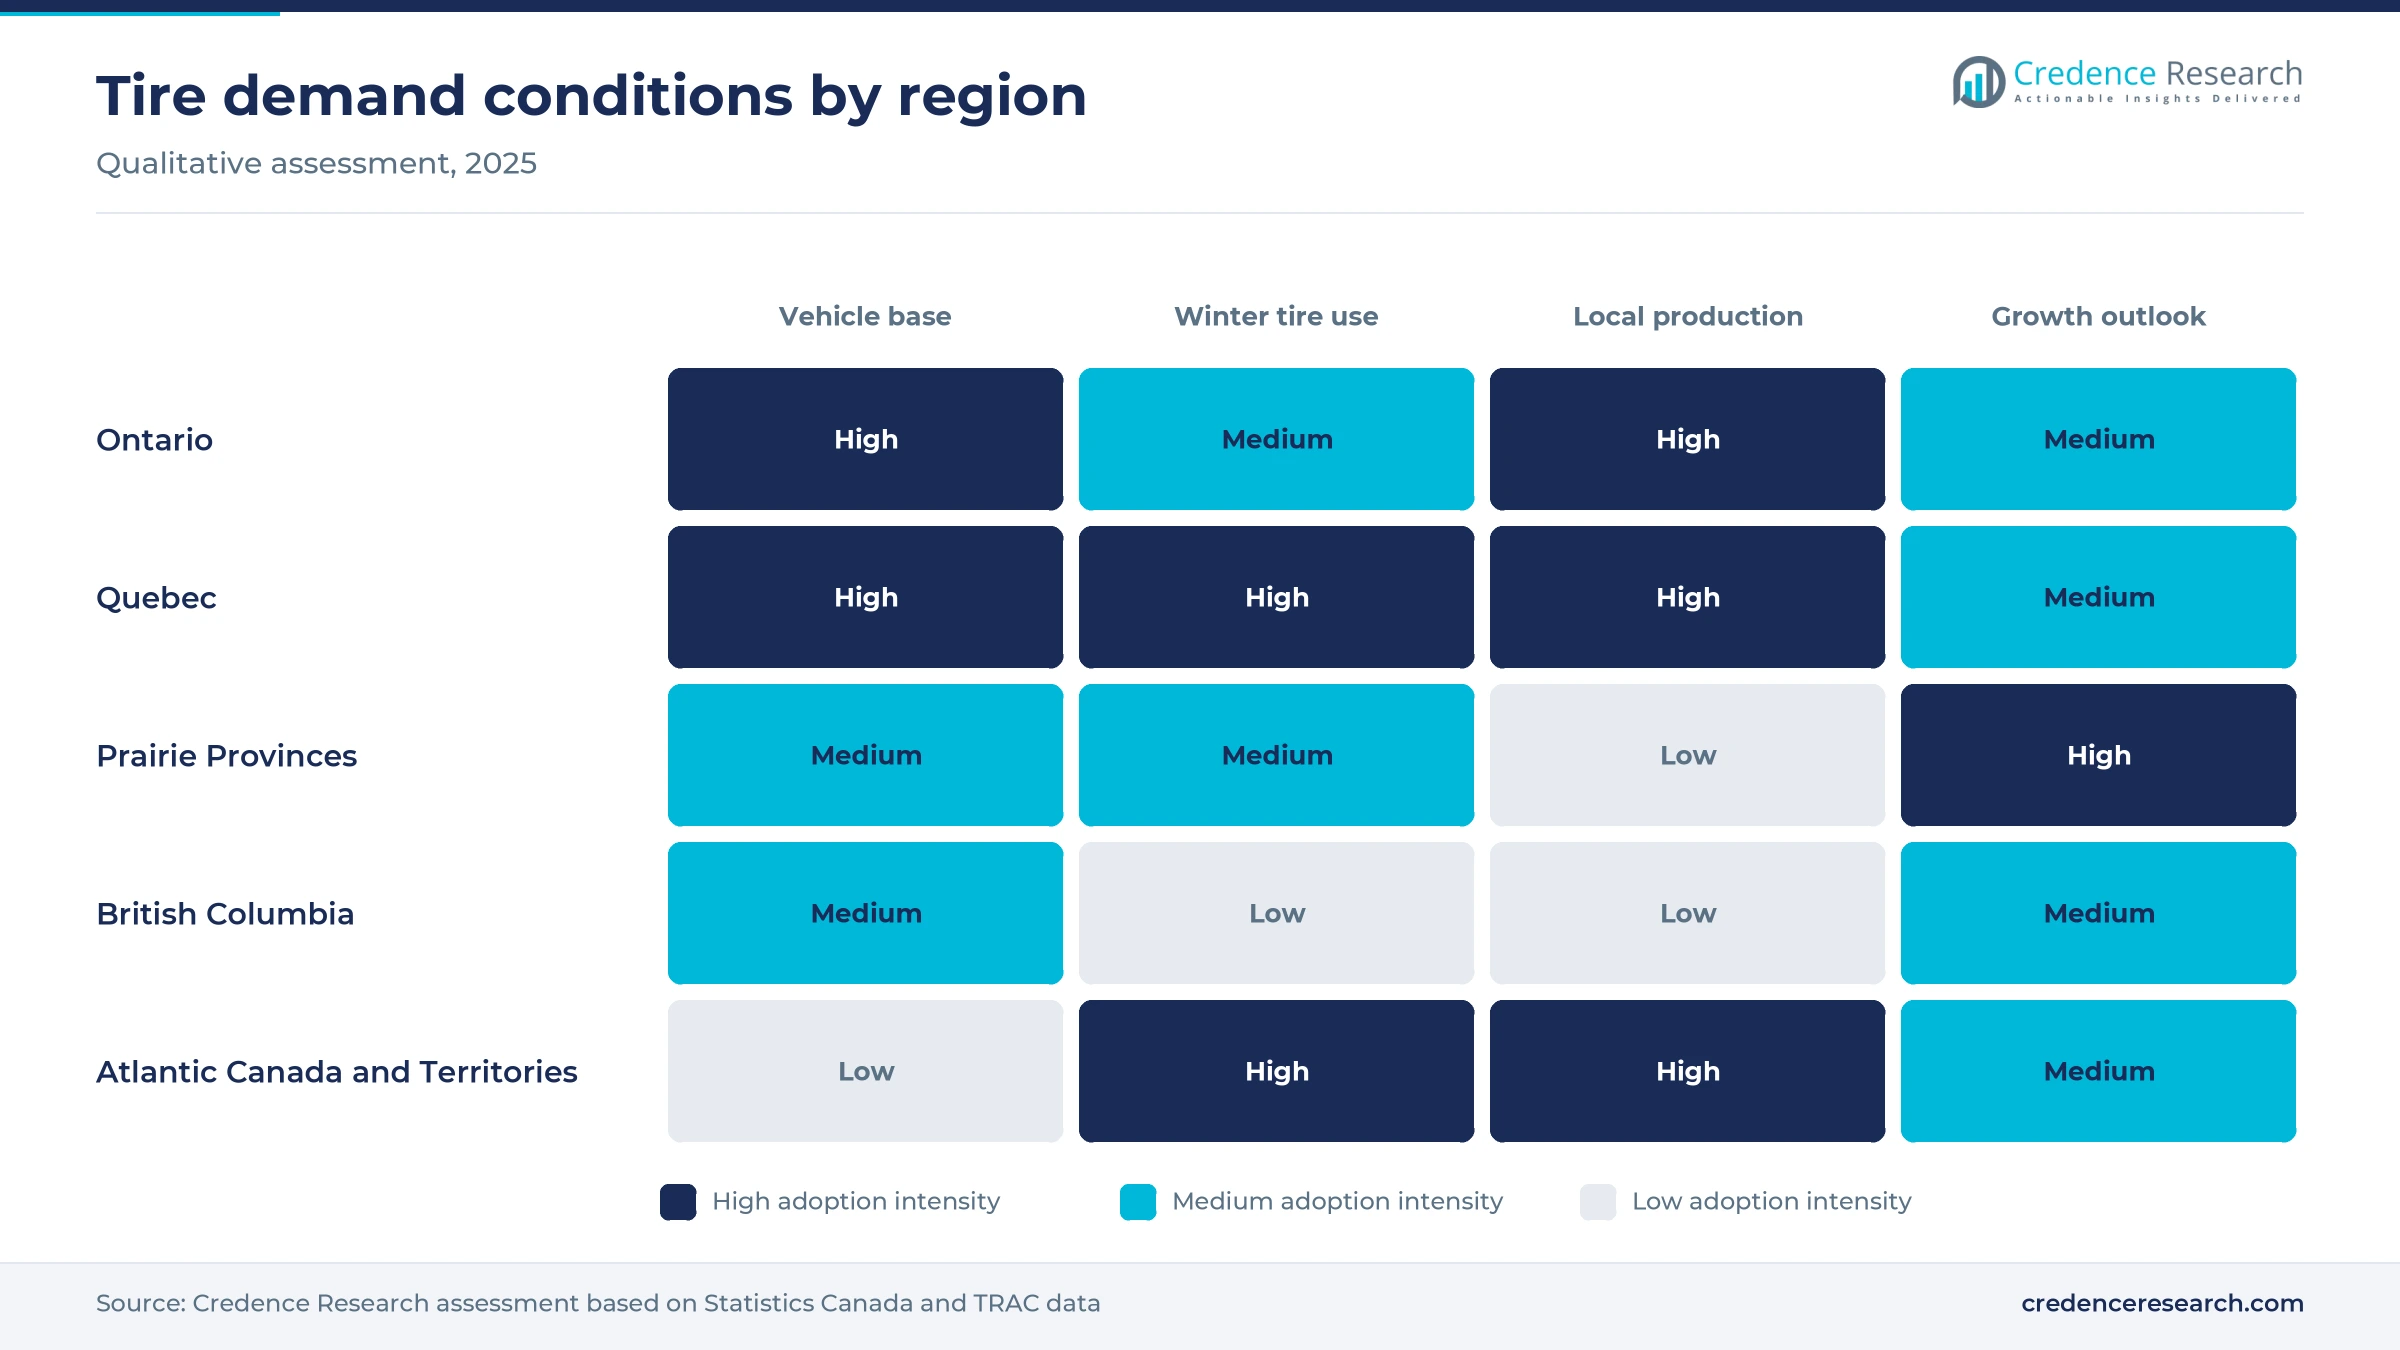
Provincial rules and incentives make a second set of tires a normal purchase for most Canadian drivers. Quebec requires winter tires with the pictogram or studs from Dec. 1 to March 15, with fines of C$200 to C$300, and British Columbia requires winter-rated tires on most highways from Oct. 1 to March 31. Ontario insurers must cut premiums for drivers with four winter tires since Jan. 1, 2016, and Manitoba Public Insurance has processed more than 240,000 winter tire loan applications. In turn, the Tire and Rubber Association of Canada found 80% of drivers used winter tires in 2025, and winter tires lead with 41.0% of 2025 value.
SUVs and pickups push buyers toward larger fitments
The shift toward larger vehicles raises the value of each tire sold, because SUV and pickup sizes cost more than car sizes. Multipurpose vehicles took 62.9% of new registrations in 2024, up from 59.7% in 2023, Statistics Canada reported in March 2025. Light truck sales then rose 3.7% in 2025 while passenger car sales fell 5.2%. Bridgestone is modernizing its Joliette, Quebec, plant with a C$312 million project that lifts output from 17,000 to 20,000 tires a day and adds larger tires for SUVs and vans, according to Investissement Québec. As a result, light truck tires are the fastest-growing vehicle type in this report.
Freight fleets and retread networks support truck tire sales
Freight trucking wears out tires quickly, so fleet replacement cycles give the market a steady commercial base. The CBSA estimated the Canadian market for truck and bus tires at about C$1.2 billion a year in September 2026. Statistics Canada reported that medium-duty vehicle registrations rose almost in step with the light fleet in 2024, while heavy-duty registrations rose 0.8%. Kal Tire, which runs more than 270 stores, says it is the largest Canadian maker of retreaded casings for medium trucks through 16 manufacturing facilities. Fleets buy new premium casings that can be retreaded several times, which keeps new and retreaded supply linked. In turn, commercial fleets grow at 4.0% a year, the fastest end user.
All-weather tires and EV-ready plants reshape the market
Shift from all-season to all-weather tires
All-weather tires, which carry the three-peak mountain snowflake symbol but stay on the vehicle all year, are taking share from all-season tires. A Bridgestone senior product manager told Autosphere that all-weather tires made up about 22% of Canadian tire sales in 2025, against 35% for all-season and 42% for winter tires. Ontario leads total sales of certified products, and certified commercial van tires reached about 8% of that category. American Tire Distributors launched its Hercules Terra Trac Cross-V AW in Canada on April 4, 2024, in 29 sizes from 16 to 22 inches. As a result, all-weather tires grow at 5.8% a year, the fastest season type.
Rise of EV-ready and larger-rim production in Canadian plants
Canadian tire plants are retooling for electric vehicles and larger fitments, which brings more premium supply closer to buyers. Goodyear announced a C$575 million expansion of its Napanee, Ontario, plant on Aug. 13, 2024, to make EV and all-terrain tires by mid-2027, adding 200 jobs for a total of more than 1,000. Michelin began a C$300 million upgrade of its Nova Scotia plants in March 2023 to produce tires for electric vehicles, with up to C$44.3 million from the Strategic Innovation Fund. Battery-electric vehicles on Canadian roads rose 48.33% to 488,612 in 2024, Electric Autonomy reported. In turn, EV replacement tires add value to the passenger car segment.
Opportunity in closing the winter tire gap in the West
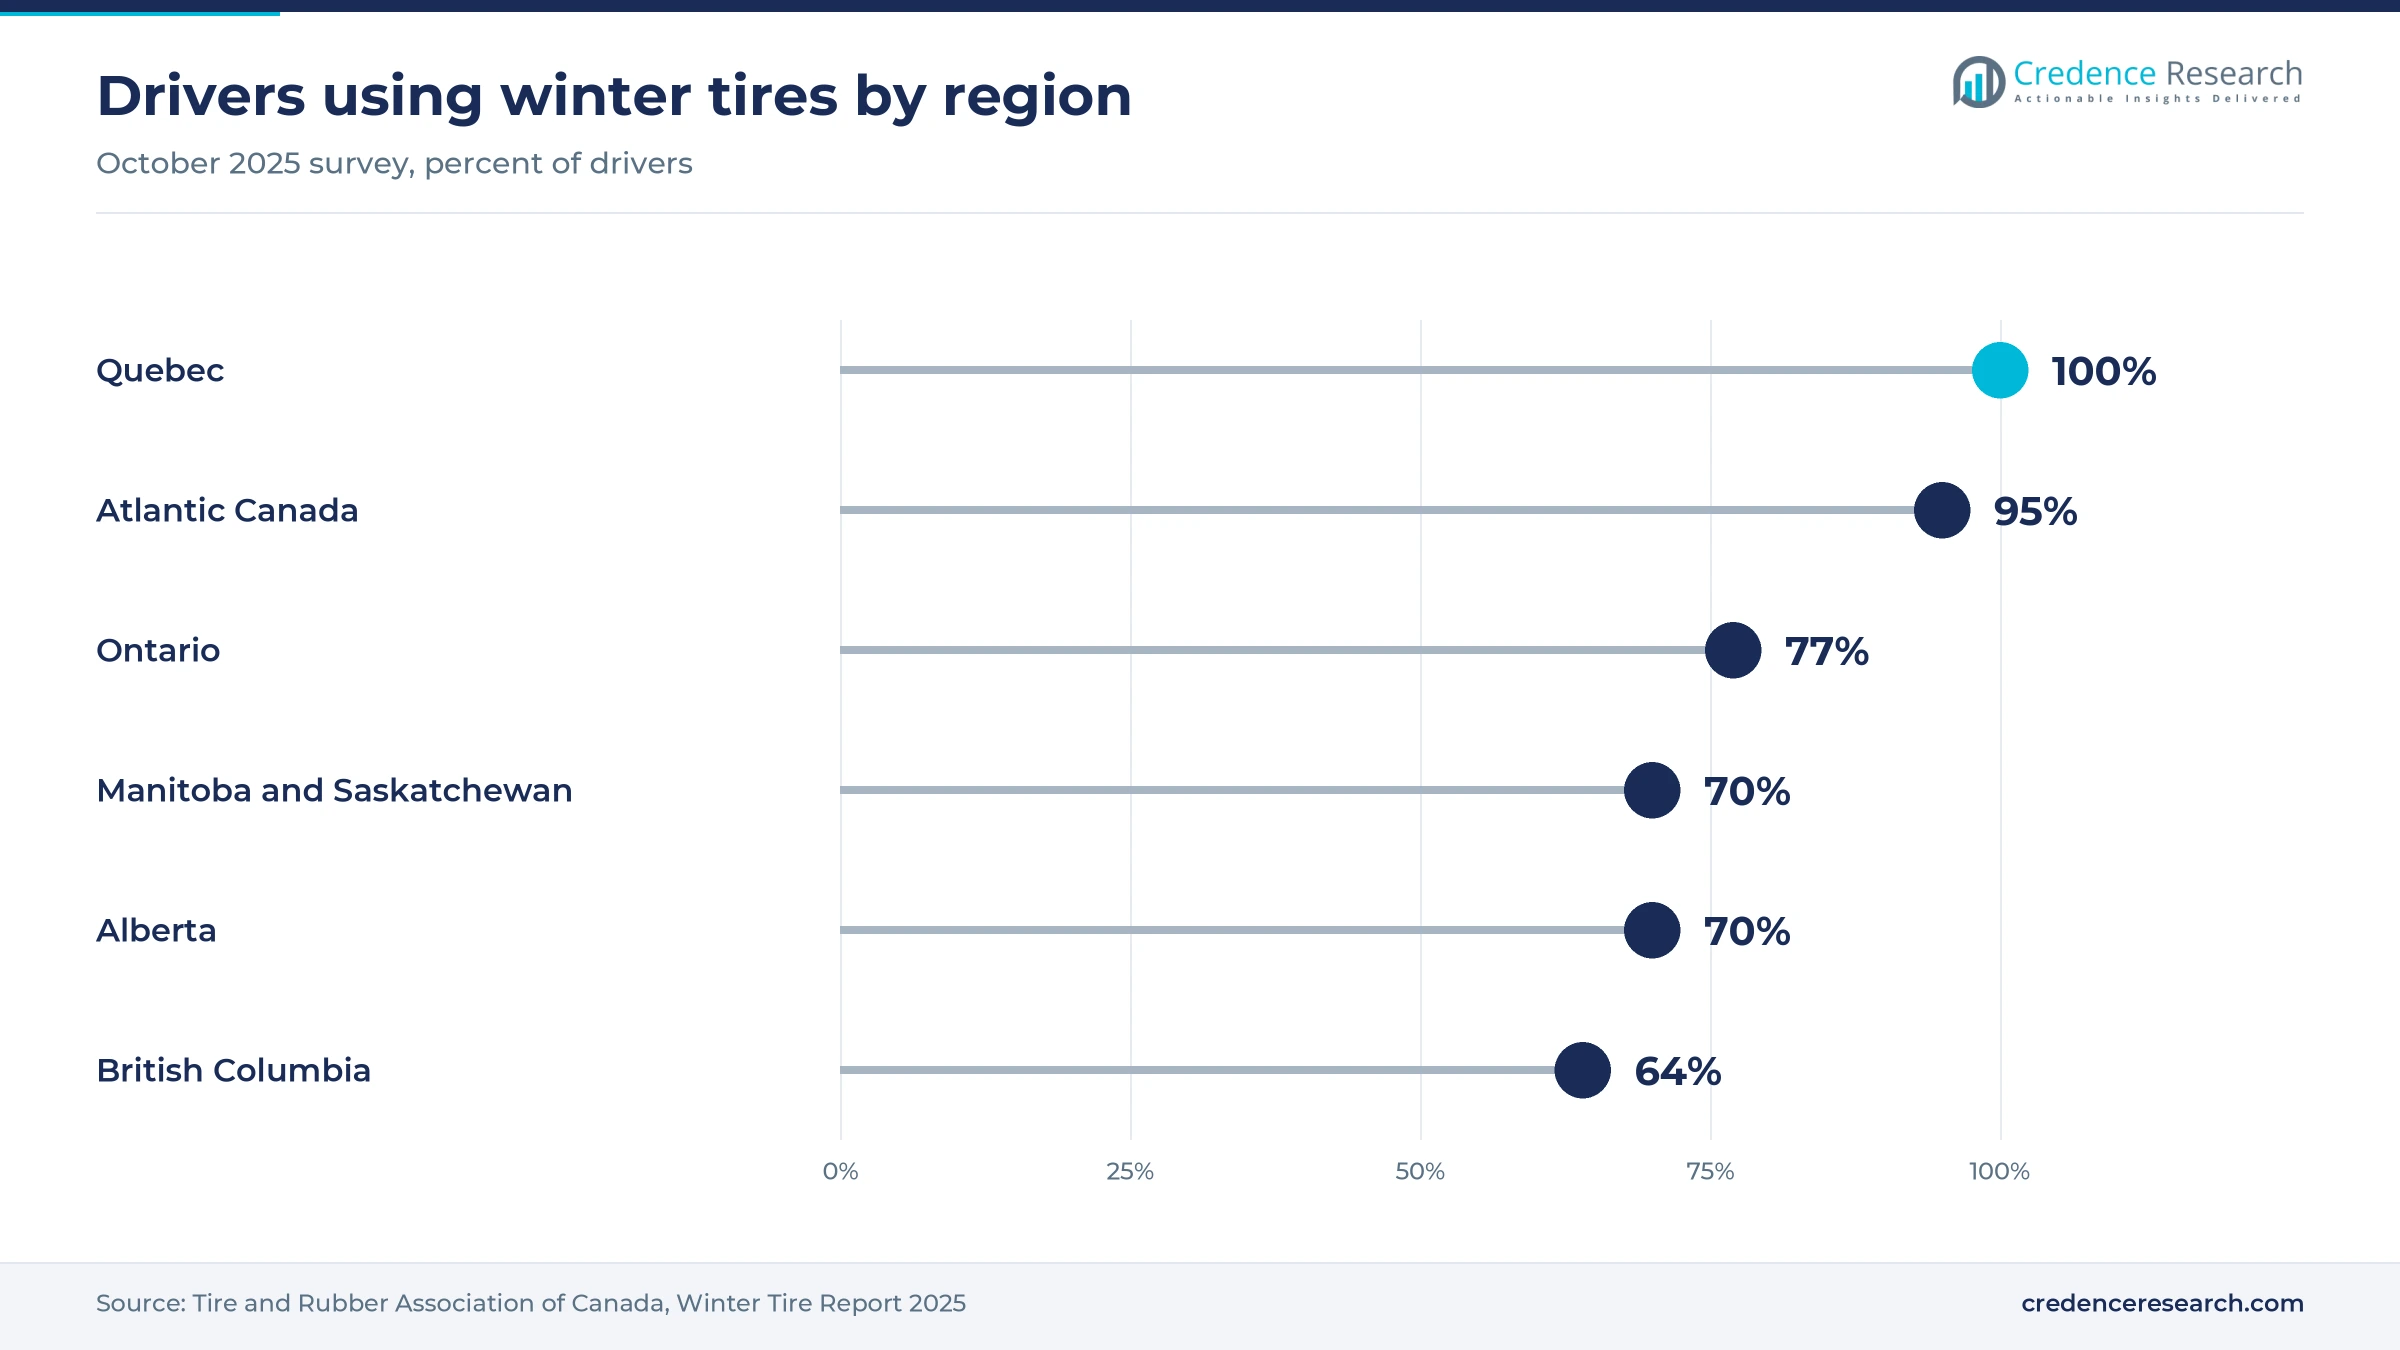
Western provinces offer the clearest volume opening, because winter tire use there still trails Quebec and Atlantic Canada. The Tire and Rubber Association of Canada survey of October 2025 found winter tire use at 64% in British Columbia and 70% in the three Prairie Provinces, against 95% in Atlantic Canada. Among drivers outside Quebec without winter tires, 75% said all-season tires were good enough and 25% said winter tires were too expensive. Another 24% of surveyed drivers cited lower insurance premiums as a reason to buy winter tires. As a result, the Prairie Provinces are the fastest-growing region in this report, and retailers that offer financing or storage can win new buyers.
Opportunity in online booking and loyalty-linked tire sales
Digital shopping is a growing opening for retailers that combine online ordering with in-store fitting and seasonal storage. Canadian e-commerce sales reached C$50.77 billion in 2025, or 6.1% of retail trade, according to Statistics Canada data published by the Nova Scotia Department of Finance and Treasury Board. Canadian Tire Corporation reported 9.8 million active Triangle Rewards members in February 2026, up 6% from 2024, and it completed 52 store projects in 2025. Its retail automotive sales also rose for a 22nd consecutive quarter at the end of 2025. As a result, online retail grows at 6.6% a year, the fastest channel in this report.
Rubber costs, cheap imports and recycling strain suppliers
Higher natural rubber prices lift production costs
Natural rubber is a main input, and its price rose sharply after 2023. The World Bank put TSR20 rubber at USD 1.38 per kg in 2023 and USD 1.75 in 2024, an increase of about 27%, with USD 1.77 forecast for 2025. Tire makers in Nova Scotia, Quebec and Ontario absorb these costs or pass them to buyers. However, the Tire and Rubber Association of Canada found 32% of drivers less likely to buy winter tires in 2025 because of affordability.
Low-priced imports pressure Canadian truck tire makers
Low-priced imports cut prices for domestic producers and retreaders in Canada. The CBSA launched dumping and subsidy investigations into Chinese truck and bus tires on Aug. 31, 2026, after complaints from Michelin and the Canadian Retread Manufacturers Association. In its statement of reasons, the CBSA estimated a 29.1% dumping margin and put China's share of truck and bus tire imports at 44.6% in 2025. Nova Scotia also reported in February 2025 that passenger and light truck tire imports from China, Cambodia and Vietnam rose nearly 30% from 2022 to 2024.
Cross-border tariffs add risk for exporters and importers
Trade tension with the United States adds cost risk on both sides of the border, because Canadian plants export many of their tires south. CBC News reported that Canada placed tires on its 2025 list of U.S. goods facing a 25% counter-tariff, which raised import costs for some brands. Nova Scotia shipped about C$1.2 billion of tires to the United States in 2023, CBC also reported. As a result, Canadian plants depend on demand in the U.S. replacement market while retailers adjust their sourcing.
Ontario recycling changes disrupt used tire collection
Recycling rules add cost and handling problems for dealers, because every new tire sold creates a used one to collect. Truck News reported on March 16, 2026, that Ontario cut the required recovery rate from 85% to 65%, while volumes at eTracks ran 43% above normal seasonal levels. Buyers still pay fees of about C$5 per passenger tire and C$15 per semi-truck tire. As a result, some dealers faced full storage before the spring changeover season, since a typical dealership can safely hold only 100 to 150 tires.
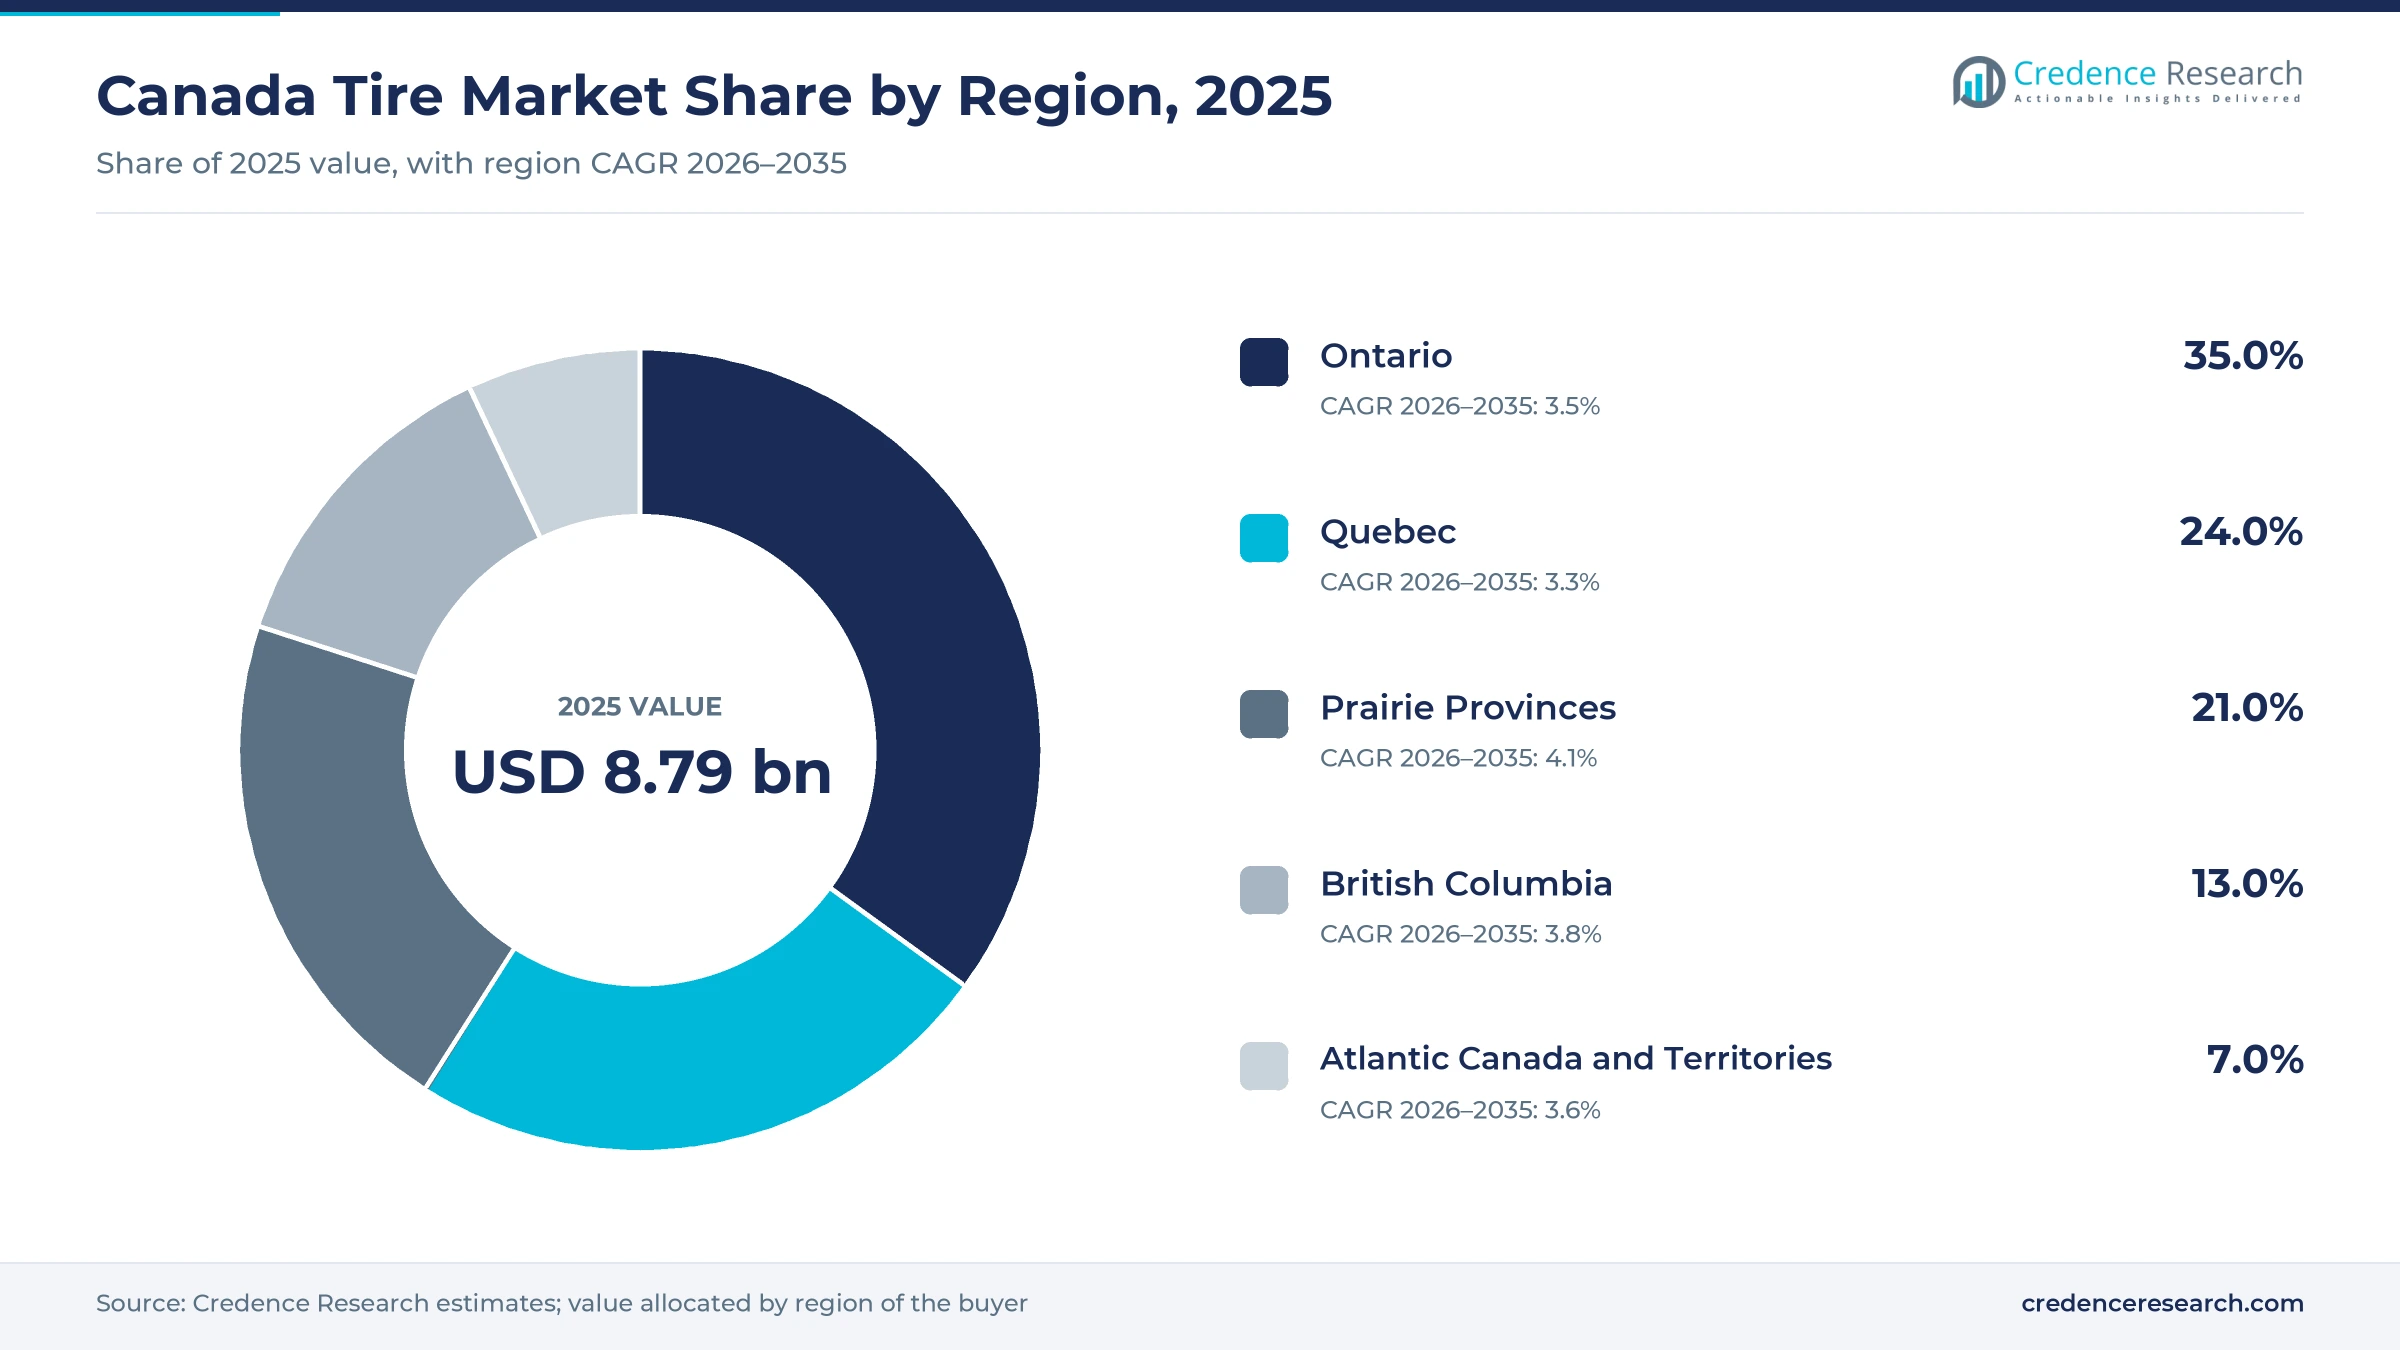
Ontario leads as the Prairie Provinces grow fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Ontario | 3.08 | 35.0% | 3.5% |
| Quebec | 2.11 | 24.0% | 3.2% |
| Prairie Provinces | 1.85 | 21.0% | 4.0% |
| British Columbia | 1.14 | 13.0% | 3.8% |
| Atlantic Canada and Territories | 0.62 | 7.0% | 3.5% |
Ontario has the largest vehicle fleet and a new EV tire line
Ontario held 35.0% of 2025 value and grows at 3.5% a year. The province held 8.8 million light-duty vehicles in 2024, or 35.9% of the national total, and registered 699,289 new vehicles that year, according to Statistics Canada. Winter tire use rose to 77% in 2025 from 67% in 2023, helped by insurance discounts that have applied since 2016. Goodyear's Napanee expansion adds local supply of EV and all-terrain tires by mid-2027.
Quebec winter rules make every driver a seasonal buyer
Quebec held 24.0% of 2025 value and grows at 3.2% a year. The province has required winter tires since 2008, so winter tire use stays at 100% from Dec. 1 to March 15. Quebec registered 477,761 new vehicles in 2024, of which 30.9% were zero-emission vehicles, Statistics Canada reported. Bridgestone employs about 1,300 people at its Joliette plant, which makes passenger and light truck tires and is moving to 20,000 tires a day after its modernization.
Prairie Provinces grow fastest as winter tire use climbs
The Prairie Provinces held 21.0% of 2025 value and grow fastest at 4.0% a year. Winter tire use in Alberta rose from 56% in 2022 to 70% in 2025, matching Manitoba and Saskatchewan, the Tire and Rubber Association of Canada found. Manitoba Public Insurance has lent up to C$2,000 per vehicle for winter tires since 2014. Edmonton-based Fountain Tire supports the commercial market as a member of the Canadian Retread Manufacturers Association.
British Columbia has highway rules but the lowest winter tire use
British Columbia held 13.0% of 2025 value and grows at 3.8% a year. Most provincial highways require winter-rated tires from Oct. 1 to March 31, yet winter tire use fell to 64% in 2025 from 68% in 2024. The province registered 219,177 new vehicles in 2024, and 20.9% were zero-emission vehicles. Vernon-based Kal Tire, founded in 1953, runs its national store and retread network from the province.
Atlantic Canada and Territories anchor domestic tire making
Atlantic Canada and Territories held 7.0% of 2025 value and grow at 3.5% a year. Winter tire use reached 95% in Atlantic Canada in 2025, up from 85% in 2024. Michelin runs three Nova Scotia plants in Bridgewater, Pictou County and Waterville, and the Bridgewater plant can make 7,500 tires a day, CBC News reported. Newfoundland and Labrador insurers have discounted premiums for winter tires since Jan. 1, 2020.
Plant expansions and a truck tire trade case since 2024
| Development | Status and market relevance |
|---|---|
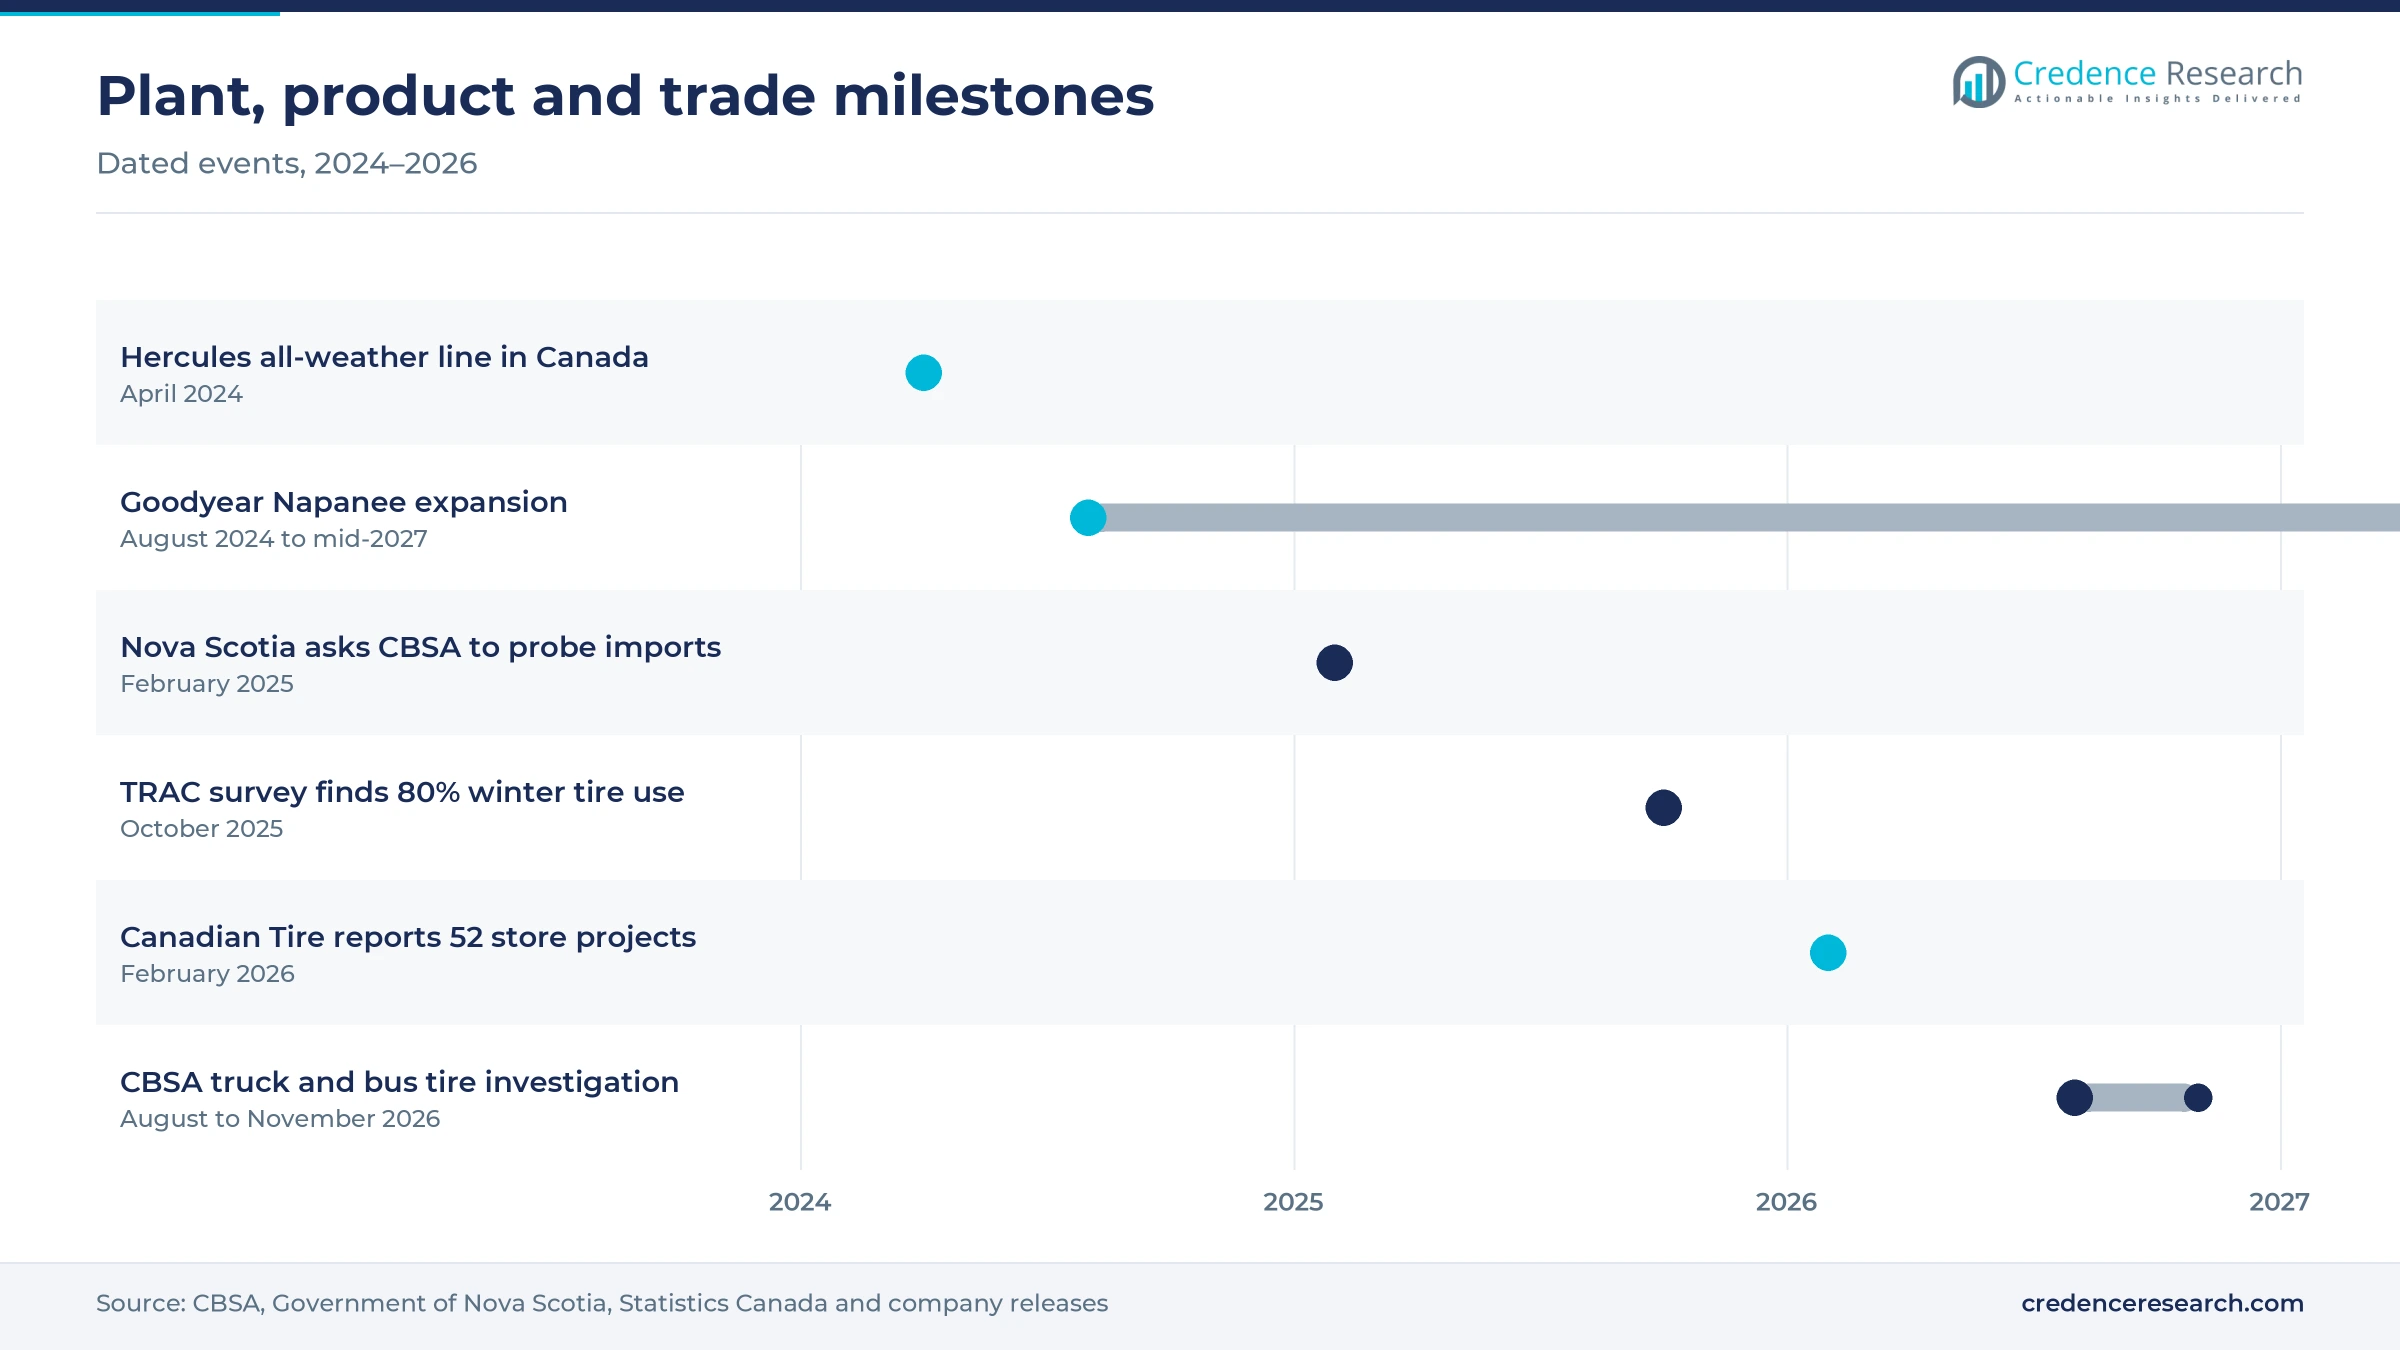
| In April 2024, American Tire Distributors launched the Hercules Terra Trac Cross-V AW all-weather tire in Canada in 29 sizes. | Adds a certified all-weather option for crossovers and light trucks |
| In August 2024, Goodyear announced a C$575 million expansion of its Napanee, Ontario, plant for EV and all-terrain tires. | Due by mid-2027, with 200 new jobs |
| In February 2025, Nova Scotia asked the CBSA to investigate passenger and light truck tire imports from China, Cambodia and Vietnam. | Imports rose nearly 30% from 2022 to 2024 |
| In February 2026, Canadian Tire Corporation reported 52 store projects completed in 2025 and record Automotive Service sales. | Widens retail fitting capacity |
| In August 2026, the CBSA opened dumping and subsidy investigations into truck and bus tires from China. | Preliminary decision due by Nov. 30, 2026 |
Snowflake ratings, EV compounds and automated tire lines
- The three-peak mountain snowflake symbol marks tires that meet a severe snow test, and Quebec accepts tires with the pictogram or studs as legal winter tires.
- EV tire compounds and constructions carry the extra weight and torque of battery vehicles, and Goodyear is adding such lines in Napanee by mid-2027.
- Automated building equipment lets Bridgestone lift Joliette output from 17,000 to 20,000 tires a day while adding larger SUV sizes.
- Truck tire retreading gives fleet casings more than one life, and Kal Tire runs 16 retread facilities for medium truck tires.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Three local makers compete with national retail chains
Competition splits into three domestic manufacturers, importers of global brands and national retail and service chains. Michelin is the only maker of new truck and bus tires in Canada, according to the complainants in the CBSA case, and runs three Nova Scotia plants that are being upgraded to make tires for electric vehicles. Goodyear competes from Napanee, Ontario and is adding EV and all-terrain lines, while Bridgestone makes passenger and light truck tires in Joliette, Quebec. On the retail side, Canadian Tire Corporation operates nearly 1,700 retail and gasoline outlets and reported record Automotive Service sales in 2025. Kal Tire and Fountain Tire compete in commercial service, retreading and heavy-duty casings for fleets and mines. Continental, Hankook and Nokian Tyres sell imported global brands through Canadian subsidiaries, and Nokian leans on its Hakkapeliitta winter range. Firms compete on winter range, price tiers, store reach and seasonal storage services. Michelin alone employs about 4,000 direct workers in Nova Scotia, which makes it the largest domestic supplier in the Canada tire market.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Michelin North America (Canada) Inc. | Domestic manufacturer | Three Nova Scotia plants, main Canadian maker of new truck and bus tires |
| The Goodyear Tire & Rubber Company | Domestic manufacturer | Napanee, Ontario, plant expanding for EV and all-terrain tires by mid-2027 |
| Bridgestone Canada Inc. | Domestic manufacturer | Joliette, Quebec, plant moving from 17,000 to 20,000 tires a day |
| Continental Tire Canada | Global brand importer | Continental passenger, light truck and commercial tires sold through Canadian dealers |
| Hankook Tire Canada Corp. | Global brand importer | Passenger, SUV, light truck and EV tires from a Canadian headquarters and warehouse |
| Nokian Tyres | Winter tire specialist | Hakkapeliitta winter tires and the Nokian One all-season tire sold across Canada |
| Canadian Tire Corporation | National retailer | Nearly 1,700 retail and gasoline outlets with automotive service |
| Kal Tire | Dealer and retreader | More than 270 stores and 16 retread facilities |
| Fountain Tire | Dealer and retreader | Edmonton-based dealer, Canadian Retread Manufacturers Association member |
Mix, not volume, will decide value growth to 2035
Credence Research's view is that product mix, not unit volume, will decide value growth in the Canada tire market to 2035. The fleet still grows, with 26.8 million registered vehicles in 2024, but vehicle assembly is shrinking and car sales are falling. Growth therefore comes from larger SUV and pickup fitments, all-weather tires and winter tire uptake in the West. Domestic plants in Nova Scotia, Quebec and Ontario are retooling for these products. The main risks are rubber prices, cheap imports and trade tension with the United States.
How Credence Research sized the market
The report uses 2025 as the base year and forecasts to 2035, with growth rates for 2026 to 2035. Market values come from the Credence Research model, which starts from the previous edition of this report and checks it against vehicle registrations, new vehicle sales, trade case data and winter tire use. Regional, vehicle type, seasonality, channel and end user splits are Credence Research estimates. Sources include Statistics Canada, the CBSA, provincial governments, the World Bank, the Tire and Rubber Association of Canada, company releases and news reports. No interviews or surveys were conducted for this edition of the report.
All-weather tires and light trucks gain share to 2035
The market should grow steadily to 2035, with all-weather tires, light truck tires and online sales growing faster than the total. Goodyear's Napanee lines are due by mid-2027, and Bridgestone's Joliette upgrade adds larger SUV sizes, which keeps more premium supply in the country. The CBSA truck tire case will shape import prices for fleets from late 2026. The Prairie Provinces gain share as winter tire use rises. Light truck tires should grow at 4.5% a year in the Canada tire market as pickups and SUVs gain share. By 2035, the market should reach USD 12.49 billion, with Ontario still the largest region.
Frequently Asked Questions
How big is the Canada tire market?
What share of tire sales in Canada are winter tires?
How many vehicles in Canada need tires?
When are winter tires mandatory in Canada?
Which companies make tires in Canada?
How large is the Canadian Tire retail network?
Why is Canada investigating truck tire imports from China?
Which region leads the Canada tire market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Vehicle Type
- 1.2.1 Passenger Car Tires
- 1.2.2 Light Truck Tires
- 1.2.3 Truck and Bus Tires
- 1.2.4 Motorcycle and Other Tires
- 1.3 By Tire Seasonality
- 1.3.1 Winter Tires
- 1.3.2 All-Season Tires
- 1.3.3 All-Weather Tires
- 1.3.4 Summer Tires
- 1.4 By End User
- 1.4.1 Consumer Replacement
- 1.4.2 Commercial Fleets
- 1.4.3 Original Equipment Manufacturer
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 8.79 billion → 2035: USD 12.49 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Canada Tire Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Canada Tire Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Canada Tire Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Canada Tire Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Canada Tire Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Canada Tire Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Canada Tire Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Canada Tire Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 8.79 billion → 2035: USD 12.49 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Canada Tire Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Vehicle Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Passenger Car Tires
- 12.3.7.2 Light Truck Tires
- 12.3.7.3 Truck and Bus Tires
- 12.3.7.4 Motorcycle and Other Tires
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Tire Seasonality - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Winter Tires
- 12.4.7.2 All-Season Tires
- 12.4.7.3 All-Weather Tires
- 12.4.7.4 Summer Tires
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End User - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Consumer Replacement
- 12.5.7.2 Commercial Fleets
- 12.5.7.3 Original Equipment Manufacturer
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Canada Tire End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Canada Tire Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Canada Tire Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Canada Tire Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Michelin North America (Canada) Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 The Goodyear Tire & Rubber Company
- 18.4 Bridgestone Canada Inc.
- 18.5 Continental Tire Canada
- 18.6 Hankook Tire Canada Corp.
- 18.7 Nokian Tyres
- 18.8 Canadian Tire Corporation
- 18.9 Kal Tire
- 18.10 Fountain Tire
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

