
Market Overview
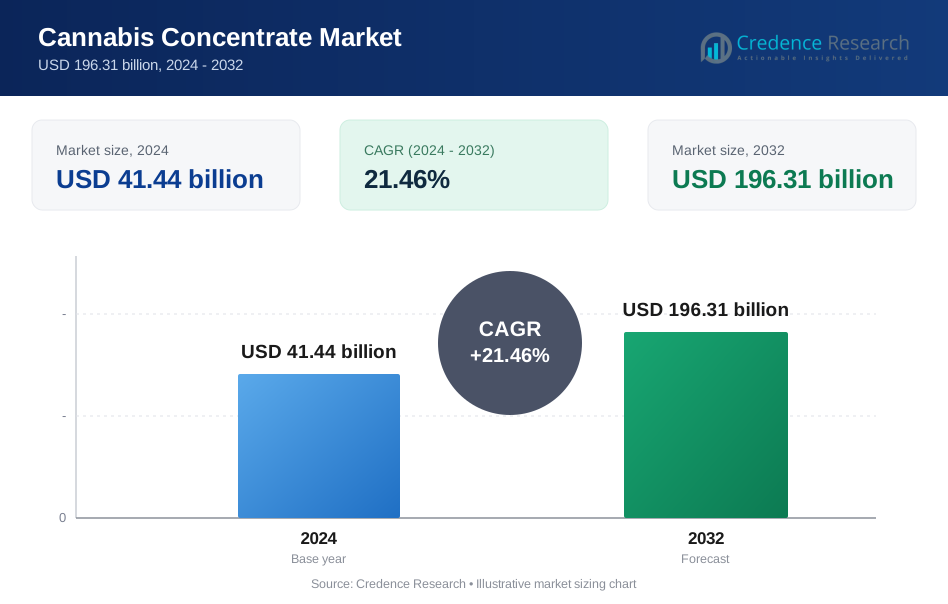
Cannabis Concentrate Market size was valued USD 41.44 billion in 2024 and is anticipated to reach USD 196.31 billion by 2032, at a CAGR of 21.46% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cannabis Concentrate Market Size 2024 | USD 41.44 Billion |
| Cannabis Concentrate Market, CAGR | 21.46% |
| Cannabis Concentrate Market Size 2032 | USD 196.31 Billion |
The cannabis concentrate market is dominated by several key players, including Archer Daniels Midland, Lemon Concentrate, S.L., Sunopata Inc., Kerr Concentrates, Inc., China Haiseng Juice Holdings Co., Ltd, Dohler GmBH, Skypeople Fruit Juice Inc., Agrana Beteiligungs Ag, Royal Cosun, and Rudolf Wild GmBH & Co. Kg. These companies compete through product innovation, advanced extraction technologies, and expansion into emerging markets. They focus on offering high-potency, safe, and clean concentrates to meet the growing medical and recreational demand. North America remains the leading region in the market, accounting for approximately 42% of global share. Strong legalization frameworks, mature distribution networks, and high consumer adoption in the U.S. and Canada contribute to this dominant position. The combination of innovation, regulatory compliance, and strategic partnerships enables these companies to maintain a competitive edge in this fast-growing and dynamic market.
Market Insights
- The cannabis concentrate market was valued at USD 41.44 billion in 2024 and is projected to reach USD 196.31 billion by 2032, growing at a CAGR of 21.46% during the forecast period.
- Key drivers include rising legalization of medical and recreational cannabis, increasing consumer preference for high-potency products, and growing demand for precise and convenient consumption formats like oils, waxes, and vape cartridges.
- Market trends show a focus on product innovation, clean extraction technologies, and the development of diverse formats, including edibles, tinctures, and minor cannabinoid concentrates, to cater to evolving consumer preferences.
- The market is competitive, with leading players emphasizing strategic partnerships, mergers, acquisitions, and expansion into emerging regions to strengthen their position, while regulatory compliance and quality assurance remain critical.
- Regionally, North America leads with approximately 42% share, followed by Europe and Asia-Pacific, while concentrates dominate over other product segments due to higher potency, convenience, and medical adoption.
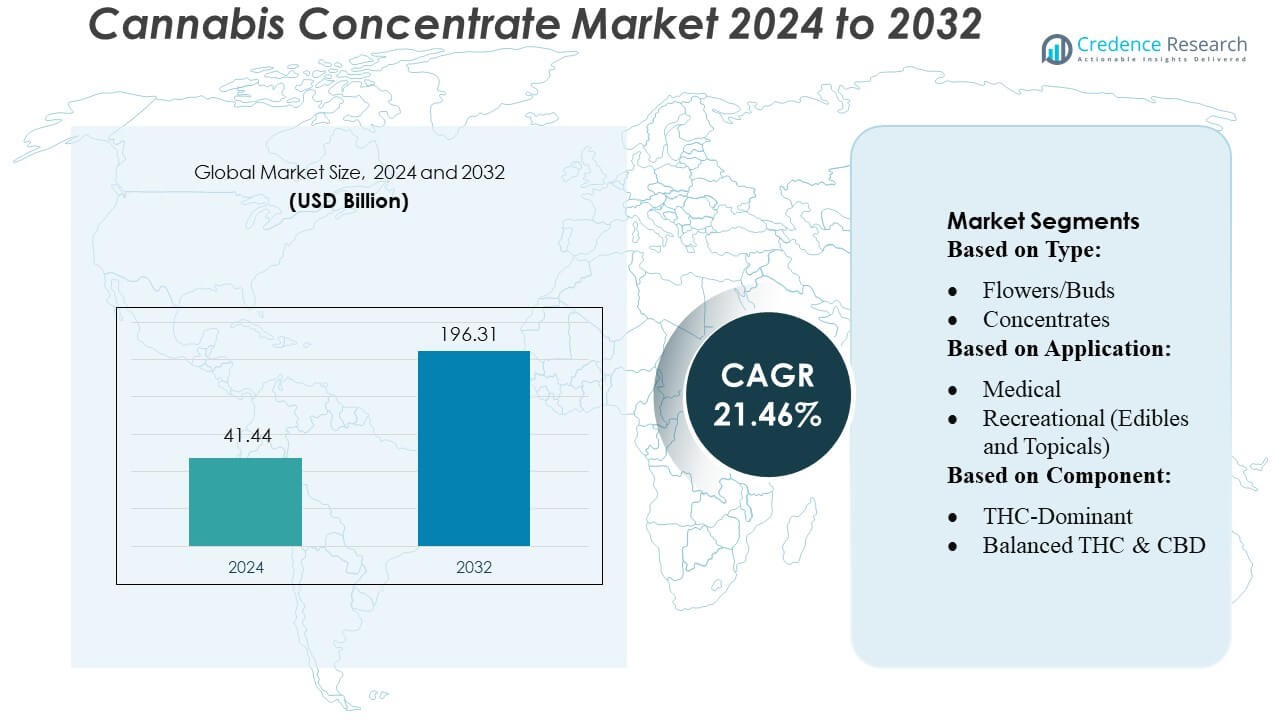
Market Segmentation Analysis:
By Type
The market segment by type remains dominated by the Flowers/Buds sub‑segment. Traditional flower products continue to command the largest share due to consumer familiarity, ease of use, and broad availability despite the growing interest in extracts. Concentrates hold a substantial minority share, driven by their higher potency, fast‑acting effects, and variety of concentrate formats (e.g., oils, waxes, shatter). The rising demand for discreet and potent consumption methods supports growth in the concentrate sub‑segment, though flower remains the backbone of overall cannabis consumption due to user habits and regulatory comfort.
- For instance, Urja Bio System Private Limited, offer industrial food waste crushers and composting machines with capacities reaching up to 1,000 kg/hr, which can reduce waste and enhance efficiency in waste management.
By Application
Within application-based segmentation, the Medical sub‑segment leads the market, reflecting widespread therapeutic use of cannabis concentrates for chronic pain, neurological conditions, and other health needs. Medical use benefits from growing physician support, increasing acceptance of cannabis-based therapies, and regulatory reforms expanding legal access. While recreational consumption (including edibles and topicals) is gaining traction, particularly where adult-use legalization expands, medical demand remains the primary driver-supported by consumer preference for controlled dosing and health-oriented applications. Industrial hemp application, though present, lags behind both medical and recreational demand by a considerable margin.
- For instance, ENCON's product documentation for its MVC evaporators consistently states a typical operating energy cost of $0.01–$0.02 per gallon of distilled water, based on an assumed electricity cost.
By Component
Among active‑constituent profiles, the THC‑Dominant sub‑segment remains dominant, reflecting consumer demand for higher potency products, especially in recreational markets. THC‑rich concentrates provide stronger psychoactive effects and satisfy preference for intensity, which fuels their popularity. Meanwhile, Balanced THC & CBD and CBD‑Dominant products are gaining interest among medical and wellness‑oriented users seeking more nuanced therapeutic benefits, but have not yet surpassed THC-dominant variants in overall market share. The demand for high‑potency experiences, combined with regulatory environments that permit THC use, underpins the dominance of the THC‑focused segment.
Key Growth Drivers
- Legalization and Regulatory Support The legalization of cannabis, both for medical and recreational use, is one of the biggest factors driving growth in the cannabis concentrate market. More countries and states are updating their laws to allow legal sale and use, which creates new opportunities for businesses and consumers alike. Legalization also reduces the risks associated with production and distribution, encouraging investment and innovation in the market. Over time, this regulatory support allows more stores, online platforms, and medical dispensaries to sell concentrates, expanding access and increasing overall demand.
- For instance, Pall's Keraflux™ TFF technology enables breweries to recover up to 80% of extract from surplus yeast, reducing waste and allowing beer blending at ratios up to 5% without negatively impacting quality.
- High Potency and Convenient Consumption Cannabis concentrates are much stronger than traditional cannabis flowers, often containing 40–90% or more of active cannabinoids like THC or CBD. This higher potency allows consumers to feel effects faster and use smaller amounts. Concentrates also come in convenient forms such as vape cartridges, oils, waxes, tinctures, and edibles. These formats are easy to use, portable, and discreet, making them attractive to modern consumers who want quick, efficient, and private ways to consume cannabis. The combination of strength and convenience has made concentrates a preferred choice for many users.
- For instance, Evoqua operates in more than 160 locations across ten countries, serving over 38,000 customers worldwide. Their extensive network enables them to provide localized solutions and support for water and wastewater treatment needs globally.
- Medical and Therapeutic Demand There is growing recognition of the medicinal benefits of cannabis for conditions like chronic pain, epilepsy, anxiety, and nausea. Cannabis concentrates are often preferred in medical applications because they allow precise and consistent dosing, which is important for patient safety and treatment effectiveness. Standardized concentrates enable doctors and patients to control how much of a compound like THC or CBD is consumed. As awareness of therapeutic benefits grows, medical patients are increasingly turning to concentrates, helping to expand the market steadily.
Key Trends & Opportunities
- Advanced and Cleaner Extraction Technologies The cannabis concentrate market is benefiting from improvements in extraction technology. Methods like CO₂ extraction, solvent-less techniques, and other modern processes improve product purity, safety, and potency. These technologies also preserve important natural compounds like terpenes, which enhance flavor and effects. As more producers adopt these advanced methods, they can offer higher-quality products that appeal to both medical patients and recreational users, creating opportunities for premium and health-focused product lines.
- For instance, KSS launched the INDU-COR™ HD tubular membrane system, designed for industrial wastewater treatment applications. This system offers a higher packing density of up to 300%, making crossflow filtration more economical while occupying less space.
- Product Innovation and Format Diversification There is a growing trend toward innovative product formats that cater to different consumer preferences. In addition to traditional oils and waxes, companies are offering tinctures, vape cartridges, edibles, sprays, and topical applications. Some products focus on minor cannabinoids or full-spectrum effects, appealing to users looking for specific health benefits or unique experiences. Product innovation allows companies to attract a wider range of consumers, including wellness-focused users, medical patients, and recreational enthusiasts.
- For instance, Emerson's Ovation™ distributed control system was utilized in a UK waste-to-energy plant. The plant processes 320,000 tons of waste annually, producing 28 megawatt-hours of electricity per hour, enough to power approximately 40,000 homes.
- Expansion into Emerging and Global Markets As cannabis laws evolve globally, emerging markets outside North America and Europe are beginning to open up. These regions present significant opportunities for growth, especially for companies with established regulatory knowledge and product experience. Early entry into these markets can help companies gain a strong market presence and capture new consumers, driving overall industry growth. Expanding globally also helps diversify revenue sources and reduce dependence on any single market.
Key Challenges
- Complex and Fragmented Regulations While legalization is expanding, cannabis laws remain inconsistent across regions. Each country, state, or province can have different rules regarding production, testing, labeling, packaging, and distribution. This fragmented regulatory environment increases the cost and complexity of operating in multiple markets. Companies must invest in compliance, licensing, and legal expertise to avoid fines or shutdowns. Navigating these rules is especially challenging for smaller players and can slow down overall market growth.
- Quality, Safety, and Public Perception Issues Ensuring high quality and safe products is critical in the cannabis concentrate market. Variations in extraction methods, plant material, or production standards can lead to inconsistent potency or harmful residues. Safety concerns, particularly with high-potency concentrates or vaping products, have caused negative media attention and public skepticism. Poorly made products can damage trust, hinder adoption by new users, and limit the willingness of regulators to support market expansion. Maintaining consistent quality and safety standards is therefore essential for sustainable growth.
Regional Analysis
North America
North America is the largest market for cannabis concentrates, holding around 40–45% of global share. The U.S. and Canada lead due to established legalization, mature retail networks, and high consumer demand for both medical and recreational products. Clear regulations and strong industry players support steady growth. Consumers prefer high-potency products like oils, waxes, and vape cartridges, while medical use continues to rise. North America remains the most developed and competitive region, attracting significant investment and product innovation in the cannabis concentrate market.
Europe
Europe accounts for roughly 25% of the global market. Medical cannabis is gradually gaining acceptance across countries like Germany, the UK, and the Netherlands. While recreational legalization is limited, evolving regulations and public awareness are driving growth in concentrates. European consumers are increasingly using oils, tinctures, and other convenient formats. Investment in extraction technology and medical-grade products is rising. The market is developing steadily, supported by regulatory approvals and healthcare demand, making Europe a key region for expansion despite slower growth than North America.
Asia-Pacific (APAC)
Asia-Pacific holds about 18% of global market share. Historically smaller than North America and Europe, APAC is growing quickly due to increasing awareness of medical cannabis and evolving regulations in countries like Thailand and South Korea. Demand for concentrates is rising, especially for medicinal and wellness applications. Companies are exploring new markets and products to meet growing consumer interest. With regulatory changes and growing investment, APAC is emerging as an important growth region for cannabis concentrates.
Latin America
Latin America represents around 10% of the global market. Growth is slower but steady, driven mainly by medical cannabis adoption in countries such as Colombia, Chile, and Brazil. Regulatory reforms and consumer interest in cannabis concentrates are gradually increasing. Products like oils, tinctures, and vape cartridges are becoming more available. As laws evolve and acceptance grows, Latin America has potential for market expansion, especially in medical and wellness segments.
Middle East & Africa (MEA)
MEA contributes about 7–8% of the market. Legal restrictions and cultural barriers limit growth, but medical cannabis is slowly gaining acceptance in some countries. Investment and production are emerging, creating early opportunities for cannabis concentrates. Consumers are primarily focused on medical and therapeutic use. While the market is small, gradual regulatory change and increased awareness could help MEA develop into a larger market over time.
Market Segmentations:
By Type:
- Flowers/Buds
- Concentrates
By Application:
- Medical
- Recreational (Edibles and Topicals)
By Component:
- THC-Dominant
- Balanced THC & CBD
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The cannabis concentrate market is highly competitive, with key players including Archer Daniels Midland, Lemon Concentrate, S.L., Sunopata Inc., Kerr Concentrates, Inc., China Haiseng Juice Holdings Co., Ltd, Dohler GmBH, Skypeople Fruit Juice Inc., Agrana Beteiligungs Ag, Royal Cosun, and Rudolf Wild GmBH & Co. Kg. The cannabis concentrate market is highly competitive, driven by continuous innovation, product differentiation, and regulatory compliance. Companies compete on quality, potency, extraction methods, and product variety, focusing on clean and safe concentrates to meet consumer demand. Strategic initiatives such as mergers, acquisitions, and partnerships are frequently employed to expand market presence and enter emerging regions. Firms also emphasize brand recognition, distribution efficiency, and customer loyalty to maintain a competitive edge. Continuous development of new concentrate formats, flavors, and cannabinoid profiles allows differentiation, while adherence to evolving legal and safety regulations remains critical. Overall, market competition is fueled by innovation, operational excellence, and the ability to respond to rapidly changing consumer preferences and regulatory environments.
Key Player Analysis
- Archer Daniels Midland
- Lemon Concentrate, S.L.
- Sunopata Inc.
- Kerr Concentrates, Inc.
- China Haiseng Juice Holdings Co., Ltd
- Dohler GmBH
- Skypeople Fruit Juice Inc.
- Agrana Beteiligungs Ag
- Royal Cosun
- Rudolf Wild GmBH & Co. Kg
Recent Developments
- In July 2025, SUEZ and SIAAP inaugurated France’s largest biogas production unit at the Seine Aval wastewater treatment plant near Paris. The facility processes 130,000 tonnes of sludge annually, generating 350 GWh of renewable energy. This covers over half the plant’s energy needs.
- In April 2025, Leanpath introduced a mobile reporting app designed for the foodservice industry. This app, which utilizes AI, makes it easier for chefs and kitchen managers to engage with food waste data.
- In January 2025, Calgon Carbon Corporation, a subsidiary of Kuraray Co., Ltd., secured a contract to supply activated carbon systems for wastewater treatment at a beverage manufacturing facility in the Asia Pacific.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Component and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to grow steadily as more countries and states adopt legal frameworks for medical and recreational cannabis.
- Consumer demand for high-potency and convenient concentrate products will continue to rise.
- Technological advancements in extraction methods will drive safer and higher-quality products.
- Product innovation and diversification in formats such as oils, waxes, tinctures, and edibles will expand market opportunities.
- Increased adoption of concentrates for medical and therapeutic applications will support long-term growth.
- Emerging markets, particularly in Asia-Pacific and Latin America, will present significant expansion opportunities.
- Strategic partnerships, mergers, and acquisitions will shape competitive dynamics and market consolidation.
- Regulatory clarity and standardization across regions will encourage investment and reduce operational risks.
- Consumer awareness and education about the benefits of concentrates will drive adoption.
- Companies focusing on sustainability, clean production processes, and quality assurance will strengthen their market position.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Legalization and Regulatory Support
Expanding legalization of medical and recreational cannabis across countries and states is opening new markets, reducing legal risks, and encouraging investment in cannabis concentrate production and distribution.
High Potency and Convenient Consumption
Cannabis concentrates offer significantly higher potency than traditional flower, enabling faster effects and smaller dosages. Their availability in convenient forms like oils, waxes, and vape cartridges appeals to consumers seeking discreet and efficient consumption.
Medical and Therapeutic Demand
Growing recognition of cannabis concentrates for treating chronic pain, neurological disorders, and other health conditions is driving adoption in the medical segment, supported by physician acceptance and regulatory reforms.
Advanced Extraction Technologies
Innovations in extraction methods, such as CO₂ and solvent-less techniques, are improving product purity, safety, and potency, enabling producers to offer higher-quality and differentiated concentrate products.
Product Innovation and Format Diversification
The development of new concentrate formats—including tinctures, edibles, and minor cannabinoid products—caters to evolving consumer preferences and expands the addressable market for both medical and recreational users.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Cannabis Concentrate Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Cannabis Concentrate Market projected to grow between 2025 and 2032?
Which Cannabis Concentrate Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Cannabis Concentrate Market?
Who are the leading companies in the Cannabis Concentrate Market?
Which region commanded the largest share of the Cannabis Concentrate Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Flowers/Buds
- 1.2.2 Concentrates
- 1.3 By Component
- 1.3.1 THC-Dominant
- 1.3.2 Balanced THC & CBD
- 1.3.3 CBD-Dominant
- 1.4 By Application
- 1.4.1 Medical
- 1.4.2 Recreational (Edibles and Topicals)
- 1.4.3 Industrial Hemp
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 41.44 billion → 2032: USD 196.31 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cannabis Concentrate Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cannabis Concentrate Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cannabis Concentrate Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cannabis Concentrate Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cannabis Concentrate Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cannabis Concentrate Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cannabis Concentrate Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cannabis Concentrate Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 41.44 billion → 2032: USD 196.31 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cannabis Concentrate Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Flowers/Buds
- 12.3.7.2 Concentrates
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 THC-Dominant
- 12.4.7.2 Balanced THC & CBD
- 12.4.7.3 CBD-Dominant
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Medical
- 12.5.7.2 Recreational (Edibles and Topicals)
- 12.5.7.3 Industrial Hemp
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cannabis Concentrate End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Cannabis Concentrate Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Cannabis Concentrate Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Cannabis Concentrate Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Archer Daniels Midland
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Lemon Concentrate, S.L.
- 18.4 Sunopata Inc.
- 18.5 Kerr Concentrates, Inc.
- 18.6 China Haiseng Juice Holdings Co., Ltd
- 18.7 Dohler GmBH
- 18.8 Skypeople Fruit Juice Inc.
- 18.9 Agrana Beteiligungs Ag
- 18.10 Royal Cosun
- 18.11 Rudolf Wild GmBH & Co. Kg
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
