
Market Overview
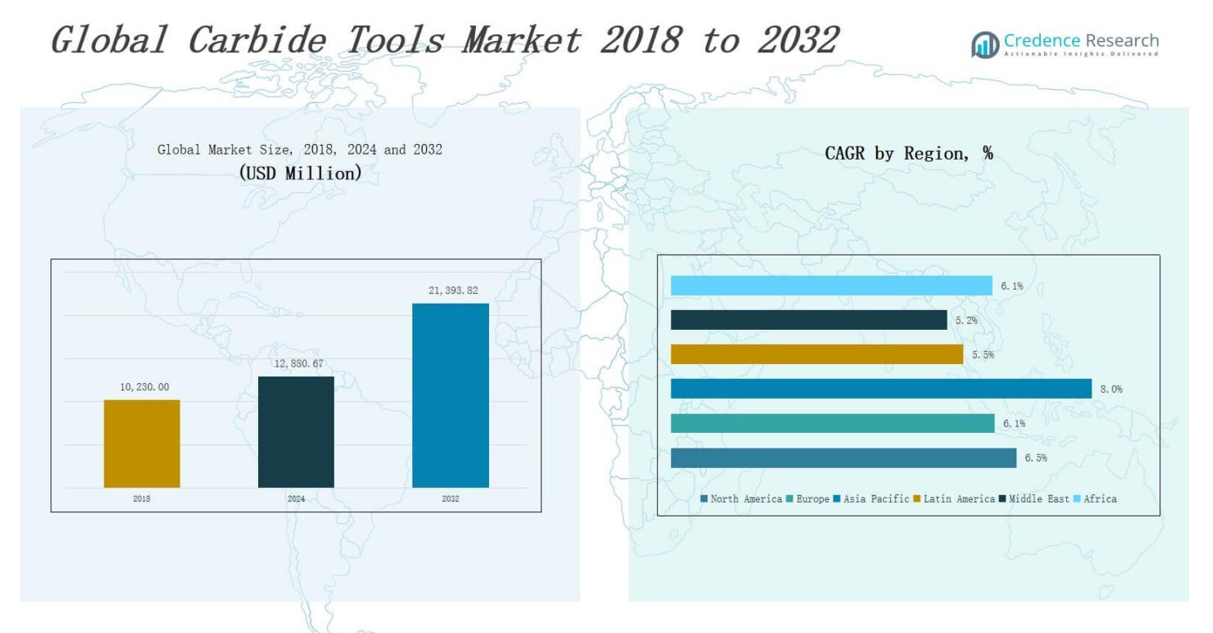
The Carbide Tools Market size was valued at USD 10,230.00 million in 2018 to USD 12,880.67 million in 2024 and is anticipated to reach USD 21,393.82 million by 2032, at a CAGR of 6.58% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Carbide Tools Market Size 2024 | USD 12,880.67 million |
| Carbide Tools Market, CAGR | 6.58% |
| Carbide Tools Market Size 2032 | USD 21,393.82 million |
The Carbide Tools Market is experiencing steady growth driven by the rising demand for high-performance machining solutions across automotive, aerospace, electronics, and general manufacturing sectors. These tools offer superior hardness, wear resistance, and heat tolerance, making them ideal for high-speed and precision cutting operations. The shift toward automation and advanced CNC machinery is accelerating carbide tool adoption, especially in mass production environments. Growing emphasis on product quality, dimensional accuracy, and reduced machining time further supports market expansion. Additionally, the surge in electric vehicle production and lightweight material usage increases the need for specialized carbide tools. Trends such as tool reconditioning, coating advancements, and the development of customized cutting geometries are enhancing tool longevity and efficiency. Manufacturers are also leveraging smart manufacturing practices and investing in R&D to innovate high-end carbide tools with improved cutting edge stability. These factors collectively contribute to the strong growth trajectory of the global carbide tools market across developed and emerging economies.
The Carbide Tools Market spans North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa, each contributing uniquely to global growth. Asia Pacific leads in growth rate due to rapid industrialization and expanding manufacturing in China, India, and Southeast Asia. Europe holds the largest revenue share, driven by advanced automotive and aerospace sectors. North America shows strong demand supported by CNC adoption and precision engineering. Latin America, the Middle East, and Africa show moderate but rising growth fueled by infrastructure and industrial development. Key players in the market include Sandvik AB, Kennametal Inc., OSG Corporation, Sumitomo Electric Industries Ltd, Guhring Ltd, Makita Corporation, YG-1 Co. Ltd, Fullerton Tool Company, Plansee Group (Ceratizit S.A.), and Allied Machine & Engineering Corp. These companies compete on innovation, tool life, precision, and global reach to meet diverse industrial and machining needs across all major regions.
Market Insights
- The Carbide Tools Market was valued at USD 10,230.00 million in 2018, reached USD 12,880.67 million in 2024, and is projected to grow to USD 21,393.82 million by 2032, at a CAGR of 6.58%.
- Growth is driven by high demand across automotive, aerospace, electronics, and general manufacturing sectors due to carbide tools’ durability, precision, and heat resistance.
- The market is expanding rapidly with CNC machining adoption, smart manufacturing, and the transition to lightweight materials in electric vehicles and precision components.
- Challenges include high initial costs for small manufacturers and supply chain risks linked to critical materials like tungsten and cobalt.
- Asia Pacific shows the highest growth at 8.0% CAGR, led by industrialization and manufacturing in China, India, and Southeast Asia; Europe holds the largest market share.
- North America maintains strong demand through CNC advancements and electric vehicle investment, while Latin America, the Middle East, and Africa are growing steadily with rising industrialization.
- Key players include Sandvik AB, Kennametal Inc., OSG Corporation, Sumitomo Electric, Guhring Ltd, Makita Corporation, YG-1 Co. Ltd, Fullerton Tool Company, Ceratizit S.A., and Allied Machine & Engineering.
Market Drivers
Rising Demand from Automotive and Aerospace Industries
The Carbide Tools Market is gaining strong momentum due to the increasing demand for high-precision and durable machining tools in automotive and aerospace sectors. These industries require tools that can maintain performance under high stress and temperature, making carbide tools an ideal choice. It supports high-speed cutting operations and delivers consistent performance when working with hard metals and alloys. The ongoing transition to lightweight materials, such as aluminum and titanium, necessitates advanced cutting solutions. Carmakers and aircraft manufacturers are scaling production, which drives tooling demand across production lines. This rising reliance on carbide tools for engine, drivetrain, and structural components continues to push market growth across both segments.
- For instance, Sandvik AB supplies advanced carbide tools that enable high-speed, precision machining of hardened automotive components, supporting major carmakers in improving engine and transmission production efficiency.
Technological Advancements in Coatings and Tool Geometry
The Carbide Tools Market benefits from continuous innovations in tool coatings and geometrical enhancements. Advanced coatings like TiAlN and diamond-like carbon extend tool life by enhancing resistance to wear, oxidation, and thermal degradation. Optimized geometries and edge designs allow for faster machining, smoother finishes, and lower tool replacement rates. These features reduce downtime and improve manufacturing efficiency, particularly in demanding applications. Companies are investing in R&D to design customized tools for specific industrial uses, further expanding application scope. Innovation remains critical for market competitiveness and long-term tool performance across diverse manufacturing environments.
- For instance, Sandvik Coromant developed its Inveio® coating technology, which aligns aluminum oxide crystals to enhance heat resistance and extend tool life in high-speed milling applications.
Growth in CNC Machining and Smart Manufacturing
The Carbide Tools Market is expanding with the proliferation of computer numerical control (CNC) machining and the shift toward Industry 4.0. Automated machining centers require reliable and long-lasting cutting tools to minimize interruptions and maintain precision. Carbide tools meet these demands with high wear resistance and predictable performance in continuous operation. Smart manufacturing facilities prioritize efficiency and accuracy, both of which are enhanced by advanced tooling systems. The integration of sensors and digital monitoring tools has also encouraged the use of carbide tools due to their compatibility with intelligent systems. It supports real-time adjustments and predictive maintenance strategies.
Expansion of Electronics and General Engineering Applications
The Carbide Tools Market is seeing broader application in the electronics and general engineering sectors. Precision tooling is essential in producing intricate electronic components, printed circuit boards, and molds. Carbide tools allow for tight tolerances and high surface quality, critical for electronics manufacturing. In general engineering, diverse applications such as die making, mold fabrication, and part prototyping rely on carbide tooling. Market participants are catering to SMEs and contract manufacturers with tailored tooling solutions. The demand for versatile and efficient tools continues to rise with increasing production complexity and quality requirements. It positions carbide tools as essential across multiple manufacturing layers.
Market Trends
Adoption of Advanced Coating Technologies Enhancing Tool Longevity
The Carbide Tools Market is witnessing a shift toward high-performance coating technologies that significantly improve tool lifespan and performance under extreme conditions. Coatings such as Titanium Aluminum Nitride (TiAlN), AlTiN, and nanocomposite films offer superior hardness, oxidation resistance, and thermal stability. These innovations allow tools to withstand high-speed machining and dry cutting processes without compromising quality. Manufacturers are focusing on multi-layered coatings to further enhance wear resistance and reduce friction. Coated carbide tools reduce tool change frequency, minimizing downtime and production costs. It is strengthening the market's value proposition for precision-intensive sectors like aerospace and automotive manufacturing.
- For instance, in August 2024, YG-1 introduced the Solid Carbide Dream Drill X featuring advanced RCH-Coating technology, which enables superior tool life and efficiency in high-speed and dry machining applications.
Rising Demand for Customized and Application-Specific Tooling
The Carbide Tools Market is increasingly moving toward customization, with end-users seeking application-specific tooling solutions to meet unique production requirements. Customized carbide tools deliver better performance by aligning with material type, machining speed, and dimensional tolerances. Toolmakers are using computer-aided design and simulation software to develop complex geometries suited for advanced materials and intricate designs. This trend improves operational efficiency and surface quality, especially in sectors requiring high-precision components. It also allows for flexible, small-batch, or prototyping applications where standard tools fall short. This personalization is shaping competitive differentiation among tool manufacturers globally.
- For instance, Monaghan Tooling Group provided a solid carbide internal recessing unit that enabled a customer to machine all internal grooves in one operation, saving substantial cycle time and improving throughput.
Integration of Smart Tooling for Industry 4.0 Compatibility
The Carbide Tools Market is embracing digital transformation through smart tooling solutions that support predictive maintenance, real-time monitoring, and process optimization. Smart carbide tools equipped with sensors help monitor tool wear, cutting forces, and temperature in real-time. These insights enable operators to make informed decisions that prevent tool failure and reduce material wastage. Industry 4.0 environments demand traceability and data-driven control, prompting wider adoption of intelligent tooling systems. It helps manufacturers maintain consistent quality and reduce downtime across automated production lines. This trend is gaining momentum in advanced manufacturing facilities worldwide.
Sustainability Focus Driving Tool Reconditioning Practices
The Carbide Tools Market is seeing a growing trend toward sustainable practices, particularly in tool reconditioning and recycling. Many industries now prefer regrinding and recoating worn carbide tools to reduce costs and environmental impact. Tool refurbishment helps extend the usable life of expensive carbide tools without compromising quality. This practice also aligns with circular economy goals and waste reduction initiatives in manufacturing. Companies offering value-added reconditioning services are gaining a competitive edge. It promotes resource efficiency while supporting long-term supply stability in the tooling ecosystem. This sustainability focus is expected to remain central in future procurement strategies.
Market Challenges Analysis
High Initial Costs and Limited Access for Small Manufacturers
The Carbide Tools Market faces challenges due to the high initial cost of carbide tooling, which can be a barrier for small and medium-sized manufacturers. Carbide tools are more expensive than traditional high-speed steel options, limiting adoption in cost-sensitive operations. Smaller firms may struggle to justify the upfront investment despite long-term efficiency benefits. The need for compatible advanced machinery and skilled operators further increases operational costs. This cost disparity affects overall market penetration in emerging economies. It restricts broader usage in sectors with tighter budget constraints.
Supply Chain Volatility and Raw Material Dependency
The Carbide Tools Market is vulnerable to supply chain disruptions and price fluctuations of critical raw materials like tungsten and cobalt. These materials are primarily sourced from a few countries, exposing manufacturers to geopolitical risks and export restrictions. Volatile raw material costs directly impact production budgets and tool pricing. This unpredictability can lead to delays, reduced profit margins, and inconsistent supply for end users. It creates uncertainty in long-term contracts and complicates inventory planning. Maintaining stable procurement channels remains a strategic challenge for toolmakers.
Market Opportunities
Expansion into Emerging Economies and SME Manufacturing Hubs
The Carbide Tools Market holds significant growth potential in emerging economies where industrialization and infrastructure development are accelerating. Countries such as India, Vietnam, and Brazil are witnessing increased investment in automotive, aerospace, and electronics manufacturing. Small and medium enterprises in these regions are upgrading their machining capabilities, creating demand for reliable and efficient cutting tools. Government-led initiatives supporting manufacturing localization and industrial clusters present new market entry points. It offers toolmakers the opportunity to expand customer base and establish long-term distribution networks. Local partnerships and cost-optimized product lines can further strengthen market position.
Growth in Electric Vehicle and Lightweight Material Machining
The Carbide Tools Market stands to benefit from the global shift toward electric vehicle (EV) production and the rising use of lightweight materials such as aluminum and carbon fiber composites. These materials require specialized cutting tools capable of maintaining performance at high speeds and tolerances. EV manufacturers prioritize precision and production efficiency, making carbide tools an essential part of the process. Toolmakers that innovate application-specific solutions for battery housings, drivetrains, and chassis components will gain a competitive edge. It creates room for product differentiation and long-term supplier relationships. The ongoing transition to sustainable mobility strengthens this opportunity.
Market Segmentation Analysis:
By Tools Type
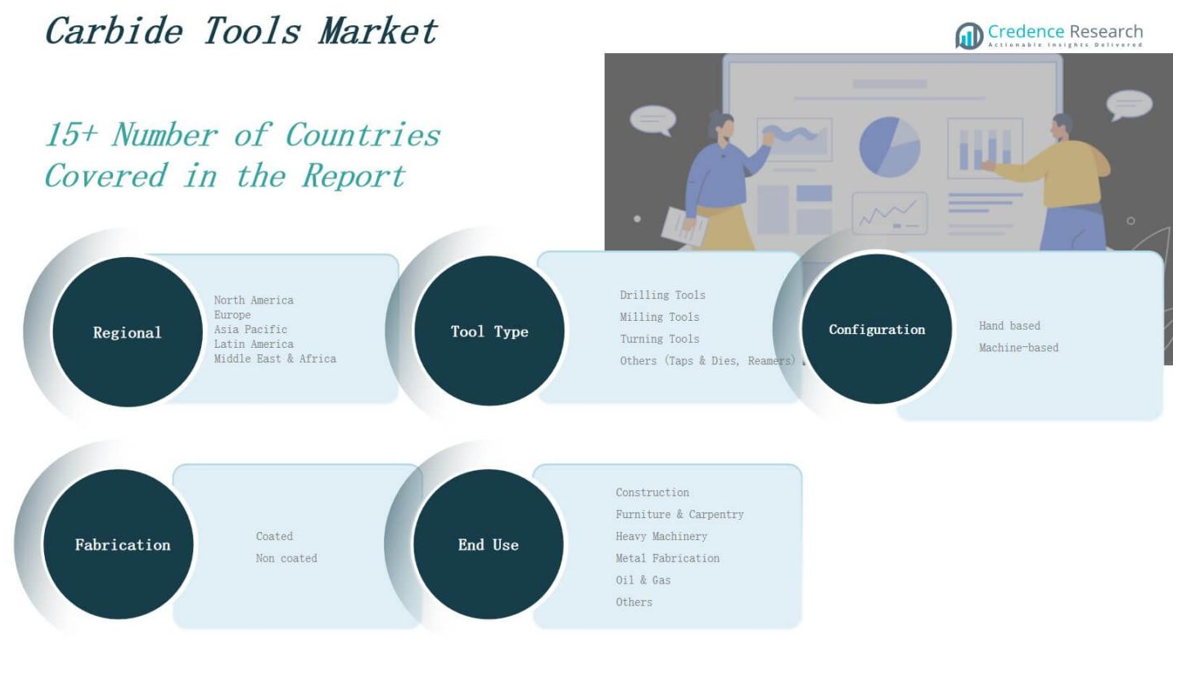
The Carbide Tools Market is segmented into drilling tools, milling tools, turning tools, and others such as taps, dies, and reamers. Drilling tools account for a significant market share due to their extensive use in construction, automotive, and aerospace sectors. Milling tools are widely applied in high-precision applications, supported by increased adoption in mold and die manufacturing. Turning tools maintain strong demand in metal fabrication and heavy equipment production. The ‘others’ category, including taps and reamers, serves specialized operations and complements core machining activities. The diversity in tool types reflects the market's ability to meet various cutting and finishing requirements across industries.
- For instance, Kennametal’s carbide drills are widely used in automotive and aerospace manufacturing, offering superior hardness and heat resistance for precision drilling and deep-hole applications.
By Configuration
The Carbide Tools Market is divided into hand-based and machine-based configurations. Machine-based tools dominate the segment owing to their integration in CNC machines and automated production environments. These tools support faster operations, greater accuracy, and reduced downtime, making them essential for high-volume production. Hand-based tools continue to serve small workshops and maintenance functions, particularly in regions with limited automation. It allows flexible operations and cost-effective usage in less complex machining tasks. The configuration segment reflects the industry’s transition toward automation while preserving utility for manual applications.
- For instance, Fastems retrofits existing machine tools with automation systems that manage pallet transfers, production planning, and resource management, increasing efficiency without the need for new CNC equipment.
By End-use
The Carbide Tools Market serves end-use industries such as construction, furniture & carpentry, heavy machinery, metal fabrication, oil & gas, and others. Construction leads demand with consistent tool usage in infrastructure and equipment assembly. Furniture and carpentry industries utilize carbide tools for clean cuts and extended tool life in wood applications. Heavy machinery and metal fabrication sectors depend on carbide tools for precision and durability in metal cutting. The oil & gas segment requires robust tools for drilling and maintenance in challenging environments. It supports a broad spectrum of industrial applications with tools tailored for performance and endurance.
Segments:
Based on Tools Type
- Drilling Tools
- Milling Tools
- Turning Tools
- Others (Taps & Dies, Reamers)
Based on Configuration
- Hand-based
- Machine-based
Based on End-use
- Construction
- Furniture & Carpentry
- Heavy Machinery
- Metal Fabrication
- Oil & Gas
- Others
Based on Fabrication
- Coated
- Non-coated
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The North America Carbide Tools Market size was valued at USD 2,516.58 million in 2018 to USD 3,111.89 million in 2024 and is anticipated to reach USD 5,142.86 million by 2032, at a CAGR of 6.5% during the forecast period. The region holds a substantial share in the global carbide tools market, driven by robust demand across aerospace, automotive, and construction industries. The United States remains the dominant contributor due to its advanced manufacturing infrastructure and emphasis on high-speed machining. It benefits from a strong base of CNC-equipped facilities and a growing inclination toward Industry 4.0 practices. The market is further supported by investments in electric vehicle production and aerospace innovation. North America's market share reflects its technological maturity and strong industrial output.
Europe
The Europe Carbide Tools Market size was valued at USD 4,353.89 million in 2018 to USD 5,350.28 million in 2024 and is anticipated to reach USD 8,586.47 million by 2032, at a CAGR of 6.1% during the forecast period. Europe accounts for the highest revenue share globally, supported by Germany, France, and Italy's strong presence in automotive, aerospace, and heavy engineering. The region's emphasis on precision machining and sustainability is encouraging the use of high-quality carbide tools. It benefits from established OEMs and innovation in tool coatings and geometries. The demand for application-specific and reconditioned tools is rising across advanced manufacturing hubs. Europe’s regulatory environment also supports adoption of durable and energy-efficient tools, reinforcing market growth.
Asia Pacific
The Asia Pacific Carbide Tools Market size was valued at USD 2,078.74 million in 2018 to USD 2,757.05 million in 2024 and is anticipated to reach USD 5,094.10 million by 2032, at a CAGR of 8.0% during the forecast period. Asia Pacific is the fastest-growing region in the global carbide tools market, fueled by rapid industrialization in China, India, and Southeast Asia. Expanding automotive production, rising investments in electronics manufacturing, and a growing machine tool industry are driving demand. It is benefiting from government initiatives that promote local manufacturing and industrial upgrades. The region's large SME base is also shifting toward higher-efficiency carbide tools. Competitive pricing and the presence of regional toolmakers are further enhancing adoption.
Latin America
The Latin America Carbide Tools Market size was valued at USD 605.62 million in 2018 to USD 754.68 million in 2024 and is anticipated to reach USD 1,156.76 million by 2032, at a CAGR of 5.5% during the forecast period. The region is witnessing gradual growth, supported by recovery in industrial activity across Brazil, Mexico, and Argentina. Demand is growing in sectors such as construction, mining, and metal fabrication. It is gaining traction from infrastructure development projects and increasing adoption of machine-based operations. The transition from conventional tools to carbide alternatives is accelerating with rising awareness of performance benefits. Market penetration remains moderate, but ongoing manufacturing expansion is improving the outlook.
Middle East
The Middle East Carbide Tools Market size was valued at USD 386.69 million in 2018 to USD 455.89 million in 2024 and is anticipated to reach USD 682.58 million by 2032, at a CAGR of 5.2% during the forecast period. The market is expanding steadily, with demand concentrated in oil & gas maintenance, construction, and infrastructure sectors. GCC countries are investing in industrial diversification and smart manufacturing, supporting tool demand. It is also driven by regional efforts to localize machining operations and reduce reliance on imports. While the market is relatively smaller, modernization across various sectors is boosting carbide tool adoption. Growth opportunities lie in automation and renewable energy applications.
Africa
The Africa Carbide Tools Market size was valued at USD 288.49 million in 2018 to USD 450.88 million in 2024 and is anticipated to reach USD 731.05 million by 2032, at a CAGR of 6.1% during the forecast period. Africa’s market is emerging, supported by gradual development in mining, infrastructure, and industrial manufacturing. South Africa leads regional demand, followed by Egypt and select West African nations. It is witnessing increased use of carbide tools for metal cutting and drilling operations in construction and resource extraction. The affordability of reconditioned tools and local tool distribution is supporting adoption. Growth remains uneven across countries, but long-term prospects are positive with rising regional industrialization.
Key Player Analysis
- OSG Corporation
- Sandvik AB (Sweden)
- Makita Corporation (Japan)
- Plansee Group (Ceratizit S.A.) (Luxembourg)
- Kennametal Inc. (U.S.)
- Sumitomo Electric Industries Ltd (Japan)
- Guhring Ltd (U.K.)
- Fullerton Tool Company Inc. (U.S.)
- YG-1 Co Ltd (Japan)
- Allied Machine & Engineering Corp (U.S.)
Competitive Analysis
The Carbide Tools Market is highly competitive, marked by the presence of global and regional manufacturers focused on innovation, quality, and cost efficiency. Leading players such as Sandvik AB, Kennametal Inc., OSG Corporation, and Sumitomo Electric Industries dominate with strong distribution networks, advanced R&D capabilities, and diversified product portfolios. These companies invest in coating technologies, tool customization, and digital integration to strengthen their market position. Mid-sized firms are targeting niche applications and offering specialized tooling solutions to differentiate themselves. It continues to attract new entrants due to growing demand in precision machining and automotive applications. Strategic partnerships, acquisitions, and regional expansions remain key tactics across the competitive landscape. The market's growth dynamics favor companies that align with Industry 4.0 trends and deliver high-performance, application-specific tools. Continuous product improvement and localized manufacturing support long-term competitiveness across both developed and emerging markets.
Recent Developments
- In March 2025, Mitsubishi Materials announced a strategic brand transition, replacing its DIAEDGE label with the unified Mitsubishi Materials brand across its global metalworking solutions, including carbide tools.
- In March 2025, Sandvik Coromant launched its new CoroDrill® Dura 462 and CoroDrill® DE10 tool families, designed for multi-material and short-hole drilling, emphasizing plug-and-play performance and improved efficiency.
- In early 2025, GWS Tool Group acquired Carbide Grinding Company, enhancing its custom and standard carbide, PCD, and CBN tool offerings to expand its U.S.-based manufacturing capabilities.
- In January 15, 2025, onsemi completed the acquisition of Qorvo's Silicon Carbide JFET business, enhancing their portfolio in silicon carbide technologies for advanced electronic applications.
Market Concentration & Characteristics
The Carbide Tools Market is moderately concentrated, with a mix of global giants and regional manufacturers competing across diverse application sectors. Leading companies such as Sandvik AB, Kennametal Inc., and Sumitomo Electric dominate through extensive product portfolios, innovation capabilities, and strong distribution networks. It exhibits characteristics of high entry barriers due to advanced technology requirements, skilled labor, and capital-intensive production processes. The market favors players that can deliver high-performance, durable tools suited for precision and high-speed machining. Product differentiation is largely based on coating technologies, tool geometry, and compatibility with automated systems. Demand is consistent across end-use industries including automotive, aerospace, construction, and electronics, creating opportunities for both volume-driven and niche players. Tool reconditioning services and customization further define competition, especially in cost-sensitive and application-specific markets. Regional firms gain traction by offering localized support and competitive pricing, while multinational players leverage R&D and scale to maintain global leadership.
Report Coverage
The research report offers an in-depth analysis based on Tools Type, Configuration, Fabrication, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for carbide tools will grow with the rising adoption of automated and precision machining systems.
- The automotive and aerospace sectors will continue to drive tool innovation and application-specific designs.
- Smart manufacturing and Industry 4.0 integration will increase the use of sensor-enabled and digital-ready carbide tools.
- Coated carbide tools will dominate due to their improved wear resistance and extended tool life.
- The shift toward electric vehicles will boost demand for high-performance tools suitable for lightweight materials.
- Tool reconditioning and recycling will become more prominent to reduce costs and support sustainability goals.
- Asia Pacific will remain a key growth region, supported by manufacturing expansion and favorable government policies.
- Small and medium enterprises will adopt machine-based carbide tools to improve productivity and accuracy.
- Technological advancements in tool geometry will enhance cutting speed, surface finish, and material compatibility.
- Strategic collaborations and acquisitions will shape the competitive landscape across global and regional markets.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand from Automotive and Aerospace Industries
Automotive and aerospace sectors require high-precision, durable tools for machining advanced materials and components. The shift to lightweight materials and increased production volumes in these industries are driving the adoption of carbide tools for their superior hardness and heat resistance.
Technological Advancements in Coatings and Tool Geometry
Continuous innovation in tool coatings (such as TiAlN and diamond-like carbon) and optimized geometries is extending tool life, improving machining speeds, and reducing downtime. These advancements make carbide tools more attractive for high-performance and precision applications.
Growth in CNC Machining and Smart Manufacturing
The proliferation of CNC machines and the adoption of Industry 4.0 practices are increasing the need for reliable, long-lasting carbide tools. Automated and smart manufacturing environments demand tools that can maintain accuracy and performance in continuous, high-speed operations.
Expansion of Electronics and General Engineering Applications
The need for tight tolerances and high surface quality in electronics and general engineering is boosting demand for carbide tools. Their ability to deliver precision in intricate and complex machining tasks makes them essential in these growing sectors.
Surge in Electric Vehicle Production and Lightweight Material Usage
The global shift toward electric vehicles and the use of lightweight materials like aluminum and composites require specialized carbide tools for efficient, high-speed machining. This trend is expanding the market for application-specific carbide tooling solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Carbide Tools Market?
What are the key segments within the Carbide Tools Market?
What are some challenges faced by the Carbide Tools Market?
Who are the major players in the Carbide Tools Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-use
- 1.2.1 Construction
- 1.2.2 Furniture & Carpentry
- 1.2.3 Heavy Machinery
- 1.2.4 Metal Fabrication
- 1.2.5 Oil & Gas
- 1.2.6 Others
- 1.3 By Tools Type
- 1.3.1 Drilling Tools
- 1.3.2 Milling Tools
- 1.3.3 Turning Tools
- 1.3.4 Others (Taps & Dies, Reamers)
- 1.4 By Fabrication
- 1.4.1 Coated
- 1.4.2 Non-coated
- 1.5 By Configuration
- 1.5.1 Hand-based
- 1.5.2 Machine-based
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 12,880.67 million → 2032: USD 21,393.82 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Carbide Tools Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Carbide Tools Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Carbide Tools Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Carbide Tools Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Carbide Tools Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Carbide Tools Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Carbide Tools Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Carbide Tools Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 12,880.67 million → 2032: USD 21,393.82 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Carbide Tools Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Construction
- 12.3.7.2 Furniture & Carpentry
- 12.3.7.3 Heavy Machinery
- 12.3.7.4 Metal Fabrication
- 12.3.7.5 Oil & Gas
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Tools Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Drilling Tools
- 12.4.7.2 Milling Tools
- 12.4.7.3 Turning Tools
- 12.4.7.4 Others (Taps & Dies, Reamers)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Fabrication - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Coated
- 12.5.7.2 Non-coated
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Configuration - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Hand-based
- 12.6.7.2 Machine-based
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Carbide Tools End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Carbide Tools Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Carbide Tools Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Carbide Tools Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Sandvik AB
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Kennametal Inc.
- 18.4 OSG Corporation
- 18.5 Sumitomo Electric Industries Ltd
- 18.6 Guhring Ltd
- 18.7 Makita Corporation
- 18.8 YG-1 Co. Ltd
- 18.9 Fullerton Tool Company
- 18.10 Plansee Group (Ceratizit S.A.)
- 18.11 Allied Machine & Engineering Corp
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

