
Cashew Kernel Market Overview:
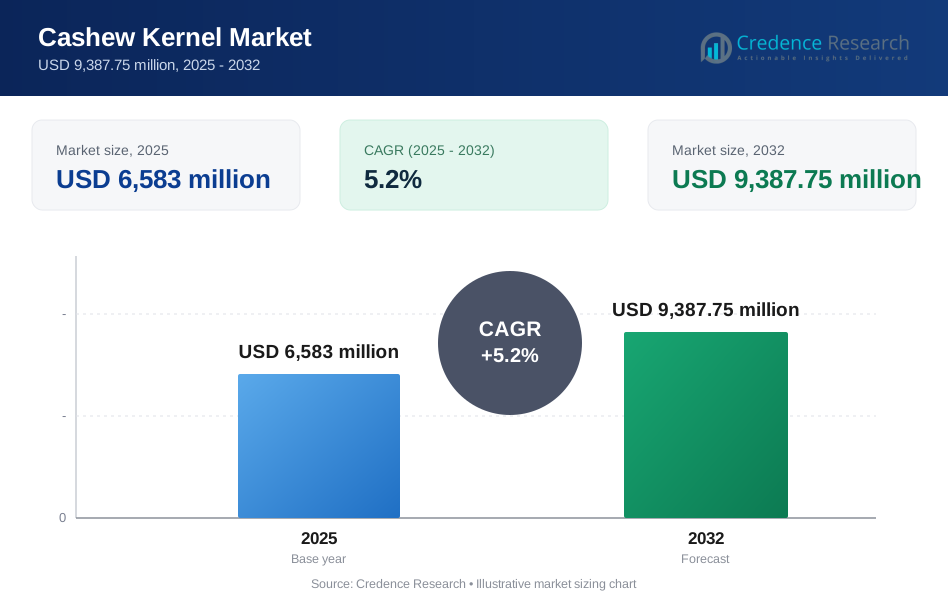
The global Cashew kernel market size was estimated at USD 6,583 million in 2025 and is expected to reach USD 9,387.75 million by 2032, growing at a CAGR of 5.2% from 2025 to 2032. Demand expansion is anchored in rising everyday snacking and premium nut-mix consumption, supported by wider retail availability across modern trade and e-commerce channels. The cashew kernel market is also benefiting from increasing usage in bakery, confectionery, and plant-forward dessert formulations that value creamy texture and mild flavor, alongside stronger gifting-led purchases in key consumption hubs.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Cashew Kernel Market Size 2025 | USD 6,583 million |
| Cashew Kernel Market, CAGR | 5.2% |
| Cashew Kernel Market Size 2032 | USD 9,387.75 million |
Key Market Trends & Insights
- The Cashew kernel market expands from USD 6,583 million (2025) to USD 9,387.75 million (2032) at a 5.2% CAGR (2025–2032).
- Asia Pacific represents 43.1% share in 2025, reflecting scale advantages in processing, domestic consumption growth, and export-oriented supply chains.
- White Wholes account for the largest share of 46.8% in 2025, supported by premium grading demand and higher retail pack preference for whole kernels.
- Organic holds 33.4% share in 2025, reflecting sustained clean-label pull and certification-led differentiation in premium retail and online channels.
- Consumer behavior remains snack-led, with 87.5% of surveyed consumers using cashew kernels as snacks and 74.5% consuming roasted formats, strengthening demand for ready-to-eat packs.

Segment Analysis
The Cashew kernel market shows a strong bias toward snack-format consumption, with consumer usage patterns reinforcing demand for roasted and flavored kernels across retail shelves and online assortments. High snack usage and repeat purchase behavior support steady throughput for standardized grades, especially where packaging formats emphasize freshness, portion control, and premium appearance. In parallel, a large share of imported kernels in developed markets flows into snack channels, reinforcing the importance of consistent grading, uniform color, and reliable supply contracts.
Food-manufacturing demand adds a second demand pillar for the Cashew kernel market, particularly where pieces and lower-cost grades improve formulation economics in bars, bakery, confectionery, and dessert inclusions. Cashew’s texture profile helps premiumize finished products, supporting higher-value ingredient positioning in select applications. The Cashew kernel market also benefits from the rise of plant-forward desserts and dairy-alternative recipes that rely on cashew for creaminess, which can lift demand for both whole and piece formats depending on the end formulation.
By Product / Form Insights
White Wholes accounted for the largest share of 46.8% in 2025. Premium retail packs and gifting assortments favor whole-kernel appearance and uniform sizing, which sustains stronger demand for White Wholes versus other grades. Quality consistency in color, breakage control, and sizing standards also supports procurement preference among branded snack players. Growing demand from food manufacturers keeps additional pull for pieces, but White Wholes remain the primary value driver in the Cashew kernel market.
By Type / Cultivation Insights
Organic accounted for the largest share of 33.4% in 2025. Clean-label preferences and concerns around residues strengthen organic positioning in premium retail, specialty stores, and online channels. Certification requirements influence procurement decisions, supplier qualification, and traceability investments across the Cashew kernel market. Organic price premiums remain a constraint in mass channels, but differentiated branding and gifting-led demand help sustain higher-margin organic offerings.
By Application Insights
Direct Consumption / Snacks leads application demand in the Cashew kernel market due to convenience-driven purchases and the popularity of roasted, salted, and flavored formats. Snack usage supports stable volume for whole kernels, while mixed-nut packs and portion-controlled packaging broaden appeal across consumer segments. Bakery & confectionery and cereals and bars drive incremental usage for inclusions where pieces offer cost efficiency and easier processing. Dairy & desserts also support application diversity where cashew-based creaminess and texture improve sensory outcomes in plant-forward recipes.
Cashew Kernel Market Drivers
Expansion of Snack Consumption and Premium Nut Mixes
The Cashew kernel market benefits from rising snack frequency and preference for nutrient-dense, convenient foods that fit busy lifestyles. Packaged roasted kernels and nut mixes support consistent repeat purchases across supermarkets, convenience retail, and digital channels. Premiumization trends also lift average selling prices where consumers trade up to whole-kernel grades and flavored variants. Strong gifting culture in several markets supports seasonal spikes and premium assortments that rely on high-appearance kernels.
- For instance, Sahale Snacks’ Pomegranate Vanilla Cashews use whole dry-roasted cashews in a premium flavored format, with a 1/4-cup serving delivering 160 calories and 4 g of protein, while the single-bag format delivers 220 calories and 6 g of protein.
Broader Use in Bakery, Confectionery, and Bar Formulations
The Cashew kernel market gains demand from manufacturers using kernels and pieces as inclusions for texture, visual appeal, and perceived quality. Bakery and confectionery products use cashew to signal premium positioning, supporting ingredient pull-through. Cereals and bars increasingly use nut inclusions, where pieces can optimize formulation costs without sacrificing taste. Foodservice and ingredient channels also drive steady offtake where cashew is used in sauces, toppings, and dessert applications.
- For instance, KIND THINS Dark Chocolate Cherry Cashew is formulated with sliced cashews and almonds for texture, and each 21 g bar is portioned at 90 calories with 2 g of protein and 2 g of dietary fiber.
Growth of Plant-Forward Desserts and Creamy Texture Applications
The Cashew kernel market is supported by rising interest in plant-forward eating patterns that increase usage in creamy desserts and dairy-alternative recipes. Cashew’s mild flavor and natural fat profile help create smooth textures in fillings, spreads, and blended bases. This demand supports both whole kernels and pieces depending on processing requirements. Innovation in ready-to-use pastes, blends, and recipe kits can expand addressable use cases beyond traditional snacking.
Supply Chain Investments in Quality, Grading, and Sourcing Reliability
The Cashew kernel market is shaped by the ability of suppliers to deliver consistent quality, food safety compliance, and grading uniformity at scale. Buyers prioritize traceability, contamination control, and stable supply contracts, particularly for branded snack and ingredient accounts. Processing improvements that reduce breakage and improve color sorting can increase yields of higher-value grades. Diversified sourcing and stronger logistics resilience help mitigate volatility and support dependable deliveries.
Cashew Kernel Market Challenges
The Cashew kernel market faces persistent price and supply volatility driven by raw nut availability, climatic variability in producing regions, and shifting trade dynamics. Quality inconsistencies, including moisture management, breakage rates, and grade variability, can disrupt contract performance and raise rejection risk. Food safety and allergen-control expectations add compliance complexity across processors, packers, and private-label supply chains. Margin pressure can intensify when retail pricing resistance limits the ability to pass through higher procurement costs.
- For instance, Bühler has positioned optical sorting as a direct response to nut-processing quality risks: its SORTEX H SpectraVision is reported to deliver up to 50% higher reject concentration, and its SORTEX LumoVision is reported to reduce aflatoxin levels by up to 90% in industrial trials, showing how processors are increasingly relying on measurable defect-removal and contamination-control technologies to protect contract performance and food safety compliance.
The Cashew kernel market also encounters challenges tied to certification, traceability, and sustainability requirements that raise operational costs for smaller suppliers. Organic certification and audit readiness can create barriers for new entrants and informal processors seeking export access. Packaging and shelf-life management become critical in humid climates, increasing the need for robust barrier materials and controlled storage. Competitive intensity among branded snack players and private-label offerings can compress differentiation unless quality and product innovation remain strong.
Cashew Kernel Market Trends and Opportunities
The Cashew kernel market is seeing premiumization through flavored and coated variants, gifting packs, and format innovation that increases value per unit sold. Product development in chocolate-coated, spiced, and regionally inspired flavors supports higher-margin positioning in modern trade. Branding and packaging upgrades also improve shelf visibility and expand premium gifting use cases. Expansion of e-commerce assortments enables broader SKU variety, supporting trial, repeat purchases, and subscription-style replenishment.
- For instance, Happilo’s online cashew portfolio includes whole, jumbo, and roasted & salted variants, while its product listings show 200 g, 200 g (pack of 2), 500 g (pack of 2), and 1 kg formats, plus an airtight zip-lock pouch format; separately, its gifting storefront lists 6 products, showing how pack architecture and online assortment can support premium positioning and repeat purchase behavior.
The Cashew kernel market has opportunity in ingredient-led growth, including ready-to-use cashew pastes, inclusions, and foodservice-focused packs tailored for bakeries and dessert makers. Plant-forward product launches can increase adoption of cashew as a texture and mouthfeel enhancer in desserts and dairy-alternative recipes. Traceability-led procurement and sustainability storytelling can strengthen supplier differentiation, especially for organic and premium lines. Geographic expansion into underpenetrated urban centers can further lift consumption through modern retail and convenience formats.
Regional Insights
North America
North America holds 26.4% share in 2025, supported by strong snack consumption, premium nut mix demand, and broad availability across mass retail and warehouse clubs. Branded and private-label players emphasize consistent grading, roasting profiles, and packaging formats that reinforce repeat purchase behavior. Growth opportunities remain strong in flavored kernels and portion-controlled packs aligned with convenience-led consumption. Food manufacturing demand also supports stable offtake through inclusions for bars, bakery items, and confectionery.
Europe
Europe accounts for 19.8% share in 2025, backed by strong demand for roasted snack kernels and premium retail assortments. Procurement preferences emphasize traceability, quality uniformity, and compliance readiness, which increases supplier qualification requirements. Premium gifting and specialty retail formats help sustain higher-value whole-kernel demand. Growth also links to bakery and confectionery usage where cashew inclusions support premium positioning and texture outcomes.
Asia Pacific
Asia Pacific represents 43.1% share in 2025, reflecting large-scale processing ecosystems, strong domestic consumption, and export-oriented supply chains. Regional demand benefits from both everyday snacking and cashew usage in sweets, desserts, and festive gifting. Processing scale and diversified product offerings improve regional competitiveness across grades and formats. Investment in quality sorting, grading, and packaging continues to strengthen supply reliability for global buyers.
Latin America
Latin America holds 7.4% share in 2025, supported by rising urban consumption, modern retail expansion, and growing interest in packaged snack nuts. The region also benefits from local production and processing in select countries that can support domestic and regional supply. Opportunities exist in value-added flavored kernels and mixed-nut snack packs targeting convenience-led purchases. Foodservice and ingredient use can expand further as bakery and dessert channels modernize.
Middle East & Africa
Middle East & Africa accounts for 3.3% share in 2025, supported by premium gifting demand, expanding modern retail, and rising adoption of packaged nuts in urban markets. Import reliance elevates the importance of logistics efficiency and shelf-life management, especially in warmer climates. Premium assortments and hospitality-driven consumption can support higher-value grades and branded packs. Market expansion is linked to broader retail availability and affordable pack sizes that improve accessibility.
Competitive Landscape
The Cashew kernel market features a mix of global branded food companies, ingredient traders, and specialized processors competing through sourcing reliability, grade consistency, and value-added product offerings. Product differentiation centers on roasting quality, flavor innovation, organic positioning, and packaging formats that support freshness and premium perception. Procurement strength and supplier relationships remain critical, particularly for stable access to high-quality kernels across seasons. Strategic partnerships and private-label supply agreements are common approaches to scale penetration and secure shelf presence.
Archer Daniels Midland Company participates in the Cashew kernel market through broad ingredient capabilities, global sourcing networks, and supply chain execution that supports consistent deliveries for large buyers. The company’s scale can support standardized quality requirements and multi-region distribution for food manufacturing customers. Emphasis on supplier qualification, traceability practices, and dependable logistics can strengthen competitiveness in premium and industrial channels. Portfolio breadth across ingredients can also support cross-selling into bakery, confectionery, and snack manufacturing accounts.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Archer Daniels Midland Company
- Bunge Limited
- Nestlé S.A.
- The Kraft Heinz Company
- John B. Sanfilippo & Son, Inc.
- Vietnam Cashew Corporation (VINACAS)
- Lien Anh Co. Ltd
- Haldiram Foods International Private Limited
- Alphonsa Cashew Industries
- Diamond Foods, LLC
- Emerald Nuts, LLC
- Aurora Products, Inc.
- CBL Natural Foods Private Limited
- Prime Nuts FZE
- Afokantan Benin Cashew
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In June 2024, Elmhurst 1925 introduced a new line of dairy-free Cashew Creamers, expanding the commercial use of cashew ingredients into plant-based beverages. The launch included four varieties Sweet Cream, Cinnamon Churro, Caramel Brulee, and Unsweetened and represents a recent cashew-based product launch connected to downstream demand for cashew kernels.
- In October 2024, Daily Crunch partnered with Fly By Jing to launch Sweet & Spicy Sichuan Sprouted Cashews and Edamame, a new cashew-based snack developed for Whole Foods Market as the brand’s first national retail launch. The product combines sprouted cashews, crispy edamame, and chili flakes, showing a recent product-and-partnership move tied to the broader cashew kernel value chain.
- In April 2025, The Cotton and Cashew Council (CCA) entered a strategic partnership with Coris Bank International and Bridge Bank Côte d’Ivoire through credit agreements worth 30 billion CFA francs, announced after meetings held on 3 and 4 April 2025 in Abidjan. The financing was aimed at supporting Côte d’Ivoire’s 2025 cashew marketing campaign, helping cooperatives and approved buyers purchase raw cashew nuts and improving sector stability.
- In July 2025, the African Cashew Alliance (ACA) signed a Memorandum of Understanding with the All India Cashew Association (AICA) to strengthen cooperation, improve transparency, and jointly address challenges across the cashew industry. The agreement formalized deeper collaboration between African and Indian cashew stakeholders and is a notable recent partnership relevant to the cashew kernel market.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 6583 million |
| Revenue forecast in 2032 | USD 9387.75 million |
| Growth rate (CAGR) | 5.2% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026-2032 |
| Quantitative units | USD million |
| Segments covered | By Product / Form Outlook: White Wholes, Scorched Wholes, Dessert Wholes, White Pieces, Scorched Pieces; By Type / Cultivation Outlook: Conventional, Organic; By Application Outlook: Direct Consumption / Snacks, Bakery & Confectionery, Dairy & Desserts, Cereals and Bars, Foodservice / Ingredients, Other Food Applications |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Archer Daniels Midland Company; Bunge Limited; Nestlé S.A.; The Kraft Heinz Company; John B. Sanfilippo & Son, Inc.; Vietnam Cashew Corporation (VINACAS); Lien Anh Co. Ltd; Haldiram Foods International Private Limited; Alphonsa Cashew Industries; Diamond Foods, LLC; Emerald Nuts, LLC; Aurora Products, Inc.; CBL Natural Foods Private Limited; Prime Nuts FZE; Afokantan Benin Cashew |
| No.of Pages | 330 |
Segmentation
By Product / Form
- White Wholes
- Scorched Wholes
- Dessert Wholes
- White Pieces
- Scorched Pieces
By Type / Cultivation
- Conventional
- Organic
By Application
- Direct Consumption / Snacks
- Bakery & Confectionery
- Dairy & Desserts
- Cereals and Bars
- Foodservice / Ingredients
- Other Food Applications
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Snack Consumption and Premium Nut Mixes
Increasing consumer preference for convenient, nutrient-dense snacks is driving demand for packaged cashew kernels, especially in roasted and flavored formats. Premiumization trends and gifting culture further boost sales of whole-kernel grades and value-added assortments.
Broader Use in Bakery, Confectionery, and Bar Formulations
Food manufacturers are incorporating cashew kernels and pieces into bakery, confectionery, and cereal bar products to enhance texture, visual appeal, and perceived quality. This ingredient-led demand supports steady offtake and premium positioning in finished goods.
Growth of Plant-Forward Desserts and Creamy Texture Applications
Rising interest in plant-based and dairy-alternative recipes is increasing the use of cashew kernels for their creamy texture and mild flavor. This trend is expanding the market into new applications such as plant-based desserts, spreads, and ready-to-use pastes.
Supply Chain Investments in Quality, Grading, and Sourcing Reliability
Investments in processing technology, grading consistency, and traceability are enabling suppliers to meet stringent quality and food safety requirements. Reliable supply and uniformity are critical for branded snack and ingredient buyers, supporting market growth.
Clean-Label and Organic Certification Demand
Consumer concerns about food safety and residues are fueling demand for organic and certified cashew kernels, particularly in premium retail and online channels. Certification-led differentiation allows suppliers to command price premiums and access new market segments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Cashew kernel market?
What is the forecast value of the Cashew kernel market?
What is the growth rate of the Cashew kernel market?
Which segment leads the Cashew kernel market by product/form?
Who are the key players in the Cashew kernel market?
Which region leads the Cashew kernel market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Direct Consumption / Snacks
- 1.2.2 Bakery & Confectionery
- 1.2.3 Dairy & Desserts
- 1.2.4 Cereals and Bars
- 1.2.5 Foodservice / Ingredients
- 1.2.6 Other Food Applications
- 1.3 By Product / Form
- 1.3.1 White Wholes
- 1.3.2 Scorched Wholes
- 1.3.3 Dessert Wholes
- 1.3.4 White Pieces
- 1.3.5 Scorched Pieces
- 1.4 By Type / Cultivation
- 1.4.1 Conventional
- 1.4.2 Organic
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 6,583 million → 2032: USD 9,387.75 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cashew Kernel Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cashew Kernel Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cashew Kernel Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cashew Kernel Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cashew Kernel Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cashew Kernel Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cashew Kernel Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cashew Kernel Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 6,583 million → 2032: USD 9,387.75 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cashew Kernel Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2025-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2025-2032
- 12.3.4 Volume Forecast, 2025-2032
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Direct Consumption / Snacks
- 12.3.7.2 Bakery & Confectionery
- 12.3.7.3 Dairy & Desserts
- 12.3.7.4 Cereals and Bars
- 12.3.7.5 Foodservice / Ingredients
- 12.3.7.6 Other Food Applications
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product / Form - Market Size and Forecast, 2025-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2025-2032
- 12.4.4 Volume Forecast, 2025-2032
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 White Wholes
- 12.4.7.2 Scorched Wholes
- 12.4.7.3 Dessert Wholes
- 12.4.7.4 White Pieces
- 12.4.7.5 Scorched Pieces
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Type / Cultivation - Market Size and Forecast, 2025-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2025-2032
- 12.5.4 Volume Forecast, 2025-2032
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Conventional
- 12.5.7.2 Organic
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cashew Kernel End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Cashew Kernel Geographic Market Outlook, 2025-2032
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Cashew Kernel Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Cashew Kernel Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Archer Daniels Midland Company
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Bunge Limited
- 18.4 Nestlé S.A.
- 18.5 The Kraft Heinz Company
- 18.6 John B. Sanfilippo & Son, Inc.
- 18.7 Vietnam Cashew Corporation (VINACAS)
- 18.8 Haldiram Foods International Private Limited
- 18.9 Diamond Foods, LLC
- 18.10 Emerald Nuts, LLC
- 18.11 Aurora Products, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

