
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cell and Gene Therapy Manufacturing Market Size 2024 | USD 19,305.00 Million |
| Cell and Gene Therapy Manufacturing Market, CAGR | 28.80% |
| Cell and Gene Therapy Manufacturing Market Size 2032 | USD 146,216.60 Million |
Market Overview
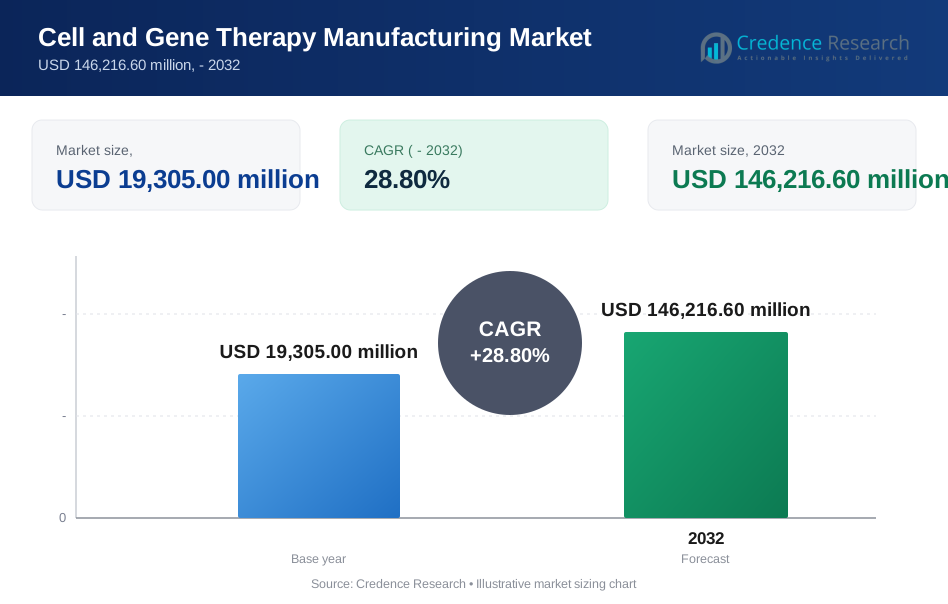
The global Cell and Gene Therapy Manufacturing Market is projected to grow from USD 19,305.00 million in 2024 to an estimated USD 146,216.60 million by 2032, with a compound annual growth rate (CAGR) of 28.80% from 2025 to 2032. This robust growth reflects the increasing demand for advanced therapeutic solutions and innovative manufacturing processes in the biotechnology and pharmaceutical industries.
Several factors drive this market's growth, including advancements in gene editing technologies, such as CRISPR, and increasing investment in personalized medicine. The rising prevalence of genetic disorders, cancer, and rare diseases, combined with the growing acceptance of gene therapies, contributes to the market's acceleration. Furthermore, the development of automated manufacturing processes, improvements in supply chain infrastructure, and the surge in strategic collaborations among pharmaceutical companies and research institutions are critical trends enhancing market growth.
Geographically, North America holds the largest market share, driven by the presence of leading biotech companies and robust healthcare infrastructure. However, regions such as Europe and Asia Pacific are expected to witness substantial growth due to increasing research activities and government initiatives to promote gene therapy. Key players in the global market include Novartis, Gilead Sciences, Bristol Myers Squibb, and Sartorius, who are actively involved in driving innovation and expanding production capacities in cell and gene therapy manufacturing.
Market Insights
- The global Cell and Gene Therapy Manufacturing Market is expected to grow from USD 19,305.00 million in 2024 to USD 146,216.60 million by 2032, driven by advancements in gene therapies and manufacturing processes.
- Technological advancements in gene editing, such as CRISPR, are enabling the development of more precise and effective therapies, accelerating market growth.
- The increasing incidence of genetic disorders, cancer, and rare diseases is driving the demand for innovative gene therapies and personalized medicine solutions.
- The high cost of manufacturing complex cell and gene therapies, along with the need for specialized facilities, is a key challenge in scaling production.
- Stringent regulatory requirements and lengthy approval processes can delay the time-to-market for new therapies, limiting industry growth.
- North America leads the market, supported by a strong biotechnology infrastructure, high demand for advanced therapies, and favorable regulatory frameworks.
- Asia-Pacific is expected to witness substantial market growth due to increasing investments in research, government support for gene therapy, and growing healthcare access.
Market Drivers
Increased Investment and Funding in Biotech and Pharma Research
The global Cell and Gene Therapy Manufacturing Market is also being driven by the surge in investment and funding for biotechnology and pharmaceutical research. Venture capital funding, government grants, and corporate investments are being funneled into the development of gene therapies, which accelerates innovation in manufacturing technologies and processes. The rise in funding has allowed for greater exploration of novel therapeutic options and has provided the necessary financial resources for scaling up production processes.
Additionally, partnerships between pharmaceutical companies and biotech firms are becoming increasingly common. These collaborations combine expertise in drug development with specialized knowledge in manufacturing, facilitating the development of therapies that can be produced at large scales. As more gene therapies receive regulatory approvals, including those from the FDA and EMA, further funding and investment are expected to flow into the market, which will drive the expansion of cell and gene therapy manufacturing capacities.
Regulatory Support and Growing Market Acceptance
Another critical factor driving growth in the global Cell and Gene Therapy Manufacturing Market is the increasing regulatory support and growing acceptance of gene therapies. In recent years, regulatory agencies such as the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) have provided clearer frameworks for the approval of gene and cell therapies. This regulatory clarity helps to streamline the development process, encouraging more players to enter the market.
Additionally, accelerated approval pathways, such as the FDA’s Orphan Drug Designation and Regenerative Medicine Advanced Therapy (RMAT) designation, have made it easier for companies to bring innovative therapies to market more quickly. These regulatory incentives are particularly important for the commercialization of gene therapies, as they provide the necessary pathways to facilitate market access. As gene therapies gain acceptance in clinical settings and patient populations, the demand for manufacturing capabilities continues to rise. Furthermore, the expanding number of commercially available gene therapies, including those for rare diseases and cancers, is fueling broader market acceptance, driving further investment and development in the sector.
Advancements in Gene Editing Technologies
One of the foremost drivers of growth in the global Cell and Gene Therapy Manufacturing Market is the rapid advancement of gene editing technologies. Techniques such as CRISPR-Cas9, TALENs, and ZFNs (Zinc Finger Nucleases) are revolutionizing the way genetic diseases are treated by enabling precise alterations to the DNA of cells. These innovations allow for the development of targeted gene therapies, making treatments more effective and personalized. For instance, CRISPR-Cas9 has successfully alleviated disease phenotypes in mouse models of type 1 diabetes, acute kidney injury, and muscular dystrophy.
TALENs have been used to inactivate the LDL receptor gene in pigs, creating a model for familial hypercholesterolemia. ZFNs have been applied to genetically modify the gol pigment gene and the ntl gene in zebrafish embryos, demonstrating their ability to create heritable mutant alleles. As these technologies become more refined and accessible, the demand for advanced manufacturing solutions to produce gene-edited therapies is expected to grow exponentially, increasing the need for specialized facilities, skilled labor, and complex production methods.
Rising Prevalence of Genetic Disorders and Chronic Diseases
The increasing prevalence of genetic disorders, chronic diseases, and cancer is a major factor driving demand for cell and gene therapies. As healthcare providers and researchers look for new ways to address the root causes of diseases, gene therapies offer a promising avenue for long-term solutions. Genetic disorders such as cystic fibrosis, muscular dystrophy, and hemophilia, along with various types of cancer, have proven difficult to treat with traditional methods. For instance, Down syndrome affects babies born in the U.S. annually, with a similar impact observed in India.
Sickle cell anaemia, cystic fibrosis, and Tay-Sachs disease are among the more common genetic disorders. Regarding chronic diseases, leukemias, brain and nervous system cancers, and lymphomas are the most prevalent malignant diseases in younger subjects. In the United States, high blood pressure, arthritis, respiratory diseases like emphysema, and high cholesterol are among the most common chronic conditions. This growing patient pool accelerates the demand for gene therapies, consequently driving the market for manufacturing capabilities and expansion.
Market Trends
Collaborations and Strategic Partnerships
Another notable trend is the rise of collaborations and strategic partnerships among biotechnology companies, pharmaceutical companies, contract manufacturing organizations (CMOs), and academic institutions. These partnerships are essential for advancing the development and manufacturing of cell and gene therapies, as they combine expertise in drug development with specialized manufacturing capabilities. Biotech firms are increasingly collaborating with larger pharmaceutical companies that have the financial resources and global reach to bring therapies to market. Additionally, partnerships with CMOs are becoming more common as companies seek to outsource the production of gene therapies to specialized facilities with expertise in the complexities of cell and gene therapy manufacturing.
These collaborations allow for the pooling of resources, knowledge, and infrastructure, enabling companies to overcome the challenges associated with the high costs, specialized equipment, and regulatory hurdles involved in gene therapy manufacturing. Furthermore, partnerships with academic and research institutions help to accelerate the discovery and development of new gene therapies, providing a steady pipeline of innovative therapies that require cutting-edge manufacturing capabilities. The trend of collaborations and strategic alliances is expected to continue growing, as companies seek to enhance their manufacturing capabilities, improve operational efficiencies, and shorten the time to market for their therapies.
Advancements in Viral Vector Production Technologies
Viral vectors are essential tools for delivering gene therapies into patient cells, and advancements in viral vector production technologies represent a critical trend in the global Cell and Gene Therapy Manufacturing Market. Viral vectors, such as lentiviruses and adenoviruses, are commonly used to introduce genetic material into the target cells, and their production has traditionally been a bottleneck in the manufacturing process. As the demand for gene therapies increases, there has been a strong push toward improving the efficiency, scalability, and safety of viral vector production. Companies are investing in novel technologies such as suspension cell culture systems, which allow for higher yields of viral vectors, as well as improvements in vector engineering to enhance their safety and efficacy profiles.
Additionally, there is a growing focus on developing viral vector platforms that can be used across a range of therapies, allowing for more efficient and cost-effective production processes. Innovations such as these are helping to overcome some of the key challenges faced by the industry, including high production costs, limited scalability, and long lead times. As advancements in viral vector production continue to emerge, they will further drive the growth and commercialization of gene therapies, facilitating their widespread adoption and paving the way for the next generation of treatments.
Shift Toward Scalable and Automated Manufacturing Processes
A significant trend in the global Cell and Gene Therapy Manufacturing Market is the increasing emphasis on scalable and automated manufacturing processes. Historically, the production of cell and gene therapies has been labor-intensive, highly specialized, and typically carried out in small batches due to the complexity of the therapies involved. However, as the demand for these therapies increases, manufacturers are focusing on developing scalable, automated production processes that can streamline the manufacturing workflow, reduce costs, and meet the growing demand for large-scale production. Automation not only enhances the efficiency and consistency of production but also minimizes the risk of human error, which is critical for the development of gene therapies where precision is paramount.
Companies are investing heavily in developing and implementing technologies such as closed-loop systems, automated cell culture systems, and robotic handling of genetic materials to support the scalability of these complex therapies. For instance, the AUTOSTEM fully automated platform has been developed as a versatile solution for manufacturing and banking cell therapies. This GMP-ready platform allows for tissue collection, isolation, cell expansion, harvest, concentration, and cryopreservation of cell-based products. Its modularity and flexibility enable adaptation to various adherent and suspension cell types, expanding its applicability in cell and gene therapy manufacturing. These advances in automation are not only improving the economics of gene therapy production but are also making therapies more accessible by increasing production efficiency and reducing the time required to bring products to market.
Cell and Gene Therapy Integration with Personalized Medicine
The integration of cell and gene therapies with personalized medicine is another key trend shaping the global market. Personalized medicine refers to the customization of healthcare treatments based on individual genetic profiles, lifestyle, and environmental factors. Gene therapy is intrinsically tied to this concept, as it involves tailoring treatments to address the unique genetic mutations of individual patients. The ability to target specific genetic alterations within a patient's genome allows for more effective and individualized therapies, reducing the risk of adverse reactions and improving the overall success of treatments.
Personalized gene therapies are particularly relevant in the treatment of rare genetic disorders, cancer, and other conditions where traditional treatments may not be as effective. This trend is further supported by advances in gene sequencing, which have made it easier and more cost-effective to identify genetic variations in patients. The ability to design bespoke therapies that target the underlying cause of diseases is pushing the demand for cell and gene therapies, which, in turn, is prompting manufacturers to adapt their processes to meet the requirements of personalized treatments.
Additionally, the FDA's approval of personalized medications, including new molecular entities and cell/gene-based therapies, demonstrates the integration of cell and gene therapies with personalized medicine. These approvals highlight the growing trend of tailoring treatments to individual genetic profiles, offering more precise and effective therapeutic options for patients. As personalized medicine continues to gain traction, cell and gene therapy companies are aligning their strategies with this trend, driving market growth and innovation.
Market Challenges
Regulatory Hurdles and Supply Chain Complexity
Another key challenge in the cell and gene therapy manufacturing market is navigating the complex and evolving regulatory landscape. Regulatory bodies such as the FDA and EMA have stringent requirements for the approval of gene therapies, which can be time-consuming and expensive for manufacturers to meet. The approval process involves rigorous clinical trials, extensive documentation, and the need for long-term monitoring of therapy outcomes. Additionally, the supply chain for gene therapy production is highly specialized and often fragmented, involving numerous stakeholders, including research institutions, biotech firms, contract manufacturing organizations, and regulatory bodies.
Managing the logistics and ensuring the consistency of raw materials, such as viral vectors and cell lines, across different regions can be a significant challenge. The complexity of these processes increases the risk of delays and supply chain disruptions, further escalating costs and hindering the timely delivery of therapies to patients. Effective management of both regulatory requirements and supply chain logistics is critical to ensuring the success of gene therapies in the market.
High Production Costs and Complex Manufacturing Processes in Cell and Gene Therapy
One of the primary challenges facing the global Cell and Gene Therapy Manufacturing Market is the high cost associated with producing these therapies. The manufacturing process is highly complex, requiring advanced technologies, specialized facilities, and skilled labor. For instance, the complexity and high cost are exemplified by the need for specialized facilities and skilled labor to handle custom, small-batch runs, particularly for personalized treatments like autologous cell therapies.
These often involve viral vectors for gene delivery, introducing additional complexity due to stability and performance variability.The production often involves custom, small-batch runs, particularly for personalized treatments, which significantly increases costs. The process requires genetic material manipulation and specialized cell cultures, necessitating rigorous quality control measures to ensure safety and efficacy. This level of precision and customization significantly increases production costs, making these therapies expensive and limiting their scalability and accessibility, especially in regions with limited healthcare resources.As demand grows, manufacturers must invest in new technologies, automation, and scalable systems to meet increasing production needs while trying to lower overall costs.
This challenge is compounded by the need to maintain regulatory compliance, adding another layer of complexity and cost. Despite the potential for significant clinical benefits, the high cost of production remains a barrier to broader adoption and accessibility, particularly in emerging markets.
Market Opportunities
Expanding Applications in Rare and Genetic Diseases
One of the most significant opportunities in the global Cell and Gene Therapy Manufacturing Market lies in the expanding applications of these therapies for rare and genetic diseases. Gene therapies have shown immense promise in treating disorders that were previously considered untreatable, such as rare genetic conditions and inherited diseases. As the global understanding of genetics advances, the identification and development of therapies for these rare conditions present a substantial market opportunity.
With more orphan drug designations and regulatory incentives being introduced by agencies like the FDA and EMA, companies can accelerate the development of these targeted therapies. This creates a pathway for manufacturers to cater to a growing patient population that requires highly specialized, personalized treatment options. Additionally, advancements in gene-editing technologies and precision medicine enable manufacturers to produce therapies tailored to the genetic makeup of individual patients, further expanding the market potential.
Technological Innovations in Manufacturing and Automation
The second major opportunity for the global Cell and Gene Therapy Manufacturing Market is the technological advancements in manufacturing processes and automation. The growing demand for scalable production solutions creates opportunities for manufacturers to adopt innovative technologies that increase efficiency and reduce costs. Automation in the production of gene therapies is critical to improving consistency, reducing human error, and scaling production to meet the rising demand.
Additionally, innovations in closed-loop systems, robotic cell handling, and the development of cost-effective viral vector production platforms are streamlining manufacturing operations. These technological advancements not only enable companies to produce gene therapies at a larger scale but also improve the overall accessibility and affordability of these therapies, opening up new market opportunities across the globe.
Market Segmentation Analysis
By Type
Cell Therapy Manufacturing is further divided into stem cell therapy and non-stem cell therapy. Stem cell therapy is one of the most widely recognized applications, offering potential treatments for a variety of conditions such as blood cancers, autoimmune diseases, and neurodegenerative disorders. Non-stem cell therapies include approaches such as T-cell therapies and CAR-T (Chimeric Antigen Receptor T-cell) therapies, which are increasingly utilized in cancer treatments.Gene Therapy Manufacturing involves the development and production of therapies that target genetic disorders by modifying or repairing genes. With advancements in gene editing technologies, such as CRISPR and TALEN, this segment is experiencing rapid growth, especially in the treatment of rare and inherited genetic diseases, as well as cancers.
By Scale
Pre-commercial/R&D Scale Manufacturing: This segment involves small-scale production aimed at research and development, clinical trials, and regulatory submissions. It requires highly specialized facilities and processes to meet strict regulatory standards. As these therapies progress through clinical phases, this scale serves as the foundation for further development.Commercial scale manufacturing refers to large-scale production after regulatory approval. This scale is essential for meeting the growing demand for approved gene and cell therapies. It requires significant investments in infrastructure, automation, and quality control to ensure consistent production at scale.
Segments
Based on Type
- Cell therapy manufacturing
- Stem cell therapy
- Non stem cell therapy
- Gene therapy manufacturing
Based on Scale
- Pre-commercial/R&D scale manufacturing
- Commercial scale manufacturing
Based on Mode
- Contract manufacturing
- In-house manufacturing
Based on Work Flow
- Cell processing
- Cell banking
- Process development
- Fill & finish operations
- Analytical and quality testing
- Raw material testing
- Vector production
- Others
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America (45%)
North America holds the largest share of the global Cell and Gene Therapy Manufacturing Market, driven by significant investments in research and development, a strong biotechnology infrastructure, and favorable regulatory environments. The United States, in particular, plays a pivotal role due to the presence of leading pharmaceutical and biotechnology companies, such as Gilead Sciences, Novartis, and Vertex Pharmaceuticals, as well as well-established academic and research institutions.
The FDA’s accelerated approval processes, including the Orphan Drug Designation and RMAT (Regenerative Medicine Advanced Therapy) designation, have facilitated faster commercialization of cell and gene therapies. Additionally, the rising prevalence of genetic disorders and cancer in the region has increased demand for advanced therapeutic solutions, further fueling market growth. The region’s strong healthcare infrastructure and increasing adoption of personalized medicine are expected to maintain North America's dominant position in the market.
Europe (30%)
Europe is the second-largest market for cell and gene therapy manufacturing, with countries such as Germany, the UK, and France leading the market. The European Medicines Agency (EMA) provides a favorable regulatory framework, helping companies in Europe expedite the development and approval of cell and gene therapies. Furthermore, the European Union’s support for biotech innovation, coupled with significant investments in healthcare research, has contributed to the region’s growth.
The market is also benefiting from the increasing number of strategic partnerships between biotechnology firms and contract manufacturing organizations (CMOs). As the demand for innovative treatments rises, Europe is becoming a key hub for the development and production of gene therapies, especially in the context of personalized medicine.
Key players
- Hoffmann-La Roche Ltd.
- Catalent Inc.
- Samsung Biologics
- Boehringer Ingelheim
- Miltenyi Biotec
- Merck KGaA
Competitive Analysis
The global Cell and Gene Therapy Manufacturing Market is highly competitive, with leading players such as F. Hoffmann-La Roche Ltd., Catalent Inc., and Samsung Biologics shaping the industry landscape. These companies leverage advanced manufacturing technologies and strong R&D capabilities to stay at the forefront of market development. F. Hoffmann-La Roche Ltd. is renowned for its extensive product portfolio and strategic business alliances, enabling it to maintain a dominant market position.
Catalent Inc. stands out with its focus on providing end-to-end solutions for gene therapy, from development to commercial-scale manufacturing. Samsung Biologics offers cutting-edge biologics manufacturing services and has expanded its capabilities to include gene therapy production. Boehringer Ingelheim, Miltenyi Biotec, and Merck KGaA are also key players, each focusing on specialized areas such as viral vector production, gene editing, and cell therapy solutions. These companies’ robust strategies and innovative solutions are critical to maintaining their competitive edge in a rapidly evolving market.
Recent Developments
- In February 2026, Johnson & Johnson announced an investment of more than $1 billion to build a next-generation cell therapy manufacturing facility in Pennsylvania focused on personalized cell therapies, including treatments targeting multiple myeloma.
- In February 2026, Cellipont Bioservices and Soter Bio announced a strategic collaboration to offer integrated U.S.-based manufacturing for complex cell therapy programs that require coordinated biomolecule and cellular processing.
- In January 2026, Cellares raised $257 million in a Series D financing to fund the global rollout of automated IDMO Smart Factories and said the network would support clinical manufacturing in the first half of 2026.
- In January 2026, Autolus Therapeutics announced it would evaluate automated manufacturing of AUCATZYL (obe-cel) on Cellares’ Cell Shuttle platform to complement its commercial manufacturing operations and prepare for expansion into new indications.
Market Concentration and Characteristics
The global Cell and Gene Therapy Manufacturing Market exhibits moderate to high market concentration, with a few key players dominating the landscape. Leading companies such as F. Hoffmann-La Roche Ltd., Catalent Inc., and Samsung Biologics control significant market share due to their extensive resources, advanced manufacturing technologies, and established expertise in the development of gene and cell therapies. However, the market also sees the emergence of smaller, specialized firms focusing on niche areas like viral vector production and personalized medicine. The market is characterized by a rapidly evolving competitive environment, driven by technological advancements, stringent regulatory requirements, and growing demand for innovative therapies. Strategic partnerships, collaborations, and acquisitions are common as companies seek to enhance their manufacturing capabilities and broaden their service offerings, further shaping the market's concentration and competitive dynamics.
Report Coverage
The research report offers an in-depth analysis based on Type, Scale, Mode, Work Flow and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to witness a surge in investment in advanced manufacturing technologies, including automation and AI-driven systems, to improve scalability and reduce production costs.
- As personalized medicine continues to gain traction, the demand for tailored cell and gene therapies will drive the market, requiring manufacturers to develop customized production processes.
- The growing need for gene therapies will increase the demand for viral vectors, prompting manufacturers to focus on enhancing viral vector production techniques to meet clinical and commercial requirements.
- Regulatory bodies worldwide are likely to streamline approval processes for cell and gene therapies, providing more clarity and faster pathways for market entry, boosting industry growth.
- With continued advancements in gene editing technologies such as CRISPR, the market will expand as these tools make gene therapies more precise and effective for a broader range of conditions.
- The increasing prevalence of rare genetic diseases will drive the demand for gene therapies, prompting manufacturers to scale production and enhance their therapeutic offerings for orphan diseases.
- Partnerships between biotech firms, pharmaceutical companies, and contract manufacturers will intensify, helping companies leverage complementary expertise in research, development, and manufacturing.
- Manufacturers will prioritize developing scalable, cost-efficient solutions to meet the growing global demand for gene and cell therapies while ensuring consistent quality and regulatory compliance.
- As emerging markets, particularly in Asia-Pacific, show increased adoption of advanced therapeutic solutions, companies will focus on establishing local manufacturing hubs to meet regional demand.
- The demand for commercial-scale production will drive companies to expand their facilities and invest in state-of-the-art technologies, enabling them to meet the global market’s growing therapeutic needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the global Cell and Gene Therapy Manufacturing Market in 2023 and 2032?
What factors are driving the growth of the Cell and Gene Therapy Manufacturing Market?
Which regions dominate the global Cell and Gene Therapy Manufacturing Market?
What are the key trends in the Cell and Gene Therapy Manufacturing Market?
Who are the leading players in the global Cell and Gene Therapy Manufacturing Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Cell and Gene Therapy Manufacturing Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Cell and Gene Therapy Manufacturing Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (2032) (base year: USD 19,305.00 million → 2032: USD 146,216.60 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Cell and Gene Therapy Manufacturing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Cell and Gene Therapy Manufacturing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Cell and Gene Therapy Manufacturing Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Cell and Gene Therapy Manufacturing Market Drivers
- 3.3 Cell and Gene Therapy Manufacturing Market Restraints & Challenges
- 3.4 Cell and Gene Therapy Manufacturing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Cell and Gene Therapy Manufacturing Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Cell and Gene Therapy Manufacturing Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Cell and Gene Therapy Manufacturing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Cell and Gene Therapy Manufacturing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Cell and Gene Therapy Manufacturing Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Cell and Gene Therapy Manufacturing market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Cell and Gene Therapy Manufacturing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Cell and Gene Therapy Manufacturing Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Cell and Gene Therapy Manufacturing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Cell and Gene Therapy Manufacturing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Cell and Gene Therapy Manufacturing Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Cell and Gene Therapy Manufacturing Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & 2032)
- 7.1.2 Channel Mix Evolution (2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Cell and Gene Therapy Manufacturing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Cell and Gene Therapy Manufacturing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Cell and Gene Therapy Manufacturing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Cell and Gene Therapy Manufacturing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Cell and Gene Therapy Manufacturing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Cell and Gene Therapy Manufacturing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Cell and Gene Therapy Manufacturing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
