
Market Overview:
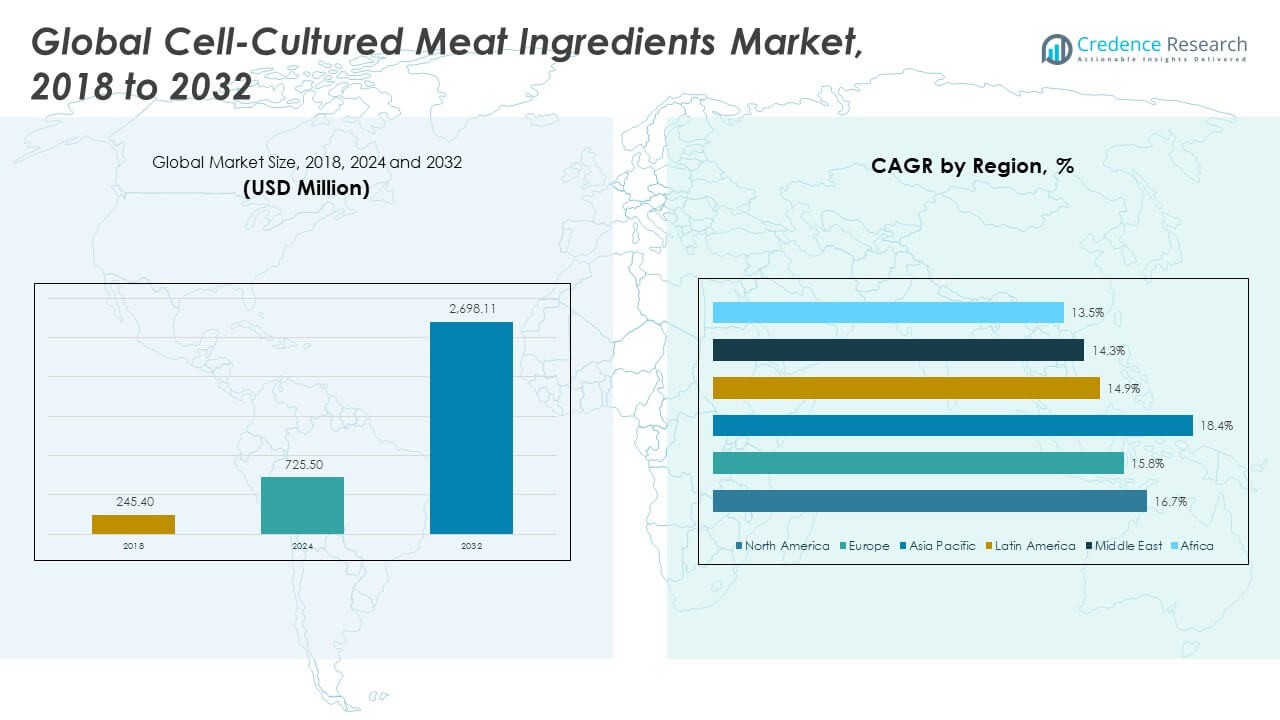
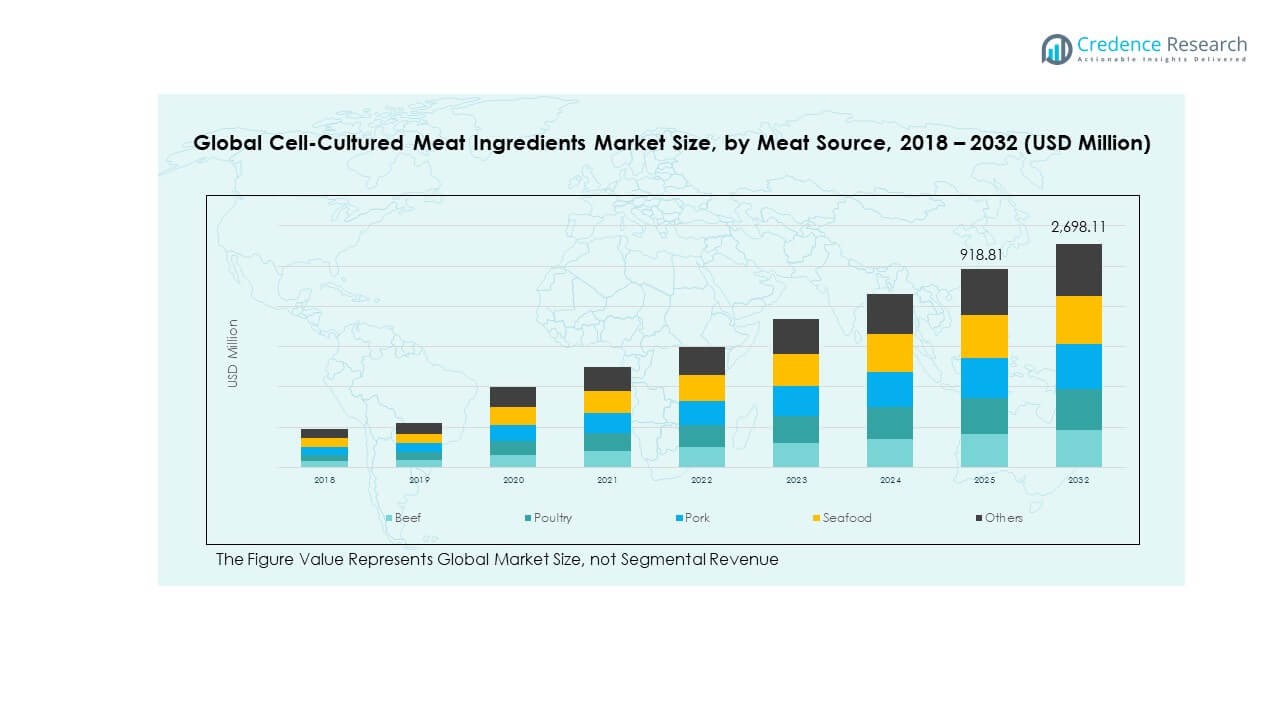
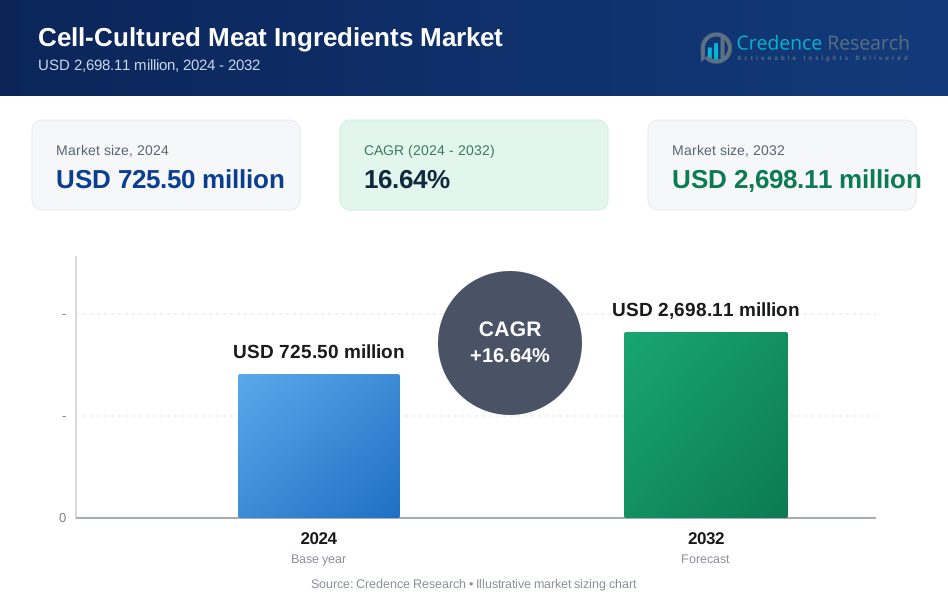
The Cell-Cultured Meat Ingredients Market size was valued at USD 245.40 million in 2018, reached USD 725.50 million in 2024, and is anticipated to reach USD 2,698.11 million by 2032, at a CAGR of 16.64% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cell-Cultured Meat Ingredients Market Size 2024 | USD 725.50 Million |
| Cell-Cultured Meat Ingredients Market, CAGR | 16.64% |
| Cell-Cultured Meat Ingredients Market Size 2032 | USD 2,698.11 Million |
Growth in this market is driven by the rising demand for sustainable, ethical, and safe protein alternatives. Manufacturers invest in advanced bioprocessing and cell-line engineering to improve scalability and cost efficiency. Biotech firms enhance media formulations and scaffolding systems to deliver better texture and nutritional quality. Government funding programs promote innovation in cellular agriculture, while startups collaborate with food giants to accelerate commercialization. It benefits from the expanding awareness of environmental impact and food safety, which boosts consumer confidence and adoption.
North America leads the market due to early regulatory frameworks, large-scale pilot projects, and strong venture funding. Europe follows with robust research activity and high consumer acceptance of sustainable protein sources. The Asia Pacific region emerges fastest, supported by food security initiatives and government investments in alternative proteins. The Middle East expands gradually through strategic food-tech investments, while Latin America and Africa show early-stage development, driven by regional collaborations and innovation hubs focused on cost-effective production.
Market Insights:
- The Global Cell-Cultured Meat Ingredients Market was valued at USD 245.40 million in 2018, reached USD 725.50 million in 2024, and is projected to reach USD 2,698.11 million by 2032, growing at a CAGR of 16.64%.
- North America (41.5%), Europe (27%), and Asia Pacific (23.6%) dominate the market due to strong research infrastructure, government support, and early regulatory adoption.
- Asia Pacific is the fastest-growing region, driven by food security initiatives, investment in cellular agriculture, and expanding middle-class demand for sustainable proteins.
- By meat source, beef accounts for around 36% of the market share, supported by consumer preference for sustainable red meat alternatives.
- Poultry holds approximately 28%, driven by shorter cell cycles and cost-efficient production processes suited for large-scale commercial deployment.
Market Drivers
Growing Demand for Sustainable and Ethical Protein Production
The Global Cell-Cultured Meat Ingredients Market grows rapidly due to the global shift toward sustainability and ethical sourcing. Consumers prefer alternatives that limit animal slaughter and environmental degradation. Brands promote cultured protein as a climate-conscious food solution. It supports efficient land and water usage compared to traditional livestock systems. Governments invest in sustainable meat innovation to meet carbon neutrality goals. Food producers explore lab-grown meat ingredients to ensure ethical food chains. Biotech firms align production models with clean-label expectations. This push for responsible consumption accelerates large-scale adoption across developed and emerging economies.
Rising Technological Advancements in Cell Cultivation and Bioprocess Engineering
Advances in cell-line engineering and nutrient formulation drive faster production cycles. It enhances tissue quality and supports large-scale cell replication under sterile conditions. Companies integrate automation in bioreactors to improve consistency and control. Research centers develop serum-free media that lower dependency on animal-derived inputs. The Global Cell-Cultured Meat Ingredients Market benefits from scalable cell proliferation systems that boost yield. Ingredient suppliers invest in advanced scaffolding materials for better texture. Bioengineering teams design hybrid growth systems that support continuous processing. These innovations reduce costs and make cultured meat commercially viable.
- For instance, Upside Foods has developed an animal-component-free serum-free growth medium that supports efficient cell proliferation with comparable growth rates to conventional media, a breakthrough enabling cost reduction and commercial scale-up.
Growing Government Funding and Regulatory Support
Public institutions and funding agencies promote research in cellular agriculture. It strengthens infrastructure for ingredient production and accelerates commercialization timelines. National food agencies create frameworks that clarify safety testing and labeling standards. The Global Cell-Cultured Meat Ingredients Market receives momentum from pilot approvals and subsidies. Companies collaborate with universities to validate technology through controlled trials. Governments encourage private partnerships to boost innovation clusters. Policy incentives for low-emission protein sources improve investor confidence. Expanding grants and national food-tech programs secure long-term support for market development.
Expanding Consumer Awareness and Market Acceptance
Awareness campaigns and media coverage boost acceptance of cultured protein sources. Consumers understand the nutritional equivalence between cultured and traditional meat. The Global Cell-Cultured Meat Ingredients Market benefits from marketing narratives centered on health and sustainability. It gains traction among millennials seeking clean and traceable food. Retail channels promote lab-grown options as futuristic yet safe. Influencers and chefs highlight taste parity achieved through precision cultivation. Health-conscious buyers associate cultured meat with reduced antibiotic risk. Increasing transparency helps bridge perception gaps and fosters mainstream adoption.
- For instance, Aleph Farms has hosted multiple public tasting events and chef collaborations serving thousands of consumers, demonstrating cultured steaks with confirmed taste parity and supporting market acceptance.
Market Trends
Rising Focus On Serum-Free and Plant-Derived Growth Media
Manufacturers move toward plant-based growth media to minimize production cost and ethical issues. It allows consistent performance while eliminating animal-origin inputs. Researchers optimize nutrient blends to balance protein density and growth rates. The Global Cell-Cultured Meat Ingredients Market sees a steady shift toward eco-friendly formulations. Companies refine amino acid and peptide ratios to maintain cell vitality. Start-ups explore algae and yeast extracts for high-value media production. New media platforms improve scalability and sustainability metrics. This trend positions serum-free systems as key enablers of cost reduction.
Adoption of 3D Bioprinting and Scaffolding for Texture Optimization
Producers implement 3D bioprinting to replicate muscle fiber structures with accuracy. It supports realistic texture and marbling in finished cultured meat. Developers focus on edible scaffolds made from natural polymers and proteins. The Global Cell-Cultured Meat Ingredients Market gains from hybrid printing models that ensure uniform nutrient flow. Advanced scaffolds improve cell adhesion and maturation across layers. Research teams test multi-material combinations for better sensory output. Companies utilize bioprinting to achieve tailored meat cuts. These advancements enhance realism and consumer satisfaction in final products.
Increased Entry of Traditional Meat and Food Giants
Large food corporations invest in cell-cultured ingredient start-ups to diversify protein portfolios. It boosts access to capital, expertise, and global distribution networks. The Global Cell-Cultured Meat Ingredients Market benefits from strategic alliances that accelerate commercialization. It gains visibility through joint ventures focused on hybrid and ready-to-cook cultured products. Established brands leverage trust and brand recognition to enhance acceptance. Mergers strengthen research pipelines for cell source and nutrient optimization. Partnerships encourage standardized protocols for industrial-scale production. These collaborations bridge the gap between innovation and market readiness.
- For instance, Tyson Foods invested in Memphis Meats (now Upside Foods) to support pilot-plant development, and JBS S.A. backed Future Meat Technologies (now Believer Meats) to accelerate large-scale bioreactor deployment for cultivated-meat production.
Emergence of Regional Innovation Clusters and Pilot Facilities
Biotech hubs form across Asia, Europe, and North America to streamline R&D and pilot testing. The Global Cell-Cultured Meat Ingredients Market thrives on shared infrastructure that supports local entrepreneurs. Governments designate research parks for cellular agriculture incubation. It encourages cost-sharing across media formulation and bioreactor engineering. Regional collaborations create employment and accelerate regulatory approval pathways. Countries establish certification systems to support export readiness. Early adopters attract foreign investors to expand production scale. These clusters evolve into long-term innovation ecosystems.
- For instance, the Singapore Food Agency approved GOOD Meat’s cultivated chicken production using serum-free media, marking the world’s first regulatory approval for animal-free cell culture media in commercial cultivated meat manufacturing.
Market Challenges Analysis
High Cost of Production and Limited Scalability
The Global Cell-Cultured Meat Ingredients Market faces high production expenses linked to nutrient media and energy inputs. Companies struggle to maintain consistent yields in large-scale facilities. Specialized bioreactors and growth factors increase capital burden. It restricts smaller firms from entering due to limited funding access. High infrastructure requirements affect competitive pricing in developing regions. Engineering teams still refine systems to achieve industrial throughput. Unstable raw material availability raises maintenance challenges. Cost reduction remains the main obstacle to widespread commercialization.
Regulatory Uncertainty and Consumer Skepticism
Varying regulations across countries create uncertainty for producers and investors. National food safety authorities require extensive testing before commercial approval. It delays time-to-market and limits cross-border trade opportunities. The Global Cell-Cultured Meat Ingredients Market faces mixed consumer opinions regarding product authenticity. Confusion about labeling and safety claims affects initial adoption. Producers must balance innovation with strict compliance documentation. Regional differences in policy frameworks slow down coordinated growth. Strong education and outreach remain essential to build long-term trust.
Market Opportunities
Integration of AI and Automation for Process Optimization
Automation systems and AI-driven analytics improve precision in cell cultivation. It supports predictive monitoring for growth cycles and nutrient balance. The Global Cell-Cultured Meat Ingredients Market gains efficiency through machine-controlled bioreactors. Intelligent sensors allow real-time corrections to maintain yield quality. Automated systems reduce labor dependency in cleanroom environments. Predictive maintenance cuts downtime and improves process stability. Integration with digital twins accelerates large-scale expansion. These technologies open new paths for industrial-level consistency.
Expansion into Pet Food and Functional Ingredient Applications
Pet food producers adopt cultured protein as a clean and allergen-free alternative. It provides high digestibility and nutritional alignment with sustainability goals. The Global Cell-Cultured Meat Ingredients Market diversifies its reach through this emerging application. It helps companies balance risk while exploring non-human consumption sectors. Functional ingredient developers test bioactive compounds derived from cultured cells. The approach supports premium segments within animal nutrition. Food innovation firms invest in co-development for these specialized uses. Expanding beyond traditional meat markets creates lasting revenue channels.
Market Segmentation Analysis:
The Global Cell-Cultured Meat Ingredients Market is divided by meat source, cell source, application, and end user.
By meat source, beef leads due to strong consumer demand for sustainable red meat alternatives. Poultry follows closely, supported by shorter cell cycles and cost-effective production. Pork gains traction in regions with high processed meat use. Seafood segments expand with focus on marine species that address overfishing concerns. Others, including exotic and hybrid meats, cater to niche food innovation projects emphasizing premium protein profiles.
- For instance, Believer Meats, a leader in cultivated meat, has built the world’s largest cultivated chicken production facility in Wilson, North Carolina, covering 200,000 square feet and capable of producing up to 12,000 metric tons (26 million pounds) of cultivated chicken annually, showcasing scalability for sustainable meat production without animal slaughter.
By cell source, adult stem cells dominate due to proven reliability and ease of differentiation. Embryonic stem cells provide high growth potential for complex tissue structures. Induced pluripotent stem cells (iPSCs) attract R&D investment for flexibility across multiple meat types. Satellite cells enable efficient muscle formation in bioreactors, improving yield control. Others, including specialized progenitor cells, offer experimental advantages for future formulations.
By application, the human food industry captures most of the demand, driven by large-scale commercialization and sustainability goals. The pet food industry grows steadily as brands introduce high-protein, allergen-free formulations.
By end user, retailers focus on expanding product reach through premium sections. Restaurants integrate cultured protein into modern menus to attract eco-conscious customers. E-commerce platforms emerge as a fast-growing channel, offering direct-to-consumer availability and global market access. Together, these segments reflect a diverse and rapidly evolving ecosystem that supports technological and commercial expansion.
- For instance, Australian company Vow Foods received regulatory approval from Food Standards Australia New Zealand (FSANZ) in 2024 to use cultivated quail cells in food products, marking the first cultivated meat approval in Australia and a major step toward commercial market entry.
Segmentation:
By Meat Source
- Beef
- Poultry
- Pork
- Seafood
- Others
By Cell Source
- Adult Stem Cells
- Embryonic Stem Cells
- Induced Pluripotent Stem Cells (iPSCs)
- Satellite Cells
- Others
By Application
- Human Food Industry
- Pet Food Industry
By End User
- Retailers
- Restaurants
- E-Commerce
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Global Cell-Cultured Meat Ingredients Market size was valued at USD 102.69 million in 2018, reached USD 300.30 million in 2024, and is anticipated to reach USD 1,120.04 million by 2032, at a CAGR of 16.7% during the forecast period. North America holds around 41.5% of the global market share, driven by strong biotechnology infrastructure and early regulatory progress. The U.S. leads regional demand with major research hubs and pilot-scale production sites. Canada supports development through food innovation programs that focus on clean protein growth. It benefits from high consumer awareness and investment in sustainable alternatives. Companies such as Eat Just and Upside Foods establish large-scale facilities to serve mainstream food channels. Partnerships between food-tech firms and traditional meat processors strengthen local production ecosystems. Venture capital funding continues to flow into next-generation ingredient startups. This region remains the testing ground for industrial and retail-scale deployment.
Europe
The Europe Global Cell-Cultured Meat Ingredients Market size was valued at USD 72.72 million in 2018, reached USD 207.58 million in 2024, and is anticipated to reach USD 728.81 million by 2032, at a CAGR of 15.8% during the forecast period. Europe accounts for about 27% of the global market share. Strong regulatory oversight and high ethical food awareness drive adoption. The Netherlands, Germany, and the U.K. host several leading cultured meat developers. It benefits from regional grants supporting bioprocess research and sustainable protein policies. Startups receive institutional support through the EU’s alternative protein programs. Consumers in major economies show strong acceptance of lab-grown protein. Europe’s food safety agencies push structured labeling frameworks that aid commercialization. The region’s leadership in clean food innovation sustains steady growth across applications.
Asia Pacific
The Asia Pacific Global Cell-Cultured Meat Ingredients Market size was valued at USD 47.23 million in 2018, reached USD 151.33 million in 2024, and is anticipated to reach USD 637.38 million by 2032, at a CAGR of 18.4% during the forecast period. Asia Pacific represents around 23.6% of the global market share and grows fastest among all regions. Strong food security initiatives and rapid urbanization drive regional interest. China, Japan, and Singapore invest heavily in cellular agriculture projects. It benefits from government incentives promoting alternative protein self-sufficiency. Regional startups collaborate with global ingredient suppliers to scale bioprocess innovation. Singapore remains a regulatory pioneer with early product approvals. Expanding middle-class populations support premium protein adoption. This region stands as the future growth engine for global cultured meat production.
Latin America
The Latin America Global Cell-Cultured Meat Ingredients Market size was valued at USD 11.62 million in 2018, reached USD 33.92 million in 2024, and is anticipated to reach USD 111.70 million by 2032, at a CAGR of 14.9% during the forecast period. Latin America holds nearly 4.1% of the total global market share. Brazil dominates regional activity with early trials in lab-grown beef ingredients. Argentina and Chile strengthen innovation partnerships through academic programs in cellular agriculture. It gains support from agritech networks adapting to sustainable protein models. Local firms explore bioreactor systems suitable for regional meat demand. The region’s lower production cost base offers competitive export potential. Rising consumer interest in sustainable foods supports pilot launches. Latin America’s transformation builds the foundation for regional ingredient production hubs.
Middle East
The Middle East Global Cell-Cultured Meat Ingredients Market size was valued at USD 7.15 million in 2018, reached USD 19.38 million in 2024, and is anticipated to reach USD 61.29 million by 2032, at a CAGR of 14.3% during the forecast period. The Middle East captures about 2.3% of the global market share. Food security challenges drive strong government focus on sustainable meat technologies. The UAE and Israel lead with pilot facilities and R&D collaborations. It benefits from sovereign investment funds supporting food-tech ventures. Regional universities contribute to media formulation research and scalable bioreactor design. Halal certification discussions guide regulatory readiness for cultured protein use. Cross-border trade programs enhance supply reliability for high-demand zones. The Middle East’s innovation-driven model positions it as a rising contributor to global capacity.
Africa
The Africa Global Cell-Cultured Meat Ingredients Market size was valued at USD 3.99 million in 2018, reached USD 12.98 million in 2024, and is anticipated to reach USD 38.89 million by 2032, at a CAGR of 13.5% during the forecast period. Africa represents about 1.4% of the global market share. Early-stage investments focus on food innovation and agricultural modernization. South Africa leads with research partnerships exploring cultured beef and poultry. Egypt’s biotechnology hubs start pilot testing of ingredient formulations. It benefits from growing urban demand for sustainable food sources. Local universities develop cost-efficient nutrient blends suited to regional conditions. Limited infrastructure remains a restraint but also creates room for foreign collaboration. Support from development agencies accelerates awareness of clean protein benefits. Africa stands at the beginning of its cultured protein transformation journey.
Key Player Analysis:
- Eat Just
- Upside Foods
- Mosa Meat
- Aleph Farms
- Meatable
- Mission Barns
- Fork and Good
- Steakholder Foods
- Vow Foods
- Others
Competitive Analysis:
The Global Cell-Cultured Meat Ingredients Market features numerous players who push innovation in growth media, scaffolding and scale-up technologies. Leading companies such as Eat Just, Upside Foods, Mosa Meat and Aleph Farms secure patents and form strategic partnerships with ingredient suppliers to strengthen downstream supply chains. It places emphasis on licensing agreements and joint ventures to gain geographic reach and regulatory approval. Competitors deploy acquisitions to access niche technologies and boost ingredient portfolios. Some firms optimize production to lower cost per kilogram and improve product texture, while others focus on premium segments such as seafood analogues or hybrid meat formats. Public-private collaborations and venture funding funnel resources toward process efficiency and sustainability. Competitive intensity remains high and will drive consolidation and differentiation across global markets.
Recent Developments:
- In October 2025, Gourmey acquired Vital Meat to form Parima, creating a scalable cross-species platform for cultivated duck and chicken products. This merger aims at global market expansion with nine regulatory filings underway. Parima focuses on cost efficiency and industrial-scale production to advance cultivated meat commercialization.
- In November 2025, WACKER launched its bioengineered growth factor "Recombinant bovine FGF-basic Food" (FGF-2 Food), specially developed for cultivated meat production. The first batches are available with deliveries starting in the fourth quarter of 2025. This food-grade growth factor promotes cell proliferation in muscle and connective tissue cells, enabling animal-free cell culture media and supporting cost reduction and scalability in cultivated meat production.
- In December 2024, Cult Food Science Corp. announced plans to acquire The Better Butchers Inc., a company specializing in fungi-based proteins and hybrid cultivated meats. This acquisition aims to advance cultivated meat technology and expand product offerings in meat alternatives.
Report Coverage:
The research report offers an in-depth analysis based on meat source, cell source, application, and end user. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Global Cell-Cultured Meat Ingredients Market will expand rapidly through advanced bioprocessing and sustainable production technologies.
- Research in serum-free growth media will continue to improve scalability and cost efficiency.
- Partnerships between biotech firms and major food producers will strengthen global supply chains.
- Market focus will shift toward hybrid and functional ingredient categories supporting broader applications.
- Regional production hubs will emerge, with Asia Pacific leading in pilot approvals and government funding.
- Consumer acceptance will grow through improved taste profiles, nutritional transparency, and ethical branding.
- Automation and AI-based monitoring systems will enhance yield consistency and reduce operational costs.
- Policy frameworks in North America and Europe will set international standards for cultured meat safety.
- Investors will prioritize projects with carbon-neutral and low-water footprint production systems.
- Continuous innovation in cell-line optimization will support long-term market stability and competitive differentiation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Global Cell-Cultured Meat Ingredients Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Cell-Cultured Meat Ingredients Market projected to grow between 2024 and 2032?
Which Global Cell-Cultured Meat Ingredients Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Cell-Cultured Meat Ingredients Market?
Who are the leading companies in the Global Cell-Cultured Meat Ingredients Market?
Which region commanded the largest share of the Global Cell-Cultured Meat Ingredients Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Cell-Cultured Meat Ingredients Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Cell-Cultured Meat Ingredients Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 725.50 million → 2032: USD 2,698.11 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Cell-Cultured Meat Ingredients Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Cell-Cultured Meat Ingredients Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Cell-Cultured Meat Ingredients Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Cell-Cultured Meat Ingredients Market Drivers
- 3.3 Cell-Cultured Meat Ingredients Market Restraints & Challenges
- 3.4 Cell-Cultured Meat Ingredients Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Cell-Cultured Meat Ingredients Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Cell-Cultured Meat Ingredients Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Cell-Cultured Meat Ingredients category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Cell-Cultured Meat Ingredients Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Cell-Cultured Meat Ingredients Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Cell-Cultured Meat Ingredients market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Cell-Cultured Meat Ingredients Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Cell-Cultured Meat Ingredients Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Cell-Cultured Meat Ingredients Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Cell-Cultured Meat Ingredients (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Cell-Cultured Meat Ingredients Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Cell-Cultured Meat Ingredients Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Cell-Cultured Meat Ingredients Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Cell-Cultured Meat Ingredients Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Cell-Cultured Meat Ingredients Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Cell-Cultured Meat Ingredients Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Cell-Cultured Meat Ingredients Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Cell-Cultured Meat Ingredients Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Cell-Cultured Meat Ingredients Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
