
Market Overview
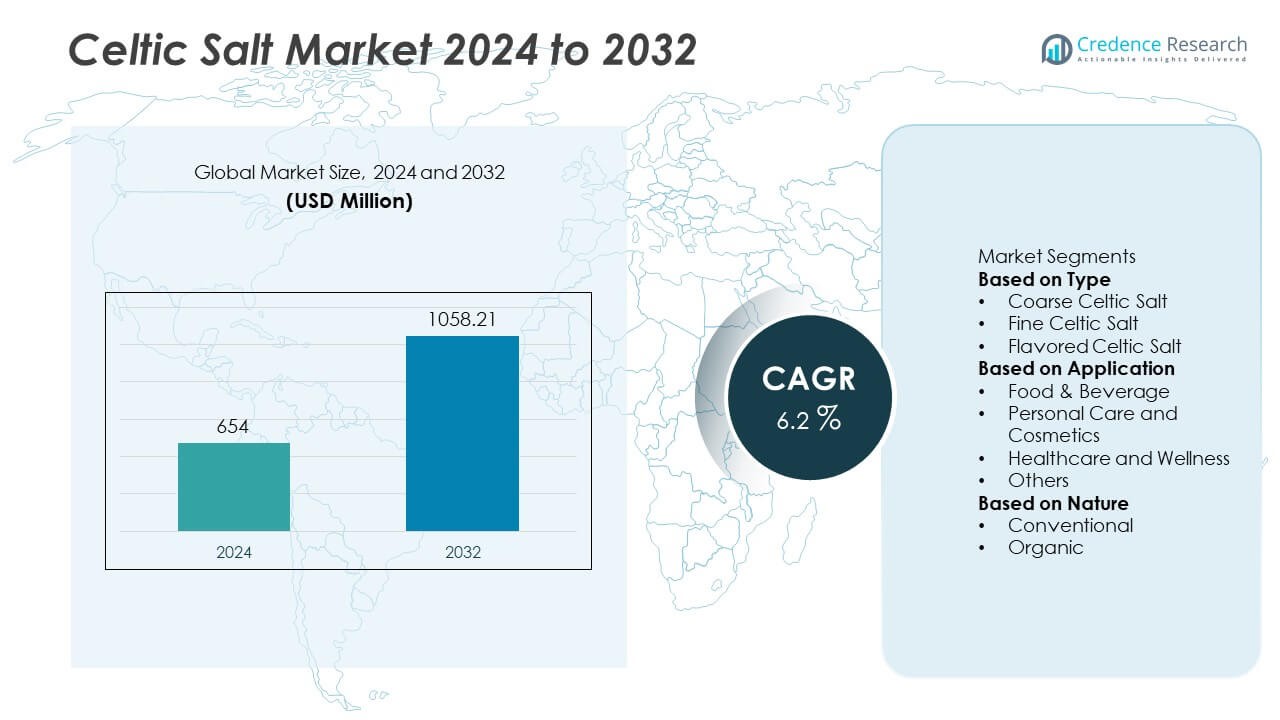
The Celtic Salt Market was valued at USD 654 million in 2024 and is expected to reach USD 1,058.21 million by 2032, registering a CAGR of 6.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Celtic Salt Market Size 2024 | USD 654 Million |
| Celtic Salt Market, CAGR | 6.2% |
| Celtic Salt Market Size 2032 | USD 1,058.21 Million |
The top players in the Celtic Salt market include Selina Naturally, Celtic Sea Salt Brand, SaltWorks Inc., San Francisco Salt Company, Maine Sea Salt Company, Cornish Sea Salt Co., Maldon Crystal Salt Company, HimalaSalt, Baja Gold Sea Salt, and The Salt Company of Iceland, each focusing on mineral-rich salt harvesting and clean-label positioning. Europe leads the market with a 37% share, supported by strong consumer demand for artisanal and natural gourmet salts. North America follows with a 32% share, driven by rising use in premium food products, wellness supplements, and personal care formulations. Asia Pacific holds a 20% share, expanding due to growing interest in nutrient-dense specialty salts and natural seasoning alternatives across emerging health-focused markets.
Market Insights
- The Celtic Salt market reached USD 654 million in 2024 and is projected to reach USD 1,058.21 million by 2032, registering a CAGR of 6.2% during the forecast period.
- Rising demand for mineral-rich, unrefined gourmet salts drives market growth, with Coarse Celtic Salt holding a 48% segment share due to strong use in culinary seasoning and food processing.
- Key trends include rising preference for clean-label, trace-mineral salts and growing product expansion in flavored blends supporting functional health and premium food applications.
- Competitive landscape features Selina Naturally, SaltWorks Inc., San Francisco Salt Company, and Cornish Sea Salt Co., focusing on sustainable harvesting, wellness branding, and expanding retail distribution across organic and specialty food channels.
- Europe leads with a 37% share due to strong gourmet salt usage, followed by North America at 32% driven by food, wellness, and personal care adoption, while Asia Pacific holds 20% supported by rising natural ingredient consumption and premium seasoning demand.
 Market Segmentation Analysis:
By Type
Coarse Celtic salt holds the largest 48% share of the Celtic Salt market, driven by its high mineral content, traditional harvesting methods, and growing preference for artisanal culinary ingredients. Consumers and gourmet chefs use coarse crystals for seasoning, salt curing, meat preservation, and cooking applications that benefit from slow-dissolving salt structure. Fine Celtic salt continues to gain traction in bakery, snacks, and table-use applications due to its easier solubility, while flavored Celtic salt expands in premium seasoning blends. Rising demand for clean-label, unrefined, and mineral-rich salt varieties supports continued growth across all product types.
- For instance, SaltWorks Inc. operates a 100,000-square-foot production facility in Woodinville, Washington, where the company processes a large volume of specialty sea salt each year using proprietary Optically Clean® technology, a chemical-free process which uses high-definition cameras and air jets to inspect every crystal and remove foreign material.
By Application
Food and beverage applications dominate with a 61% share, supported by rising adoption in gourmet foods, bakery items, premium snacks, meat products, and artisanal cooking. Celtic salt is valued for its trace minerals, lower sodium perception, and moist crystalline texture, appealing to health-conscious consumers seeking natural alternatives to refined table salt. The personal care and cosmetics segment grows due to increasing use in bath salts, scrubs, and mineral-rich skin formulations, while healthcare and wellness applications benefit from demand for electrolyte balance and natural mineral supplements. Expansion of specialty retail and e-commerce platforms strengthens market penetration.
- For instance, Cornish Sea Salt Co. supplies mineral-rich sea salt to food manufacturers and skincare brands, and laboratory analysis confirms the presence of more than 60 naturally occurring trace minerals, including minerals like calcium, potassium, and magnesium.
By Nature
Conventional Celtic salt accounts for a leading 67% share, driven by wider production availability, strong commercial distribution, and competitive pricing in bulk supply for food manufacturers and retailers. Organic Celtic salt shows faster growth as consumers associate organic certification with purity, sustainable harvesting, and environmentally responsible practices. Increasing interest in natural functional ingredients and premium culinary salts supports growth potential for both formats. Manufacturers focus on transparent sourcing, eco-friendly packaging, and certification standards to strengthen brand value and expand presence in global health food markets.
Key Growth Drivers
Increasing Demand for Natural and Mineral-Rich Salt Alternatives
Consumers increasingly shift toward natural, unrefined, and mineral-rich salts, driving strong demand for Celtic salt. Its higher levels of magnesium, calcium, and trace electrolytes support positioning in health-focused diets and clean-label food formulations. The growing rejection of chemically processed table salt encourages food manufacturers and gourmet brands to incorporate Celtic salt into premium seasoning blends and packaged foods. Health-conscious consumers and culinary professionals value its mild flavor and moist texture, supporting broader adoption across retail and food service channels, which strengthens market expansion.
- For instance, Selina Naturally's laboratory analysis shows that Celtic Sea Salt contains trace minerals, including magnesium and calcium. Celtic Sea Salt and other unrefined sea salts are known to contain a range of minerals and trace elements. Selina Naturally, a producer of Celtic Sea Salt, is a company that exports its products to distributors.
Rising Use in Functional Food, Wellness, and Nutraceutical Products
Celtic salt increasingly appears in electrolyte supplements, mineral tonics, wellness beverages, and herbal formulations aimed at restoring hydration and promoting metabolic balance. As consumers emphasize preventive health and holistic nutrition, naturally harvested salt varieties gain more credibility as functional ingredients. The wellness industry promotes Celtic salt for potential benefits in pH balance and improved digestion, expanding application beyond culinary uses. Partnerships with nutraceutical brands and growth of direct-to-consumer health products contribute to sustained demand across global nutritional markets.
- For instance, Baja Gold Sea Salt provides mineral-rich formulations that contain significantly more magnesium and potassium than standard table salt, validated through third-party mineral assays. The company supplies salt ingredients to nutraceutical manufacturers producing electrolyte powders and hydration supplements.
Expansion of Premium and Gourmet Culinary Applications
Celtic salt benefits from rising interest in artisan cooking, gourmet meal kits, and high-quality seasoning categories. Restaurants, craft food producers, and specialty spice companies use coarse and flavored Celtic salt in finishing blends, rubs, smoked salts, and fermented food products. The increasing popularity of global cuisine, home-chef culture, and culinary-focused social media amplifies demand for premium salt varieties. Retailers expand shelf space for gourmet salts as consumers pay more for unique flavor experiences and traceable origin, supporting robust market growth.
Key Trends & Opportunities
Growth of Organic and Sustainable Harvesting Practices
Demand for organic and responsibly harvested salts creates opportunities for producers using environmentally conscious extraction and solar evaporation methods. Brands highlight traceability, hand-harvesting, and low-impact production on packaging to attract eco-aware consumers. Certifications and sustainability messaging enhance premium positioning in natural grocery and online marketplaces. This trend supports differentiation against conventional sea salt and positions Celtic salt as a high-value culinary and wellness ingredient with strong brand storytelling potential.
- For instance, The Salt Company of Iceland produces 1,500 metric tons of geothermal-evaporated sea salt each year using renewable energy sourced from a 75-megawatt geothermal plant, enabling zero-fuel production and verified carbon-neutral salt harvesting through independent environmental audits.
Expansion of E-Commerce and Direct-to-Consumer Distribution
Online health retailers and specialty e-commerce platforms increase global consumer access to Celtic salt, allowing small-batch producers to scale distribution without traditional retail constraints. Subscription services and personalized nutrition programs incorporate Celtic salt into curated wellness boxes. Digital marketing, influencer-led food content, and recipe-based promotions encourage trial and repeat purchases. This shift supports strong demand growth, especially in regions where gourmet and natural foods continue to expand.
- For instance, the San Francisco Salt Company sells a variety of gourmet and mineral salts, including Himalayan salt and organic blends, for cooking and personal care purposes through online marketplaces such as Amazon and its DTC platform.
Key Challenges
Higher Pricing Compared to Conventional Table and Sea Salt
Celtic salt’s artisanal harvesting, lower production volumes, and premium positioning result in significantly higher retail pricing than refined table salt. This limits adoption among cost-sensitive consumers and challenges penetration into mass-market food processing. Price competition from Himalayan pink salt and other premium sea salts further intensifies pressure, requiring clear value communication related to mineral benefits and purity. Brands must balance quality, sourcing transparency, and affordability to broaden market appeal.
Limited Awareness and Inconsistent Quality Standardization
In some markets, consumer familiarity with Celtic salt remains low, and confusion with other unrefined salts challenges brand recognition. Variations in mineral composition, moisture levels, and grain texture across suppliers can create inconsistency in product quality. Lack of strong global regulatory standards for specialty salts also impacts trust and labeling clarity. Manufacturers and associations must improve education and standardization to support widespread acceptance and long-term adoption.
Regional Analysis
North America
North America holds a 34% share of the Celtic Salt market, driven by strong consumer demand for natural, unrefined, and mineral-rich salt alternatives across the United States and Canada. Growth is supported by rising adoption in gourmet foods, premium seasoning blends, functional beverages, and wellness supplements. E-commerce channels, specialty health retailers, and direct-to-consumer brands drive higher product visibility and repeat purchases. The region benefits from strong marketing of clean-label and paleo, keto, and whole-food nutrition trends. Increased use in personal care and bath therapy products also strengthens market expansion, supported by well-developed distribution networks.
Europe
Europe accounts for a 28% share of the Celtic Salt market, supported by a long tradition of sea salt harvesting and strong consumer preference for artisanal and naturally sourced condiments. France, Germany, and the United Kingdom represent major demand hubs, driven by growth in gourmet culinary applications, organic food retail, and spa and wellness therapies. Premium food manufacturers use Celtic salt in craft bakery, fermented foods, and specialty seasoning categories. Sustainability, traceability, and organic certifications further support adoption across supermarkets and specialty food stores. Expanding gastronomic tourism and culinary education continue to reinforce long-term growth.
Asia Pacific
Asia Pacific holds a 22% share of the market, with demand rising in Japan, South Korea, China, and Australia. Growth is driven by the expanding health and wellness sector, increasing adoption of mineral-rich salts in functional foods, and a rising focus on clean-label ingredients. Culinary interest in Western and gourmet food preparation also contributes to higher household and restaurant usage. E-commerce platforms accelerate regional penetration, supported by health influencers and natural-living communities. The growing spa and mineral therapy industry supports use in bath salts and topical wellness formulations, helping strengthen market presence across the region.
Latin America
Latin America holds an 8% share, supported by growing interest in natural and traditional food ingredients. Brazil, Mexico, and Chile lead adoption, driven by increased health awareness and rising demand in premium culinary products and clean-label packaged foods. Celtic salt appears in specialty food stores, organic markets, and wellness-focused online retail channels. Limited domestic production and higher import dependence influence pricing, slowing broader consumption among cost-sensitive buyers. However, expanding middle-class spending and the popularity of gourmet cooking and fusion cuisines support continued market development across the region.
Middle East & Africa
Middle East and Africa represent an 8% share of the Celtic Salt market, driven by increasing preference for natural and minimally processed salt options across the United Arab Emirates, Saudi Arabia, and South Africa. Demand is supported by growth in high-end hospitality, specialty retail, and personal care formulations, including mineral bath salts and exfoliation products. Higher disposable income in Gulf countries and rising tourism-based culinary experiences help premium salt imports gain traction. Limited awareness in some countries and higher pricing constrain mass-market penetration, yet expanding wellness retail and spa industries support steady long-term growth.
Market Segmentations:
By Type
- Coarse Celtic Salt
- Fine Celtic Salt
- Flavored Celtic Salt
By Application
- Food & Beverage
- Personal Care and Cosmetics
- Healthcare and Wellness
- Others
By Nature
- Conventional
- Organic
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Selina Naturally, Celtic Sea Salt Brand, SaltWorks Inc., San Francisco Salt Company, Maine Sea Salt Company, Cornish Sea Salt Co., Maldon Crystal Salt Company, HimalaSalt, Baja Gold Sea Salt, and The Salt Company of Iceland lead the competitive landscape of the Celtic Salt market. The competition centers on product purity, mineral-rich composition, sourcing transparency, and expanding distribution across retail, gourmet, and wellness channels. Companies focus on differentiating their offerings through artisan harvesting methods, low processing, and traceability from coastal salt beds. Leading brands strengthen market visibility through partnerships with natural food retailers, premium restaurants, and e-commerce platforms that support direct-to-consumer sales. Product innovation includes flavored blends, fine and coarse grain variants, and organic-certified salt targeted toward health-conscious consumers. Marketing emphasizes natural electrolytes, lower sodium content, and alignment with clean-label trends. As demand rises in food, personal care, and wellness formulations, key players continue investing in sustainable harvesting, brand storytelling, and regional expansion strategies.
Key Player Analysis
- Selina Naturally
- Celtic Sea Salt Brand
- SaltWorks Inc.
- San Francisco Salt Company
- Maine Sea Salt Company
- Cornish Sea Salt Co.
- Maldon Crystal Salt Company
- HimalaSalt (Sustainable Sourcing LLC)
- Baja Gold Sea Salt
- The Salt Company of Iceland
Recent Developments
- In 2025, SaltWorks Inc. announced the launch of a new portfolio of specialty salts developed exclusively for the food-industry and private-label markets.
- In November 2024, Cornish Sea Salt Co. introduced its "TekSalt" product in its food-manufacturing range, designed to allow lower sodium usage without sacrificing flavour.
- In July 2023, SeaAgri Solutions, LLC (maker of Baja Gold Sea Salt) launched the newly-branded Baja Gold Salt Co., with modern branding, expanded product portfolio including a liquid mineral tincture and bath soak, and a new Shopify e-commerce platform.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Nature and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for mineral-rich, natural salts will increase as consumers shift toward clean-label foods.
- Food manufacturers will expand use of Celtic salt in gourmet seasoning and premium snack products.
- Growth in wellness and holistic nutrition will support product demand in supplements and electrolyte blends.
- Personal care brands will integrate Celtic salt into exfoliation, bath, and skin-repair formulations.
- Flavored and smoked Celtic salt varieties will expand retail presence and attract culinary professionals.
- Online distribution and specialty e-commerce will strengthen global market reach for premium salt brands.
- Sustainable and ethical salt harvesting practices will become essential for brand differentiation.
- Restaurants and artisanal bakeries will increase adoption due to rising demand for authentic flavors.
- Innovation in packaging and traceability will improve product transparency and consumer trust.
- Strong growth potential will emerge in Asia Pacific as natural seasoning and health trends accelerate.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Celtic Salt market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Celtic Salt market projected to grow between 2025 and 2032?
Which Celtic Salt market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Celtic Salt market?
Who are the leading companies in the Celtic Salt market?
Which region commanded the largest share of the Celtic Salt market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 654 million → 2032: USD 1,058.21 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Celtic Salt Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Celtic Salt Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Celtic Salt Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Celtic Salt Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Celtic Salt Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Celtic Salt Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Celtic Salt Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Celtic Salt Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 654 million → 2032: USD 1,058.21 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Celtic Salt Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Celtic Salt Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Celtic Salt Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Celtic Salt Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

