
Market Overview
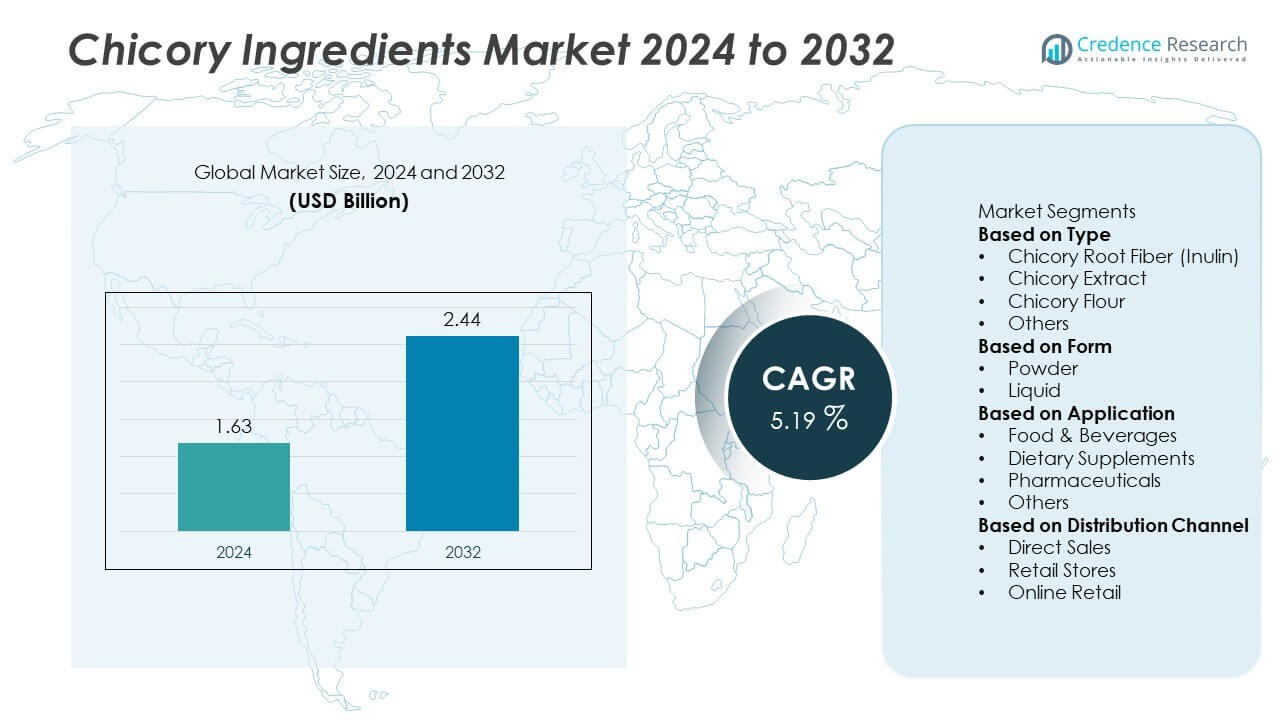
The Chicory Ingredients Market was valued at USD 1.63 billion in 2024 and is projected to reach USD 2.44 billion by 2032, registering a 5.19% CAGR during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Chicory Ingredients Market Size 2024 | USD 1.63 Billion |
| Chicory Ingredients Market, CAGR | 5.19% |
| Chicory Ingredients Market Size 2032 | USD 2.44 Billion |
Top players in the Chicory Ingredients market, including Cosucra Groupe Warcoing, Sensus, Beneo GmbH, Leroux, The Tierra Group, Pioneer Chicory, PMV Nutrient Products Pvt. Ltd., Murlikrishna Foods Pvt. Ltd., Farmvilla Food Industries Pvt. Ltd., and Nutraceutix Inc., strengthen their presence through high-quality inulin production, advanced extraction systems, and strong collaborations with food and nutraceutical brands. These companies focus on clean-label formulations, functional fiber innovation, and efficient supply chains to meet rising global demand. Europe leads the market with a 38% share due to strong cultivation and processing infrastructure, followed by Asia Pacific with a 32% share supported by growing use in food and beverage applications.
 Market Insights
- The Chicory Ingredients market reached USD 1.63 billion in 2024 and will grow at a 5.19% CAGR through the forecast period.
- Demand grows as food and beverage brands adopt chicory root fiber and extract to meet rising needs for natural sweeteners and digestive health solutions.
- Key trends highlight strong expansion of inulin-fortified bakery, dairy, and nutrition products, with chicory root fiber holding a 42% segment share.
- Competition rises as major players enhance extraction technology and product purity, though seasonal cultivation limits supply stability.
- Europe leads with a 38% regional share, followed by Asia Pacific at 32% and North America at 21%, driven by high use in food and supplement applications.
Market Segmentation Analysis:
By Type
Chicory root fiber (inulin) leads the type segment with a 42% market share, driven by its strong use as a natural prebiotic and sugar-reduction ingredient across food and beverage formulations. Demand grows as manufacturers replace synthetic additives with plant-based fibers to improve digestive health and product texture. Chicory extract and chicory flour expand steadily due to rising interest in herbal ingredients and caffeine-free beverage alternatives. The “others” category benefits from niche applications in flavor enhancement, snacks, and bakery mixes. Continuous innovation in clean-label products supports inulin’s strong dominance.
- For instance, Cosucra Groupe Warcoing's inulin-based products are a key driver in the food and beverage sector, where they are used in sugar reduction and digestive health formulations.
By Form
The powder segment dominates the form category with a 67% market share, supported by its longer shelf life, easy handling, and broad compatibility with dry food blends, supplements, and bakery applications. Powdered chicory ingredients are widely adopted for prebiotic fortification, flavor addition, and sugar replacement. The liquid segment grows in beverage concentrates, syrups, and ready-to-drink formulations, driven by rising demand for natural flavoring agents. While both forms serve diverse applications, powder maintains a firm lead due to its processing advantages and widespread industrial use.
- For instance, Beneo GmbH leads the powdered chicory segment with its inulin-based products, such as Orafti® HP, which offer high fiber content and significant health benefits like improved digestive wellness.
By Application
Food and beverages hold the dominant position in the application segment with a 58% market share, supported by growing use of chicory-derived ingredients in bakery items, dairy alternatives, cereals, and coffee substitutes. Manufacturers leverage chicory root fiber for its prebiotic properties and clean-label appeal. The dietary supplements segment expands as consumers prioritize gut health and natural functional ingredients. Pharmaceuticals use chicory for digestive benefits, while the “others” category includes animal feed and personal care. Strong demand for functional foods continues to anchor the leadership of the food and beverage segment.
Key Growth Drivers
Rising Demand for Prebiotic and Gut-Health Ingredients
Growing consumer focus on digestive wellness drives strong demand for chicory-derived inulin, a widely recognized natural prebiotic. Food and beverage brands increasingly incorporate chicory fiber into cereals, dairy alternatives, bakery products, and nutritional drinks to enhance gut health benefits and support clean-label positioning. As awareness of microbiome health rises, manufacturers adopt inulin to reduce sugar, improve texture, and fortify products with functional fiber. This shift toward natural digestive-support ingredients continues to accelerate the adoption of chicory-based solutions across global markets.
- For instance, Sensus has made significant strides with its Frutafit® inulin, which is used by various food brands to enhance their product offerings in the growing digestive wellness category.
Increasing Use of Chicory as a Sugar and Fat Replacer
Chicory ingredients gain traction as manufacturers reformulate products to meet rising demand for low-sugar, low-fat, and calorie-reduced foods. Inulin provides natural sweetness, bulking properties, and fat-mimicking texture, making it a preferred replacement for synthetic additives. Food producers use chicory in chocolate, bakery items, dairy alternatives, and plant-based snacks to enhance mouthfeel without compromising nutrition. Regulatory support for clean-label ingredients and reformulation initiatives further strengthen the adoption of chicory-based fibers and extracts in mainstream food applications.
- For instance, the food industry uses agave-derived inulin as a fat replacer, enabling manufacturers to deliver creamy textures in reduced-fat products like ice creams without the added calories associated with full fat. Companies such as The Tierra Group supply agave inulin for these applications, leveraging its ability to form a particle gel that mimics the mouthfeel of fat.
Expanding Applications in Functional Foods and Nutraceuticals
The nutraceutical sector increasingly adopts chicory ingredients due to their digestive health benefits, natural origin, and compatibility with supplements and fortified foods. Dietary supplement brands incorporate chicory fiber into capsules, powders, and gummies targeting gut health and immunity. The functional food category benefits from rising consumer demand for plant-based, natural, and wellness-focused ingredients. As product developers expand formulations for immunity, weight management, and overall wellness, chicory continues to gain relevance across multiple health-driven categories.
Key Trends & Opportunities
Growing Preference for Clean-Label and Plant-Based Ingredients
A major trend shaping the market is the rising shift toward natural and plant-derived ingredients in food, beverages, and supplements. Chicory fiber aligns well with clean-label expectations, offering digestive benefits and natural sweetness without synthetic additives. Brands reformulate products to replace artificial fibers and chemical sweeteners with chicory-based alternatives. Expanding plant-based food categories-including dairy-free, vegan snacks, and meat alternatives-create strong opportunities for chicory in both texture improvement and nutritional enhancement.
- For instance, Ingredion Incorporated offers a range of clean-label ingredient solutions, including chicory root fiber (inulin), which functions as a prebiotic, bulking agent, and sugar reducer.
Expansion of Chicory in Coffee Substitutes and Specialty Beverages
Chicory extract and roasted chicory continue to gain popularity as caffeine-free coffee alternatives, driven by rising interest in healthier beverage options. Specialty beverage brands use chicory to enhance flavor depth, reduce acidity, and support functional drink formulations. Growth in herbal beverages, wellness drinks, and cold-brew substitutes creates new opportunities for chicory-based ingredients. As consumers explore novel flavors and caffeine-conscious choices, chicory enjoys expanding use in both premium and mainstream beverage categories.
- For instance, chicory has gained prominence as a popular ingredient for roasted, caffeine-free coffee alternatives, with a growing demand for such beverages. Its use in these drinks enhances flavor complexity while providing a healthier, caffeine-free option for consumers.
Increasing Industrial Adoption in Pharmaceuticals and Personal Care
Pharmaceutical and personal care companies integrate chicory ingredients for their anti-inflammatory, prebiotic, and soothing properties. Chicory extract appears in digestive health medicines, herbal formulations, and skincare products targeting hydration and microbiome balance. Rising interest in natural active ingredients supports further adoption across topical and ingestible applications. This trend opens new pathways for diversification beyond food and supplements.
Key Challenges
Supply Variability Due to Agricultural Dependence
Chicory production relies heavily on agricultural factors such as seasonal yields, soil quality, and climate conditions. Supply fluctuations affect raw material availability and price stability for ingredient manufacturers. Variability in crop output can disrupt production planning for food, nutraceutical, and beverage companies. Smaller processors struggle with inconsistent supply chains, increasing procurement challenges. Ensuring stable chicory sourcing remains a key constraint for market expansion.
Competition from Alternative Functional Ingredients
Chicory ingredients face strong competition from other prebiotic fibers, natural sweeteners, and plant-based functional materials such as fructooligosaccharides (FOS), resistant starches, and agave fibers. Some alternatives offer lower cost, different functional benefits, or broader compatibility with specific formulations. As manufacturers evaluate ingredient versatility and pricing, chicory must compete based on performance, clean-label appeal, and nutritional value. This competitive pressure poses a challenge to market share growth in both food and nutraceutical sectors.
Regional Analysis
North America
North America holds a market share of 32%, supported by rising demand for prebiotic fibers, clean-label ingredients, and plant-based food formulations. Food and beverage companies increasingly use chicory inulin for sugar reduction, digestive health claims, and texture enhancement. Strong consumer interest in functional foods and dietary supplements accelerates adoption across mainstream brands. The region benefits from advanced R&D capabilities and frequent product innovations in nutrition bars, beverages, and dairy alternatives. Expanding retail availability and high awareness of gut-health solutions further strengthen North America’s position in the chicory ingredients market.
Europe
Europe accounts for a market share of 38%, driven by strong chicory cultivation, established processing facilities, and long-standing use of chicory in food and beverage applications. The region leads in producing chicory root fiber due to favorable farming environments and advanced extraction technologies. Rising demand for natural sweeteners, functional fibers, and clean-label reformulations supports high consumption across bakery, confectionery, and dairy sectors. European consumers show strong preference for plant-based and digestive wellness products, further strengthening market growth. Regulatory support for natural ingredients enhances Europe’s leadership in the global chicory ingredients market.
Asia Pacific
Asia Pacific holds a market share of 22%, fueled by expanding food processing industries, rising health awareness, and growing adoption of chicory-based ingredients in functional foods and supplements. The region benefits from increasing consumption of prebiotic fibers in beverages, nutritional products, and fortified foods. Manufacturers integrate chicory fiber to support sugar reduction and improve digestive health claims. Rapid urbanization, rising disposable incomes, and growth in nutraceutical demand further contribute to market expansion. Strong interest in natural and plant-derived ingredients positions Asia Pacific as a fast-growing market for chicory ingredients.
Latin America
Latin America captures a market share of 5%, supported by rising interest in natural functional ingredients and steady adoption across food, beverage, and dietary supplement applications. Demand strengthens as manufacturers incorporate chicory fibers into bakery items, dairy substitutes, and wellness-focused products. Growth in herbal beverages and plant-based formulations also supports usage of chicory extracts. Although production capabilities remain limited, expanding imports and increasing awareness of digestive health trends drive market development. The region’s growing nutraceutical sector further supports adoption of chicory ingredients.
Middle East & Africa
The Middle East & Africa region holds a market share of 3%, driven by gradual adoption of chicory ingredients in health-oriented foods, beverages, and supplements. Rising prevalence of digestive health concerns increases consumer interest in natural prebiotic fibers. Food manufacturers incorporate chicory in low-sugar formulations and clean-label products to align with shifting dietary preferences. Although market penetration remains moderate due to limited processing facilities, rising imports and expanding retail distribution support demand. Growth in functional food and nutraceutical sectors strengthens the region’s long-term potential for chicory ingredient use.
Market Segmentations:
By Type
- Chicory Root Fiber (Inulin)
- Chicory Extract
- Chicory Flour
- Others
By Form
- Powder
- Liquid
By Application
- Food & Beverages
- Dietary Supplements
- Pharmaceuticals
- Others
By Distribution Channel
- Direct Sales
- Retail Stores
- Online Retail
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis of the Chicory Ingredients market highlights the presence of major players such as Cosucra Groupe Warcoing, Sensus, Beneo GmbH, Leroux, The Tierra Group, Pioneer Chicory, PMV Nutrient Products Pvt. Ltd., Murlikrishna Foods Pvt. Ltd., Farmvilla Food Industries Pvt. Ltd., and Nutraceutix Inc. These companies compete by expanding production capacity, improving extraction efficiency, and developing high-purity inulin and chicory-based functional ingredients. Many invest in advanced drying, filtration, and refining technologies to enhance product quality for use in dietary supplements, functional foods, and pharmaceutical formulations. Partnerships with food manufacturers support broader application development, while sustainability initiatives help strengthen brand positioning. Companies also emphasize R&D to introduce cleaner-label products and diversify chicory ingredient formats. Strong distribution networks and customized product solutions further reinforce competitive advantage in a market shaped by rising health awareness and growing preference for natural fiber ingredients.
Key Player Analysis
- Cosucra Groupe Warcoing
- Sensus
- Beneo GmbH
- Leroux
- The Tierra Group
- Pioneer Chicory
- PMV Nutrient Products Pvt. Ltd.
- Murlikrishna Foods Pvt. Ltd.
- Farmvilla Food Industries Pvt. Ltd.
- Nutraceutix Inc.
Recent Developments
- In September 2025, BENEO secured approval from the Thai FDA for an exclusive prebiotic claim for its chicory‑root fibre “Orafti® Inulin,” enabling manufacturers in Thailand to market this health benefit on pack.
- In June 2025, BENEO GmbH published research showing that combining its chicory‑derived inulin‑type fructans with human milk oligosaccharide (HMO) 2’‑fucosyllactose produced additive or synergistic benefits for toddler gut‑microbiota in a pre‑clinical study.
- In August 2024, DKSH extended its exclusive distribution agreement with Cosucra in Australia and New Zealand to promote Cosucra’s chicory‑root fibre ranges FIBRULINE™ and FIBRULOSE™.
Report Coverage
The research report offers an in-depth analysis based on Type, Form, Application, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for chicory root fiber will rise as consumers seek digestive health benefits.
- Adoption of chicory ingredients in clean-label foods will expand across global markets.
- Food and beverage companies will increase use of chicory as a natural sugar replacer.
- Growth in plant-based diets will boost demand for chicory-based functional ingredients.
- Dietary supplement makers will introduce more inulin-rich formulations for gut wellness.
- Advances in extraction technology will improve product purity and yield efficiency.
- Manufacturers will expand cultivation zones to reduce supply risks and seasonal shortages.
- Chicory flour will gain traction in gluten-free bakery and snack applications.
- Asia Pacific markets will grow faster due to rising health awareness and product diversification.
- Partnerships between farming cooperatives and ingredient companies will strengthen supply chains.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Chicory Ingredients market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Chicory Ingredients market projected to grow between 2025 and 2032?
Which Chicory Ingredients market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Chicory Ingredients market?
Who are the leading companies in the Chicory Ingredients market?
Which region commanded the largest share of the Chicory Ingredients market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1.63 Billion → 2032: USD 2.44 Billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Chicory Ingredients Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Chicory Ingredients Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Chicory Ingredients Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Chicory Ingredients Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Chicory Ingredients Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Chicory Ingredients Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Chicory Ingredients Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Chicory Ingredients Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1.63 Billion → 2032: USD 2.44 Billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Chicory Ingredients Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Chicory Ingredients Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Chicory Ingredients Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Chicory Ingredients Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

