
Cervical Dysplasia Market Overview:
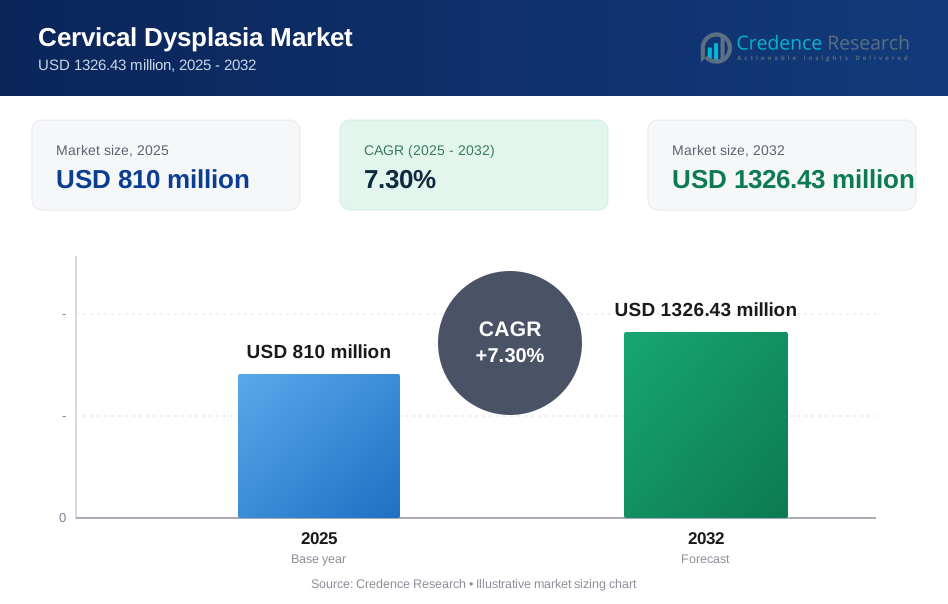
The global Cervical Dysplasia Market size was estimated at USD 810 million in 2025 and is expected to reach USD 1326.43 million by 2032, growing at a CAGR of 7.3% from 2025 to 2032. Demand expansion is primarily driven by rising screening coverage and the clinical shift toward higher-sensitivity HPV-based testing, which increases detection, triage, and follow-up procedure volumes across care pathways. Growth momentum is further supported by broader access to colposcopy and outpatient treatment options that shorten referral cycles and increase procedural throughput in organized screening systems.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Cervical Dysplasia Market Size 2025 | USD 810 million |
| Cervical Dysplasia Market, CAGR | 7.3% |
| Cervical Dysplasia Market Size 2032 | USD 1326.43 million |
Key Market Trends & Insights
- The Cervical Dysplasia Market is projected to expand from USD 810 million (2025) to USD 1326.43 million (2032), reflecting a 7.3% CAGR over 2025–2032.
- Diagnostics accounted for the largest share of 63.1% in 2025, supported by scaling HPV testing volumes and triage-driven confirmatory workflows.
- Surgical Treatment represented 38.8% share in 2025, reflecting continued reliance on excisional/ablative interventions for high-grade lesions in procedure settings.
- North America held 30.1% of revenue in 2025, supported by structured screening pathways and high test utilization across lab and hospital networks.
- Europe reached 26.9% share in 2025, reflecting strong screening compliance and steady demand for colposcopy and biopsy confirmation in referral systems.

Segment Analysis
Cervical Dysplasia Market demand is shaped by the interplay of screening intensity, triage rules, and capacity for confirmatory diagnosis and outpatient treatment. Increasing HPV-based screening adoption elevates the volume of patients moving from initial testing into colposcopy, biopsy, and intervention decision pathways, which expands procedural and diagnostic utilization. Cervical Dysplasia Market workflows also increasingly emphasize risk-based management, which sustains repeat testing and follow-up appointments for surveillance cohorts while prioritizing intervention for higher-grade lesions.
Cervical Dysplasia Market purchasing and utilization patterns are influenced by laboratory throughput needs, test menu standardization, and the ability to integrate results into clinical decision pathways. Health systems often prioritize validated testing platforms, consistent sample workflows, and interoperability with laboratory information systems to reduce turnaround time and improve patient follow-up adherence. Cervical Dysplasia Market growth is reinforced by outpatient migration of procedures, which increases utilization across ambulatory sites and specialty clinics that can deliver standardized care with shorter scheduling lead times.
By Type Insights
High-Grade Cervical Dysplasia is typically prioritized in clinical pathways because higher-risk lesions require closer surveillance and more frequent confirmation and intervention decisions. Cervical Dysplasia Market growth in high-grade management is supported by expanded screening coverage that increases detection of clinically actionable lesions. Cervical Dysplasia Market protocols often direct high-grade patients toward confirmatory colposcopy and biopsy, increasing downstream diagnostic and procedural volumes. Cervical Dysplasia Market demand is also supported by efforts to reduce loss to follow-up through streamlined referral workflows and clinic capacity expansion.
By Diagnosis Insights
HPV DNA Test utilization is expanding within cervical screening pathways because high-sensitivity testing improves risk stratification and supports structured triage. Cervical Dysplasia Market diagnostic demand rises as positive HPV results increase referrals for colposcopy, particularly for high-risk genotypes. Cervical Dysplasia Market adoption is also reinforced by improved laboratory automation, standardized sample workflows, and broader availability of molecular platforms in centralized labs and hospital networks. Cervical Dysplasia Market confirmation volumes remain supported by biopsy use in cases requiring histopathology to guide intervention decisions.
By Treatment Insights
Surgical Treatment accounted for the largest share of 38.8% in 2025. Cervical Dysplasia Market reliance on excisional and ablative procedures remains strong because many high-grade lesions require definitive removal or destruction to reduce progression risk. Cervical Dysplasia Market procedure volumes benefit from outpatient delivery models that reduce inpatient dependency and improve scheduling capacity. Cervical Dysplasia Market utilization is also supported by clinician familiarity and guideline-aligned protocols that favor procedure-based resolution for eligible patients.
By End User Insights
Hospitals remain central to Cervical Dysplasia Market workflows due to integrated diagnostics, referral coordination, and access to colposcopy and biopsy services. Cervical Dysplasia Market expansion is supported by specialty clinics that increase appointment availability and shorten wait times for colposcopy and follow-up. Cervical Dysplasia Market growth in diagnostic centers is reinforced by higher testing throughput and centralized lab efficiencies that support large screening volumes. Cervical Dysplasia Market procedure migration toward ambulatory surgical centers also supports utilization growth where outpatient intervention pathways are well established.
Cervical Dysplasia Market Drivers
Expansion of HPV-based screening and risk-based management
Cervical Dysplasia Market growth is supported by rising screening coverage and greater use of HPV testing as a primary screening tool. HPV-based approaches increase identification of higher-risk patients who require triage and confirmatory diagnosis. Cervical Dysplasia Market demand rises as positive screening results translate into downstream colposcopy, biopsy, and follow-up visits. Cervical Dysplasia Market pathways also sustain repeat testing and surveillance in low-grade cohorts, expanding diagnostic utilization over time.
Higher diagnostic throughput enabled by lab automation and standardized workflows
Cervical Dysplasia Market demand benefits from laboratory consolidation and investment in higher-throughput diagnostic processing. Standardized sample workflows and automation improve turnaround time and reduce operational variability. Cervical Dysplasia Market adoption strengthens when health systems can integrate testing results with electronic records and referral scheduling. Cervical Dysplasia Market utilization increases as streamlined workflows reduce loss to follow-up and improve patient retention through the care pathway.
Outpatient procedure shift for lesion management
Cervical Dysplasia Market growth is reinforced by increasing outpatient delivery of excisional and ablative interventions. Outpatient treatment models improve access, reduce scheduling bottlenecks, and shorten care timelines for eligible patients. Cervical Dysplasia Market procedure volumes rise when ambulatory sites and specialty clinics expand capacity and standardize protocols. Cervical Dysplasia Market adoption is also supported by clinician preference for guideline-aligned interventions with clear clinical endpoints.
- For instance, WISAP’s thermocoagulation platform uses a probe heated to 100°C for 20 seconds, and company-cited clinical data reported a 95% cure rate overall, including successful treatment in 97% of 485 women with CIN1 and 96.5% of 680 women with CIN2, reinforcing the suitability of fast outpatient treatment models.
Public health focus on early detection and prevention-oriented care pathways
Cervical Dysplasia Market growth is strengthened by public health initiatives aimed at early detection and improved screening participation. Organized programs encourage routine testing and structured follow-up pathways, increasing diagnostic and procedural demand. Cervical Dysplasia Market momentum also benefits from awareness campaigns that increase screening uptake among under-screened populations. Cervical Dysplasia Market expansion is further supported by ongoing improvements in access to diagnostic infrastructure and trained clinical capacity.
- For instance, QIAGEN’s careHPV test has been used in low-resource screening settings, and in a study of 464 women, self-collected and provider-collected samples showed 90.5% overall agreement while 79.8% of participants preferred self-collection, highlighting how accessible screening formats can improve participation in under-screened populations.
Cervical Dysplasia Market Challenges
Cervical Dysplasia Market growth faces persistent constraints from screening access gaps and uneven follow-up adherence, particularly in resource-limited settings. Patients may experience delays between screening, confirmatory diagnosis, and treatment due to appointment availability or referral friction. Cervical Dysplasia Market outcomes can be affected by loss to follow-up, which reduces completion rates for colposcopy and biopsy confirmation. Cervical Dysplasia Market scale-up is also limited where laboratory infrastructure and trained colposcopy capacity are insufficient for rising demand.
- For instance, Cepheid’s Xpert HPV is a 60-minute molecular test that targets the E6 and E7 oncogenes of 14 cancer-related HPV types and was accepted to the WHO list of prequalified in vitro diagnostics in 2017, highlighting how faster near-patient testing platforms can help shorten the interval between screening and diagnostic escalation in infrastructure-constrained settings.
Cervical Dysplasia Market complexity is increased by variability in clinical pathways, reimbursement, and guideline adoption across regions and health systems. Differences in triage protocols and test selection can create heterogeneous care pathways and inconsistent utilization patterns. Cervical Dysplasia Market stakeholders also manage operational challenges related to specimen handling, turnaround time, and integration with clinical scheduling. Cervical Dysplasia Market standardization efforts require investment, training, and sustained quality management to ensure consistent performance.
Cervical Dysplasia Market Trends and Opportunities
Cervical Dysplasia Market trends increasingly emphasize HPV primary screening, improved triage, and streamlined diagnostic pathways that reduce delays from screening to confirmation. Health systems are prioritizing workflow integration, including better connectivity between laboratories, clinics, and referral scheduling. Cervical Dysplasia Market opportunities expand where organized screening programs scale and where diagnostic networks improve reach into under-screened populations. Cervical Dysplasia Market demand also benefits from operational improvements that increase throughput and reduce patient drop-off.
- For instance, Roche’s cobas HPV test detects 14 high-risk HPV types, reports HPV 16 and HPV 18 individually, and on Roche’s fully automated cobas 5800/6800/8800 platforms can deliver up to 96 results in about three hours, with up to 384 results on the cobas 6800 and 1,056 results on the cobas 8800 in an eight-hour shift, demonstrating a company-specific advance in high-volume screening efficiency and triage readiness.
Cervical Dysplasia Market opportunity is also supported by care delivery expansion outside traditional hospital settings, including specialty clinics, diagnostic centers, and ambulatory procedure sites. Outpatient migration supports higher capacity and improved patient convenience where procedures can be delivered efficiently. Cervical Dysplasia Market growth is reinforced by investments in clinician training, quality protocols, and standardized documentation to improve comparability across sites. Cervical Dysplasia Market adoption improves when pathways support timely intervention for high-grade lesions and structured surveillance for low-grade cohorts.
Regional Insights
North America
Cervical Dysplasia Market in North America held 30.1% share in 2025, supported by structured screening pathways and high access to HPV testing and follow-up services. Cervical Dysplasia Market demand is reinforced by established laboratory networks and strong capacity for colposcopy and biopsy confirmation. Cervical Dysplasia Market utilization remains steady due to organized care pathways that support repeat testing and surveillance. Cervical Dysplasia Market growth also benefits from outpatient procedure availability for intervention and follow-up care.
Europe
Cervical Dysplasia Market in Europe accounted for 26.9% share in 2025, supported by organized screening programs and steady testing compliance in multiple countries. Cervical Dysplasia Market demand is sustained by referral-based clinical pathways that route positive screens into colposcopy and biopsy confirmation. Cervical Dysplasia Market growth is strengthened where HPV-based screening is scaled and standardized. Cervical Dysplasia Market adoption is also supported by emphasis on consistent documentation and quality systems across sites.
Asia Pacific
Cervical Dysplasia Market in Asia Pacific reached 29.4% share in 2025, supported by large addressable screening volumes and expanding diagnostic capacity in high-population countries. Cervical Dysplasia Market growth is reinforced by increasing availability of testing services, scaling private diagnostics, and investments in clinical capacity. Cervical Dysplasia Market utilization rises as referral networks improve and more patients complete confirmatory pathways. Cervical Dysplasia Market opportunity is strengthened by programmatic screening expansion and modernization of laboratory workflows.
Latin America
Cervical Dysplasia Market in Latin America represented 9.3% share in 2025, supported by gradual expansion of screening and follow-up services in urban centers. Cervical Dysplasia Market demand is shaped by uneven access and variable adherence to follow-up pathways across geographies. Cervical Dysplasia Market growth is supported where diagnostic centers and specialty clinics expand capacity and reduce delays. Cervical Dysplasia Market performance improves as organized programs increase participation and continuity of care.
Middle East & Africa
Cervical Dysplasia Market in Middle East & Africa accounted for 4.3% share in 2025, reflecting lower average screening coverage and constraints in diagnostic and follow-up infrastructure. Cervical Dysplasia Market growth is supported by improving access initiatives and increasing investment in diagnostic capability in select markets. Cervical Dysplasia Market expansion remains tied to building colposcopy and biopsy capacity and improving referral completion. Cervical Dysplasia Market demand improves as awareness and screening participation increase over time.
Competitive Landscape
Cervical Dysplasia Market competition is driven by the breadth and performance of HPV testing platforms, the ability to integrate diagnostic workflows into laboratory and clinic operations, and the availability of procedure-support technologies that improve confirmation and intervention pathways. Cervical Dysplasia Market participants compete on sensitivity, workflow efficiency, automation readiness, and fit with health system protocols for triage and follow-up. Cervical Dysplasia Market differentiation also comes from installed base scale, service networks, and the ability to support screening programs that require consistent throughput and quality management.
Hologic, Inc. is positioned in Cervical Dysplasia Market workflows through women’s health diagnostics that support HPV testing and laboratory throughput needs, with emphasis on platform standardization and operational compatibility across health system environments. Cervical Dysplasia Market adoption for Hologic, Inc. is supported when laboratories prioritize consistent sample workflows and integrated result reporting that improves care pathway continuity. Cervical Dysplasia Market participation also aligns with screening expansion strategies that require scalable testing and predictable turnaround times. Cervical Dysplasia Market competitiveness is strengthened by supporting structured triage and confirmatory pathways across patient cohorts.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Hologic, Inc.
- F. Hoffmann-La Roche Ltd.
- QIAGEN
- Abbott Laboratories
- Becton, Dickinson and Company (BD)
- Quest Diagnostics
- CooperSurgical, Inc.
- DYSIS Medical Ltd.
- Zilico Ltd.
- Merck & Co., Inc.
- GlaxoSmithKline (GSK)
- Guided Therapeutics
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In January 2026, Teal Health announced national availability of its at-home cervical cancer screening service across all 50 U.S. states, including the FDA-authorized Teal Wand self-collection device and its telehealth platform. Teal also stated that the Teal Wand became the first and only self-collection device authorized for at-home cervical cancer screening on May 9, 2025.
- In March 2025, Self-screen said its HPV Risk Assay was recommended to the Uruguayan Ministry of Health for cervical cancer screening and that it had partnered with Biodiagnostico to support market access in Uruguay. The company also highlighted that its PreCursor-M+ methylation test can help triage HPV-positive women with fewer unnecessary referrals and treatments, which is relevant to management of cervical precancer and dysplasia.
- In October 2024, Hologic announced a definitive agreement to acquire Gynesonics for approximately $350 million, and Hologic completed the acquisition in January 2025. Although Gynesonics is focused on minimally invasive women’s health solutions rather than cervical dysplasia specifically, Hologic is listed among the major companies active in the cervical dysplasia market, so the deal is still a notable market update.
- In May 2024, Roche announced FDA approval of its HPV self-collection solution, described as one of the first available in the United States, allowing patients to collect their own vaginal sample in a healthcare setting for analysis with Roche’s cobas HPV test. This update is important for the cervical dysplasia market because HPV screening is a core step in identifying women at risk early in the cervical disease pathway.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 810 million |
| Revenue forecast in 2032 | USD 1,326.43 million |
| Growth rate (CAGR) | 7.3% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026–2032 |
| Quantitative units | USD million |
| Segments covered | By Type Outlook: Low-Grade Cervical Dysplasia, High-Grade Cervical Dysplasia; By Diagnosis Outlook: Pap Smear Test, HPV DNA Test, Colposcopy, Biopsy, Other Diagnostic Tests; By Treatment Outlook: Surgical Treatment, Non-Surgical Treatment; By End User Outlook: Hospitals, Specialty Clinics, Diagnostic Centers, Ambulatory Surgical Centers, Other End Users |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Hologic, Inc.; F. Hoffmann-La Roche Ltd.; QIAGEN; Abbott Laboratories; Becton, Dickinson and Company (BD); Quest Diagnostics; CooperSurgical, Inc.; DYSIS Medical Ltd.; Zilico Ltd.; Merck & Co., Inc.; GlaxoSmithKline (GSK); Guided Therapeutics |
| No. of Pages | 335 |
Segmentation
By Type
- Low-Grade Cervical Dysplasia
- High-Grade Cervical Dysplasia
By Diagnosis
- Pap Smear Test
- HPV DNA Test
- Colposcopy
- Biopsy
- Other Diagnostic Tests
By Treatment
- Surgical Treatment
- Loop Electrosurgical Excision Procedure (LEEP)
- Cryosurgery
- Cold Knife Conization (CKC)
- Other Surgical Treatments
- Non-Surgical Treatment
- Topical Medications
- Immunotherapy
By End User
- Hospitals
- Specialty Clinics
- Diagnostic Centers
- Ambulatory Surgical Centers
- Other End Users
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the Cervical Dysplasia Market size and forecast?
What is the CAGR for Cervical Dysplasia Market during 2025–2032?
What is the largest segment in Cervical Dysplasia Market?
What factors are driving Cervical Dysplasia Market growth?
Who are the key players in Cervical Dysplasia Market?
Which region leads Cervical Dysplasia Market in 2025?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Cervical Dysplasia Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2025; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Cervical Dysplasia Market Snapshot
- 2.1.1 Market Size – Historical (2025) & Forecast (2025-2032) (2025: USD 810 million → 2032: USD 1326.43 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Cervical Dysplasia Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2025 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2025
- 2.3.2 Top 10 Players by Volume Share – 2025
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Cervical Dysplasia Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Cervical Dysplasia Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Cervical Dysplasia Market Drivers
- 3.3 Cervical Dysplasia Market Restraints & Challenges
- 3.4 Cervical Dysplasia Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Cervical Dysplasia Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Cervical Dysplasia Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Cervical Dysplasia category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Cervical Dysplasia Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Cervical Dysplasia Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2025)
- 5.1.2 Global Export Volume by Country (2025)
- 5.1.3 Global Import Value by Country (2025)
- 5.1.4 Global Import Volume by Country (2025)
- 5.1.5 Net Trade Balance by Country (2025)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2025)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Cervical Dysplasia market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Cervical Dysplasia Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2025
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Cervical Dysplasia Market Share Analysis – 2025
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2025)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Cervical Dysplasia Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Cervical Dysplasia (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Cervical Dysplasia Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Cervical Dysplasia Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2025 & 2032)
- 7.1.2 Channel Mix Evolution (2025-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Cervical Dysplasia Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Cervical Dysplasia Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Cervical Dysplasia Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Cervical Dysplasia Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Cervical Dysplasia Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Cervical Dysplasia Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Cervical Dysplasia Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
