
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| China Interior Design Market Size 2023 | USD 16,396.97 million |
| China Interior Design Market, CAGR | 6.33% |
| China Interior Design Market Size 2032 | USD 28,505.43 million |
Market Overview:
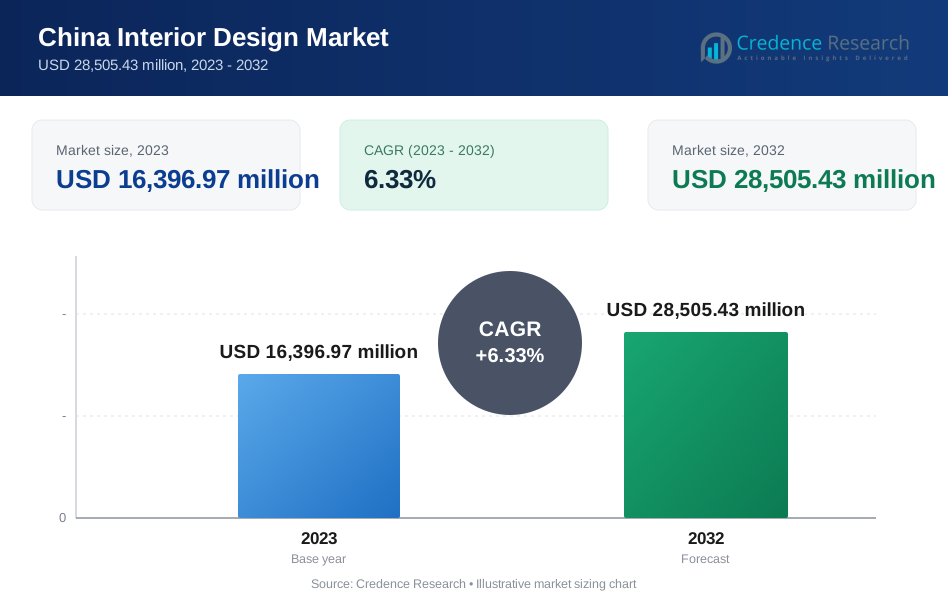
China Interior Design Market size was valued at USD 16,396.97 million in 2023 and is anticipated to reach USD 28,505.43 million by 2032, at a CAGR of 6.33% during the forecast period (2023-2032).
Several key factors are propelling the growth of the interior design market in China. First, rapid urbanization and infrastructure development have led to a surge in real estate projects, creating strong demand for professional interior design services. Government policies encouraging urban renewal and green building initiatives further contribute to market expansion. Second, the rise of the middle-class population and increased disposable income have heightened consumer spending on home renovations and premium interior aesthetics. Consumers are increasingly seeking personalized and high-quality designs that reflect their lifestyle and aspirations. Third, technological advancements such as 3D visualization, virtual reality (VR), and artificial intelligence (AI)-driven design tools are revolutionizing the industry, enabling designers to offer immersive experiences and efficient project execution. Additionally, the growing influence of sustainability and eco-friendly design has led to the adoption of energy-efficient materials, smart lighting solutions, and eco-conscious furniture, aligning with government initiatives for green building development.
China's interior design market exhibits strong regional variations, with major urban centers driving demand. Tier 1 cities such as Beijing, Shanghai, Guangzhou, and Shenzhen represent the most lucrative markets due to high disposable incomes, modern real estate projects, and an increasing preference for international design trends. The rapid expansion of luxury residential and commercial spaces in these cities has fueled demand for high-end interior design services. Tier 2 and Tier 3 cities, including Chengdu, Hangzhou, Wuhan, and Nanjing, are also witnessing rapid growth as economic development accelerates and younger consumers seek modern living spaces. The government’s push for urbanization and infrastructure development in these regions is expected to drive further expansion. Additionally, the rise of online interior design services and digital platforms is allowing firms to tap into a broader customer base across China, making interior design services more accessible to a wider demographic.
Market Insights:
- The China interior design market was valued at USD 16,396.97 million in 2023 and is projected to reach USD 28,505.43 million by 2032, growing at a CAGR of 6.33% during the forecast period.
- Rapid urbanization and infrastructure expansion are driving strong demand for interior design services, particularly in Tier 1 and fast-developing Tier 2 and Tier 3 cities.
- Growing emphasis on smart home technology, AI-driven design tools, and eco-friendly materials is transforming the industry and aligning with China’s sustainability initiatives.
- Rising middle-class population and disposable income have led to increased investment in personalized, high-quality interior aesthetics for residential and commercial spaces.
- The market remains highly competitive and fragmented, with a mix of domestic firms, international players, and independent designers competing for market share.
- Strict environmental regulations and rising material and labor costs pose challenges, especially for small and mid-sized firms adapting to sustainability requirements.
- Tier 1 cities such as Beijing, Shanghai, and Guangzhou dominate the high-end market, while Tier 2 and Tier 3 cities are growing rapidly due to urbanization and digital accessibility.
Market Drivers:
Urbanization and Infrastructure Development
China's rapid urbanization has been a primary catalyst for the growth of the interior design market. With continuous expansion in real estate development, particularly in major metropolitan areas and emerging Tier 2 and Tier 3 cities, the demand for professional interior design services has surged. For instance, In 2023, the Ministry of Housing and Urban-Rural Development reported that over 1.5 million new residential units were completed in major cities like Beijing and Shanghai, with an additional 2.3 million units in Tier 2 and Tier 3 cities. Government initiatives promoting smart cities, urban renewal projects, and modern infrastructure have further fueled this trend. As millions of people migrate from rural to urban areas, residential and commercial properties are being developed at an unprecedented pace, creating substantial opportunities for interior designers to cater to diverse aesthetic and functional requirements. The growing preference for high-quality, customized interiors in both private and public spaces underscores the critical role of interior design in shaping modern urban living.
Rising Disposable Incomes and Changing Consumer Preferences
China’s expanding middle class and increasing disposable incomes have significantly influenced the interior design market. Consumers are now prioritizing aesthetics, comfort, and personalized designs that reflect their lifestyles and aspirations. The younger generation, in particular, is more inclined toward contemporary and internationally inspired interiors, integrating elements of minimalism, smart home technology, and sustainable materials. This shift in consumer behavior has led to greater investment in home renovation and redesign projects, driving demand for premium design services, high-end furnishings, and cutting-edge decor solutions. For instance, companies such as Oppein and Holike are catering to this demand by offering personalized cabinetry and interior solutions. Moreover, the hospitality and retail sectors are embracing sophisticated interior designs to enhance customer experiences, further propelling market growth.
Technological Advancements in Interior Design
The integration of advanced technologies has revolutionized China’s interior design industry, enhancing both the design process and customer experience. Virtual reality (VR) and augmented reality (AR) tools allow clients to visualize interior spaces before implementation, improving decision-making and reducing design iterations. Artificial intelligence (AI) is also playing a transformative role by automating design suggestions based on consumer preferences, optimizing space utilization, and streamlining project management. For instance, companies like Kujiale and Coohom have developed VR-powered design platforms that enable homeowners and designers to create and visualize 3D-rendered interiors before finalizing layouts and materials. Additionally, digital platforms offering online interior design consultations and e-commerce-driven furniture and decor solutions have made professional design services more accessible. As technology continues to evolve, interior designers are leveraging these innovations to create highly customized, efficient, and aesthetically appealing spaces.
Growing Emphasis on Sustainability and Green Design
Sustainability has become a key focus in China’s interior design market, driven by government policies promoting green building practices and increased environmental awareness among consumers. The demand for eco-friendly materials, energy-efficient lighting, and sustainable furniture is on the rise, influencing both residential and commercial design projects. Developers and interior designers are increasingly incorporating recycled materials, smart home systems, and energy-saving designs to align with the country’s carbon neutrality goals. For instance, leading Chinese developers like China Vanke and Evergrande Group are integrating green building materials such as low-VOC paints, bamboo flooring, and recycled wood into their residential and commercial projects. The adoption of biophilic design principles, which integrate natural elements into indoor spaces, is also gaining traction. As environmental concerns continue to shape market trends, the emphasis on sustainable and responsible design is expected to play a pivotal role in the industry's future growth.
Market Trends:
Integration of Smart Home Technologies
The increasing adoption of smart home solutions is reshaping China’s interior design market, as homeowners and businesses seek greater convenience, efficiency, and automation. Advanced home automation systems, including voice-controlled lighting, climate regulation, and security features, are being seamlessly incorporated into interior designs. For instance, companies like Xiaomi and Huawei have introduced smart home ecosystems that integrate AI-powered voice assistants, automated lighting, and climate control systems, allowing homeowners to manage their living spaces effortlessly. Consumers are prioritizing smart furniture and multifunctional spaces that optimize space utilization without compromising aesthetics. With the proliferation of the Internet of Things (IoT), interior designers are collaborating with technology providers to create intuitive and connected living spaces. As 5G networks continue to expand across China, the demand for technology-driven interiors is expected to grow, enhancing both functionality and user experience.
Rise of Minimalist and Contemporary Design Styles
Chinese consumers are increasingly favoring minimalist and contemporary interior design styles, moving away from traditional and overly elaborate aesthetics. The preference for open spaces, neutral color palettes, and clean lines reflects a broader global influence on interior design trends in China. Scandinavian, Japanese, and industrial design inspirations are becoming popular, emphasizing simplicity and functionality. This trend is particularly strong among younger homeowners and urban dwellers who seek modern, clutter-free interiors. For instance, Ziinlife, a Shanghai-based design brand, aims to share new perspectives on furniture design with creative solutions. Their collections feature simple, functional furniture designed to display "the hidden beauty from ordinary life," reflecting Scandinavian design principles. Additionally, modular furniture and space-saving solutions are gaining traction in compact urban apartments, allowing residents to maximize their living areas without compromising on style or comfort.
Growing Popularity of Personalized and Custom Interior Design
Personalization has become a key trend in China’s interior design market, with consumers seeking unique and tailored solutions that reflect their individual tastes and lifestyles. Custom furniture, bespoke lighting fixtures, and one-of-a-kind decor pieces are in high demand, particularly in the luxury residential and hospitality segments. Interior designers are leveraging digital tools to provide highly customized design solutions, offering 3D renderings and virtual walkthroughs to cater to specific client preferences. For instance, platforms like Kujiale and Coohom provide AI-powered 3D visualization tools, enabling homeowners to experiment with different layouts, color schemes, and furnishings before finalizing their designs. The rise of online platforms has further enabled consumers to collaborate with designers remotely, streamlining the customization process. As disposable incomes rise and consumers become more design-conscious, the demand for personalized interiors is expected to continue growing.
Expansion of Sustainable and Eco-Friendly Designs
Sustainability is no longer just a niche trend but a mainstream movement in China’s interior design industry. Consumers are increasingly opting for environmentally friendly materials such as bamboo, reclaimed wood, and non-toxic paints to reduce their carbon footprint. Developers and interior designers are integrating green building principles, such as passive cooling techniques and energy-efficient lighting, to create eco-conscious living and working environments. The Chinese government’s commitment to carbon neutrality and stricter environmental regulations are further driving sustainable design innovations. As a result, brands specializing in eco-friendly interior solutions are witnessing rising demand, and green certifications for residential and commercial spaces are becoming more valuable in the real estate market. For instance, leading real estate developers like China Vanke and Longfor Group are incorporating sustainable building materials such as recycled wood, bamboo flooring, and low-VOC paints into their residential and commercial projects to align with China's carbon neutrality goals.
Market Challenges Analysis:
Rising Costs of Raw Materials and Labor
The increasing costs of raw materials and skilled labor present a significant challenge to China’s interior design market. Prices of essential materials such as wood, metals, and high-quality fabrics have surged due to supply chain disruptions, environmental regulations, and fluctuating import tariffs. Additionally, labor costs have risen as demand for skilled interior designers, architects, and craftsmen grows, particularly in major urban centers. These cost pressures are making high-end interior design services less accessible to middle-income consumers, potentially limiting market expansion.
Stringent Regulatory and Environmental Compliance
China’s tightening regulations on construction and environmental sustainability have introduced compliance challenges for interior designers and developers. Stricter standards on material sourcing, energy efficiency, and waste management require businesses to adopt sustainable practices, which often involve higher costs and extended project timelines. Non-compliance with these regulations can lead to legal penalties, project delays, or increased operational expenses. While sustainability is a growing trend, the regulatory burden can be complex, particularly for smaller firms with limited resources.
High Competition and Market Fragmentation
The interior design industry in China is highly fragmented, with a mix of international firms, established domestic players, and independent designers competing for market share. This intense competition has led to pricing pressures, making it difficult for some firms to maintain profitability. Additionally, consumer preferences are rapidly evolving, requiring constant innovation and adaptation to stay relevant. Smaller design firms and freelance designers often struggle to differentiate themselves in an increasingly saturated market, limiting their growth potential.
Fluctuations in Real Estate Market Demand
The interior design market is closely tied to the real estate sector, making it vulnerable to fluctuations in property demand and government policies. Periods of slowing real estate growth, tighter mortgage policies, or restrictions on housing investments can directly impact the demand for interior design services. Any downturn in residential or commercial real estate can lead to reduced client budgets, delayed projects, and overall market uncertainty. As a result, interior design firms must adopt diversified strategies to mitigate risks associated with real estate market fluctuations.
Market Opportunities:
China’s interior design market presents significant opportunities driven by urbanization, rising disposable incomes, and evolving consumer preferences. The rapid expansion of smart cities and infrastructure development continues to fuel demand for high-quality interior design services in both residential and commercial sectors. The government’s focus on green building initiatives and sustainable urban planning creates a favorable environment for interior designers to integrate eco-friendly solutions, energy-efficient materials, and smart home technologies. Additionally, the increasing preference for personalized and luxury interior designs among the affluent population opens new avenues for high-end, bespoke design services. With a growing number of homeowners investing in renovations and modern interior aesthetics, firms offering innovative and technology-driven solutions are well-positioned to capitalize on this expanding market.
The rise of digital platforms and e-commerce in the interior design industry further enhances market opportunities. Online consultation services, virtual design tools, and AI-powered interior design solutions are making professional services more accessible to a broader consumer base. This shift toward digital transformation allows design firms to reach customers in Tier 2 and Tier 3 cities, where demand for modern interiors is rising. Additionally, the hospitality, retail, and office sectors are increasingly prioritizing interior aesthetics to enhance customer experiences, creating a steady demand for commercial interior design solutions. As sustainability, smart technology, and digital innovation continue to shape consumer expectations, companies that embrace these trends are likely to gain a competitive edge in China’s evolving interior design landscape.
Market Segmentation Analysis:
The China interior design market is diverse, catering to various project types, service offerings, budget ranges, and client profiles. Each segment plays a crucial role in shaping market demand and influencing industry growth.
By Project Type, the residential sector dominates due to rising homeownership, increasing disposable incomes, and the growing preference for modern and personalized living spaces. The commercial and hospitality segments are expanding rapidly as businesses focus on aesthetics to enhance customer experiences. Healthcare, retail, educational, and public building projects also contribute significantly, driven by government investments in infrastructure and facility modernization.
By Service Type, interior design consulting, space planning, and decoration are among the most sought-after services. Furniture & fixture selection, lighting design, and color consultation are increasingly in demand as consumers seek fully integrated design solutions tailored to their specific needs.
By Budget Range, projects vary widely, from under $10,000 for minor refurbishments to over $500,000 for luxury and large-scale developments. The mid-range segment ($10,000-$100,000) holds a significant market share, particularly for residential and small commercial projects.
By Project Complexity, the market caters to simple refurbishments, major renovations, new builds, and high-end luxury projects. The high-end segment is growing due to rising demand for premium design, bespoke interiors, and exclusive aesthetics.
By Client Type, homeowners and businesses represent the largest client base, while architects, contractors, developers, and property managers drive demand in large-scale and commercial projects. The growing collaboration between interior designers and real estate developers further strengthens the market.
Segmentation:
By Project Type
- Residential
- Commercial
- Hospitality
- Healthcare
- Retail
- Educational
- Public Buildings
By Service Type
- Interior Design Consulting
- Interior Decoration
- Space Planning
- Furniture & Fixture Selection
- Lighting Design
- Color Consultation
By Budget Range
- Under $10,000
- $10,000-$50,000
- $50,000-$100,000
- $100,000-$250,000
- $250,000-$500,000
- Over $500,000
By Project Complexity
- Simple Refurbishment
- Major Renovation
- New Build
- High-End Luxury
By Client Type
- Homeowners
- Businesses
- Architects
- Contractors
- Developers
- Property Managers
Regional Analysis:
China's interior design market exhibits strong regional variations, with demand largely influenced by economic development, urbanization, and real estate activity. The market is primarily segmented into Tier 1 cities, Tier 2 and Tier 3 cities, and emerging urban centers, each contributing differently to the overall industry growth. The distribution of market share varies, with Tier 1 cities leading the segment, followed by rapidly expanding Tier 2 and Tier 3 markets.
Tier 1 Cities: Beijing, Shanghai, Guangzhou, and Shenzhen (Market Share: ~45%)
Tier 1 cities dominate the interior design market, accounting for nearly 45% of the total industry revenue. These metropolitan hubs attract high-income professionals, luxury property developments, and commercial real estate investments, creating significant demand for premium interior design services. Shanghai and Beijing, in particular, are centers for luxury residential and hospitality design, with an increasing preference for high-end, customized interiors. The presence of international design firms and large-scale commercial projects further fuels the market. Additionally, the growing number of technology-driven smart homes in Shenzhen and Guangzhou contributes to the adoption of innovative, tech-integrated interior solutions.
Tier 2 and Tier 3 Cities: Chengdu, Hangzhou, Wuhan, Nanjing, Xi’an (Market Share: ~35%)
Tier 2 and Tier 3 cities are emerging as key growth drivers, collectively holding around 35% of the market share. These cities have experienced rapid economic development and urbanization, leading to a surge in residential and commercial construction. Rising disposable incomes and changing lifestyle preferences have fueled demand for modern, functional interior designs. Chengdu and Hangzhou, known for their vibrant real estate markets, are seeing increased investment in upscale residential and commercial interior projects. With government policies promoting regional urbanization and infrastructure expansion, interior design firms have vast opportunities to cater to the growing middle-class population seeking stylish and affordable design solutions.
Emerging Urban Centers and Rural Areas (Market Share: ~20%)
Smaller urban centers and rural areas collectively contribute approximately 20% of the interior design market. While demand in these regions remains relatively lower than in major cities, increased homeownership and rising interest in aesthetic home improvements are gradually shaping the market. Prefabricated modular homes and cost-effective interior design solutions are gaining popularity in these regions, especially as digital platforms make interior design services more accessible. Government-backed initiatives to develop smart and eco-friendly housing in suburban and rural areas are expected to further stimulate market expansion in the coming years.
Key Player Analysis:
- Gensler
- Jacobs Engineering Group Inc.
- Perkins and Will
- Stantec Inc
- Areen Design Services Ltd
- IA Interior Architects
- Cannon Design
- Hirsch Bedner Associates
- NELSON & Associates Interior Design and Space Planning Inc.
- Büro Kif
- Framework Studio
- Company 13
- Company 14
Competitive Analysis:
China’s interior design market is highly competitive, with a mix of international design firms, domestic market leaders, and independent designers vying for market share. Established global firms bring expertise in luxury and commercial interiors, catering to high-net-worth individuals and multinational corporations. Domestic players, including large-scale interior design companies and boutique studios, dominate the mid-to-high-end residential and commercial segments, leveraging deep market knowledge and cultural insights to offer tailored design solutions. For instance, OPPEIN Home Group has established itself as a global leader in the home décor and cabinetry industries, offering custom home furnishing solutions. The market is also witnessing increased digitalization, with online design platforms providing affordable and accessible interior design services to a broader consumer base. Technology-driven firms integrating AI, virtual reality (VR), and smart home solutions are gaining a competitive edge. Additionally, the demand for eco-friendly and sustainable designs is pushing firms to adopt innovative materials and green building practices. As competition intensifies, companies that differentiate through technological innovation, personalization, and sustainability are poised for long-term success in China’s evolving interior design landscape.
Recent Developments:
- In January 21, 2025, AECOM announced that it will deliver an Investigation Study for Hong Kong's first Wetland Conservation Park in the Northern Metropolis. This project involves comprehensive services for the investigation stage, including preliminary design and engineering infrastructure.
- In November 2024, Gensler, the world-renowned architectural firm, has partnered with Studio T Arts & Entertainment to expand the $30 million 'Innovation Factory,' aimed at empowering underserved youth
Market Concentration & Characteristics:
The China interior design market is highly fragmented, with a mix of large domestic firms, international design companies, and independent designers competing for market share. No single company dominates the industry, as consumer preferences vary across different income groups and regional markets. Tier 1 cities, where demand for luxury and high-end designs is concentrated, attract well-established firms, while mid-tier and budget-conscious segments are largely served by smaller studios and online design platforms. The market is characterized by rapid digital transformation, rising demand for personalized designs, and a growing emphasis on sustainability. The adoption of AI, virtual reality (VR), and smart home technologies is reshaping design processes, enhancing customer experiences, and improving project efficiency. Additionally, regulatory policies promoting eco-friendly construction and green building practices are pushing firms to integrate sustainable materials and energy-efficient solutions. As the industry evolves, companies that leverage technology, sustainability, and customization will remain competitive.
Report Coverage:
The research report offers an in-depth analysis based on By Project Type, By Service Type, By Budget Range , By Project Complexity and By Client Type. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market is expected to continue growing at a steady CAGR, driven by urbanization, rising disposable incomes, and evolving consumer preferences.
- Smart home integration will become a key trend, with increasing adoption of AI, IoT, and automation in residential and commercial interiors.
- Sustainability and eco-friendly designs will gain prominence, driven by government policies and consumer awareness of green building practices.
- Tier 2 and Tier 3 cities will emerge as high-growth areas, offering new opportunities for interior design firms as urbanization expands beyond Tier 1 cities.
- Personalized and customizable interiors will see rising demand, particularly in luxury residential and high-end commercial spaces.
- Online design platforms will continue to expand, making professional interior design services more accessible to a broader consumer base.
- Collaboration between technology firms and designers will enhance project efficiency, customer experience, and design visualization.
- Competition will intensify, with domestic firms leveraging cultural insights while international firms target premium segments.
- Regulatory frameworks on environmental standards will push the adoption of sustainable materials and energy-efficient solutions in interior design.
- Investment in commercial and hospitality interiors will grow, as businesses prioritize aesthetics to enhance customer engagement and brand identity.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rapid Urbanization and Infrastructure Development
China's ongoing urbanization and large-scale infrastructure projects are fueling demand for interior design services, especially in Tier 1 and fast-growing Tier 2 and Tier 3 cities, as new residential and commercial spaces require professional design solutions.
Rising Disposable Incomes and Middle-Class Expansion
The growth of China's middle class and increasing disposable incomes are leading to higher consumer spending on home renovations and premium interior aesthetics, driving demand for personalized and high-quality interior design services.
Technological Advancements in Design Tools
The adoption of 3D visualization, virtual reality (VR), and AI-driven design platforms is transforming the industry by enabling immersive client experiences, efficient project execution, and greater customization, making professional design more accessible.
Government Policies Supporting Green Building and Sustainability
Policies promoting urban renewal, green building, and carbon neutrality are encouraging the use of eco-friendly materials and energy-efficient solutions, pushing both demand and innovation in sustainable interior design.
Digitalization and Online Design Platforms
The rise of online interior design services and digital platforms is expanding market reach, allowing firms to serve a broader demographic, including customers in emerging urban centers and rural areas, thus increasing overall market penetration.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size and growth projection of China's interior design market?
What are the key drivers of growth in China’s interior design market?
Which regions in China contribute the most to the interior design market?
What are the key challenges faced by the China interior design market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Budget Range
- 1.2.1 Under $10,000
- 1.2.2 $10,000-$50,000
- 1.2.3 $50,000-$100,000
- 1.2.4 $100,000-$250,000
- 1.2.5 $250,000-$500,000
- 1.2.6 Over $500,000
- 1.3 By Project Type
- 1.3.1 Residential
- 1.3.2 Commercial
- 1.3.3 Hospitality
- 1.3.4 Healthcare
- 1.3.5 Retail
- 1.3.6 Educational
- 1.3.7 Public Buildings
- 1.4 By Service Type
- 1.4.1 Interior Design Consulting
- 1.4.2 Interior Decoration
- 1.4.3 Space Planning
- 1.4.4 Furniture & Fixture Selection
- 1.4.5 Lighting Design
- 1.4.6 Color Consultation
- 1.5 By Project Complexity
- 1.5.1 Simple Refurbishment
- 1.5.2 Major Renovation
- 1.5.3 New Build
- 1.5.4 High-End Luxury
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 16,396.97 million → 2032: USD 28,505.43 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 China Interior Design Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 China Interior Design Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 China Interior Design Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 China Interior Design Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 China Interior Design Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 China Interior Design Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 China Interior Design Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 China Interior Design Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 16,396.97 million → 2032: USD 28,505.43 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 China Interior Design Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Budget Range - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Under $10,000
- 12.3.7.2 $10,000-$50,000
- 12.3.7.3 $50,000-$100,000
- 12.3.7.4 $100,000-$250,000
- 12.3.7.5 $250,000-$500,000
- 12.3.7.6 Over $500,000
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Project Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Residential
- 12.4.7.2 Commercial
- 12.4.7.3 Hospitality
- 12.4.7.4 Healthcare
- 12.4.7.5 Retail
- 12.4.7.6 Educational
- 12.4.7.7 Public Buildings
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Service Type - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Interior Design Consulting
- 12.5.7.2 Interior Decoration
- 12.5.7.3 Space Planning
- 12.5.7.4 Furniture & Fixture Selection
- 12.5.7.5 Lighting Design
- 12.5.7.6 Color Consultation
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Project Complexity - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Simple Refurbishment
- 12.6.7.2 Major Renovation
- 12.6.7.3 New Build
- 12.6.7.4 High-End Luxury
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 China Interior Design Geographic Market Outlook, 2023-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 China Interior Design Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 China Interior Design Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Gensler
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Jacobs Engineering Group Inc.
- 17.4 Perkins and Will
- 17.5 Stantec Inc
- 17.6 Areen Design Services Ltd
- 17.7 IA Interior Architects
- 17.8 Cannon Design
- 17.9 Hirsch Bedner Associates
- 17.10 NELSON & Associates Interior Design and Space Planning Inc.
- 17.11 OPPEIN Home Group
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

