
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| China Interior Finish Market Size 2023 | USD 1,195.16 million |
| China Interior Finish Market, CAGR | 8.16% |
| China Interior Finish Market Size 2032 | USD 2,423.29 million |
Market Overview:
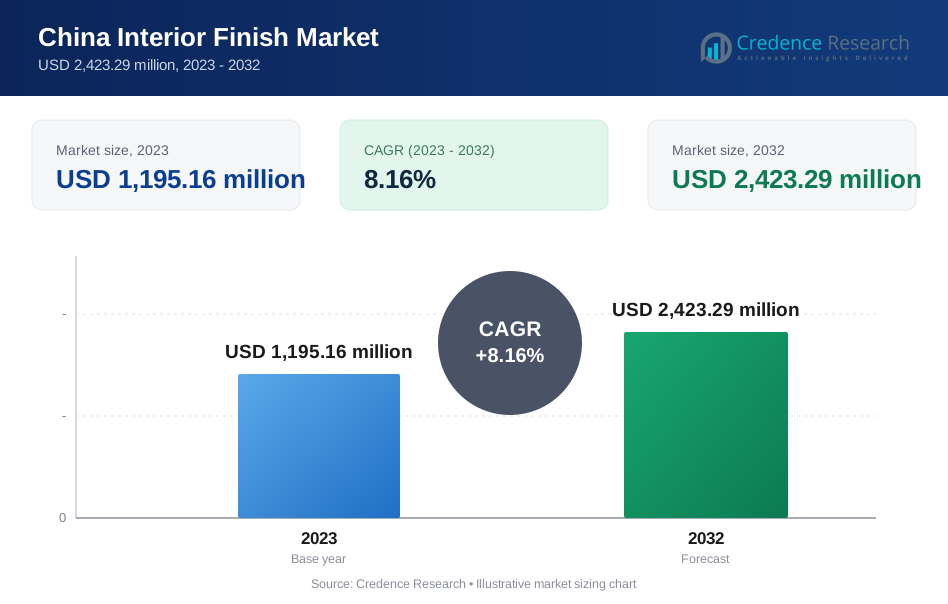
China Interior Finish Market size was valued at USD 1,195.16 million in 2023 and is anticipated to reach USD 2,423.29 million by 2032, at a CAGR of 8.16% during the forecast period (2023-2032).
One of the key factors driving the China Interior Finish Market is the booming real estate industry, which has led to high demand for premium interior finishing materials such as flooring, wall coverings, ceiling systems, and decorative paints. The shift toward modern architectural designs and sustainable materials is accelerating the adoption of eco-friendly interior finishes, including low-VOC paints, bamboo flooring, and recycled wood panels. Additionally, the rising middle-class population, coupled with changing lifestyle preferences, is driving consumer demand for luxury and customized interior solutions. Technological advancements, such as smart home integration and the use of digital printing in interior décor, are further propelling market growth. Moreover, government initiatives promoting green buildings and energy efficiency standards are encouraging the adoption of sustainable interior finish products across new construction and renovation projects.
The China Interior Finish Market exhibits strong regional variations, with tier-1 cities such as Beijing, Shanghai, Guangzhou, and Shenzhen leading in demand due to rapid urbanization, high disposable incomes, and a concentration of high-end residential and commercial projects. These cities have a strong preference for premium interior finishes, including high-performance coatings, luxury vinyl flooring, and advanced modular ceiling systems. Meanwhile, tier-2 and tier-3 cities are emerging as significant markets due to government-led urban development programs and increasing investments in residential construction. Additionally, the growing construction of commercial complexes, hotels, and office spaces in these regions is contributing to market expansion. The western and central provinces are also witnessing steady growth, driven by infrastructure projects and industrial development. Overall, the market’s growth trajectory is expected to remain strong, supported by rising real estate investments and evolving consumer preferences.
Market Insights:
- Booming real estate industry continues to drive demand for premium interior finishes, including flooring, wall coverings, ceiling systems, and decorative paints, across residential and commercial sectors.
- Sustainable materials are gaining traction, with increasing adoption of low-VOC paints, bamboo flooring, and recycled wood panels due to environmental regulations and growing consumer awareness.
- Technological advancements, such as smart home integration, digital printing, and nanotechnology coatings, are transforming the interior finish market by offering innovative and high-performance solutions.
- Tier-1 cities like Beijing, Shanghai, Guangzhou, and Shenzhen dominate the market, with high demand for luxury interior solutions, while tier-2 and tier-3 cities are emerging as key growth areas due to government-backed urban development projects.
- Rising disposable incomes and shifting lifestyle preferences are driving demand for personalized, aesthetic-driven interior solutions, particularly in the high-end residential and hospitality sectors.
- Government initiatives promoting energy efficiency and green buildings are accelerating the adoption of sustainable and modular interior finishes, creating growth opportunities for eco-friendly product manufacturers.
- Fluctuating raw material costs and supply chain disruptions pose challenges to the market, pushing manufacturers to invest in local sourcing, cost-effective alternatives, and supply chain resilience strategies.
Market Drivers:
Rising Urbanization and Infrastructure Development
China's rapid urbanization is a major driver of the interior finish market, as expanding cities and new housing projects continue to boost demand for high-quality interior materials. The government’s focus on infrastructure development, including residential, commercial, and industrial spaces, has led to a surge in construction activities. For instance, according to the National Bureau of Statistics. The government’s infrastructure development initiatives, such as the "14th Five-Year Plan," have allocated $1.4 trillion for urban renewal and smart city projects. With large-scale urban renewal projects underway, the need for durable, aesthetically appealing, and functional interior finishes has increased significantly. The expansion of smart cities and eco-friendly buildings further supports the adoption of innovative finishing materials, including energy-efficient coatings, advanced wall panels, and modular flooring solutions. As urbanization continues, the interior finish market will see sustained growth, driven by the increasing preference for modern and high-performance materials.
Shifting Consumer Preferences Toward Sustainability and Aesthetics
Growing environmental awareness among consumers and stricter regulations on sustainable construction materials have fueled the demand for eco-friendly interior finishes. The Chinese government has implemented stringent policies to reduce carbon footprints in the construction sector, encouraging the use of low-VOC paints, recycled wood, bamboo flooring, and water-based adhesives. For instance, Companies like Nippon Paint China have introduced low-VOC paints with formaldehyde removal efficiency. At the same time, changing consumer lifestyles and rising disposable incomes have led to greater interest in premium and customized interior finishes. Homeowners and businesses are seeking interior solutions that offer both aesthetic appeal and long-term functionality, resulting in increased adoption of high-end decorative paints, luxury vinyl tiles, and smart lighting systems. The intersection of sustainability and aesthetics is redefining product offerings, pushing manufacturers to innovate in material design and production techniques.
Technological Advancements in Interior Finishes
The adoption of advanced technologies in interior finish products is revolutionizing the market, enabling manufacturers to offer digitally printed wall coverings, 3D-textured surfaces, and self-cleaning coatings. For example, Guangdong Dongpeng Holdings has developed nano-ceramic tiles with anti-bacterial properties, achieving over 99% reduction in bacterial growth, as verified by SGS testing. Smart home integration is also influencing the interior finish market, with innovations such as voice-controlled lighting systems, touchless wall panels, and heat-reflective paints gaining popularity. The development of nanotechnology-enhanced coatings and anti-bacterial flooring solutions is further enhancing product appeal, particularly in the commercial and healthcare sectors. Additionally, prefabricated and modular interior solutions are gaining traction due to their cost-efficiency and time-saving benefits in large-scale construction projects. With continuous investments in research and development, technological advancements will remain a driving force behind market expansion.
Government Policies and Real Estate Growth
The Chinese government’s supportive policies for green building initiatives, smart city infrastructure, and affordable housing projects have significantly influenced the interior finish market. The New Urbanization Plan and the National Green Building Action Plan are pushing for higher standards in construction materials, leading to increased demand for energy-efficient and sustainable interior finishes. Additionally, the steady growth of the real estate sector, driven by increasing residential property sales and large-scale commercial projects, is fueling demand for modern and durable interior finishes. For instance, the Shanghai Tower, a LEED Platinum-certified building, utilizes advanced interior finishes like low-VOC paints and energy-efficient lighting. The rising popularity of co-working spaces, luxury hotels, and high-end office buildings is further contributing to the adoption of advanced finishing materials. As government regulations and real estate investments continue to shape the market landscape, interior finish manufacturers are aligning their strategies to meet evolving industry standards and consumer expectations.
Market Trends:
Growing Demand for Smart and Automated Interior Solutions
The integration of smart technologies into interior finishes is transforming the market landscape in China. For example, Shelly's new Gen4 devices, expected in early 2025, support multiple protocols like Wi-Fi, Bluetooth, Zigbee, and Matter, ensuring wide integration with platforms like Google Home, Alexa, and Apple HomeKit. Home automation systems, including intelligent lighting, smart window treatments, and automated climate control, are becoming standard in high-end residential and commercial projects. Consumers are increasingly opting for voice-activated controls, sensor-based temperature regulation, and energy-efficient LED solutions to enhance convenience and energy savings. The demand for smart coatings that offer self-cleaning, anti-microbial, and thermal insulation properties is also gaining momentum, particularly in urban households and public infrastructure projects. As the adoption of IoT-driven interior solutions rises, manufacturers are focusing on integrating digital technology with traditional finishing materials to cater to evolving consumer preferences.
Increasing Popularity of Sustainable and Low-Emission Materials
Sustainability is a defining trend in China's interior finish market, as both regulatory mandates and consumer awareness drive demand for low-emission paints, biodegradable flooring, and eco-friendly wall panels. The construction industry is witnessing a shift toward materials that contribute to carbon neutrality and improved indoor air quality, aligning with China’s broader environmental goals. The adoption of bamboo-based products, water-based adhesives, and non-toxic finishes is expanding, particularly in green-certified residential and commercial spaces. For instance, For instance, the Engineering Research Centre for Bamboo Winding Composites (ERCBWC) has developed new bamboo composites that can be utilized in various applications, including heavy-duty drainage pipes and flooring. These products are not only durable but also contribute to carbon-negative outcomes over their life cycle, with engineered bamboo materials showing a potential for long-term sustainability due to their ability to store carbon. Additionally, manufacturers are investing in recyclable and reusable materials, ensuring a reduced ecological footprint while maintaining durability and aesthetic appeal. This trend is expected to accelerate as China tightens its environmental policies and consumers prioritize health-conscious living environments.
Rise of Customization and Aesthetic-Driven Interiors
Chinese consumers are increasingly seeking personalized interior solutions that reflect their lifestyle preferences, leading to a surge in demand for customized flooring, decorative wall treatments, and bespoke ceiling designs. High-end residential and commercial spaces are embracing 3D-printed decorative panels, digitally customized wallpapers, and artisanal handcrafted finishes to achieve unique aesthetics. The luxury interior finish segment is also experiencing growth, with an emphasis on premium wood finishes, metallic wall accents, and intricate mosaic tiling. This shift toward personalization is particularly evident in hospitality, retail, and office spaces, where experiential design elements play a crucial role in enhancing brand identity. As aesthetic preferences continue to evolve, manufacturers are offering a diverse range of textures, patterns, and finishes to meet the growing demand for tailored interior designs. For instance, companies such as Shangpin Custom Furniture are focusing on handcrafted wood finishes that allow customers to choose from various stains and textures. Their recent collection features over 30 different wood types and finishes, enabling clients to create truly bespoke interiors.
Expansion of Prefabricated and Modular Finishing Systems
The adoption of modular interior solutions is on the rise, driven by the need for time-efficient and cost-effective construction practices. Prefabricated wall panels, ceiling systems, and flooring modules are increasingly being used in residential complexes, office buildings, and commercial spaces, reducing installation time and labor costs. The trend is further supported by China's rapid urban development and large-scale real estate projects, where speed and efficiency are critical factors. In addition, modular kitchen and bathroom solutions are becoming popular in urban housing, providing homeowners with ready-to-install, customizable interior elements. With advancements in lightweight materials and improved assembly techniques, modular finishing systems are expected to gain further traction, catering to the growing demand for flexible and high-quality interior solutions. For instance, Ark Prefab Co., Ltd. has introduced modular kitchen units designed for rapid installation. These kitchens can be assembled in less than two days on-site, significantly cutting down construction time compared to conventional kitchens, which typically take weeks to install.
Market Challenges Analysis:
Regulatory Compliance and Environmental Constraints
The China Interior Finish Market faces significant challenges due to stringent government regulations on environmental sustainability and emissions control. The construction sector is under increasing pressure to comply with China’s green building standards, which mandate the use of low-VOC paints, non-toxic adhesives, and energy-efficient materials. While these regulations aim to enhance indoor air quality and reduce the carbon footprint, they also impose higher costs on manufacturers, requiring investment in research, development, and production of eco-friendly alternatives. Additionally, the frequent updates to environmental policies create uncertainty in material sourcing and product development, making it difficult for businesses to adapt quickly. Compliance with these evolving standards requires continuous innovation, increasing operational costs and limiting the availability of affordable interior finish products for cost-sensitive consumers.
Fluctuating Raw Material Costs and Supply Chain Disruptions
The volatility in raw material prices poses another major restraint on the market. The prices of wood, polymers, metal fixtures, and chemical coatings fluctuate due to global supply chain disruptions, trade restrictions, and changes in raw material availability. China’s heavy reliance on imported timber and specialty coatings further amplifies the challenge, as tariffs and logistical inefficiencies drive up costs. Additionally, the construction sector slowdown in certain regions has led to inconsistent demand for interior finish materials, affecting production planning and inventory management. The increasing cost of transportation, labor shortages, and supply chain bottlenecks have also contributed to delays in project execution. To mitigate these challenges, industry players must adopt strategic sourcing, invest in local material production, and explore alternative materials that offer cost efficiency without compromising quality and performance.
Market Opportunities:
The China Interior Finish Market presents significant growth opportunities, driven by expanding urbanization, rising disposable incomes, and increasing consumer demand for high-quality, aesthetically appealing interior solutions. The rapid development of smart cities and green buildings is fueling demand for sustainable, energy-efficient, and technologically advanced finishing materials. With government policies promoting eco-friendly construction and stricter regulations on low-emission materials, there is an opportunity for manufacturers to innovate in recyclable, biodegradable, and VOC-free products. The growing trend of luxury and customized interiors in both residential and commercial segments also creates a demand for premium wall finishes, designer flooring, and modular ceiling systems, further expanding the market potential.
Additionally, the rise of prefabricated construction and modular interior solutions is opening new avenues for growth, as these technologies offer cost-effective, time-efficient, and flexible design alternatives. The expansion of e-commerce platforms in China has enhanced accessibility to a wide range of interior finish materials, enabling manufacturers to reach a broader consumer base. Technological advancements in digital printing, smart coatings, and nanotechnology are also shaping the future of interior finishes, offering innovative solutions tailored to evolving customer needs. With increasing investments in commercial infrastructure, office spaces, and hospitality projects, the market is well-positioned for sustained expansion, offering lucrative opportunities for companies that can adapt to evolving design trends, regulatory requirements, and consumer preferences.
Market Segmentation Analysis:
By Type
The China Interior Finish Market is segmented into Personalized Customization and Standardized Package. The Personalized Customization segment is experiencing strong growth as consumers increasingly seek tailored interior solutions that reflect their aesthetic preferences and lifestyle needs. This trend is particularly prevalent in high-end residential and luxury commercial spaces, where unique materials, textures, and digital printing techniques are used to create distinctive interior designs. Additionally, advancements in smart home technology and the growing demand for sustainable, eco-friendly materials are further enhancing the appeal of customized interior finishes. Conversely, the Standardized Package segment holds a significant share in the market due to its cost-effectiveness, efficiency, and wide applicability in large-scale construction projects. Real estate developers, commercial properties, and public infrastructure projects favor standardized interior solutions for their ease of installation, uniform quality, and reduced material wastage. As urbanization expands, this segment will continue to grow, particularly in affordable housing and mass commercial developments.
By Application
The market is also segmented by application into Residential, Commercial Indoor, and Public Space. The Residential segment leads the market, driven by rising urbanization, increasing disposable income, and evolving consumer preferences for modern and sustainable interiors. The demand for smart, durable, and energy-efficient interior finishes is growing as homeowners focus on long-term value. The Commercial Indoor segment, including offices, retail spaces, and hotels, is witnessing strong growth due to corporate investments in high-end, aesthetically appealing environments. Meanwhile, the Public Space segment, covering government buildings, transport hubs, and educational institutions, is expanding due to government-driven infrastructure projects promoting sustainable and durable interior materials.
Segmentation:
By Type
- Personalized Customization
- Standardized Package
By Application
- Residential
- Commercial Indoor
- Public Space
Regional Analysis:
Eastern China: Dominating the Market with High Urbanization
Eastern China holds the largest share of the China Interior Finish Market, accounting for approximately 40% of the total market. This dominance is driven by the presence of major metropolitan hubs such as Shanghai, Hangzhou, and Nanjing, where rapid urbanization and a thriving real estate sector continue to propel demand for high-quality interior finishes. The region’s strong economic base, supported by high disposable incomes and large-scale commercial developments, has led to increased investment in luxury interiors, energy-efficient coatings, and smart home solutions. Additionally, government-led green building initiatives in these cities have accelerated the adoption of sustainable materials, further strengthening market growth.
Southern China: Expanding Residential and Commercial Developments
Southern China holds a market share of around 25%, with cities like Guangzhou, Shenzhen, and Xiamen serving as key growth centers. The region’s strong manufacturing base and high-paced real estate development contribute to the rising demand for modular flooring, premium wall treatments, and decorative ceiling systems. Southern China is also witnessing an increasing preference for customized interior solutions, particularly in the luxury residential and hospitality sectors. The influx of technology-driven construction projects, including smart offices and co-working spaces, is further fueling demand for innovative interior finishing materials.
Northern China: Rising Infrastructure Projects and Sustainability Initiatives
Northern China represents approximately 18% of the market share, driven by ongoing infrastructure and commercial developments in cities such as Beijing, Tianjin, and Shijiazhuang. The government’s push for affordable housing and green construction is stimulating demand for low-emission paints, recyclable flooring materials, and modular interior solutions. Additionally, Beijing’s role as a political and economic hub has led to increased investments in high-end office spaces, government buildings, and retail interiors, boosting market expansion. The focus on energy-efficient and temperature-regulating materials is particularly strong in this region due to its harsh winter climate, further influencing product demand.
Western and Central China: Emerging Markets with Strong Potential
Western and Central China collectively account for 17% of the market, but they are experiencing the fastest growth rates, driven by urbanization initiatives, industrial expansion, and government-backed infrastructure projects. Cities like Chengdu, Xi’an, and Wuhan are witnessing increasing demand for cost-effective, durable interior finishes as new residential and commercial developments rise. The Belt and Road Initiative (BRI) is further enhancing construction activity, creating new opportunities for modular interior systems and eco-friendly materials. Although these regions currently lag behind the more developed eastern and southern provinces, their rapid economic development presents significant future growth potential for the interior finish market.
Key Player Analysis:
- Saint-gobain
- Tristan Group
- ALGEDRA
- ARCH-INTERIORS Design Group
- Mimar Interiors
- B&B Italia
- Korte Company
- Tri-State Installation Services
- Stamhuis Group
- Pella Corporation
- Company 13
- Company 14
Competitive Analysis:
The China Interior Finish Market is highly competitive, characterized by the presence of both domestic and international players offering a diverse range of products, including flooring, wall coverings, paints, coatings, and modular ceiling systems. Leading companies compete on product innovation, sustainability, pricing strategies, and distribution networks to strengthen their market position. For instance, Nippon Paint has invested heavily in developing low-VOC (volatile organic compound) paints that comply with China’s stringent environmental regulations. Domestic manufacturers leverage cost advantages, local raw material sourcing, and extensive retail networks, while international brands focus on premium quality, eco-friendly certifications, and advanced technology integration to attract high-end consumers. Market competition is further intensified by the rising demand for sustainable and smart interior solutions, prompting companies to invest in R&D for low-emission materials, digital printing technologies, and energy-efficient coatings. The growing e-commerce presence and direct-to-consumer sales channels are also reshaping competitive dynamics, enabling smaller players to gain market access. As regulatory standards evolve, companies that adapt to environmental policies and shifting consumer preferences will maintain a competitive edge.
Recent Developments:
- Saint-Gobain completed the acquisition of FOSROC, a prominent construction chemicals player in Asia and emerging markets, on February 10, 2025. This move aims to strengthen Saint-Gobain's global presence in the construction chemicals sector and aligns with their strategy to lead in light and sustainable construction.
- In September 2023, a fund managed by Tristan Capital Partners acquired its first assets for a new German logistics platform. The assets, located in Glauchau and Zwickau, comprise 92,000 sqm of warehouse space and are let to VW and Schnellecke.
- In January 21, 2025,Saint-Gobain completed the acquisition of Grupo Ovniver, a leader in chemical product solutions for construction in Mexico and Central America4. Ovniver’s brands and teams will integrate into Saint-Gobain to promote lightweight and sustainable construction solutions in the Mexican and Latin American markets.
Market Concentration & Characteristics:
The China Interior Finish Market is moderately fragmented, with a mix of large multinational corporations, domestic manufacturers, and specialized regional players. While global brands dominate the high-end and premium interior finish segment, local companies maintain strong market presence through cost-effective solutions, extensive distribution networks, and localized product offerings. The market is witnessing intensifying competition, driven by rising demand for eco-friendly, technologically advanced, and aesthetically appealing materials. Key characteristics of the market include a strong shift toward sustainability, digital innovation, and smart interior solutions. The adoption of low-VOC paints, modular flooring, and 3D-printed wall finishes reflects growing consumer preference for customization and energy efficiency. Additionally, e-commerce and direct-to-consumer sales models are expanding market accessibility, enabling smaller players to compete effectively. As government regulations on green building materials tighten, companies investing in sustainable innovation and compliance will gain a competitive advantage.
Report Coverage:
The research report offers an in-depth analysis based on By Type and By Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising urbanization and infrastructure expansion will continue to drive demand for high-quality interior finish materials across residential and commercial sectors.
- Sustainability and environmental compliance will shape product innovation, with increased adoption of low-VOC paints, recycled materials, and energy-efficient finishes.
- Smart home integration will fuel demand for intelligent interior solutions, including sensor-based lighting, automated climate control, and digital wall panels.
- Prefabricated and modular interior systems will gain traction, reducing construction time and costs while enhancing design flexibility.
- Technological advancements in digital printing, nanotechnology coatings, and 3D-printed décor will enhance customization and material performance.
- Government policies promoting green buildings will accelerate the use of sustainable interior finishes, influencing industry-wide material standards.
- E-commerce expansion will drive accessibility, enabling consumers and businesses to source diverse interior finish products efficiently.
- Luxury and high-end interior solutions will witness steady growth as consumer preferences shift toward premium aesthetics and customized designs.
- Fluctuating raw material costs and supply chain challenges may impact pricing strategies, prompting manufacturers to explore alternative materials and local sourcing.
- Regional market development in Western and Central China will present new growth opportunities as urbanization spreads beyond tier-1 cities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the China Interior Finish Market?
What factors are driving the growth of the China Interior Finish Market?
What are the key segments within the China Interior Finish Market?
Which regions lead the China Interior Finish Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 China Interior Finish Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global China Interior Finish Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 1,195.16 million → 2032: USD 2,423.29 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 China Interior Finish Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. China Interior Finish Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 China Interior Finish Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 China Interior Finish Market Drivers
- 3.3 China Interior Finish Market Restraints & Challenges
- 3.4 China Interior Finish Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 China Interior Finish Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 China Interior Finish Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, China Interior Finish category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 China Interior Finish Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. China Interior Finish Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the China Interior Finish market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 China Interior Finish Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 China Interior Finish Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 China Interior Finish Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in China Interior Finish (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New China Interior Finish Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global China Interior Finish Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America China Interior Finish Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe China Interior Finish Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific China Interior Finish Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America China Interior Finish Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East China Interior Finish Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa China Interior Finish Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. China Interior Finish Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
