
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| China Luxury Interior Design Market Size 2023 | USD 13,481.96 million |
| China Luxury Interior Design Market, CAGR | 5.72% |
| China Luxury Interior Design Market Size 2032 | USD 22,253.00 million |
Market Overview
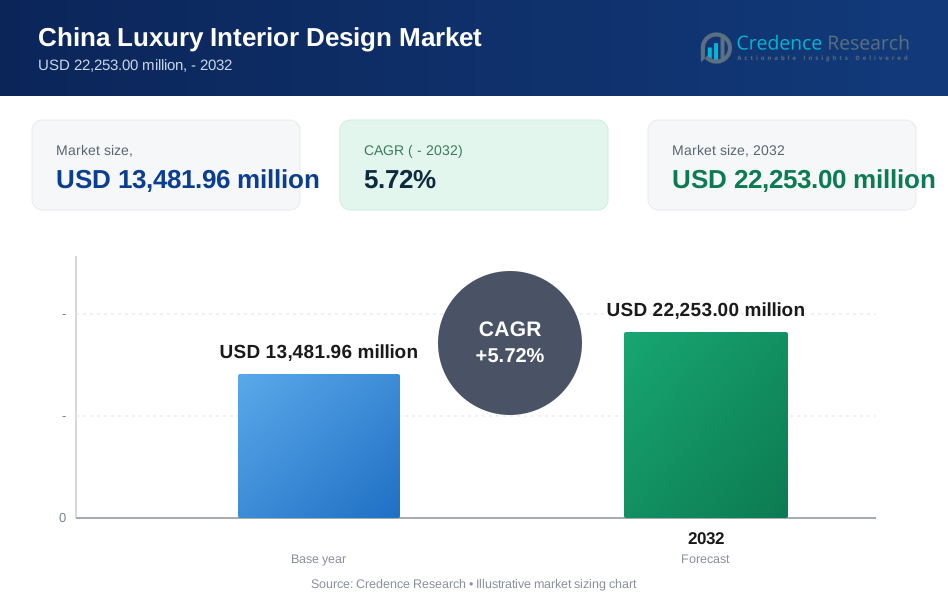
The China Luxury Interior Design Market is projected to grow significantly over the coming years, reflecting rising demand for high-end living spaces. The market size is expected to expand from USD 13,481.96 million in 2023 to an estimated USD 22,253.00 million by 2032, registering a robust compound annual growth rate (CAGR) of 5.72% from 2024 to 2032.
Key drivers of the market include the growing demand for exclusive and aesthetically appealing designs among high-net-worth individuals, as well as the increasing importance of sustainable and eco-friendly materials in luxury interiors. Emerging trends such as smart home integration and the use of cutting-edge technologies in design processes are further enhancing market attractiveness. Additionally, collaborations between luxury brands and interior designers are fueling innovation and expanding product portfolios to cater to discerning customer preferences.
Geographically, the market is dominated by tier-1 cities such as Beijing, Shanghai, and Guangzhou, where rapid urbanization and a concentration of wealthy individuals drive demand for premium interior design services. However, tier-2 and tier-3 cities are also witnessing notable growth as luxury lifestyles gain traction. Prominent players in the market include established firms like HOK, Gensler, Perkins & Will, and Hirsch Bedner Associates (HBA), along with local design studios that bring unique cultural elements into their offerings.
Market Insights
- The China luxury interior design market is projected to grow from USD 13,481.96 million in 2023 to USD 22,253.00 million by 2032, with a CAGR of 5.72% from 2024 to 2032.
- Increasing wealth among high-net-worth individuals is driving the demand for exclusive and personalized interior designs in both residential and commercial spaces.
- Rapid urbanization in tier-1 cities and the rise of affluence in tier-2 and tier-3 cities are fueling the expansion of luxury interior design services.
- Consumers are increasingly focused on sustainable and eco-friendly materials, pushing designers to integrate green building practices and energy-efficient solutions.
- Economic uncertainties and regulatory challenges, including real estate market fluctuations, can limit the growth of luxury interior design services in certain regions.
- Tier-1 cities such as Beijing, Shanghai, and Guangzhou dominate the market, but tier-2 and tier-3 cities are witnessing substantial growth as luxury lifestyles expand.
- The integration of smart home technologies and innovative design practices, such as AR/VR, is becoming a significant factor driving the market’s evolution.
Market Drivers
Rising Affluence and Expanding High-Net-Worth Individual (HNWI) Population
The rapid economic growth in China has led to a significant increase in disposable incomes, resulting in a burgeoning population of high-net-worth individuals (HNWIs). For instance, the number of HNWIs in China grew from approximately 780,000 in 2022 to over 1 million by 2024. This demographic shift is particularly notable in tier-1 cities like Beijing, Shanghai, and Shenzhen, where affluent families are investing significantly in luxurious and customized living spaces. The demand for premium interior design services is further fueled by these consumers’ aspirations for sophisticated aesthetics that reflect their social status. Additionally, the trend of personalization in luxury design is evident as consumers increasingly seek bespoke interiors that showcase their unique tastes and lifestyles. The integration of advanced technologies, such as virtual reality and 3D modeling, allows designers to create immersive experiences that cater to the specific preferences of these affluent clients. As a result, the luxury interior design market is evolving to meet the demands of a growing clientele that values exclusivity and personalization.
Urbanization and Premium Real Estate Development
China's rapid urbanization has dramatically transformed its urban landscape, leading to an increased demand for luxury housing and premium real estate. For example, between 2020 and 2024, the construction of high-end residential complexes surged by over 30%, reflecting a robust appetite for luxury living among affluent consumers. This trend is particularly pronounced in major cities where developers are focusing on creating aesthetically superior interiors to attract discerning buyers. The luxury interior design sector is thus positioned to thrive as property owners prioritize unique designs that not only enhance aesthetic appeal but also contribute to long-term property value appreciation. Furthermore, the alignment of luxury interior design with real estate development promotes a strategic investment approach for stakeholders in the industry. As urban centers continue to expand, the integration of exceptional interior design with premium real estate will remain a key driver of growth in this market segment.
Growing Focus on Personalization and Experiential Design
Consumers in China are increasingly prioritizing personalization and experiential design in their interiors, fueling the demand for bespoke luxury solutions. Interior designers are embracing advanced technologies such as 3D modeling, virtual reality (VR), and augmented reality (AR) to offer immersive design experiences and enable clients to visualize and customize their spaces before implementation. This emphasis on tailored designs has led to the incorporation of unique materials, custom furniture, and exclusive artistic elements that reflect the individual tastes and lifestyles of clients. The pursuit of distinctive and meaningful living environments continues to drive innovation in the luxury interior design market.
Emerging Trends in Sustainability and Smart Technology Integration
Sustainability and smart home technology are shaping the future of luxury interior design in China. Environmentally conscious consumers are increasingly demanding eco-friendly materials, energy-efficient systems, and sustainable design practices. In response, interior designers are integrating renewable resources, sustainable sourcing, and green building standards into their projects. Concurrently, the rising adoption of smart home technologies, including intelligent lighting, climate control, and integrated security systems, is transforming how luxury interiors are designed. These advancements not only enhance functionality but also align with the modern, tech-savvy preferences of China’s affluent clientele. The convergence of sustainability and technology ensures that luxury interior design remains innovative and relevant in the evolving market landscape.
Market Trends
High Competition and Fragmentation
The China luxury interior design market is characterized by intense competition and fragmentation, with numerous players ranging from global firms to local boutique studios vying for market share. This competitive landscape often results in price pressures that compel firms to innovate continuously in order to differentiate their services. For instance, Goldmantis, a leading Chinese interior design company, has successfully navigated this environment by focusing on eco-friendly designs and sustainable practices to attract environmentally conscious consumers. In 2022, Goldmantis achieved a remarkable turnover of 21.8 billion RMB, illustrating how aligning services with evolving consumer values can lead to success. However, smaller firms may struggle to compete with established players that possess greater resources and access to premium materials. Additionally, maintaining consistent quality and client satisfaction poses significant challenges for all market participants in such a competitive arena. As a result, companies must prioritize innovation and adaptability to thrive amid the pressures of a fragmented market.
Economic Uncertainty and Regulatory Barriers
Economic fluctuations and uncertainties significantly impact the luxury interior design market in China. Changes in property market regulations can lead to reduced demand for luxury housing, which directly affects the need for high-end interior design services. For example, recent stricter real estate policies have resulted in a slowdown in luxury housing developments, prompting a decrease in demand for bespoke interior design solutions. This environment necessitates adaptability and strategic planning among designers to mitigate risks and sustain growth. Navigating complex regulatory frameworks, including permits and compliance with building codes, presents additional challenges for interior designers. Firms must remain agile in their strategies to respond effectively to these economic uncertainties while ensuring compliance with evolving regulations. Consequently, the ability to adapt to these challenges is crucial for sustaining business operations and achieving long-term success in the dynamic luxury interior design landscape of China.
Growth of Smart and Connected Interiors
The rise of smart home technologies is a defining trend in the luxury interior design market. Clients are demanding advanced automation systems that seamlessly integrate lighting, climate control, security, and entertainment into their interiors. Designers are working closely with technology providers to create spaces that are not only aesthetically pleasing but also highly functional and responsive. The incorporation of voice-activated systems, energy-efficient appliances, and AI-driven solutions reflects the tech-savvy preferences of modern Chinese consumers.
Expansion of Eco-Friendly and Sustainable Practices
Sustainability continues to be a critical focus for the luxury interior design market in China. Consumers are increasingly opting for eco-friendly materials such as reclaimed wood, recycled metals, and low-VOC paints. Designers are also adopting green building standards and certifications, ensuring that their projects align with environmental goals. The emphasis on sustainability extends to energy-efficient lighting, water-saving fixtures, and renewable energy integration, making luxury interiors environmentally responsible without compromising on style and comfort.
Market Challenges
High Competition and Fragmentation
The China luxury interior design market is characterized by intense competition and fragmentation, with numerous players ranging from global firms to local boutique studios vying for market share. This competitive landscape often results in price pressures that compel firms to innovate continuously in order to differentiate their services. For instance, Goldmantis, a leading Chinese interior design company, has successfully navigated this environment by focusing on eco-friendly designs and sustainable practices to attract environmentally conscious consumers. In 2022, Goldmantis achieved a remarkable turnover of 21.8 billion RMB, illustrating how aligning services with evolving consumer values can lead to success. However, smaller firms may struggle to compete with established players that possess greater resources and access to premium materials. Additionally, maintaining consistent quality and client satisfaction poses significant challenges for all market participants in such a competitive arena. As a result, companies must prioritize innovation and adaptability to thrive amid the pressures of a fragmented market.
Economic Uncertainty and Regulatory Barriers
Economic fluctuations and uncertainties significantly impact the luxury interior design market in China. Changes in property market regulations can lead to reduced demand for luxury housing, which directly affects the need for high-end interior design services. For example, recent stricter real estate policies have resulted in a slowdown in luxury housing developments, prompting a decrease in demand for bespoke interior design solutions. This environment necessitates adaptability and strategic planning among designers to mitigate risks and sustain growth. Navigating complex regulatory frameworks, including permits and compliance with building codes, presents additional challenges for interior designers. Firms must remain agile in their strategies to respond effectively to these economic uncertainties while ensuring compliance with evolving regulations. Consequently, the ability to adapt to these challenges is crucial for sustaining business operations and achieving long-term success in the dynamic luxury interior design landscape of China.
Market Opportunities
Expansion in Emerging Cities and Suburban Areas
While tier-1 cities like Beijing, Shanghai, and Guangzhou have historically dominated the luxury interior design market in China, there is significant growth potential in tier-2 and tier-3 cities, as well as suburban areas. For instance, these regions are witnessing a substantial increase in demand for luxury interior design services. With rising disposable incomes, residents in these cities are increasingly prioritizing well-designed living spaces. A report indicates that 45% of middle-class consumers in tier-2 and tier-3 cities express interest in purchasing luxury goods, surpassing the 37% interest seen in tier-1 cities. This shift suggests a growing market for luxury interior design as these consumers seek to enhance their living environments with premium aesthetics and functionality.Moreover, the real estate sector in these emerging cities is booming, with developers focusing on creating high-end residential and commercial projects. The construction of approximately 7,000 new malls across China by 2025 highlights the expanding retail landscape, further driving demand for sophisticated interior design solutions tailored to affluent consumers. This trend presents a lucrative opportunity for interior designers and companies to tap into new markets and offer tailored services to an increasingly affluent clientele outside traditional metropolitan hubs.
Growth of Luxury Commercial Spaces and Hospitality Sector
In addition to residential demand, there is a burgeoning market for luxury interior design services within commercial spaces and the hospitality industry. The 2024 China Hotel Industry Development Report notes that there are around 610,000 accommodation facilities in China, including approximately 320,000 hotels. The hotel chain rate has increased significantly, indicating a shift towards more standardized luxury experiences that require high-quality interior design to meet guest expectations. As China solidifies its position as a global business hub, corporate clients are increasingly investing in luxurious office spaces designed to reflect their brand image.Furthermore, with China’s growing importance as a global business and tourism hub, the demand for high-end office buildings, luxury hotels, restaurants, and retail spaces is on the rise. Corporate clients, hotels, and resorts are seeking innovative, customized interiors to elevate their brand image and offer unique customer experiences. This growing trend of luxury in commercial properties presents an attractive market opportunity for interior design firms to expand their offerings and gain a competitive edge in these emerging segments.
Market Segmentation Analysis
By Type
The luxury interior design market in China is mainly divided into two segments: Repeatedly Decorated and Newly Decorated interiors. Repeatedly Decorated spaces involve frequent renovations or redesigns to keep up with evolving trends or maintain a modern aesthetic. This segment is particularly favored by high-net-worth individuals (HNWI) who value personalization and exclusivity, continuously updating their residential and commercial spaces to reflect their latest preferences. The demand for this segment is driven by a desire for innovation and maintaining a fashionable environment. In contrast, Newly Decorated interiors focus on the initial design and construction of luxury spaces, such as newly built high-end residences, commercial properties, and luxury hotels. This segment emphasizes the use of unique materials, advanced technology, and premium finishes to create distinctive, one-of-a-kind designs. The growth of this segment is primarily fueled by the booming real estate market, urbanization, and the increasing number of wealthy individuals seeking brand-new luxurious spaces.
By Application
The China luxury interior design market is segmented by application into Residential, Commercial, and Other sectors. The Residential segment remains the largest and most lucrative, driven by affluent consumers investing in custom-designed luxury homes such as villas, mansions, and high-end apartments that reflect personal style and modern tastes. The Commercial segment has seen rapid growth, fueled by increasing demand for luxury offices, retail spaces, hotels, and restaurants, where businesses seek to create premium, functional, and visually appealing environments that align with their brand identities. The "Other" applications include luxury interiors for institutional and public spaces, such as hospitals, airports, and cultural institutions, which require a balance of high-end design, functionality, and enhanced customer experiences.
Segments
Based on Type
- Repeatedly Decorated
- Newly Decorated
Based on Application
- Residential
- Commercial
- Others
Based on Region
- Beijing
- Shanghai
- Guangzhou
Regional Analysis
East China (40%)
East China, particularly cities such as Shanghai and Hangzhou, holds the largest market share in the luxury interior design sector, contributing approximately 40% of the total market value. Shanghai, as one of China’s financial and cultural centers, is home to a significant number of high-net-worth individuals and luxury property developments, driving demand for premium interior design services. The region’s economic prosperity, coupled with a strong focus on urban development and modernization, has led to an increasing number of luxury residential and commercial projects. This region also benefits from a high concentration of international design firms and global luxury brands, further fueling its dominance in the market.
South China (30%)
South China, including Guangzhou, Shenzhen, and Macau, is another critical region contributing about 30% to the market share. This region has seen rapid economic growth, particularly driven by the tech sector and tourism. Guangzhou and Shenzhen are home to affluent populations with an increasing appetite for luxurious, custom-designed interiors in both residential and commercial spaces. The demand in this region is also bolstered by the hospitality industry, with luxury hotels and resorts seeking top-tier design services. In Macau, the thriving luxury tourism sector further drives the demand for upscale interior design solutions in hotels and casinos.
Key players
- Aecom
- Gensler
- Jacobs Engineering Group Inc.
- Perkins and Will
- Stantec Inc.
- Areen Design Services Ltd
- IA Interior Architects
- Cannon Design
- Hirsch Bedner Associates
- NELSON & Associates Interior Design and Space Planning Inc.
- Walue Furniture Co. Ltd.
- Glodon Company Limited
Competitive Analysis
The China luxury interior design market is highly competitive, with both global design firms and regional players vying for market share. Major global firms such as Aecom, Gensler, and Jacobs Engineering Group Inc. dominate the market due to their strong brand recognition, extensive experience, and ability to handle large-scale projects. These companies offer comprehensive services, from design to project management, which attracts affluent clients seeking high-end, turn-key solutions. Regional players like Areen Design Services Ltd. and IA Interior Architects offer localized expertise and often capitalize on their deep understanding of Chinese culture and consumer preferences, giving them an edge in catering to the unique tastes of Chinese luxury consumers. Hirsch Bedner Associates and Perkins and Will focus on luxury hospitality and high-end residential projects, contributing to their strong position in the market. Smaller, specialized firms also play a significant role by providing bespoke, personalized services to high-net-worth individuals. As the market grows, competition will continue to intensify, requiring firms to innovate and differentiate themselves through design quality and customer service.
Recent Developments
- In December 2024, AECOM announced its strategic partnership with local developers in Shanghai to enhance luxury residential projects. This collaboration aims to integrate sustainable design practices into high-end interiors, reflecting the growing demand for eco-friendly living spaces among affluent consumers.
- In December 2024, Gensler released its 2025 Design Forecast highlighting trends that will shape urban environments, including a focus on adaptable and human-centered spaces. This report emphasizes the need for luxury interior designs that not only cater to aesthetic preferences but also promote well-being and sustainability, aligning with evolving consumer values in China.
- In January 2025, Jacobs Engineering Group Inc. unveiled its new luxury design division in Beijing, aimed at providing bespoke interior design services for high-end commercial and residential projects. This initiative is part of Jacobs' strategy to capture the growing luxury market in China, responding to increased demand for personalized and sophisticated interior solutions.
- In January 2025, Perkins and Will announced a significant project in Guangzhou focusing on luxury hospitality design. The project aims to create a unique guest experience through innovative interior design that reflects local culture while incorporating modern luxury elements, catering to both domestic and international travelers.
- In December 2024, Stantec Inc. launched a new line of interior design services specifically targeting the luxury sector in China. This initiative includes collaborations with local artisans to create bespoke furnishings that resonate with Chinese aesthetics and craftsmanship, enhancing the appeal of high-end residential projects.
- Throughout late 2024, Hirsch Bedner Associates (HBA) has been actively involved in several high-profile hotel renovations across major Chinese cities. Their focus on creating immersive luxury experiences has positioned them as leaders in hospitality design, responding to the increasing demand for unique and culturally relevant interiors.
- In January 2025, NELSON & Associates announced a partnership with Chinese tech companies to incorporate smart home technologies into their luxury interior designs. This move aims to cater to tech-savvy affluent clients looking for integrated smart solutions within their living spaces.
- In December 2024, Walue Furniture Co. Ltd. expanded its operations by launching a new collection of customizable luxury furniture tailored for the Chinese market. This initiative reflects the growing trend of personalization among consumers seeking unique pieces that align with their individual tastes.
- In July 2024, Glodon Company Limited inaugurated its Smart Construction headquarters in Guangzhou, focusing on integrating technology into interior design processes. This facility aims to enhance efficiency and creativity in luxury interior projects by leveraging big data and AI-driven design tools.
Market Concentration and Characteristics
The China luxury interior design market exhibits a moderate level of market concentration, with a mix of global design firms and local players competing for dominance. Major international players, such as Aecom, Gensler, and Jacobs Engineering Group Inc., hold significant market share due to their vast expertise, global presence, and capacity to manage large-scale projects, particularly in high-end residential, commercial, and hospitality sectors. At the same time, local firms, including Areen Design Services Ltd. and IA Interior Architects, leverage their deep understanding of Chinese culture and consumer preferences, allowing them to cater to specific regional tastes. The market is characterized by a growing demand for customization, innovation, and sustainable design, as affluent consumers seek unique, personalized interiors that blend luxury with functionality. The trend toward integrating advanced technologies, such as smart home systems and sustainable materials, further shapes the competitive dynamics within the market, encouraging firms to differentiate through creativity and specialized offerings.
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- As the affluent population in China grows, the demand for bespoke and highly personalized interior designs will continue to rise, driven by a desire for unique and exclusive spaces.
- Tier-2 and tier-3 cities will become key growth areas, as urbanization and rising disposable incomes drive demand for luxury interior design services outside traditional metropolitan hubs.
- Sustainability will play an increasingly important role, with affluent clients seeking eco-friendly materials, energy-efficient designs, and green building certifications in their luxury interiors.
- The integration of smart home technologies, including automation systems, voice control, and AI, will become a prominent feature in luxury interior designs, catering to the tech-savvy elite.
- Designs that blend traditional Chinese elements with modern aesthetics will continue to gain popularity, offering a unique fusion of cultural heritage and contemporary luxury.
- Biophilic design, incorporating natural elements like plants and water features, will be a growing trend as consumers prioritize well-being and healthy living environments.
- Demand for luxury interior design will extend beyond residential spaces into commercial sectors, including high-end offices, retail outlets, and luxury hospitality venues.
- The boom in luxury real estate development, including villas, penthouses, and exclusive estates, will drive an increase in demand for top-tier interior design services.
- Interior design firms will increasingly partner with luxury brands to create cohesive, high-end experiences, integrating exclusive furniture, art, and decor into their designs.
- Luxury interior design will increasingly be seen as a long-term investment by clients looking for timeless elegance, with a focus on durability, quality, and lasting value over trends.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the China Luxury Interior Design Market in 2023 and 2032?
What is the projected CAGR for the China Luxury Interior Design Market?
What are the main drivers of the China Luxury Interior Design Market?
Which regions are leading the demand for luxury interior design in China?
Who are the key players in the China Luxury Interior Design Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 China Luxury Interior Design Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global China Luxury Interior Design Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (2032) (base year: USD 13,481.96 million → 2032: USD 22,253.00 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 China Luxury Interior Design Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. China Luxury Interior Design Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 China Luxury Interior Design Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 China Luxury Interior Design Market Drivers
- 3.3 China Luxury Interior Design Market Restraints & Challenges
- 3.4 China Luxury Interior Design Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 China Luxury Interior Design Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 China Luxury Interior Design Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, China Luxury Interior Design category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 China Luxury Interior Design Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. China Luxury Interior Design Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the China Luxury Interior Design market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 China Luxury Interior Design Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 China Luxury Interior Design Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 China Luxury Interior Design Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in China Luxury Interior Design (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New China Luxury Interior Design Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global China Luxury Interior Design Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & 2032)
- 7.1.2 Channel Mix Evolution (2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America China Luxury Interior Design Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe China Luxury Interior Design Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific China Luxury Interior Design Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America China Luxury Interior Design Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East China Luxury Interior Design Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa China Luxury Interior Design Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. China Luxury Interior Design Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
