
Market Overview:
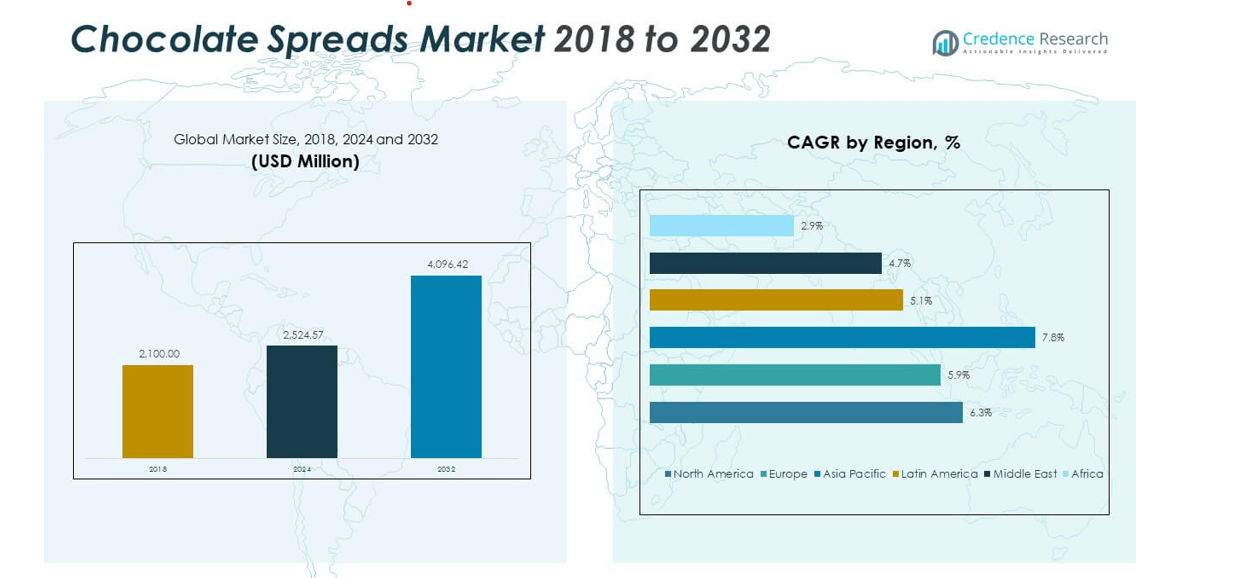
The Chocolate Spreads Market size was valued at USD 2,100.00 million in 2018 to USD 2,524.57 million in 2024 and is anticipated to reach USD 4,096.42 million by 2032, at a CAGR of 6.33% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Chocolate Spreads Market Size 2024 | USD 2,524.57 million |
| Chocolate Spreads Market, CAGR | 6.33% |
| Chocolate Spreads Market Size 2032 | USD 4,096.42 million |
Rising consumer preference for convenient, indulgent, and healthy breakfast options is driving steady market growth. Manufacturers are developing low-sugar, organic, and plant-based chocolate spreads to meet health-focused consumer needs. The demand for premium spreads made with natural ingredients and sustainable cocoa sources continues to expand. Innovations in flavor combinations, such as nut-based or protein-enriched variants, attract younger demographics. Strong promotional campaigns and the growing influence of digital media enhance brand visibility and consumer awareness globally.
Europe leads the market due to its established chocolate culture and high per capita consumption. North America follows, supported by increasing adoption of ready-to-eat breakfast and snack products. The Asia-Pacific region shows strong potential driven by urbanization, rising incomes, and Western dietary influence. Latin America and the Middle East are witnessing gradual growth, while Africa presents emerging opportunities with expanding retail networks and increasing consumer exposure to international food trends.
Market Insights:
- The Chocolate Spreads Market was valued at USD 2,100.00 million in 2018, reached USD 2,524.57 million in 2024, and is projected to attain USD 4,096.42 million by 2032, growing at a CAGR of 6.33%.
- Europe dominates with a 41.57% share due to its strong chocolate culture, premium product demand, and established retail network, while North America holds 26.05% driven by innovation and convenience-focused consumption.
- Asia-Pacific follows with a 25.69% share and is the fastest-growing region, fueled by urbanization, rising disposable income, and increasing adoption of Western breakfast trends.
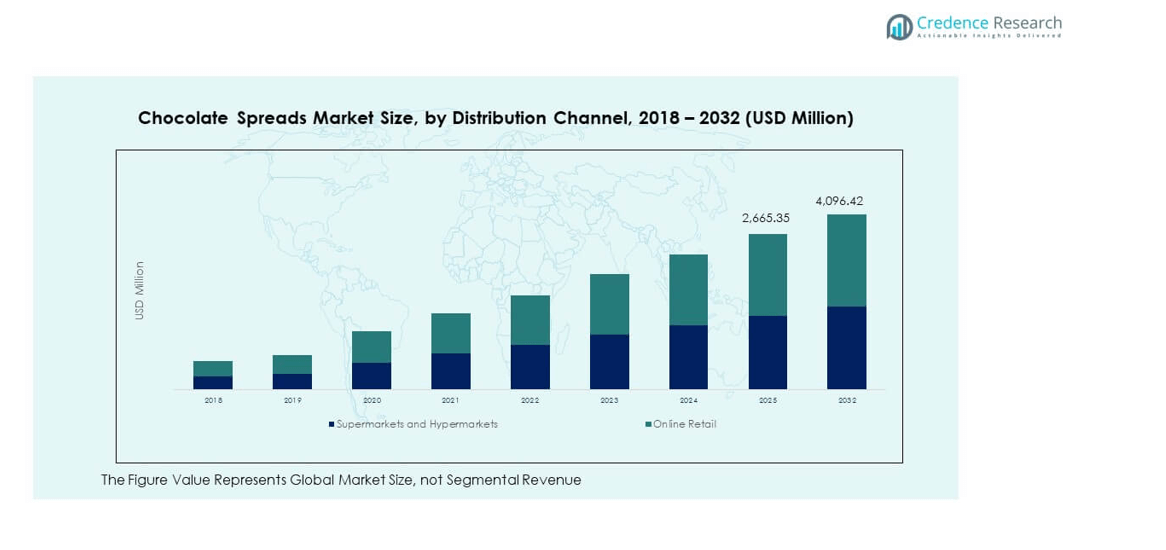
- Supermarkets and hypermarkets account for nearly 55% of total sales, supported by wider brand availability and promotional campaigns across retail chains.
- Online retail contributes roughly 45%, showing rapid expansion due to digital adoption, home delivery convenience, and broader access to emerging brands.
Market Drivers
Rising Demand for Premium and Health-Conscious Chocolate Spread Varieties
The growing preference for premium and health-oriented food products is a major factor driving market growth. Consumers are shifting toward spreads with natural ingredients, low sugar, and added nutrients. Manufacturers introduce innovative formulations with nut-based or plant-based ingredients to attract health-focused buyers. It helps address rising concerns about obesity and artificial additives. Premium packaging and organic certification further strengthen consumer trust. The availability of sugar-free and protein-enriched options supports sustained demand. The Chocolate Spreads Market benefits from evolving dietary trends that combine indulgence with nutrition.
Expanding Product Availability Through Online Retail and Specialty Stores
The rapid expansion of online platforms and specialty food outlets enhances product accessibility. E-commerce has become a critical sales channel, offering wide product variety and convenience. Retailers collaborate with digital platforms for direct consumer engagement and promotional campaigns. It supports brand visibility and repeat purchases through subscription models. Supermarkets also dedicate more shelf space to spreads with unique textures and flavors. Product sampling and influencer collaborations increase awareness among urban consumers. This widespread availability contributes to consistent market expansion and customer retention.
- For example, in 2024, Lake Champlain Chocolates expanded its online retail operations and strengthened partnerships with e-commerce platforms to improve nationwide delivery efficiency. The company emphasized direct-to-consumer growth and digital engagement to meet increasing demand for its premium chocolate and spread products.
Growing Use of Chocolate Spreads in Bakery and Dessert Applications
The growing use of chocolate spreads in bakery and dessert applications drives the market significantly. Food manufacturers and bakeries integrate spreads in pastries, donuts, and croissants for flavor enhancement. The versatility of chocolate spreads enables their use in both commercial and household settings. It also promotes product diversification across foodservice chains and quick-service restaurants. Industrial demand rises with the trend toward ready-to-eat bakery products. Companies invest in heat-resistant formulations for better shelf stability. These developments strengthen the market’s integration within the wider processed food industry.
Innovation in Flavors and Texture Profiles Attracting Younger Consumers
Innovation in flavor and texture variety plays a crucial role in attracting new consumers. Brands experiment with hazelnut, caramel, sea salt, and dark chocolate blends to suit regional tastes. The introduction of crunchy, whipped, and layered textures appeals to younger demographics. It enhances the sensory experience and encourages brand switching among buyers. Manufacturers focus on limited-edition variants and seasonal launches to maintain engagement. Such experimentation fuels competitive differentiation in the market. The Chocolate Spreads Market benefits from these dynamic flavor innovations and texture diversification efforts.
- For example, in 2024, Ferrero launched Nutella Plant-Based in select European markets, replacing milk with chickpeas and rice syrup. The product caters to vegan consumers and was certified by the Vegetarian Society, aligning with the rising demand for plant-based chocolate spreads.
Market Trends
Rising Popularity of Vegan and Plant-Based Chocolate Spreads
The global shift toward plant-based diets is influencing product development strategies. Manufacturers are focusing on dairy-free and vegan-certified chocolate spreads to attract eco-conscious consumers. Coconut, almond, and oat-based alternatives gain popularity in regions emphasizing sustainability. It supports environmental goals while catering to lactose-intolerant buyers. Retailers highlight such offerings in dedicated vegan sections, increasing visibility. The trend aligns with broader consumer values of ethical sourcing and clean labeling. This transformation strengthens the market’s presence among the growing vegan population globally.
Increasing Integration of Functional Ingredients in Chocolate Spreads
Manufacturers are integrating functional ingredients such as protein, vitamins, and probiotics into spreads. These enhancements target health-aware consumers seeking added nutritional value. The innovation aligns with fitness and wellness trends dominating the food sector. It improves product differentiation and supports premium pricing strategies. Functional spreads gain traction in both retail and foodservice channels. It also boosts consumer loyalty through perceived health benefits. The Chocolate Spreads Market experiences higher adoption due to this merging of taste and functionality.
- For instance, in September 2024, Ferrero launched Nutella Plant-Based, a vegan version of its iconic hazelnut cocoa spread. The innovation aligns with growing consumer demand for plant-based and sustainable food products, marking Ferrero’s entry into the expanding vegan chocolate spreads segment.
Growing Influence of Sustainability and Ethical Cocoa Sourcing Practices
Sustainability and ethical sourcing have become major purchasing factors among consumers. Brands adopt fair-trade certifications and traceable supply chains to ensure transparency. It builds brand reputation and consumer trust while promoting responsible farming communities. Companies invest in sustainable packaging and recyclable materials to minimize environmental impact. The trend encourages long-term supplier relationships and stable cocoa availability. Marketing campaigns emphasizing ethical sourcing attract conscious buyers. This growing awareness pushes manufacturers toward more transparent production ecosystems.
- For example, in 2023, Barry Callebaut reported continued progress under its “Forever Chocolate” sustainability program, highlighting reductions in carbon intensity and expanded traceability across its cocoa supply chain. The company also advanced digital transparency initiatives to ensure responsible sourcing and improved environmental performance.
Adoption of Smart Packaging and Digital Branding Strategies
Technological innovation in packaging and branding enhances consumer interaction. Smart packaging with QR codes offers details on ingredients, sourcing, and recipes. It enables better engagement through storytelling and brand loyalty initiatives. Digital advertising and influencer marketing amplify reach across social platforms. Companies adopt personalized campaigns based on regional consumer behavior. It helps differentiate brands in a crowded retail landscape. The Chocolate Spreads Market benefits from the integration of smart technologies and digital storytelling.
Market Challenges Analysis
Volatility in Cocoa Prices and Supply Chain Disruptions Affecting Stability
Fluctuations in global cocoa prices present significant challenges to market profitability. Cocoa supply depends heavily on climatic conditions in West African countries. It exposes producers to high operational and procurement risks. Political instability and trade restrictions further complicate sourcing. Price volatility impacts small and medium manufacturers relying on imported raw materials. Rising logistics costs also influence retail pricing and profit margins. Companies mitigate risks through long-term contracts and diversified sourcing, but unpredictability persists. The Chocolate Spreads Market faces ongoing pressure from unstable commodity markets and fragile logistics networks.
Rising Health Concerns and Regulatory Restrictions on Sugar Content
Growing public concern over high sugar intake affects product demand. Health authorities implement labeling regulations and sugar taxes to promote dietary balance. It compels manufacturers to reformulate products without compromising taste or texture. The use of alternative sweeteners increases production complexity and costs. Consumers scrutinize ingredient lists more closely, influencing purchase decisions. Stringent regional food safety standards add compliance challenges. Companies invest in R&D for clean-label and low-calorie variants to retain market share. These restrictions reshape product development strategies and distribution priorities across key regions.
Market Opportunities
Expansion into Emerging Economies and Untapped Consumer Segments
Expanding into emerging economies presents strong growth potential for manufacturers. Rising disposable income and urbanization in Asia-Pacific, Latin America, and Africa boost consumption. Localized flavor innovation caters to regional taste preferences and cultural trends. It encourages market entry through partnerships with local distributors and retailers. Smaller brands leverage online marketplaces to penetrate new demographics. Growing youth populations with evolving snacking habits further drive adoption. The Chocolate Spreads Market finds substantial room for expansion in these developing regions.
Product Diversification Through Functional, Organic, and Premium Variants
Product diversification toward organic and fortified variants creates lucrative opportunities. Health-driven consumers prefer spreads with higher cocoa content and natural ingredients. It motivates producers to introduce gluten-free and allergen-free alternatives. The focus on premium-quality offerings enhances competitiveness in developed markets. Collaboration with fitness and wellness brands increases consumer engagement. Companies explore co-branding opportunities with bakery and confectionery players. This shift toward premiumization supports steady long-term market growth across multiple retail channels.
Market Segmentation Analysis:
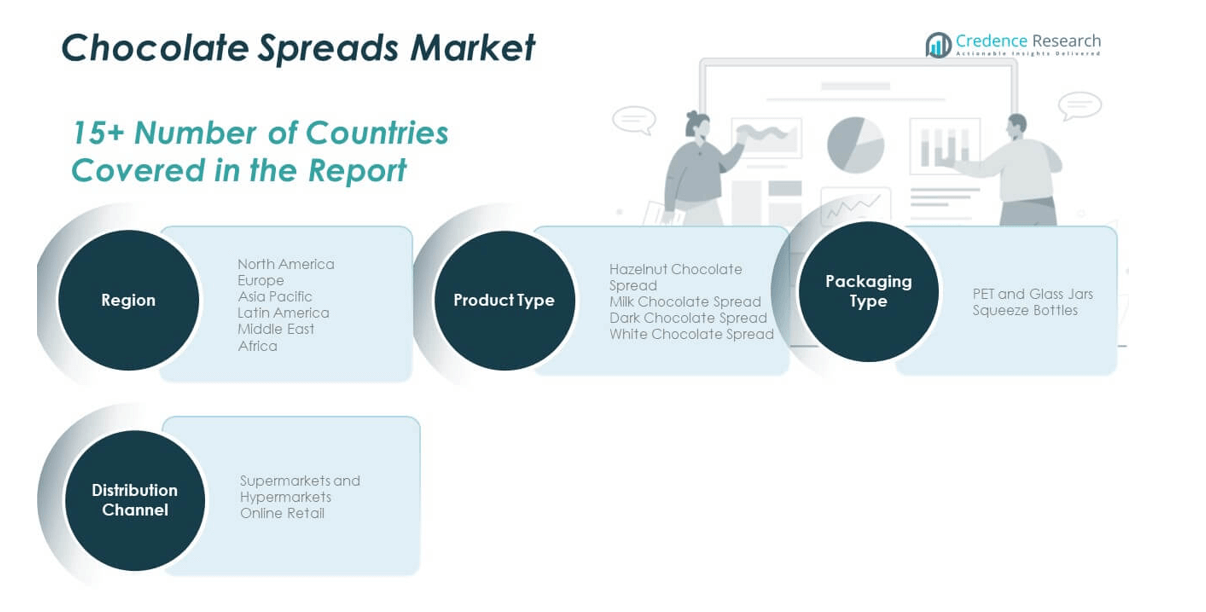
The Chocolate Spreads Market is segmented by product type, packaging type, and distribution channel, each contributing distinctly to its expansion.
By product type, hazelnut chocolate spread leads due to its rich flavor and high consumer acceptance across Europe and North America. Milk chocolate spread follows, appealing to families and younger consumers for its mild sweetness and creamy texture. Dark chocolate spread gains traction among health-conscious buyers seeking lower sugar and higher cocoa content. White chocolate spread serves a niche segment but grows through bakery and dessert applications, diversifying market reach and usage occasions.
- For example, in April 2025, Ferrero Group announced a CAD 445 million investment to expand its Brantford, Ontario facility. The project includes advanced automation upgrades and increased Nutella production capacity to support growing demand across North America.
By packaging type, PET and glass jars dominate due to their convenience, reusability, and premium presentation, which enhance shelf appeal. Squeeze bottles record steady growth, driven by their portability and user-friendly design, suitable for on-the-go consumers. Manufacturers are investing in lightweight and recyclable materials to support sustainability goals. Packaging innovation helps brands differentiate in competitive retail environments while ensuring freshness and extended shelf life. It strengthens brand visibility and consumer preference across multiple price segments.
- For example, in 2024, The Hershey Company strengthened its sustainability initiatives by enhancing recyclable packaging across its portfolio. The company reported steady progress toward reducing plastic waste and improving material efficiency as part of its environmental responsibility goals.
By distribution channel, supermarkets and hypermarkets remain the leading retail outlets, offering diverse brands and promotional discounts. Online retail experiences rapid growth due to increasing digital penetration and consumer preference for home delivery. It enables smaller brands to reach niche markets through direct-to-consumer models. Enhanced visibility through e-commerce platforms boosts brand awareness and accessibility. These distribution dynamics create a balanced mix of traditional and modern retail approaches, ensuring consistent availability and long-term market growth.
Segmentation:
By Product Type
- Hazelnut Chocolate Spread
- Milk Chocolate Spread
- Dark Chocolate Spread
- White Chocolate Spread
By Packaging Type
- PET and Glass Jars
- Squeeze Bottles
By Distribution Channel
- Supermarkets and Hypermarkets
- Online Retail
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Chocolate Spreads Market size was valued at USD 557.34 million in 2018 to USD 658.90 million in 2024 and is anticipated to reach USD 1,067.12 million by 2032, at a CAGR of 6.3% during the forecast period. North America holds a market share of 26.05%. The region benefits from high disposable income, a strong breakfast culture, and the growing popularity of ready-to-eat foods. Major brands dominate retail shelves through innovative flavor blends and nut-based variants. Consumers prefer spreads with lower sugar and clean-label ingredients, aligning with wellness trends. The U.S. leads in product launches supported by aggressive marketing and online retail penetration. Canada shows growing demand for organic chocolate spreads. Strategic tie-ups with bakery chains and cafes enhance product reach. It continues to grow as consumer awareness of premium and natural spreads expands across the region.
Europe
The Europe Chocolate Spreads Market size was valued at USD 894.60 million in 2018 to USD 1,049.65 million in 2024 and is anticipated to reach USD 1,645.75 million by 2032, at a CAGR of 5.9% during the forecast period. Europe accounts for a market share of 41.57%. The region remains the largest consumer base, supported by a long-established chocolate culture and diverse product offerings. Germany, France, and the U.K. lead in consumption driven by strong brand loyalty and premium demand. Manufacturers focus on sustainability, ethical cocoa sourcing, and recyclable packaging. European consumers favor hazelnut spreads and artisanal variants. Innovation in plant-based chocolate spreads attracts vegan consumers. Supermarkets and hypermarkets dominate distribution channels. It continues to lead due to premiumization and evolving consumer preferences for natural and ethical products.
Asia Pacific
The Asia Pacific Chocolate Spreads Market size was valued at USD 443.10 million in 2018 to USD 560.07 million in 2024 and is anticipated to reach USD 1,017.14 million by 2032, at a CAGR of 7.8% during the forecast period. The region holds a market share of 25.69%. Rising urbanization, income growth, and Western dietary influence drive strong demand. Consumers in India, China, and Japan are adopting chocolate spreads for breakfast and snacking. Local players introduce affordable and locally flavored products to expand reach. Online retail and convenience stores strengthen product accessibility. International brands invest in regional manufacturing to lower logistics costs. The rise of e-commerce platforms supports growth across Tier 2 and Tier 3 cities. It is becoming a vital growth engine with a young consumer base and rising health awareness.
Latin America
The Latin America Chocolate Spreads Market size was valued at USD 109.20 million in 2018 to USD 129.74 million in 2024 and is anticipated to reach USD 192.00 million by 2032, at a CAGR of 5.1% during the forecast period. Latin America represents a market share of 4.84%. Brazil and Argentina dominate due to strong chocolate consumption patterns and expanding retail infrastructure. Consumers prefer affordable products with localized taste preferences. Manufacturers introduce value packs and nut-based variants to attract price-sensitive buyers. Urban centers witness rising demand through supermarkets and e-commerce platforms. Marketing campaigns target younger demographics to encourage adoption. Local and international brands compete through flavor innovation and promotions. It continues to develop steadily as economic conditions and consumer awareness improve.
Middle East
The Middle East Chocolate Spreads Market size was valued at USD 67.20 million in 2018 to USD 74.71 million in 2024 and is anticipated to reach USD 106.94 million by 2032, at a CAGR of 4.7% during the forecast period. The region accounts for a market share of 2.69%. The demand is fueled by premium product imports and an expanding café culture. Gulf Cooperation Council (GCC) countries lead in consumption with strong retail growth. Product innovation focuses on halal-certified and low-sugar variants. Increasing tourism and hospitality investments create new distribution opportunities. Online channels grow rapidly through regional e-commerce platforms. Imported brands gain popularity among urban consumers. It maintains steady growth supported by youth demographics and premium lifestyle trends.
Africa
The Africa Chocolate Spreads Market size was valued at USD 28.56 million in 2018 to USD 51.51 million in 2024 and is anticipated to reach USD 67.46 million by 2032, at a CAGR of 2.9% during the forecast period. Africa holds a market share of 2.16%. Growth is moderate due to limited awareness and low per capita income in several countries. Urban markets such as South Africa and Egypt lead in consumption. Distribution expansion through modern retail outlets supports gradual adoption. Consumers increasingly prefer affordable options with long shelf life. Local production efforts reduce dependency on imports. Marketing campaigns promote the use of spreads as a convenient breakfast option. It is expected to expand gradually with improving retail access and changing dietary habits.
Key Player Analysis:
- Ferrero International S.A.
- The Hershey Company
- Nestlé S.A.
- Mondelez International, Inc.
- Mars, Incorporated
- NUTKAO S.r.l.
- Oetker India Pvt. Ltd.
- Nutiva Inc.
Competitive Analysis:
The Chocolate Spreads Market features strong competition among global and regional brands focusing on innovation, flavor diversity, and health-oriented products. Key players include Ferrero International S.A., The Hershey Company, Nestlé S.A., Mondelez International, Mars Incorporated, NUTKAO S.r.l., Dr. Oetker India Pvt. Ltd., and Nutiva Inc. These companies emphasize clean-label formulations, sustainable sourcing, and advanced packaging to strengthen brand loyalty. It benefits from ongoing investments in product differentiation, marketing campaigns, and digital distribution. Firms expand through strategic mergers, regional collaborations, and e-commerce penetration. Increasing consumer preference for vegan and low-sugar spreads drives research and product reformulation. Strong global distribution networks and innovation pipelines ensure sustained competitiveness. The market remains dynamic, driven by innovation, brand positioning, and expanding retail presence across developed and emerging economies.
Recent Developments:
- In May 2025, Ferrero International S.A. announced the launch of a new flavor variant of its flagship spread: “Nutella Peanut.” The company stated the product would combine its classic cocoa-hazelnut base with roasted peanuts, targeting the U.S. market with a planned rollout in spring 2026.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Packaging Type and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising consumer demand for natural, organic, and low-sugar spreads will drive product innovation.
- Expansion in online retail and direct-to-consumer channels will enhance global product accessibility.
- Growing popularity of plant-based and vegan chocolate spreads will reshape product portfolios.
- Regional players will focus on local flavor preferences to strengthen market penetration.
- Premium and artisanal chocolate spreads will gain traction among health-conscious consumers.
- Strategic mergers and brand collaborations will expand distribution and strengthen competitive positioning.
- Sustainable sourcing of cocoa and recyclable packaging will become key brand differentiators.
- Adoption of automation and AI in production will improve quality control and supply efficiency.
- Rising influence of social media marketing will boost brand visibility among younger demographics.
- Emerging economies in Asia-Pacific and Latin America will offer high-growth opportunities through urbanization and lifestyle changes.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Chocolate Spreads Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Chocolate Spreads Market projected to grow between 2024 and 2032?
What are the key drivers for the growth of the Chocolate Spreads market?
Which is the major packaging type segment in Chocolate Spreads Market by drugs by route of administration?
Who are the leading companies in the Chocolate Spreads Market?
Which region commanded the largest share of the Chocolate Spreads Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Chocolate Spreads Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Chocolate Spreads Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,524.57 million → 2032: USD 4,096.42 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Chocolate Spreads Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Chocolate Spreads Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Chocolate Spreads Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Chocolate Spreads Market Drivers
- 3.3 Chocolate Spreads Market Restraints & Challenges
- 3.4 Chocolate Spreads Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Chocolate Spreads Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Chocolate Spreads Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Chocolate Spreads category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Chocolate Spreads Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Chocolate Spreads Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Chocolate Spreads. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Chocolate Spreads Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Chocolate Spreads Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Chocolate Spreads Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Chocolate Spreads (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Chocolate Spreads
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Chocolate Spreads Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Chocolate Spreads Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Chocolate Spreads Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Chocolate Spreads Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Chocolate Spreads Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Chocolate Spreads Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Chocolate Spreads Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Chocolate Spreads Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
