
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
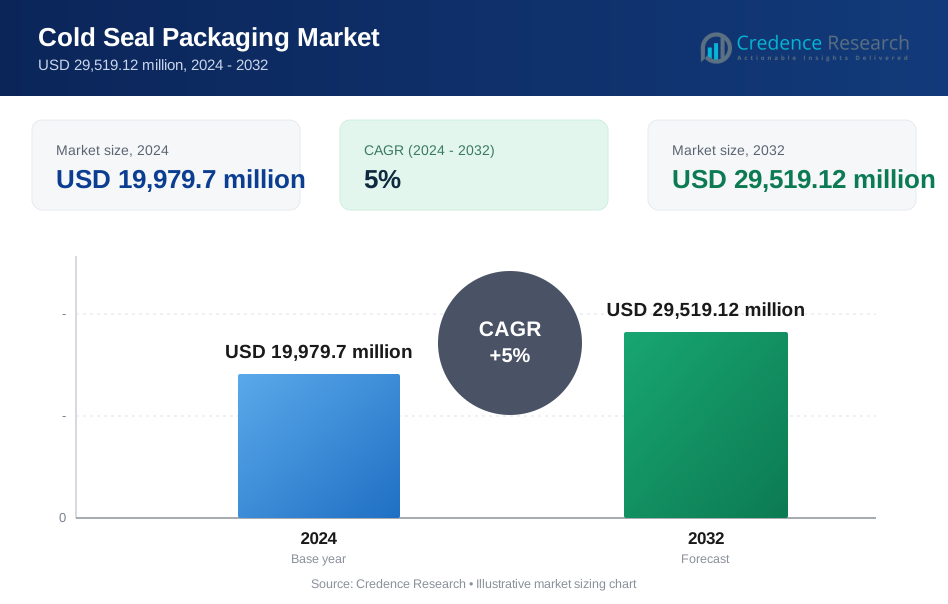
| Cold Seal Packaging Market Size 2024 | USD 19979.7 Million |
| Cold Seal Packaging Market, CAGR | 5% |
| Cold Seal Packaging Market Size 2032 | USD 29519.12 Million |
Market Overview:
The Cold Seal Packaging Market is projected to grow from USD 19979.7 million in 2024 to an estimated USD 29519.12 million by 2032, with a compound annual growth rate (CAGR) of 5% from 2024 to 2032.
The Cold Seal Packaging market is primarily driven by the increasing demand for convenience and extended shelf life in packaged goods. Consumers are seeking packaging solutions that offer ease of use, such as peelable and resealable features, which cold seal packaging effectively provides. Additionally, the growing emphasis on sustainability is pushing manufacturers to adopt cold seal packaging materials that are recyclable and reduce environmental impact. Advances in packaging technology have also contributed to market expansion by improving the functionality and aesthetics of cold seal packaging. The shift towards health-conscious and organic food products also supports the demand for cold seal packaging, as it helps maintain product freshness and integrity. Furthermore, the rise in online food delivery services and ready-to-eat meals has increased the need for secure and user-friendly packaging solutions, further propelling market growth.
Regionally, North America and Europe are leading the Cold Seal Packaging market, owing to their well-established food and beverage industries and high consumer demand for convenience packaging. In North America, particularly the United States, the market benefits from a robust food and beverage sector and a growing trend towards sustainable packaging solutions. Europe follows closely, driven by stringent environmental regulations and a strong focus on reducing packaging waste. The Asia-Pacific region is witnessing the fastest growth, fueled by rapid industrialization, urbanization, and increasing disposable incomes in countries like China and India. This region's expanding food and beverage industry and rising consumer preferences for convenient packaging are expected to drive significant market growth in the coming years. Additionally, emerging markets in Latin America and the Middle East are beginning to adopt cold seal packaging solutions, driven by growing consumer demand for packaged foods and beverages and improvements in packaging infrastructure.
Market Drivers:
Rising Demand for Convenience Packaging:
The increasing demand for convenience in the packaging industry is a major driver of the Cold Seal Packaging market. Consumers today prioritize products that offer ease of use and quick access. Cold seal packaging addresses this need by providing features such as peelable, resealable, and tamper-evident designs. These attributes enhance the convenience of handling and consuming packaged goods, particularly in sectors like food and beverage, where quick and simple access is crucial. The rise of on-the-go lifestyles and the growing popularity of ready-to-eat meals and snacks further amplify this demand. Consequently, manufacturers are investing in cold seal technology to meet consumer expectations and gain a competitive edge in the market.
Growing Emphasis on Sustainability:
Sustainability has become a key focus in the packaging industry, driving the adoption of environmentally friendly solutions. Cold seal packaging is increasingly recognized for its eco-friendly attributes, as it often involves materials that are recyclable and reduce waste. For instance, a survey conducted by ALPLA group found that 54% of younger consumers always or often base their purchasing decisions on sustainable packaging. The shift towards sustainable practices is partly influenced by stringent environmental regulations and consumer awareness about ecological issues. Companies are actively seeking packaging solutions that minimize environmental impact, and cold seal packaging fits well within these sustainability goals. By reducing the reliance on traditional adhesives and utilizing recyclable materials, cold seal packaging supports the broader industry trend towards greener and more responsible packaging options.
Advancements in Packaging Technology:
Technological advancements play a significant role in driving the Cold Seal Packaging market. Innovations in packaging technology have led to improved cold seal materials and processes, enhancing the functionality and aesthetics of packaging solutions. Developments such as high-performance sealants and advanced barrier properties have expanded the applications of cold seal packaging, making it suitable for a wider range of products. For instane, Bostik recently introduced Turbo-Seal® LOOP 1.0, the industry's first cold seal adhesive that meets BPI-certification for industrial compostable flexible packaging applications. These advancements enable manufacturers to offer packaging that not only meets practical requirements but also appeals to consumers in terms of design and functionality. The continuous evolution of technology in this field supports market growth by providing more efficient and effective packaging solutions.
Expansion of the Food and Beverage Sector:
The growth of the food and beverage sector is a critical driver for the Cold Seal Packaging market. As the industry expands globally, there is a heightened need for packaging solutions that ensure product freshness and extend shelf life. Cold seal packaging is well-suited to this requirement, offering effective protection against contamination and spoilage. The increasing popularity of packaged and convenience foods, driven by changing consumer lifestyles and preferences, contributes to the rising demand for cold seal packaging. Additionally, the growth of online food delivery services and the need for secure and user-friendly packaging solutions further support the market. As the food and beverage industry continues to evolve, the demand for innovative packaging solutions like cold seal technology is expected to grow correspondingly.
Market Trends:
Increased Focus on Eco-Friendly Materials:
One of the significant trends in the Cold Seal Packaging market is the increased focus on eco-friendly materials. As sustainability becomes a higher priority across industries, there is a growing demand for packaging solutions that align with environmental goals. Cold seal packaging is evolving to incorporate materials that are recyclable, compostable, or made from renewable resources. For instance, 60% of consumers expect compostable or recyclable packaging in the near future, according to Mondi's report. This shift is driven by both regulatory pressures and consumer preferences for greener products. Manufacturers are investing in research and development to create packaging solutions that not only perform effectively but also contribute to reducing environmental impact. This trend reflects the broader movement towards sustainable practices within the packaging industry, making eco-friendly cold seal packaging a prominent feature in market offerings.
Integration of Smart Packaging Technologies:
The integration of smart packaging technologies is another notable trend shaping the Cold Seal Packaging market. Smart packaging incorporates features such as QR codes, sensors, and RFID tags, which enhance the functionality and value of packaging. These technologies provide benefits such as improved traceability, better inventory management, and enhanced consumer engagement. For instance, QR codes can offer consumers access to additional product information, while sensors can monitor product conditions and ensure freshness. As technology continues to advance, cold seal packaging is increasingly incorporating these smart features to meet the evolving needs of both manufacturers and consumers. This trend is expected to drive innovation and expand the application scope of cold seal packaging.
Customization and Aesthetic Enhancements:
Customization and aesthetic enhancements are becoming increasingly important in the Cold Seal Packaging market. Consumers are looking for packaging that not only serves functional purposes but also appeals to their preferences in terms of design and personalization. Manufacturers are responding by offering a wide range of customizable options, including various colors, shapes, and finishes. These enhancements allow brands to differentiate their products on the shelf and create a more engaging consumer experience. For instance, Mondi Group, a global leader in packaging and paper, reported that 66% of Gen Z and 65% of Millennials rate the importance of packaging to the unboxing experience as important or very important, compared to only 46% of Boomers. Additionally, the ability to customize packaging supports brand identity and marketing strategies, making it a valuable trend for companies looking to stand out in a competitive market. As a result, the demand for aesthetically pleasing and customizable cold seal packaging solutions is on the rise.
Expansion into Emerging Markets:
The Cold Seal Packaging market is witnessing significant expansion into emerging markets, driven by increasing industrialization and changing consumer preferences. Regions such as Asia-Pacific, Latin America, and the Middle East are experiencing rapid growth in sectors like food and beverage, where the demand for innovative packaging solutions is rising. In these regions, the adoption of cold seal packaging is being accelerated by the growing middle class, urbanization, and increased disposable incomes. Manufacturers are targeting these emerging markets with tailored solutions that address local needs and preferences, contributing to the overall growth of the market. This trend highlights the global nature of the cold seal packaging industry and the opportunities for expansion in new and developing regions
Market Restraints and Challenges:
High Production Costs:
One of the primary restraints in the Cold Seal Packaging market is the high production costs associated with advanced packaging materials and technologies. The development and implementation of cold seal packaging require specialized equipment and high-quality materials, which can lead to increased production expenses. These costs can be a barrier for smaller manufacturers and businesses operating with tight budgets. Additionally, the need for continuous investment in technology upgrades to stay competitive further adds to the financial burden. The challenge of managing these high production costs can limit market entry and growth for certain players in the industry.
Limited Adhesive Compatibility:
Cold seal packaging relies on specific adhesive formulations that can limit the types of materials and products that can be effectively packaged. The compatibility of cold seal adhesives with various substrates can be a challenge, particularly when dealing with unconventional or multi-layer materials. This limitation can restrict the versatility of cold seal packaging and impact its applicability across different sectors. Manufacturers must carefully select and test adhesives to ensure they meet the required performance standards, which can complicate the packaging process and increase development time.
Environmental Concerns:
Despite the shift towards more sustainable materials, environmental concerns related to cold seal packaging persist. Some cold seal materials, particularly those that are not recyclable or compostable, can contribute to environmental waste. As sustainability becomes a central focus, there is pressure on manufacturers to address these concerns and develop more eco-friendly solutions. The challenge of balancing performance with environmental impact requires ongoing innovation and adaptation, as companies strive to meet both regulatory standards and consumer expectations for greener packaging options.
Regulatory and Compliance Issues:
Navigating regulatory and compliance issues poses another significant challenge for the Cold Seal Packaging market. Different regions and countries have varying regulations and standards for packaging materials, which can complicate the process of international distribution and market entry. Compliance with these regulations requires thorough knowledge and continuous monitoring of global standards, adding complexity to the packaging development and approval process. This regulatory landscape can impact the speed and efficiency with which new packaging solutions are brought to market.
Market Segmentation Analysis:
By Material Type
The Cold Seal Packaging market is segmented by material type into polyethylene (PE), polypropylene (PP), and other materials. Polyethylene (PE) dominates the market due to its versatility, cost-effectiveness, and excellent sealability properties. PE-based cold seal films are widely used in various applications, including food and beverage packaging, due to their ability to maintain product freshness and extend shelf life. Polypropylene (PP) is also significant, offering superior strength and resistance to heat and chemicals, making it suitable for packaging sensitive and high-value products. Other materials, including biodegradable and compostable options, are emerging in response to growing sustainability concerns, contributing to a gradual shift towards eco-friendlier packaging solutions.
By Industry Type
The Cold Seal Packaging market is categorized by industry type into food and beverage, pharmaceuticals, personal care, and other industries. The food and beverage sector is the largest segment, driven by the demand for convenient, tamper-evident, and extended shelf life packaging. Cold seal packaging is widely used for snacks, confectionery, and ready-to-eat meals. The pharmaceutical industry follows, where cold seal packaging ensures product integrity and safety by providing secure and user-friendly packaging for medications and health products. The personal care segment utilizes cold seal packaging for items such as lotions and cosmetics, requiring attractive and functional packaging solutions. Other industries, including electronics and household goods, also adopt cold seal technology for specialized applications, contributing to the market's diverse growth.
Segmentation:
By Material Type
- Polyethylene (PE),
- Polypropylene (PP),
- Other materials.
By Industry Type
- Food and beverage,
- Pharmaceuticals,
- Personal care,
- Other industries.
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a significant share of the Cold Seal Packaging market, accounting for approximately 35% of the global market. The United States is the largest contributor within this region, driven by a well-established food and beverage sector and a high demand for convenience packaging. The market in North America benefits from a robust infrastructure and technological advancements, which support the development and implementation of cold seal packaging solutions. Additionally, consumer preferences for eco-friendly and user-friendly packaging drive the demand for cold seal technology. The region's focus on sustainability and innovative packaging solutions further fuels market growth.
Europe
Europe follows closely, with a market share of around 30%. The European market is characterized by stringent environmental regulations and a strong emphasis on reducing packaging waste. The adoption of cold seal packaging in Europe is driven by these regulatory pressures and the growing consumer demand for sustainable packaging solutions. Countries such as Germany, France, and the United Kingdom are key players, with significant investments in research and development to enhance packaging technology. The European market's focus on sustainability and high-quality standards continues to drive the growth of cold seal packaging solutions.
Asia-Pacific
The Asia-Pacific region is experiencing the fastest growth in the Cold Seal Packaging market, holding a market share of approximately 25%. This growth is fueled by rapid industrialization, urbanization, and rising disposable incomes in countries such as China and India. The expanding food and beverage industry in this region, coupled with increasing consumer preferences for convenient packaging, contributes to the high demand for cold seal packaging solutions. Additionally, the region's growing emphasis on improving packaging infrastructure and adopting innovative technologies supports the market's expansion. The Asia-Pacific market is expected to continue its rapid growth trajectory as economic development progresses.
Latin America and Middle East & Africa
Latin America and the Middle East & Africa together account for the remaining 10% of the Cold Seal Packaging market. In Latin America, the market is driven by increasing consumer demand for packaged foods and beverages, alongside improvements in packaging infrastructure. Similarly, the Middle East & Africa region is witnessing growth due to rising urbanization and changing consumer lifestyles. Although these regions currently hold a smaller share of the market, ongoing developments and increasing investments in packaging solutions are expected to drive future growth. As these regions continue to evolve economically and socially, the demand for cold seal packaging is likely to rise, contributing to the global market expansion.
Key Player Analysis:
- Altea Packaging
- Amcor plc
- American Printpak
- Bags and Pouches Pte. Ltd.
- Baoshengyuan
- Bemis Company, Inc.
- Constantia Flexibles Group GmbH
- Cortec Corporation
- Coveris Holdings S.A.
- Enmalyn
- Guanzhou Heyusheng
- Huhtamäki Oyj
- Mondi Group
- Pouch Makers Canada
- ProAmpac Holdings, Inc.
- PSG
- Rizon Group
- Sealed Air Corporation
- Sonoco Products Company
- Swisspac
- Uniflex
- Watershed Packaging
- Winpak Ltd.
Competitive Analysis:
The Cold Seal Packaging market is characterized by a competitive landscape with several key players dominating the industry. Major companies such as Amcor plc, Berry Global Inc., and Sealed Air Corporation lead the market with their extensive product portfolios and advanced packaging technologies. These firms focus on innovation, investing in research and development to enhance the performance and sustainability of cold seal packaging solutions. Additionally, they leverage strategic partnerships and acquisitions to expand their market presence and capabilities. Emerging players are also entering the market, contributing to increased competition and diversity in packaging solutions. The competitive environment drives continuous improvements in technology and materials, offering a wide range of options for consumers and businesses. Companies must navigate this dynamic landscape by balancing innovation with cost-effectiveness to maintain a competitive edge and meet evolving market demands.
Recent Developments:
- In November 2023, American Packaging Corp., an established film converter, adhesive manufacturer Bostik, and PE film producer Charter Next Gen developed a polyethylene cold seal film that meets the Association of Plastic Recyclers’ protocols, qualifying it for recycling. This collaboration between APC, Bostik, and CNG marks a significant advancement in recyclable film technology. Their joint efforts highlight a strategic move to lead in promoting eco-friendly solutions within the packaging industry.
Market Concentration & Characteristics:
The Cold Seal Packaging market exhibits moderate concentration, with a few major players holding significant market share while numerous smaller firms contribute to the competitive landscape. Key players such as Amcor plc, Berry Global Inc., and Sealed Air Corporation dominate the market due to their extensive technological capabilities and broad product offerings. These companies focus on continuous innovation and operational efficiency to maintain their leadership positions. The market characteristics include a high emphasis on technological advancements and sustainability, with a growing trend towards eco-friendly and customizable packaging solutions. The industry is marked by rapid technological developments and a dynamic competitive environment, with players investing in research and development to meet evolving consumer demands. Overall, the market is characterized by a balance of established leaders and emerging innovators driving growth and diversity in packaging solutions.
Report Coverage:
The research report offers an in-depth analysis based on By Material Type, and By Industry Type. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Cold Seal Packaging market is expected to grow steadily, driven by increasing consumer demand for convenience and easy-to-use packaging solutions.
- Advancements in packaging technology will continue to enhance the functionality and efficiency of cold seal packaging.
- The shift towards sustainable and eco-friendly materials will drive innovation and adoption of more environmentally responsible cold seal solutions.
- Expansion into emerging markets, particularly in Asia-Pacific and Latin America, will contribute significantly to market growth.
- Increased focus on smart packaging technologies will lead to the integration of features like QR codes and sensors in cold seal packaging.
- Regulatory pressures for reducing packaging waste will encourage manufacturers to develop recyclable and compostable cold seal options.
- The rise in online food delivery services and ready-to-eat meals will boost demand for secure and convenient packaging solutions.
- Customization and aesthetic enhancements will become more prevalent, allowing brands to differentiate their products and engage consumers.
- Competitive dynamics will intensify as new players enter the market and existing companies expand their portfolios through mergers and acquisitions.
- Continued investment in research and development will drive innovation, addressing emerging consumer preferences and market demands.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Cold Seal Packaging market?
What drives the growth of the Cold Seal Packaging market?
Which regions are leading the Cold Seal Packaging market?
What are the main challenges faced by the Cold Seal Packaging market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Cold Seal Packaging Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Cold Seal Packaging Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 19,979.7 million → 2032: USD 29,519.12 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Cold Seal Packaging Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Cold Seal Packaging Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Cold Seal Packaging Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Cold Seal Packaging Market Drivers
- 3.3 Cold Seal Packaging Market Restraints & Challenges
- 3.4 Cold Seal Packaging Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Cold Seal Packaging Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Cold Seal Packaging Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Cold Seal Packaging category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Cold Seal Packaging Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Cold Seal Packaging Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Cold Seal Packaging market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Cold Seal Packaging Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Cold Seal Packaging Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Cold Seal Packaging Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Cold Seal Packaging (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Cold Seal Packaging Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Cold Seal Packaging Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Cold Seal Packaging Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Cold Seal Packaging Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Cold Seal Packaging Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Cold Seal Packaging Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Cold Seal Packaging Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Cold Seal Packaging Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Cold Seal Packaging Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
