
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Commercial Aircraft Parts Manufacturer Approval Market Size 2024 | USD 247.8 million |
| Commercial Aircraft Parts Manufacturer Approval Market , CAGR | 5.8% |
| Commercial Aircraft Parts Manufacturer Approval Market Size 2032 | USD 389.03 million |
Market Overview
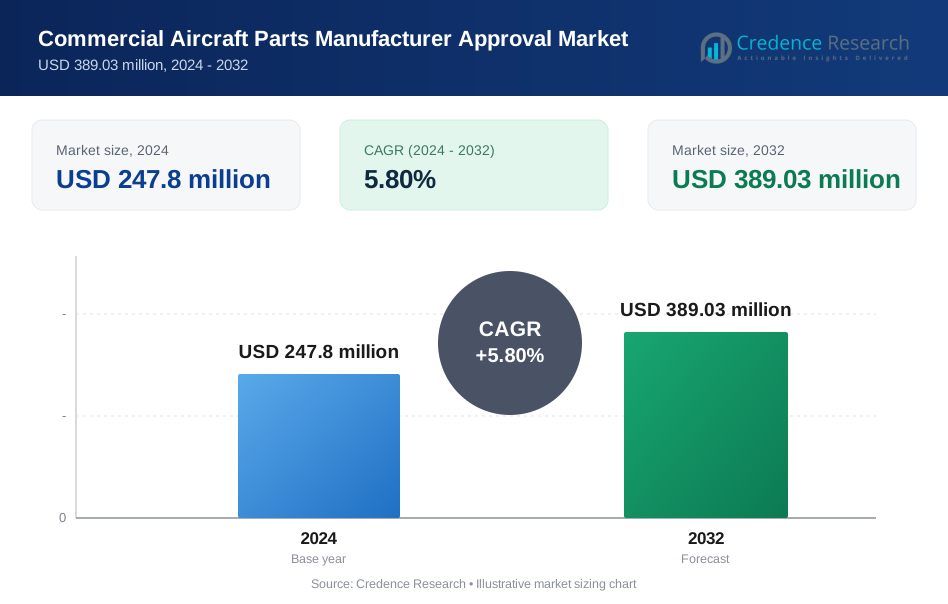
The Commercial Aircraft Parts Manufacturer Approval (PMA) market is projected to grow from USD 247.8 million in 2024 to USD 389.03 million by 2032, at a compound annual growth rate (CAGR) of 5.8%.
The growth of the Commercial Aircraft Parts Manufacturer Approval (PMA) market is primarily driven by the increasing demand for cost-effective, high-quality aircraft components and the rising need for aircraft maintenance and repair services. As airlines and aircraft operators seek to reduce operational costs, PMA parts offer a more affordable alternative to OEM parts without compromising safety or performance. Additionally, the growing trend toward sustainability and environmental responsibility in the aviation industry further fuels the adoption of PMA parts, as manufacturers focus on producing more eco-friendly solutions. Advancements in manufacturing technologies, such as 3D printing and digitalization, have also contributed to the expansion of the PMA market by enabling more efficient and precise production processes. The growing number of aircraft in service, particularly in emerging markets, and the increasing complexity of aviation regulations continue to support the demand for certified PMA parts, ensuring the market’s steady growth in the coming years.
The Commercial Aircraft Parts Manufacturer Approval (PMA) market is witnessing substantial growth across various regions. North America leads the market, holding around 40% of the share in 2024, driven by a large fleet and stringent regulatory frameworks. Europe follows with a 25% share, supported by a growing demand for MRO services and low-cost carriers. The Asia-Pacific region, expected to experience the fastest growth, holds 20% of the market, driven by rapid fleet expansion in countries like China and India. The Rest of the World, including the Middle East, Latin America, and Africa, accounts for 15%, with steady growth in air travel and MRO investments. Key players such as Able Aerospace Services Inc. (Textron Company), AMETEK, Inc., and Spirit Aerosystems Inc. are leading the charge in these regions, capitalizing on expanding opportunities and strengthening their market positions.
Market Insights
- The Commercial Aircraft Parts Manufacturer Approval (PMA) market is projected to grow from USD 247.8 million in 2024 to USD 389.03 million by 2032, at a CAGR of 5.8%.
- The market is driven by the increasing demand for cost-effective, high-quality aircraft components and a rising need for aircraft maintenance and repair services.
- Advancements in manufacturing technologies such as 3D printing and digitalization have expanded the range of PMA parts and enhanced production efficiency.
- The growth of the global aircraft fleet, especially in emerging markets, boosts the demand for PMA parts as airlines seek affordable maintenance solutions.
- North America leads the market in 2024, with a 40% share, driven by a large fleet and strong regulatory frameworks like the FAA.
- Europe holds 25% of the market share in 2024, driven by MRO demand, low-cost carriers, and increasing regional airline growth.
- The Asia-Pacific region is expected to experience the fastest growth, with a 20% share, due to the rapid expansion of the aviation industry and fleet modernization.
Market Drivers
Cost Efficiency and Competitive Advantage
One of the key drivers of the Commercial Aircraft Parts Manufacturer Approval (PMA) market is the demand for cost-effective alternatives to original equipment manufacturer (OEM) parts. Airlines and aircraft operators are increasingly under pressure to manage rising operational costs, including maintenance and repair expenses. PMA parts offer a more affordable solution without compromising quality or safety. For instance, Wencor has PMA on over 6,000 aircraft parts and produces more than 400 new PMA parts each year. The competitive pricing of PMA components makes them an attractive option for operators seeking to reduce their maintenance costs, thereby driving market growth.
Regulatory Compliance and Safety Assurance
The stringent regulatory environment governing the aviation industry ensures that all aircraft components meet high safety and quality standards. PMA parts are rigorously tested and certified by aviation regulatory authorities such as the FAA, guaranteeing that they meet or exceed these safety requirements. For instance, Chromalloy received FAA approval in November 2024 for its CFM56-5B/7B High-Pressure Turbine (HPT) Stage 1 Vane, expanding its portfolio of FAA-approved components for commercial aerospace engines. This regulatory approval instills confidence in operators, further driving the demand for certified PMA components. As a result, PMA parts continue to gain acceptance in the market, especially for replacement parts in older aircraft models that are no longer supported by OEMs.
Technological Advancements in Manufacturing
Advancements in manufacturing technologies, such as 3D printing, additive manufacturing, and precision engineering, have significantly enhanced the production of PMA parts. These technologies enable manufacturers to produce complex components with greater precision, reduced lead times, and lower production costs. The adoption of these innovations has expanded the range of PMA parts available in the market, attracting more customers and stimulating growth in the sector. Additionally, these advancements contribute to the development of more sustainable and environmentally friendly components, in line with the aviation industry's sustainability goals.
Growth in Global Aircraft Fleet and MRO Demand
The increasing number of aircraft in service worldwide, especially in emerging markets, is a major driver of the PMA market. With a growing global fleet, the demand for maintenance, repair, and overhaul (MRO) services has risen, creating a need for reliable and cost-efficient replacement parts. PMA parts are well-positioned to meet this demand, particularly as airlines look for affordable solutions to maintain aging aircraft. The continuous expansion of the global aviation industry ensures sustained demand for PMA components, providing long-term market growth potential.
Market Trends
Sustainability and Environmental Responsibility
A growing trend in the Commercial Aircraft Parts Manufacturer Approval (PMA) market is the increased emphasis on sustainability and environmental responsibility. With the aviation industry focusing on reducing its carbon footprint, PMA manufacturers are aligning their operations with eco-friendly practices. For instance, Lufthansa Technik developed the 'Cyclean' aircraft engine wash system that injects vaporized hot water directly into the core engine, effectively removing combustion residues and contaminants. This includes the development of components made from sustainable materials, as well as the use of energy-efficient production processes. As airlines and aircraft operators are also prioritizing greener solutions, demand for PMA parts that contribute to sustainability continues to rise.
Digitalization and Advanced Manufacturing Techniques
The integration of digital technologies and advanced manufacturing techniques is a significant trend shaping the PMA market. Digitalization, including the use of data analytics and computer-aided design (CAD), enables manufacturers to streamline production processes, optimize supply chains, and improve component quality. Additionally, technologies like 3D printing and additive manufacturing are revolutionizing the production of complex parts, enabling more customized solutions and reducing production costs. These innovations are driving the increased adoption of PMA parts, particularly in the repair and replacement of specific components.
Focus on Aftermarket Services and Global MRO Network Expansion
The increasing demand for aftermarket services and the expansion of global Maintenance, Repair, and Overhaul (MRO) networks are further fueling the growth of the PMA market. Airlines and operators are seeking more cost-efficient alternatives for maintaining their fleets, which has led to a rise in the use of PMA parts for replacements and repairs. For instance, Pratt & Whitney is increasing the capacity of its Singapore engine center, Eagle Services Asia (ESA), by expanding its facilities to 48,000 sq. ft, which will increase its capabilities by two-thirds of its current capacity. Additionally, the expansion of MRO facilities, particularly in emerging markets, is improving access to PMA parts and services, thereby strengthening the overall market demand.
Enhanced Customization and Product Innovation
Customization is becoming a critical trend in the PMA market, as manufacturers focus on delivering tailored solutions for various aircraft types and specific operational requirements. This trend is supported by innovations in material science and manufacturing capabilities, allowing for more specialized and optimized components. The ability to offer customized PMA parts that meet the unique needs of aircraft operators is becoming increasingly important, as it ensures improved performance, reduced downtime, and greater operational efficiency.
Market Challenges Analysis
Stringent Regulatory and Certification Processes
One of the major challenges faced by the Commercial Aircraft Parts Manufacturer Approval (PMA) market is the complex and stringent regulatory environment. Obtaining approval from aviation authorities such as the Federal Aviation Administration (FAA) or European Union Aviation Safety Agency (EASA) requires manufacturers to meet rigorous standards of quality and safety. The lengthy and costly process of obtaining certification for PMA parts can be a significant barrier to entry for smaller manufacturers. Additionally, the regulatory landscape is continuously evolving, which means companies must stay up to date with new regulations and compliance requirements. This presents a challenge in terms of both time and resources, especially for manufacturers seeking to introduce new PMA parts or expand into new markets. Any delays or missteps in the certification process can lead to financial setbacks and regulatory issues, slowing down the growth of the market. Furthermore, international certification requirements can vary, making it difficult for manufacturers to access global markets.
Competition from OEM and Counterfeit Parts
Another significant challenge in the PMA market is the competition from Original Equipment Manufacturer (OEM) parts, which are often seen as the industry standard due to their direct association with aircraft manufacturers. Despite the cost advantages of PMA parts, some aircraft operators remain hesitant to adopt them because of perceived concerns regarding quality and reliability. This is further exacerbated by the rising threat of counterfeit parts entering the market, which undermine confidence in PMA products. While regulatory bodies actively work to combat counterfeiting, the presence of counterfeit parts poses a risk to both safety and brand reputation. Consequently, PMA manufacturers must continuously invest in quality control measures and certifications to differentiate their products from counterfeit alternatives, ensuring their parts are seen as trustworthy and reliable. For instance, McFarlane Aviation, in March 2024, acquired PMA Products Inc., expanding its portfolio to include hundreds of FAA-approved parts for aircraft like Piper, Beechcraft, and Cessna, including landing gear bolts, fuel system caps, and engine parts. This ongoing competition challenges the growth potential of the PMA market and requires manufacturers to emphasize safety, regulatory compliance, and transparency in their operations, as well as strengthen consumer trust.
Market Opportunities
The Commercial Aircraft Parts Manufacturer Approval (PMA) market presents significant opportunities driven by the growing global fleet of aircraft and the increasing demand for cost-effective maintenance and repair solutions. As airlines and operators strive to reduce operating costs, PMA parts offer an attractive alternative to Original Equipment Manufacturer (OEM) components due to their lower price points without compromising on safety and performance. This trend is especially evident in the aftermarket segment, where airlines are looking to maintain older aircraft models that may no longer be supported by OEMs. With the expansion of the global aircraft fleet, particularly in emerging economies, the need for reliable and cost-efficient PMA parts is expected to rise, providing substantial growth potential for manufacturers that can meet evolving market demands.
Another key opportunity lies in the increasing focus on sustainability within the aviation industry. As environmental concerns gain prominence, aircraft operators and manufacturers are placing greater emphasis on reducing carbon emissions and adopting greener technologies. PMA manufacturers are responding by developing more eco-friendly components, including lightweight materials and energy-efficient parts. Additionally, advances in manufacturing techniques such as 3D printing and additive manufacturing present opportunities for producing customized, high-performance PMA parts with shorter lead times and lower costs. These technological innovations not only support sustainability but also enhance the efficiency and precision of PMA production. The growing emphasis on sustainability, combined with the demand for cost-effective alternatives, positions the PMA market for continued expansion and innovation in the coming years.
Market Segmentation Analysis:
By Type
The Commercial Aircraft Parts Manufacturer Approval (PMA) market is segmented by type, with key categories including engine components, landing gear, airframe parts, and electrical systems. Engine components hold the largest share due to their critical role in aircraft performance and maintenance. PMA parts for engines provide a cost-effective solution for operators seeking alternatives to OEM parts. As aircraft technology advances, the demand for PMA parts in other categories, such as landing gear and electrical systems, is also expanding, providing growth opportunities across various types of components.
By Application
The application segment of the PMA market includes commercial aviation, military aviation, and others. The commercial aviation sector dominates the market, driven by the growing global fleet of aircraft and the increasing demand for affordable maintenance solutions. As airlines and operators seek to optimize operational costs, PMA parts are increasingly favored for their cost-efficiency in both routine maintenance and repair. Additionally, the military aviation sector is expanding its use of PMA components, particularly for older aircraft models requiring specialized parts.
Segments:
Based on Type
- Engines and Propellers
- Small Airplanes
- Other
Based on Application
- Small widebody
- Medium widebody
- Large widebody
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
In 2024, North America is expected to hold the largest share of the Commercial Aircraft Parts Manufacturer Approval (PMA) market, accounting for 40% of the global market. The region's dominance is driven by the high number of commercial and military aircraft in service, particularly in the United States, which has one of the largest fleets globally. The demand for cost-effective and high-quality maintenance, repair, and overhaul (MRO) solutions fuels the adoption of PMA parts in North America. The strong regulatory framework, led by the Federal Aviation Administration (FAA), further supports the growth of PMA components, ensuring their acceptance across both commercial and military aviation sectors. The region also benefits from a well-established network of PMA manufacturers, with leading companies focusing on innovation and the development of sustainable components.
Europe
Europe holds a significant share of the PMA market, accounting for 25% in 2024. The region's growth is attributed to the large fleet of commercial and cargo aircraft operating across European countries, as well as the increasing demand for MRO services. The European Union Aviation Safety Agency (EASA) plays a key role in certifying PMA parts for the European market, fostering confidence in their quality and safety. The growth of low-cost carriers and the expansion of regional airlines further drive the demand for affordable PMA components. Additionally, Europe is witnessing advancements in digital manufacturing and sustainable aviation technologies, which are contributing to the growing adoption of PMA parts across various aircraft applications.
Asia-Pacific
The Asia-Pacific region is expected to experience the fastest growth in the PMA market, with a projected market share of 20% in 2024. The rapid expansion of the aviation industry in countries such as China, India, and Japan, coupled with the increasing number of aircraft in service, creates substantial demand for cost-efficient MRO solutions. The rising middle class and growing air travel in the region contribute to the rapid fleet expansion, further driving the need for PMA parts. Additionally, the region's focus on modernizing aging fleets and improving maintenance capabilities offers significant opportunities for PMA manufacturers to expand their presence. As regulatory frameworks in the region continue to evolve, the acceptance of PMA parts is expected to increase.
Rest of the World
The rest of the world, including regions such as the Middle East, Africa, and Latin America, accounts for 15% of the global PMA market in 2024. These regions are experiencing steady growth in air travel and fleet expansion, particularly in the Middle East, where major airlines such as Emirates and Qatar Airways continue to expand their fleets. As these regions invest in upgrading their MRO infrastructure, the demand for PMA parts is also expected to rise. Furthermore, Latin America and Africa are gradually adopting PMA components as a cost-effective solution for fleet maintenance, driving steady growth in these regions.
Key Player Analysis
- Spirit Aerosystems Inc.
- AMETEK, Inc.
- Aerospace LLC
- Aeroflot
- Airforms Inc. (McFarlane Aviation LLC)
- Pma Aeroparts LLC
- HEICO Corporation
- Fluid Components International LLC
- Wencor Group LLC
- Able Aerospace Services Inc. (Textron Company)
- Aero Brake & Spares Inc.
- Adpma LLC
Competitive Analysis
The Commercial Aircraft Parts Manufacturer Approval (PMA) market is highly competitive, with leading players such as Able Aerospace Services Inc. (Textron Company), Adpma LLC, Aeroflot, Aero Brake & Spares Inc., Aerospace LLC, Airforms Inc. (McFarlane Aviation LLC), AMETEK, Inc., Fluid Components International LLC, HEICO Corporation, Pma Aeroparts LLC, Spirit Aerosystems Inc., and Wencor Group LLC. These companies are focusing on expanding their product portfolios and strengthening their market presence through innovations in manufacturing, quality control, and regulatory compliance. For instance, manufacturers are investing heavily in sustainable technologies and advanced manufacturing processes like 3D printing and additive manufacturing to improve the efficiency and customization of PMA parts. Additionally, partnerships and collaborations with airlines and MRO service providers are key strategies to enhance market penetration. The market also witnesses increasing competition from OEM parts, prompting PMA manufacturers to emphasize reliability, cost-effectiveness, and safety standards. With the growing demand for affordable and high-quality components, these players are positioning themselves to capitalize on emerging opportunities in both mature and developing markets.
Recent Developments
- In December 2024, Aero Dienst GmbH, a German aviation firm, teamed up with India-based AeroSource International to strengthen its footprint in India’s booming business aviation sector and the broader APAC region. This strategic collaboration aims to offer a wide range of MRO services by combining Aero Dienst’s technical proficiency with AeroSource’s regulatory knowledge and corporate network, providing Indian corporates with comprehensive, end-to-end solutions.
- In January 2024, GMR Aero Technic (GAT) announced partnerships with Lufthansa Technik AG. The collaboration with Lufthansa brings Cyclean®, an eco-friendly engine cleaning system, to Indian airports.
- In March 2024, McFarlane Aviation revealed its acquisition of PMA Products, Inc., a company specializing in the manufacture of PT6 turboshaft engines and FAA-approved parts for various aircraft models, including Piper, Beechcraft, and Cessna.
Market Concentration & Characteristics
The Commercial Aircraft Parts Manufacturer Approval (PMA) market is characterized by moderate to high market concentration, with a few key players holding significant market shares. Leading companies such as Able Aerospace Services Inc. (Textron Company), AMETEK, Inc., and Spirit Aerosystems Inc. dominate the market, leveraging their extensive experience, technological advancements, and strong relationships with airlines and MRO service providers. However, the market also features a diverse range of small and medium-sized manufacturers, especially in emerging markets, which offer cost-effective alternatives to original equipment manufacturer (OEM) parts. These manufacturers focus on specific niches within the market, such as engine components or landing gear, and often benefit from lower production costs and regional expertise. As the demand for PMA parts increases, especially in the aftermarket and fleet maintenance sectors, competition among both large and smaller players continues to intensify, fostering innovation and driving market growth.
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for cost-effective, high-quality aircraft components will continue to drive the growth of the PMA market.
- Airlines will increasingly adopt PMA parts to reduce operational costs while maintaining safety and performance.
- Advancements in manufacturing technologies, such as 3D printing and digitalization, will enhance the production of PMA parts.
- Sustainable aviation practices will push PMA manufacturers to develop more eco-friendly components.
- The growing number of aircraft in service, particularly in emerging markets, will create a sustained need for PMA parts.
- Regulatory bodies will maintain stringent standards, ensuring PMA parts meet or exceed safety requirements.
- As fleet modernization continues, the demand for PMA parts in the maintenance, repair, and overhaul sector will grow.
- Market players will increasingly focus on innovation and quality to differentiate themselves from competitors.
- The expansion of low-cost carriers and regional airlines will boost the adoption of PMA parts globally.
- The evolving regulatory environment will encourage manufacturers to adapt quickly and meet new compliance requirements.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Commercial Aircraft Parts Manufacturer Approval (PMA) Market?
What factors are driving the growth of the Commercial Aircraft Parts Manufacturer Approval (PMA) Market?
What are the key segments within the Commercial Aircraft Parts Manufacturer Approval (PMA) Market?
Who are the major players in the Commercial Aircraft Parts Manufacturer Approval (PMA) Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Commercial Aircraft Parts Manufacturer Approval Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Commercial Aircraft Parts Manufacturer Approval Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 247.8 million → 2032: USD 389.03 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Commercial Aircraft Parts Manufacturer Approval Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Commercial Aircraft Parts Manufacturer Approval Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Commercial Aircraft Parts Manufacturer Approval Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Commercial Aircraft Parts Manufacturer Approval Market Drivers
- 3.3 Commercial Aircraft Parts Manufacturer Approval Market Restraints & Challenges
- 3.4 Commercial Aircraft Parts Manufacturer Approval Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Commercial Aircraft Parts Manufacturer Approval Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Commercial Aircraft Parts Manufacturer Approval Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Commercial Aircraft Parts Manufacturer Approval category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Commercial Aircraft Parts Manufacturer Approval Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Commercial Aircraft Parts Manufacturer Approval Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Commercial Aircraft Parts Manufacturer Approval. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Commercial Aircraft Parts Manufacturer Approval Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Commercial Aircraft Parts Manufacturer Approval Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Commercial Aircraft Parts Manufacturer Approval Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Commercial Aircraft Parts Manufacturer Approval (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Commercial Aircraft Parts Manufacturer Approval
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Commercial Aircraft Parts Manufacturer Approval Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Commercial Aircraft Parts Manufacturer Approval Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Commercial Aircraft Parts Manufacturer Approval Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Commercial Aircraft Parts Manufacturer Approval Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Commercial Aircraft Parts Manufacturer Approval Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Commercial Aircraft Parts Manufacturer Approval Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Commercial Aircraft Parts Manufacturer Approval Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Commercial Aircraft Parts Manufacturer Approval Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
