
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Companion Animal Specialty Drugs Market Size 2024 | USD 56831.06 Million |
| Companion Animal Specialty Drugs Market, CAGR | 4.41% |
| Companion Animal Specialty Drugs Market Size 2032 | USD 80264.31 Million |
Market Overview:
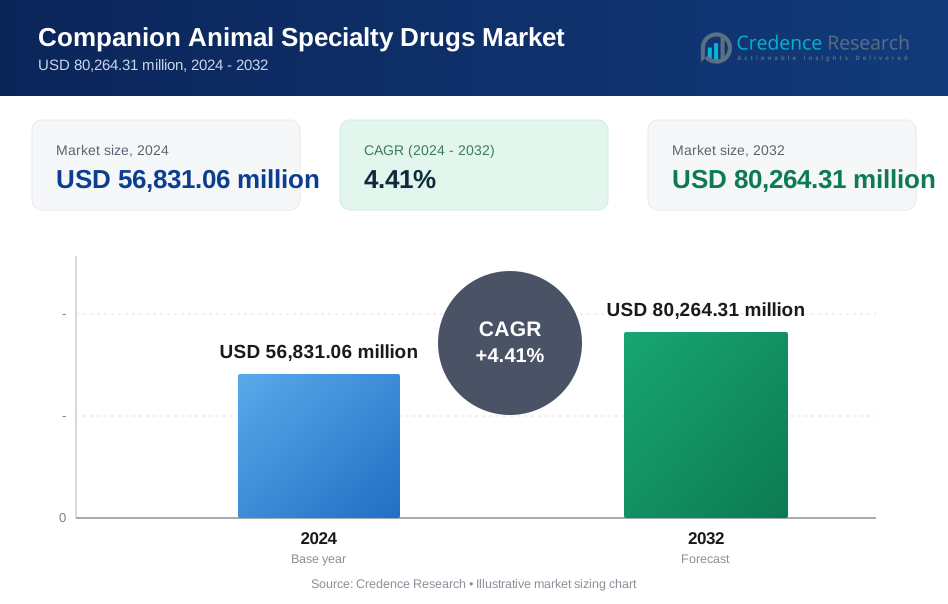
The Companion Animal Specialty Drugs Market is projected to grow from USD 56831.06 million in 2024 to an estimated USD 80264.31 million by 2032, with a compound annual growth rate (CAGR) of 4.41% from 2024 to 2032.
Key drivers of the companion animal specialty drugs market include the growing trend of pet humanization and increasing expenditure on veterinary care. Owners increasingly view their pets as family members, leading to higher demand for innovative treatments. The rise in the prevalence of chronic conditions such as arthritis, diabetes, and obesity among pets has further boosted the need for specialty drugs. Additionally, advancements in veterinary pharmaceuticals, including monoclonal antibodies and targeted therapies, have broadened treatment options for conditions like cancer and autoimmune diseases. Increasing awareness campaigns and government support for animal health are also driving market expansion. The growing number of pet insurance policies that cover specialty treatments enhances affordability, encouraging adoption of advanced therapeutics.
The market exhibits regional variation, with North America holding the largest share due to its well-established veterinary healthcare infrastructure, high pet ownership rates, and increasing adoption of premium pet care products. Europe follows closely, driven by rising awareness of animal welfare and regulatory support for innovative drugs. Asia-Pacific is emerging as a high-growth region, fueled by increasing pet adoption rates in countries like China, India, and Japan, along with growing disposable incomes. Latin America and the Middle East & Africa are expected to show steady growth, supported by expanding veterinary care access and increasing pet health awareness. This regional diversity underscores the global opportunities within the companion animal specialty drugs market.
Market Insights:
- The market is expected to grow from USD 56,831.06 million in 2024 to USD 80,264.31 million by 2032, at a CAGR of 4.41%, reflecting rising demand for innovative veterinary treatments.
- The increasing trend of pet humanization is driving demand for specialized drugs targeting chronic conditions like arthritis, diabetes, and cancer in pets.
- Technological advancements, including monoclonal antibodies and gene therapies, are transforming treatment options for complex diseases in companion animals.
- North America leads the market with a 40% share, supported by high pet ownership rates, robust veterinary infrastructure, and over 4.4 million insured pets in 2022.
- Europe holds a 30% market share, driven by strong animal welfare regulations, growing insurance penetration, and advancements in veterinary R&D.
- The Asia-Pacific region, capturing 20% of the market, is experiencing rapid growth due to rising pet adoption rates, with China alone housing over 99 million pets and a $34 billion pet care market in 2022.
- Emerging regions like Latin America and the Middle East & Africa show steady growth, with Brazil's 55 million pet dogs and expanding veterinary infrastructure in countries like South Africa and the UAE supporting demand.
Market Drivers:
Growing Trend of Pet Humanization
The increasing trend of pet humanization is a key driver for the companion animal specialty drugs market. Pets are increasingly regarded as family members, leading to heightened awareness and willingness among owners to invest in advanced healthcare solutions. For instance, according to the American Pet Products Association (APPA), Americans spent over $150.6 billion on their pets in 2024. This shift has driven demand for specialized treatments, including drugs tailored to chronic conditions such as arthritis, obesity, and diabetes in pets. The rising availability of premium pet care products and services underscores the growing commitment of pet owners to enhance the quality of life for their companions, further fueling market growth.
Rise in Chronic and Lifestyle-Related Conditions
The prevalence of chronic and lifestyle-related conditions in pets has surged, mirroring trends seen in human health. Diseases such as cancer, cardiovascular conditions, and obesity are becoming more common in companion animals, necessitating targeted therapies and innovative treatment options. For example, Banfield Pet Hospital's State of Pet Health Report found that overweight and obesity increased by 37% in dogs and 90% in cats since 2007. Advances in veterinary pharmaceuticals, including monoclonal antibodies, chemotherapeutics, and immune modulators, are addressing these conditions with higher efficacy. Additionally, the rising awareness of preventative healthcare and the importance of early diagnosis have encouraged the adoption of specialty drugs to manage and treat these conditions effectively.
Advancements in Veterinary Pharmaceuticals
Technological advancements in veterinary pharmaceuticals are significantly driving the market for companion animal specialty drugs. Innovations such as sustained-release formulations, biologics, and gene therapies have expanded the range of treatment options available to veterinarians and pet owners. For instance, Zoetis introduced Cytopoint®, a monoclonal antibody therapy for canine atopic dermatitis, which provides relief for 4 to 8 weeks with a single injection. These advancements enable precise targeting of diseases, improve drug efficacy, and reduce side effects, enhancing the overall treatment experience for pets. Furthermore, the integration of diagnostics and therapeutics has streamlined the development of personalized medicine for animals, ensuring better outcomes for a wide array of health issues.
Increasing Access to Veterinary Care and Insurance
The growing accessibility of veterinary care and the rise in pet insurance coverage have also contributed to the demand for specialty drugs. As veterinary clinics and hospitals expand their capabilities, more pet owners can access advanced diagnostic tools and specialized treatments. Simultaneously, the increasing availability of pet insurance policies that cover costly specialty drugs and treatments has improved affordability for pet owners, encouraging them to pursue comprehensive care. For instance, according to the North American Pet Health Insurance Association (NAPHIA), the total number of pets insured in the U.S. at the end of 2023 was nearly 5.7 million, which represents a 17% increase over 2022. This shift has driven demand for specialized treatments, including drugs tailored to chronic These developments have collectively strengthened the adoption of companion animal specialty drugs, making them a vital component of modern veterinary practice.
Market Trends:
Rising Adoption of Targeted Therapies
One of the significant trends in the companion animal specialty drugs market is the increasing adoption of targeted therapies, such as monoclonal antibodies and small molecule inhibitors. These therapies offer precision treatment for complex conditions, including cancer, autoimmune disorders, and dermatological issues in pets. For instance, Elanco Animal Health introduced Galliprant®, a targeted therapy for canine osteoarthritis, which specifically blocks the EP4 receptor to reduce pain and inflammation without the side effects commonly associated with NSAIDs. Their ability to target specific pathways or disease mechanisms has made them a preferred choice among veterinarians and pet owners. Companies are investing heavily in R&D to develop these advanced drugs, reflecting a shift toward personalized veterinary medicine. The success of such therapies highlights the market's focus on improving outcomes and minimizing side effects.
Growing Demand for Preventative Care
Preventative care is becoming a cornerstone of veterinary healthcare, driving the adoption of specialty drugs designed to mitigate the onset of chronic conditions. Vaccines, anti-parasitic medications, and nutraceuticals are witnessing growing demand as pet owners prioritize proactive health measures. For example, Boehringer Ingelheim's NexGard® Spectra, a broad-spectrum parasiticide, protects against fleas, ticks, heartworm, and intestinal worms, demonstrating the growing demand for comprehensive preventative care. This trend is further supported by increasing awareness campaigns about the benefits of preventative healthcare for pets. Pharmaceutical companies are responding by expanding their portfolios with drugs that not only treat illnesses but also enhance overall health and well-being, aligning with the shift toward holistic animal care.
Digital Integration and Telemedicine Expansion
The integration of digital tools in veterinary practice is transforming how specialty drugs are prescribed and delivered. Telemedicine platforms are enabling veterinarians to remotely diagnose and manage conditions, expanding access to specialty care for pet owners in underserved areas. For instance, VetNOW has developed a comprehensive telemedicine platform that allows veterinarians to conduct virtual consultations, prescribe medications, and monitor patient progress remotely. These platforms often facilitate the online distribution of prescription medications, streamlining access to specialty drugs. Additionally, data analytics and digital health records are aiding veterinarians in tracking treatment efficacy and optimizing therapeutic strategies, further reinforcing the role of technology in advancing companion animal healthcare.
Increasing Focus on Rare and Underserved Conditions
Another emerging trend is the growing attention toward addressing rare and underserved conditions in companion animals. Diseases that were previously overlooked due to limited research are now being targeted through specialized drug development. For example, Morris Animal Foundation has funded research into feline infectious peritonitis (FIP), a previously untreatable disease, leading to the development of new therapeutic approaches. Pharmaceutical companies are collaborating with veterinary researchers to identify unmet needs and create therapies for conditions such as feline infectious peritonitis (FIP) or certain genetic disorders in specific breeds. This focus on rare conditions is broadening the scope of the market and paving the way for innovative solutions in veterinary medicine.
Market Challenges Analysis:
High Development Costs and Regulatory Hurdles
The development of companion animal specialty drugs involves significant financial and time investments, posing a major challenge for manufacturers. Research and development costs are elevated due to the need for extensive clinical trials to ensure drug safety and efficacy. Regulatory approvals, often modeled after stringent human pharmaceutical standards, further increase costs and lengthen time-to-market. These factors can deter smaller players from entering the market, limiting innovation and competition.
Limited Awareness in Emerging Markets
In many emerging regions, the market faces challenges from limited awareness about advanced veterinary care and specialty drugs. Pet owners in these areas often rely on traditional treatments or over-the-counter medications, reducing the demand for specialty pharmaceuticals. Additionally, a lack of infrastructure for advanced veterinary care and a shortage of trained veterinarians in rural and semi-urban areas restricts the adoption of specialized treatments. Bridging this knowledge and infrastructure gap is critical to unlocking the market's potential in these regions.
Affordability and Access Barriers
Specialty drugs for companion animals are often expensive, making them inaccessible for a significant portion of pet owners, particularly in cost-sensitive markets. While pet insurance can mitigate some of these expenses, its penetration remains low in several regions. High treatment costs combined with limited insurance coverage can lead to lower adoption rates, hindering market growth.
Complexity of Personalized Treatments
The rising demand for personalized veterinary medicine presents its own set of challenges. Developing targeted therapies tailored to specific breeds, species, or conditions requires a deep understanding of animal genetics and disease mechanisms, as well as advanced manufacturing capabilities. This complexity adds to the financial and operational burden for pharmaceutical companies, making the widespread availability of such treatments a long-term challenge.
Market Opportunities:
The Companion Animal Specialty Drugs Market presents significant growth opportunities fueled by the increasing trend of pet humanization and rising awareness of advanced veterinary care. As pet owners increasingly view their animals as family members, demand for innovative drugs addressing chronic and complex conditions is surging. The growing prevalence of diseases such as cancer, arthritis, and diabetes in companion animals underscores the need for targeted therapies and biologics. Pharmaceutical companies can capitalize on this by expanding their portfolios to include monoclonal antibodies, gene therapies, and other cutting-edge solutions tailored to veterinary needs. The increasing availability of pet insurance, which often covers high-cost specialty treatments, further supports the market’s potential by enhancing affordability for pet owners.
Emerging markets such as Asia-Pacific, Latin America, and the Middle East & Africa offer untapped opportunities due to rising pet adoption rates and improving veterinary healthcare infrastructure. As disposable incomes grow and awareness of pet health increases in these regions, the demand for specialized treatments is expected to rise. Companies investing in regional manufacturing facilities and distribution networks can gain a competitive edge by addressing local needs efficiently. Additionally, advancements in telemedicine and digital health platforms offer opportunities to enhance accessibility to specialty drugs in underserved areas. By leveraging these trends and expanding into developing markets, the industry can sustain growth and improve the quality of life for companion animals globally.
Market Segmentation Analysis:
The Companion Animal Specialty Drugs Market is segmented by product and distribution channel, each catering to specific health needs and market dynamics in the animal healthcare sector.
By Product, the market encompasses a diverse range of offerings, including antibiotics, anti-inflammatory drugs, parasiticides, heartworm treatments, behavioral products, nutritional products, anti-obesity drugs, skin care products, and vaccines. Among these, parasiticides and vaccines dominate due to the high prevalence of parasitic infections and the growing emphasis on preventive healthcare for pets. Nutritional products and anti-obesity drugs are experiencing notable growth, driven by increased awareness among pet owners regarding pet nutrition and weight management. Additionally, skin care products are gaining traction due to rising cases of dermatological issues in companion animals.
By Distribution Channel, the market is segmented into modern trade, online distribution, neighborhood stores, and other retail formats. Modern trade, including veterinary clinics and specialty pet stores, holds a significant share, as pet owners often prefer expert guidance when purchasing specialty drugs. Online distribution is witnessing rapid growth, fueled by the convenience of home delivery and competitive pricing. Platforms offering prescription fulfillment services are particularly popular. Neighborhood stores continue to serve as a critical segment, particularly in rural areas and regions with limited access to modern trade or online platforms.
Segmentation:
By Product:
- Antibiotics
- Anti-Inflammatory Drugs
- Parasiticides
- Heartworm
- Behavioral Products
- Nutritional Products
- Anti-Obesity Drugs
- Skin Care Products
- Vaccines
By Distribution Channel:
- Modern Trade
- Online Distribution
- Neighborhood Stores
- Other Retail Format
By Region:
- North America
- United States
- Canada
- Europe
- Germany
- France
- United Kingdom
- Asia-Pacific
- China
- India
- Japan
- Latin America
- Brazil
- Mexico
- Middle East and Africa
- United Arab Emirates
- South Africa
Regional Analysis:
The Companion Animal Specialty Drugs Market demonstrates significant regional diversity, shaped by differences in pet ownership, veterinary healthcare infrastructure, and economic development. Each region contributes uniquely, with varying growth trajectories and opportunities.
North America
North America leads the market, capturing approximately 40% of the global share, driven by its robust veterinary care infrastructure and high pet ownership rates. In the United States, over 67% of households, or approximately 85 million families, own pets, fueling demand for advanced treatments. The region's adoption of pet insurance has grown significantly, with over 4.4 million pets insured in 2022, reducing financial barriers to specialty drugs. Furthermore, innovative R&D initiatives by pharmaceutical giants in the U.S. have resulted in the development of cutting-edge therapies such as monoclonal antibodies and gene-targeted drugs, solidifying the region’s market leadership.
Europe
Europe holds about 30% of the global market share, supported by strong animal welfare regulations and growing awareness of pet health. Countries like Germany, where approximately 47% of households own pets, lead in adopting advanced veterinary pharmaceuticals. In the UK, pet insurance coverage exceeds 30%, compared to less than 3% in the U.S., making specialty treatments more accessible. Additionally, the European Union’s regulatory framework facilitates the approval of innovative drugs, further driving growth. The presence of established pharmaceutical manufacturers and investment in veterinary R&D enhance the region's competitiveness.
Asia-Pacific
Asia-Pacific accounts for around 20% of the global market share, emerging as a high-growth region due to rising pet adoption and expanding veterinary healthcare. China is home to over 99 million pet dogs and cats, with pet-related spending surpassing $34 billion in 2022, indicating a growing willingness to invest in advanced treatments. In India, the pet care market is growing driven by increasing urbanization and disposable incomes. Japan’s aging pet population also drives demand for specialty drugs targeting chronic conditions. Local pharmaceutical companies in Asia-Pacific are investing in cost-effective manufacturing, making advanced treatments more accessible.
Latin America and Middle East & Africa
The combined regions of Latin America and the Middle East & Africa represent around 10% of the global market share, with improving veterinary care access and rising pet ownership driving growth. In Brazil, one of the largest pet markets globally, there are over 55 million pet dogs, creating substantial demand for veterinary pharmaceuticals. South Africa and the UAE are expanding their veterinary infrastructure, supported by growing awareness campaigns for pet health. However, challenges such as limited pet insurance penetration and lower awareness of specialty drugs remain barriers to faster adoption.
Key Player Analysis:
- Biogenesis Bago SA
- Boehringer Ingelheim International GmbH.
- Ceva Santé Animale
- Elanco Animal Health Incorporated
- Merck Animal Health (Merck & Co., Inc.)
- NEOGEN Corporation.
- Piramal Group
- Vetoquinol S.A.
- Virbac S.A.
- Zoetis
Competitive Analysis:
The Companion Animal Specialty Drugs Market is highly competitive, driven by the presence of global pharmaceutical leaders and emerging regional players. Companies such as Zoetis Inc., Elanco Animal Health, Boehringer Ingelheim, and Merck Animal Health dominate the market by leveraging extensive R&D capabilities, robust product portfolios, and global distribution networks. These key players focus on developing innovative therapies, including monoclonal antibodies, gene therapies, and targeted biologics, addressing complex conditions such as cancer and autoimmune diseases in pets. For instance, Merck Animal Health collaborates with Vetigenics to develop novel therapeutic antibodies for treating chronic diseases in companion animals, showcasing their dedication to advancing veterinary medicine through cutting-edge research. Regional players contribute to the competitive landscape by offering cost-effective solutions tailored to local markets, particularly in Asia-Pacific and Latin America. Strategic collaborations, mergers, and acquisitions further intensify competition as companies seek to expand market reach and enhance their offerings. The growing adoption of digital platforms for veterinary services and e-commerce for prescription drugs provides additional opportunities, enabling companies to strengthen their presence in this rapidly evolving market.
Recent Developments:
- In October 2024, Ceva Santé Animale opened a 12,000 m² European logistics platform in Montpon-Ménestérol, France. The facility features advanced technology, including a Warehouse Management System for 20,000 pallets, autonomous carts, and energy self-sufficiency with geothermal probes and photovoltaic panels. Its BREEAM certification highlights sustainable practices.
- In August 2024, Elanco Animal Health invested $130 million to expand biologics manufacturing in Elwood, Kansas. The 25,000-square-foot addition includes a pilot plant, a cutting-edge quality control lab, and enhanced monoclonal antibody production capabilities, boosting manufacturing and research potential.
Market Concentration & Characteristics:
The Companion Animal Specialty Drugs Market is moderately concentrated, with key global players such as Zoetis Inc., Elanco Animal Health, Boehringer Ingelheim, and Merck Animal Health commanding a significant share. These companies dominate the market through robust R&D investments, innovative product pipelines, and expansive distribution networks. Their focus on targeted biologics and advanced therapies positions them as leaders in addressing complex health conditions in companion animals. Regional players add to the market’s diversity by offering cost-effective solutions and catering to localized demands, particularly in high-growth regions like Asia-Pacific and Latin America. The market is characterized by rapid technological advancements, including personalized medicine and biologics, driving innovation. Additionally, the growing availability of pet insurance and digital platforms for veterinary care has enhanced access to specialty drugs, further expanding market opportunities while encouraging a competitive and dynamic environment.
Report Coverage:
The research report offers an in-depth analysis based on By Product: and By Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Advances in targeted biologics and gene therapies will revolutionize treatment for chronic and complex pet health conditions.
- Growing pet humanization trends will drive demand for premium and innovative veterinary drugs.
- Expansion of pet insurance coverage will improve affordability and boost the adoption of specialty treatments.
- Emerging markets in Asia-Pacific and Latin America will see rapid growth due to rising pet ownership and improved veterinary infrastructure.
- Digital health platforms and telemedicine will enhance access to specialty drugs in underserved regions.
- Increasing focus on rare and genetic conditions in pets will drive innovation in personalized veterinary medicine.
- Adoption of preventative care measures will expand the demand for vaccines and nutraceuticals targeting pet wellness.
- Regulatory support in developed regions will accelerate the approval and availability of advanced veterinary pharmaceuticals.
- Partnerships between pharmaceutical companies and veterinary research institutions will fuel R&D and market expansion.
- Sustainability efforts in drug manufacturing will gain prominence, aligning with global environmental goals.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Companion Animal Specialty Drugs Market?
What is driving market growth?
Which region holds the largest market share?
What challenges does the market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Companion Animal Specialty Drugs Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Companion Animal Specialty Drugs Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 56,831.06 million → 2032: USD 80,264.31 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Companion Animal Specialty Drugs Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Companion Animal Specialty Drugs Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Companion Animal Specialty Drugs Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Companion Animal Specialty Drugs Market Drivers
- 3.3 Companion Animal Specialty Drugs Market Restraints & Challenges
- 3.4 Companion Animal Specialty Drugs Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Companion Animal Specialty Drugs Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Companion Animal Specialty Drugs Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Companion Animal Specialty Drugs category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Companion Animal Specialty Drugs Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Companion Animal Specialty Drugs Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Companion Animal Specialty Drugs market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Companion Animal Specialty Drugs Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Companion Animal Specialty Drugs Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Companion Animal Specialty Drugs Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Companion Animal Specialty Drugs (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Companion Animal Specialty Drugs Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Companion Animal Specialty Drugs Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Companion Animal Specialty Drugs Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Companion Animal Specialty Drugs Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Companion Animal Specialty Drugs Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Companion Animal Specialty Drugs Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Companion Animal Specialty Drugs Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Companion Animal Specialty Drugs Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Companion Animal Specialty Drugs Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
