
Companion Animal Vaccine Market Overview:
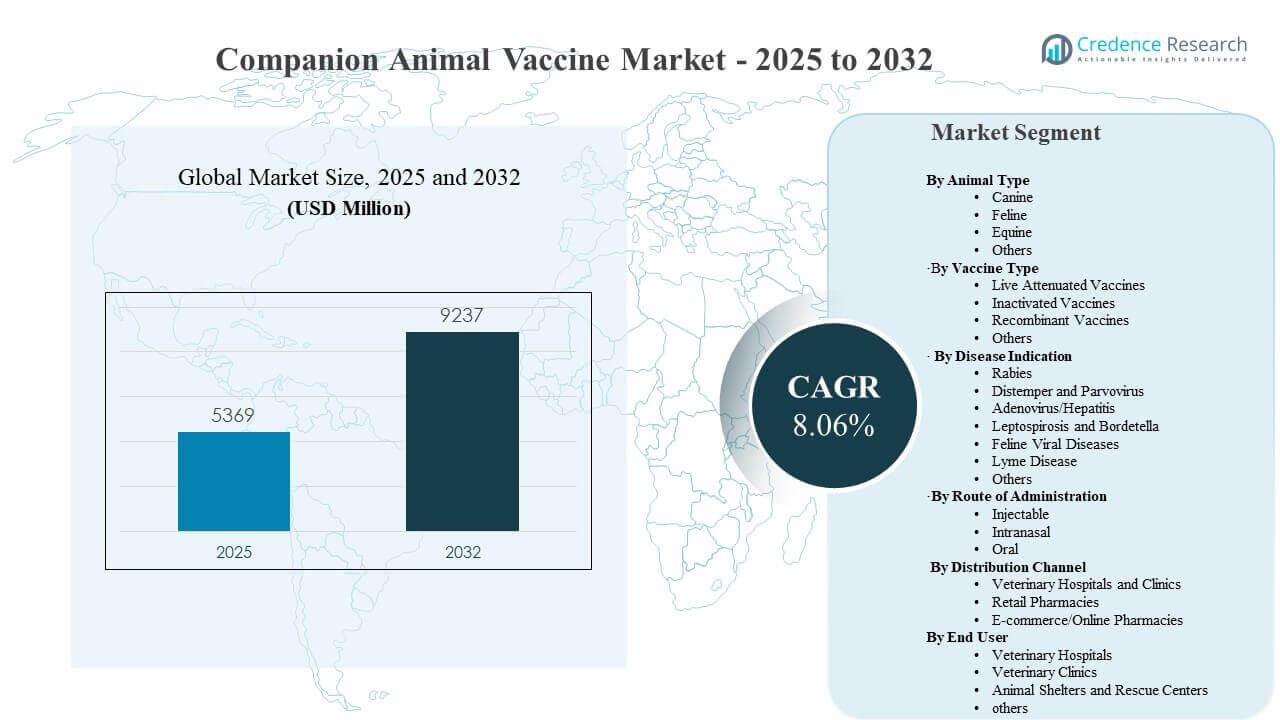
The global Companion Animal Vaccine Market size was estimated at USD 5,369 million in 2025 and is expected to reach USD 9,237 million by 2032, growing at a CAGR of 8.06% from 2025 to 2032. Growth is primarily driven by the continued shift toward preventive veterinary care as owners and veterinarians prioritize routine immunization to reduce infectious disease risk and avoid high-cost treatment episodes. Companion animal population growth, wider availability of combination vaccines, and expanding clinic networks that standardize vaccine protocols are reinforcing repeat booster demand across core indications.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Companion Animal Vaccines Market Size 2025 | USD 5,369 million |
| Companion Animal Vaccines Market, CAGR | 8.06% |
| Companion Animal Vaccines Market Size 2032 | USD 9,237 million |
Key Market Trends & Insights
- The Companion Animal Vaccine Market is projected to expand from USD 5,369 million (2025) to USD 9,237 million (2032), reflecting an 8.06% CAGR (2025–2032).
- North America accounted for 39.90% of 2025 revenue, supported by high preventive-care penetration and strong clinic-based vaccine administration.
- Canine accounted for the largest share of 60.90% in 2025, driven by higher vaccination frequency tied to core protocols and exposure-linked boosters.
- Live attenuated vaccines held a 39.80% share in 2025, sustained by broad product availability and long-standing clinical familiarity.
- Rabies represented 34.20% of 2025 demand, supported by public health alignment and formal compliance requirements in many markets.
Segment Analysis
Companion animal vaccines are increasingly positioned as a foundational component of preventive care programs, with clinics bundling immunization into wellness plans to improve adherence and visit retention. The Companion Animal Vaccine Market benefits from protocol standardization, which supports predictable purchasing patterns for core vaccines and boosters. Cold-chain handling and documentation requirements continue to favor clinic-led delivery, reinforcing the role of professional administration in maintaining compliance and repeat dosing cycles.
Product and platform innovation is shaping competitive differentiation as manufacturers focus on improving safety profiles, dosing convenience, and targeted disease coverage. Practices are also prioritizing consistent supply, reduced visit friction, and clearer reminder pathways, which supports structured re-vaccination behavior. The Companion Animal Vaccine Market also reflects demand resilience because core vaccinations are often treated as non-discretionary spend by engaged pet owners and organized care providers.
A growing share of vaccination volumes is influenced by institutional and high-throughput settings such as veterinary hospitals and shelter intake pathways. These channels accelerate early-life immunization and drive combination vaccine utilization to reduce time to protection. The Companion Animal Vaccine Market is also supported by expanding owner awareness of zoonotic and vector-borne risks, which sustains demand beyond core pediatric schedules.
By Animal Type Insights
Canine accounted for the largest share of 60.90% in 2025. Canine vaccination volume remains high because core schedules are widely adopted and booster compliance is reinforced by boarding, grooming, and daycare requirements. Veterinary networks also standardize canine preventive bundles, supporting predictable demand for multi-disease protection. The Companion Animal Vaccine Market continues to benefit from broader product availability and established clinical pathways in canine care.
By Vaccine Type Insights
Live Attenuated Vaccines accounted for the largest share of 39.80% in 2025. Live attenuated formats remain widely used due to strong clinical familiarity and broad availability across core indications. Clinic purchasing often favors established options that fit standardized protocols and support consistent scheduling. The Companion Animal Vaccine Market maintains steady utilization of live attenuated products where cost-efficiency and proven performance shape formulary decisions.
By Disease Indication Insights
Rabies accounted for the largest share of 34.20% in 2025. Rabies demand is reinforced by public health alignment and regulatory expectations that prioritize consistent coverage across companion animals. Documentation requirements and renewal reminders support repeat dosing cycles, especially in organized clinical networks. The Companion Animal Vaccine Market sustains rabies-related volumes because compliance-driven purchasing remains stable across economic cycles.
By Route of Administration Insights
Injectable administration remains the dominant care standard in routine veterinary immunization pathways, supported by established clinical workflows and broad product availability across core schedules. Intranasal options are used selectively for respiratory coverage in higher-exposure settings where mucosal immunity and rapid protection are valued. Oral administration remains niche and indication-specific, but convenience can support adherence in targeted scenarios. The Companion Animal Vaccine Market continues to prioritize routes that align with cold-chain control, reliable dosing, and documentation.
By Distribution Channel Insights
Veterinary Hospitals and Clinics accounted for the largest share of 52.70% in 2025. Clinical settings lead because vaccines are typically administered under professional supervision, supporting cold-chain integrity and compliance documentation. Organized clinic networks also drive bundled preventive-care offerings that encourage on-time boosters and protocol adherence. The Companion Animal Vaccine Market continues to rely on clinic-led delivery because it enables standardized care pathways and predictable procurement.
By End User Insights
Veterinary hospitals represent a central immunization hub due to higher case throughput, integrated diagnostics, and standardized preventive-care scheduling. Veterinary clinics also contribute significantly through routine wellness visits and community access, particularly in suburban and emerging urban markets. Animal shelters and rescue centers influence early-life immunization volume by implementing rapid intake protocols and population-level protection strategies. The Companion Animal Vaccine Market benefits when end users adopt consistent scheduling, documentation, and reminder systems that lift booster compliance.
Companion Animal Vaccines Market Drivers
Preventive care penetration and protocol standardization
Preventive care is increasingly prioritized as owners seek to avoid costly infectious disease outcomes and improve long-term animal health. Veterinary hospitals and clinics standardize immunization schedules, which strengthens repeat booster demand and reduces missed-dose risk. Clinic networks also bundle vaccines into wellness plans that support adherence through reminders and recurring visits. The Companion Animal Vaccine Market gains stability because core vaccines are treated as essential services within routine care pathways.
Rising companion animal ownership and higher lifetime care spending
Companion animal ownership continues to expand across major markets, increasing the addressable vaccination base for core immunizations and boosters. Higher lifetime care spending supports broader uptake of recommended vaccines beyond minimum requirements. Owners also demonstrate stronger willingness to follow veterinarian guidance when vaccination is tied to safety, travel, and community exposure. The Companion Animal Vaccine Market benefits from this shift toward proactive, lifetime health management.
- For instance, Trupanion reported that it now protects more than 1 million pets, has paid more than 2.1 million claims in under 60 seconds, and maintains 98%+ monthly retention, showing how digital payment infrastructure and sustained owner engagement are reinforcing long-term veterinary care utilization.
Manufacturer innovation and portfolio differentiation
Manufacturers compete by upgrading formulations and expanding coverage across core and emerging indications to improve clinical outcomes and practice adoption. Product improvements that simplify scheduling and support consistent protection strengthen clinic confidence and repeat purchasing. Portfolio breadth also supports multi-disease bundling, improving operational efficiency for high-volume practices. The Companion Animal Vaccine Market grows when innovation aligns with clinic workflows and measurable preventive outcomes.
- For instance, Zoetis launched Vanguard Recombishield as the first and only canine Bordetella vaccine with pertactin protein; it is indicated for dogs 8 weeks and older, and in one study it reduced coughing duration by 80% and nasal shedding duration by 23%, giving clinics a measurable efficacy-based differentiation point.
Expansion of veterinary service capacity and organized care delivery
Growth in veterinary service capacity supports higher vaccination throughput, improved recordkeeping, and tighter compliance management. Corporate and multi-site practices increasingly implement standardized protocols and centralized purchasing, supporting reliable vaccine volumes. These organizations also invest in digital reminders and care plans that improve booster rates. The Companion Animal Vaccine Market gains momentum when service capacity and preventive program execution scale together.
Companion Animal Vaccines Market Challenges
Cold-chain requirements and supply reliability remain persistent operational challenges, particularly for practices and distributors serving remote geographies. Inventory constraints, shipment variability, and storage limitations can disrupt adherence to scheduled dosing, which influences clinical outcomes and client satisfaction. Pricing pressure can also rise when practices balance affordability with preferred brands and product types. The Companion Animal Vaccine Market faces added complexity when compliance expectations are high but distribution reliability is uneven.
- For instance, Blackfrog Technologies’ Emvólio portable cold-chain unit has delivered more than 200,000 vaccines across 16 Indian states and has been reported to reduce vaccine wastage by up to 99%, underscoring how measurable refrigeration performance can directly strengthen supply continuity in difficult-service locations.
Vaccine hesitancy and inconsistent preventive-care adherence can limit uptake of non-core immunizations and reduce booster completion rates. Some owners delay care due to cost sensitivity, limited appointment availability, or misunderstandings about schedules and risk. Variability in local regulations and documentation requirements can also increase administrative burden for providers. The Companion Animal Vaccine Market must navigate these behavioral and operational frictions to sustain consistent demand.
Companion Animal Vaccines Market Trends and Opportunities
Digital reminders, wellness subscriptions, and practice management tools are improving booster adherence and supporting recurring revenue models for clinics and manufacturers. These tools strengthen schedule consistency, reduce missed appointments, and support standardized protocols across multi-site networks. E-commerce channels are also expanding access to ancillary preventive products that complement immunization programs. The Companion Animal Vaccine Market gains opportunity as care delivery becomes more organized and data-driven.
- For instance, Indooroopilly Vet Clinic reported that Covetrus Ascend’s SMS client communications feature enabled automated appointment reminders and other client updates, while the platform saved 16 hours per week and reduced consultation time by 5 to 10 minutes per visit, demonstrating how software-led workflows can improve follow-up consistency and operational efficiency in preventive care delivery.
Vaccine platform differentiation is creating opportunities for premium positioning through improved safety perception, targeted disease coverage, and product innovations that reduce visit friction. Practices are increasingly focused on client experience, which supports demand for options that simplify administration and follow-up. Shelter and rescue vaccination pathways also create volume opportunities tied to population-level protection strategies. The Companion Animal Vaccine Market can expand through partnerships that strengthen delivery infrastructure and adherence outcomes.
Regional Insights
North America (39.90%)
Companion Animal Vaccine Market performance in North America accounted for 39.90% of 2025 revenue, supported by high preventive-care penetration, established clinical protocols, and strong compliance-driven demand tied to core immunization schedules. Veterinary hospitals and consolidated clinic networks strengthen purchasing consistency through standardized formularies and recurring wellness plans. High service accessibility and mature documentation practices reinforce booster adherence. Companion Animal Vaccine Market scale is also supported by strong owner willingness to spend on preventive care and routine veterinary visits.
Europe (24.60%)
Companion Animal Vaccine Market demand in Europe represented 24.60% of 2025 revenue, supported by structured veterinary care delivery and broad adoption of routine immunization schedules across major markets. Procurement emphasizes quality, reliability, and consistent supply to support standardized preventive-care pathways. Regulatory and public health alignment supports ongoing demand for core vaccines, with increasing attention to guideline-led boosters in organized practices. Companion Animal Vaccine Market growth is reinforced where clinic capacity and owner awareness continue to improve.
Asia Pacific (22.30%)
Companion Animal Vaccine Market growth in Asia Pacific captured 22.30% of 2025 revenue, supported by rising pet adoption, expanding veterinary infrastructure, and improving preventive-care awareness in major urban markets. Clinic network expansion strengthens protocol standardization and improves documentation, which supports repeat boosters over time. Market expansion is uneven across countries due to variability in spend, access, and preventive-care norms. Companion Animal Vaccine Market momentum improves as service capacity and owner education scale together.
Latin America (7.80%)
Companion Animal Vaccine Market development in Latin America held 7.80% of 2025 revenue, supported by increasing urban pet ownership and a growing base of private veterinary services that promote routine immunization. Adoption varies by income and access, which can affect booster adherence and uptake beyond core vaccines. Clinic-led care remains central because professional administration supports recordkeeping and schedule compliance. Companion Animal Vaccine Market growth improves as preventive programs and clinic density expand.
Middle East & Africa (5.40%)
Companion Animal Vaccine Market adoption in the Middle East & Africa accounted for 5.40% of 2025 revenue, supported by growing companion animal ownership in select urban centers and increasing availability of veterinary services. Preventive-care behavior remains uneven, and access constraints can limit routine vaccination coverage in some areas. Where organized clinics expand, protocol standardization and documentation can strengthen booster compliance. Companion Animal Vaccine Market growth is likely to track improvements in veterinary capacity and owner awareness.
Competitive Landscape
Competition in the Companion Animal Vaccine Market is shaped by portfolio breadth across core indications, supply reliability, and the ability to align products with standardized clinic protocols. Leading manufacturers compete through product upgrades, platform differentiation, and commercial programs that support clinic adherence and client retention. Distribution reach and cold-chain execution remain important for sustaining consistent demand. Brand trust and long-standing clinical familiarity continue to influence formulary selection and repeat purchasing.
Zoetis competes through a broad companion animal portfolio and strategies that support clinic-led preventive-care delivery, including schedule alignment, clinical education, and practice-facing programs that reinforce adherence. Product positioning emphasizes consistent protection within routine immunization workflows and compatibility with standardized protocols across multi-site networks. Commercial execution is strengthened when supply reliability and documentation support reduce friction for high-throughput providers. Companion Animal Vaccine Market performance is supported when product differentiation connects directly to clinic productivity and owner compliance.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Zoetis
- Merck Animal Health
- Boehringer Ingelheim Animal Health
- Elanco Animal Health
- Virbac
- Phibro Animal Health
- Ceva Santé Animale
- Dechra Pharmaceuticals
- Vetoquinol
- HIPRA
- Indian Immunologicals Ltd.
- Biogenesis Bago
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In a March 2026, BioVaxys Technology Corp. and Adiverna LLC announced a research collaboration to develop mRNA-based vaccines for companion animals, specifically dogs and cats, targeting rabies, leptospirosis, feline infectious peritonitis, and other veterinary applications.
- In a November 2025, Zoetis announced the U.S. launch of Vanguard Recombishield, a new injectable vaccine for dogs against Bordetella bronchiseptica, and the company said it is the first and only canine vaccine with pertactin protein for an optimized immune response.
- In a September 2024, Merck Animal Health announced the expansion of its NOBIVAC NXT platform with USDA-approved NOBIVAC NXT FeLV, which it described as the first feline leukemia virus vaccine built on its RNA-particle technology platform.
- In a September 2024, Boehringer Ingelheim announced its acquisition of Saiba Animal Health, adding Saiba’s therapeutic vaccination technology platform and species-specific companion-animal product candidates to Boehringer’s animal health R&D pipeline.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 5369 million |
| Revenue forecast in 2032 | USD 9237 million |
| Growth rate (CAGR) | 8.06% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026-2032 |
| Quantitative units | USD million |
| Segments covered | By Animal Type; By Vaccine Type; By Disease Indication; By Route of Administration; By Distribution Channel; By End User |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Zoetis; Merck Animal Health; Boehringer Ingelheim Animal Health; Elanco Animal Health; Virbac; Phibro Animal Health; Ceva Santé Animale; Dechra Pharmaceuticals; Vetoquinol; HIPRA; Indian Immunologicals Ltd.; Biogenesis Bago |
| No.of Pages | 328 |
Segmentation
By Animal Type
- Canine
- Feline
- Equine
- Others
By Vaccine Type
- Live Attenuated Vaccines
- Inactivated Vaccines
- Recombinant Vaccines
- Others
By Disease Indication
- Rabies
- Distemper and Parvovirus
- Adenovirus/Hepatitis
- Leptospirosis and Bordetella
- Feline Viral Diseases
- Lyme Disease
- Others
By Route of Administration
- Injectable
- Intranasal
- Oral
By Distribution Channel
- Veterinary Hospitals and Clinics
- Retail Pharmacies
- E-commerce/Online Pharmacies
By End User
- Veterinary Hospitals
- Veterinary Clinics
- Animal Shelters and Rescue Centers
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Preventive care penetration and protocol standardization
Veterinary hospitals and clinics are increasingly standardizing immunization schedules and bundling vaccines into wellness plans, which strengthens repeat booster demand and reduces missed-dose risk. This approach treats core vaccines as essential services, supporting stable and recurring market demand.
Rising companion animal ownership and higher lifetime care spending
The growing global population of companion animals, coupled with owners' willingness to invest in long-term health, expands the addressable base for core immunizations and boosters. Increased spending on lifetime care supports broader uptake of recommended vaccines beyond minimum requirements.
Manufacturer innovation and portfolio differentiation
Manufacturers are enhancing vaccine formulations, expanding disease coverage, and introducing products that simplify scheduling and administration. These innovations improve clinical outcomes, support multi-disease bundling, and drive repeat purchasing by aligning with clinic workflows.
Expansion of veterinary service capacity and organized care delivery
Growth in veterinary service infrastructure, including corporate and multi-site practices, enables higher vaccination throughput, better recordkeeping, and improved compliance management. Standardized protocols and digital reminders in these settings further boost booster rates and market momentum.
Owner awareness of zoonotic and vector-borne risks
Increasing awareness among pet owners about zoonotic and vector-borne diseases sustains demand for vaccines beyond core pediatric schedules. This trend is reinforced by public health campaigns and regulatory requirements, particularly for diseases like rabies.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size and forecast for the Companion Animal Vaccine Market?
What is the CAGR for the Companion Animal Vaccine Market?
What is the largest segment in the Companion Animal Vaccine Market?
What factors are driving growth in the Companion Animal Vaccine Market?
Who are the leading companies in the Companion Animal Vaccine Market?
Which region leads the Companion Animal Vaccine Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Animal Type
- 1.2.1 Canine
- 1.2.2 Feline
- 1.2.3 Equine
- 1.2.4 Others
- 1.3 By Vaccine Type
- 1.3.1 Live Attenuated Vaccines
- 1.3.2 Inactivated Vaccines
- 1.3.3 Recombinant Vaccines
- 1.3.4 Others
- 1.4 By Disease Indication
- 1.4.1 Rabies
- 1.4.2 Distemper and Parvovirus
- 1.4.3 Adenovirus/Hepatitis
- 1.4.4 Leptospirosis and Bordetella
- 1.4.5 Feline Viral Diseases
- 1.4.6 Lyme Disease
- 1.4.7 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 5,369 million → 2032: USD 9,237 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Companion Animal Vaccines Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Companion Animal Vaccines Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Companion Animal Vaccines Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Companion Animal Vaccines Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Companion Animal Vaccines Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Companion Animal Vaccines Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Companion Animal Vaccines Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Companion Animal Vaccines Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 5,369 million → 2032: USD 9,237 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Companion Animal Vaccines Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Animal Type - Market Size and Forecast, 2025-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2025-2032
- 12.3.4 Volume Forecast, 2025-2032
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Canine
- 12.3.7.2 Feline
- 12.3.7.3 Equine
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Vaccine Type - Market Size and Forecast, 2025-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2025-2032
- 12.4.4 Volume Forecast, 2025-2032
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Live Attenuated Vaccines
- 12.4.7.2 Inactivated Vaccines
- 12.4.7.3 Recombinant Vaccines
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Disease Indication - Market Size and Forecast, 2025-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2025-2032
- 12.5.4 Volume Forecast, 2025-2032
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Rabies
- 12.5.7.2 Distemper and Parvovirus
- 12.5.7.3 Adenovirus/Hepatitis
- 12.5.7.4 Leptospirosis and Bordetella
- 12.5.7.5 Feline Viral Diseases
- 12.5.7.6 Lyme Disease
- 12.5.7.7 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Companion Animal Vaccines Geographic Market Outlook, 2025-2032
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Companion Animal Vaccines Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Companion Animal Vaccines Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Zoetis
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Merck Animal Health
- 17.4 Boehringer Ingelheim Animal Health
- 17.5 Elanco Animal Health
- 17.6 Virbac
- 17.7 Phibro Animal Health
- 17.8 Ceva Santé Animale
- 17.9 Dechra Pharmaceuticals
- 17.10 Vetoquinol
- 17.11 HIPRA
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

